
 Low Fat Granola Market | 2026-2036
Low Fat Granola Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Granola Market Analytics
Supermarket shelf allocation for better-for-you breakfast items is tilting toward low-fat granola variants as retailers respond to shifting basket composition. Bob's Red Mill leverages its heritage grain sourcing to sustain premium placement in conventional grocery. KIND Snacks anchors its position through clean-label formulations that compete directly with private-label alternatives.
Low fat granola denotes a baked cereal cluster containing reduced oil content, typically achieved through modified oven profiles or binding agents that maintain structural integrity without excessive fat inclusion, serving commercial and retail markets seeking calorie-controlled breakfast solutions. Organic and gluten-free product types lead current revenue pools, while fruit-infused variants represent the fastest-growing segment as manufacturers target flavor differentiation without fat addition. Single-serve pouches command margin concentration among packaging types due to convenience premiums in away-from-home consumption.
FDA nutrition-labeling requirements and USDA organic certification standards shape formulation transparency and ingredient sourcing across North American supply chains, with EFSA health claims guidelines influencing European product positioning. The EU Green Deal's sustainable packaging directives further constrain material choices for resealable and bulk container formats. Stakeholders must monitor evolving clean-label definitions and regional allergen thresholds to maintain formulation compliance and shelf access.
Market Dynamics
Clean-label reformulations using reduced-oil baking processes are compressing traditional manufacturing cost structures while expanding addressable demand among calorie-conscious consumers in corporate wellness programs.
Growth Catalysts
- Corporate Wellness Mandates:Employer-sponsored nutrition programs in the United States are standardizing low-fat breakfast options as reimbursable wellness expenditures, creating institutional procurement pull.
- EU Green Deal Packaging Directives:Biodegradable pouch requirements are accelerating material innovation among contract manufacturers serving European retail chains.
- Fruit-Infused Binding Technologies:Natural pectin and fruit-puree binding systems are replacing oil-based cohesion methods without sacrificing cluster integrity.
Market Restraints
- Oat Supply Concentration:North American oat milling capacity clusters in the Canadian prairies and upper Midwest, exposing formulations to weather-driven input volatility.
- FDA Serving-Size Labeling Rigor:Strict portion-definition requirements complicate multi-serve packaging claims and restrict marketing flexibility.
- Private-Label Substitution:Retailer-owned brands in Germany and Japan are compressing branded price premiums through direct sourcing from co-manufacturers.
Strategic Opportunities
- Single-Serve Convenience Channel:Airport and railway kiosk networks in Japan represent underpenetrated away-from-home consumption nodes with premium tolerance.
- USDA Organic Certification Tailwinds:Federal procurement preferences for organic ingredients in federal feeding programs create institutional demand expansion.
- Direct-to-Employer Distribution:Bypassing retail markup through corporate pantry subscription models captures recurring B2B revenue streams.
Industry Challenges
- Clean-Label Definition Fluidity:Evolving consumer interpretations of "natural" and "minimally processed" force continuous formulation audits against shifting benchmark standards.
- Cross-Contamination Certification Burden:Gluten-free and allergen-free production line segregation requires capital-intensive facility modifications and extended third-party validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Granola Market |
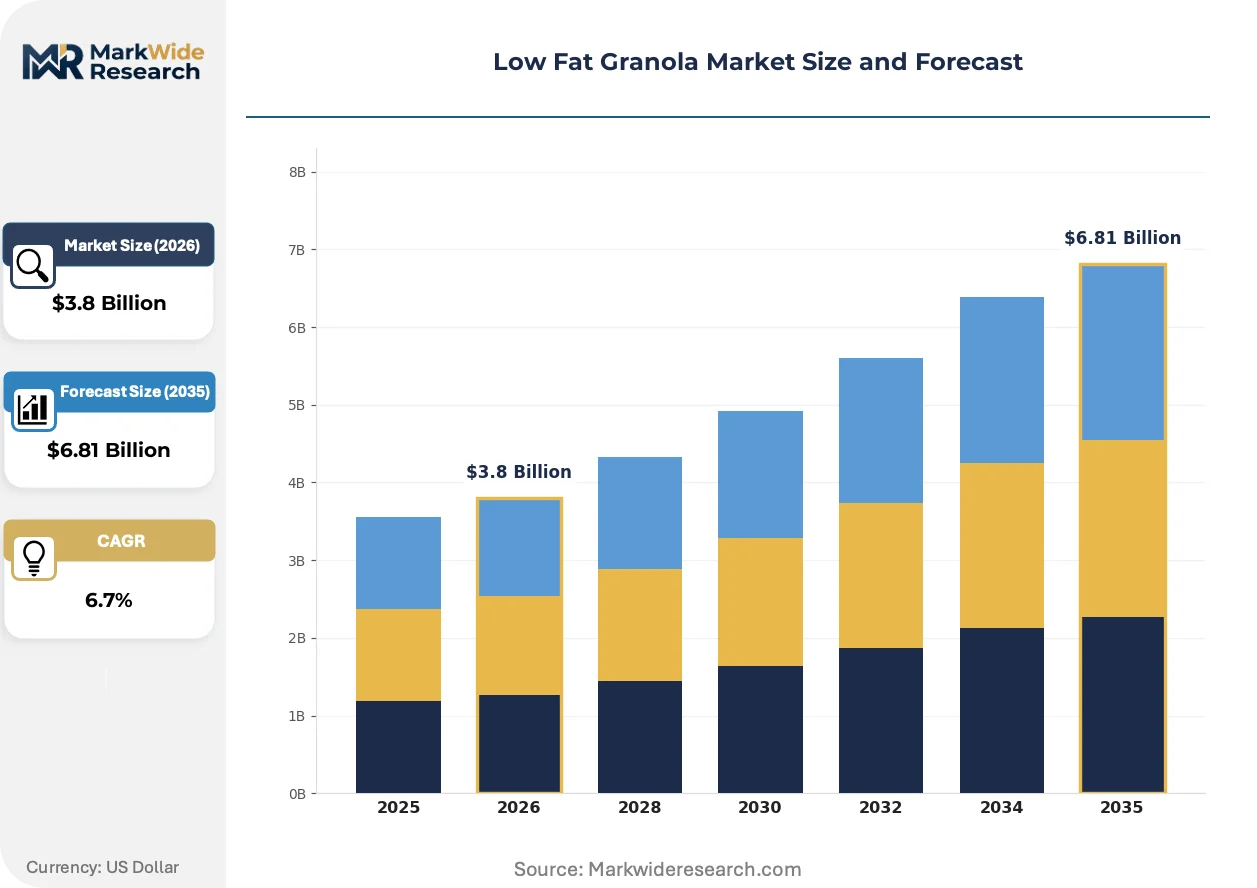
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Gluten-Free, Nut-Based, Fruit-Infused Customer Type: Health-Conscious Consumers, Athletes, Weight Watchers, Busy Professionals Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops Packaging Type: Resealable Bags, Boxes, Single-Serve Pouches, Bulk Containers |
| Companies Covered | Bob's Red Mill, KIND Snacks, Go Raw, Purely Elizabeth, Nature's Path, Brekky Mix, Paleonola, Udi's, Familia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Granola Market Evolving Landscape
Modified oven profiles and alternative binding agents are restructuring how manufacturers achieve structural integrity without fat dependence, while regulatory pressure on packaging sustainability accelerates material experimentation.
Spray-dried fruit puree binding systems are replacing conventional oil emulsions as the primary cluster cohesion mechanism in reduced-fat formulations. Mid-size co-manufacturers in the Pacific Northwest are retrofitting convection lines to accommodate lower-temperature, extended-bake cycles. This thermal processing shift is rendering obsolete traditional rotary oven configurations optimized for high-fat granola production.
EFSA health claims guidelines are tightening evidentiary requirements for satiety and glycemic-response marketing statements on European-packaged products. Manufacturers must now commission clinical substantiation studies before deploying functional claims on resealable pouch formats. German and Dutch brands are responding by reformulating around EFSA-approved fiber-content thresholds rather than pursuing novel health-positioning territories.
Corporate procurement departments are consolidating breakfast-category suppliers into single-source contracts with annual volume commitments. Foodservice distributors serving United States tech campuses are displacing fragmented local bakery relationships with national low-fat granola supply agreements. This concentration pattern is most visible in Seattle and Austin employer feeding operations, where wellness-program administrators prioritize nutritional consistency across multiple campus locations.
Low Fat Granola Market Segmentation
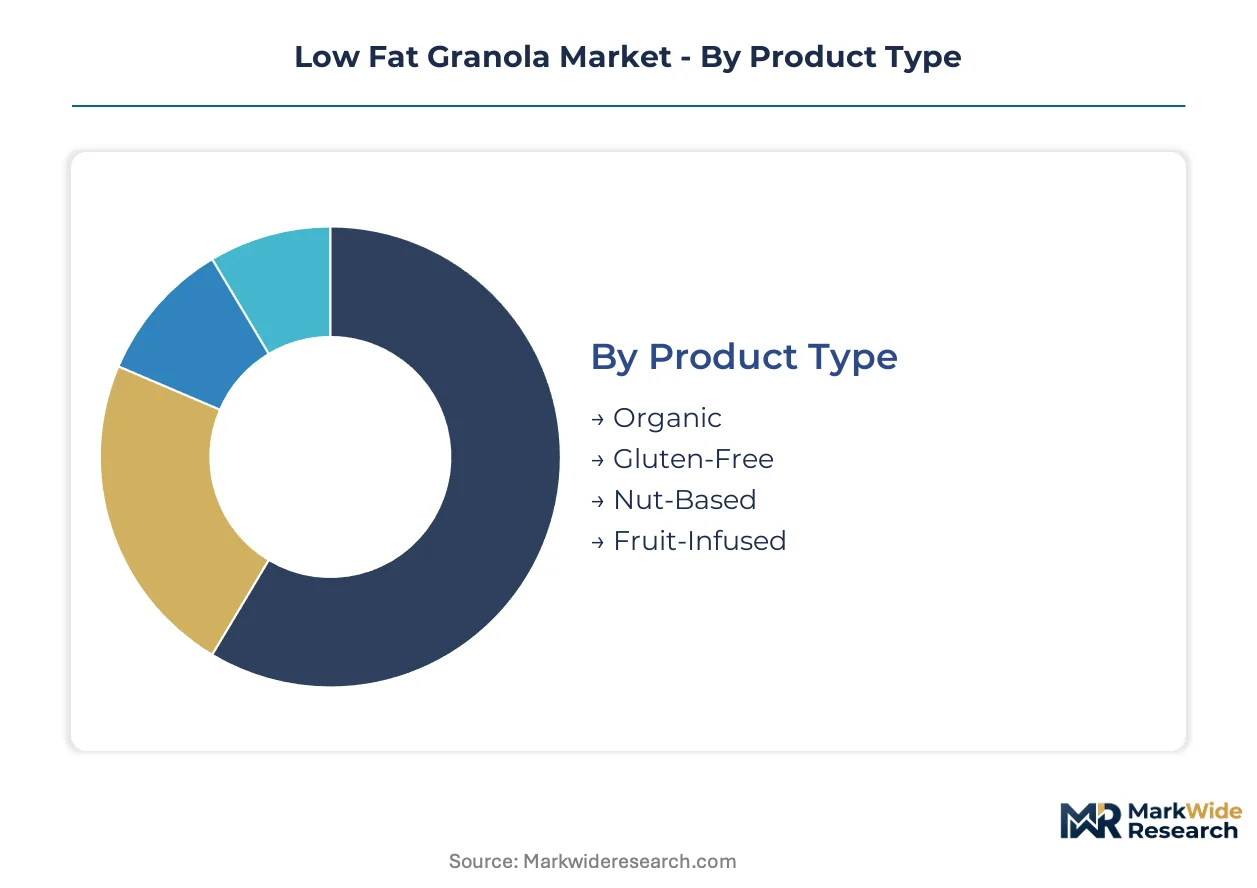
Low fat granola manufacturers segment offerings across four dimensions that determine formulation priorities, margin architecture, and channel access. Product type and packaging format decisions cascade through supply chain configuration and retail placement strategy.
Product Type:
Cost tier differentiation in low fat granola correlates directly with ingredient sourcing protocols and certification burden.
- Organic:USDA-certified organic oats and sweeteners command premium shelf positioning in conventional grocery. Procurement contracts with certified grain elevators in the Dakotas and Saskatchewan secure supply for national brands targeting federal feeding program eligibility.
- Fruit-Infused:Spray-dried fruit puree binding systems replace oil emulsions while delivering flavor differentiation. Japanese and German retailers are expanding SKU allocation for these variants as clean-label definitions tighten around added-sugar disclosure.
- Gluten-Free:Dedicated production lines and third-party certification add facility overhead. Demand concentrates among celiac-diagnosed consumers and wellness-adjacent buyers seeking digestive positioning.
- Nut-Based:Almond and cashew inclusions elevate protein content but complicate allergen labeling. Co-manufacturers in the Pacific Northwest maintain segregated roasting operations for these formulations.
Organic commands the established base. The steepest expansion runs through Fruit-Infused.
Customer Type:
Application context determines serving size preferences, flavor profile tolerance, and price elasticity across consumption occasions.
- Busy Professionals:Single-serve pouch demand peaks in airport kiosks and corporate pantry programs where convenience premiums offset per-ounce cost multiples. Seattle and Austin tech campus feeding operations standardize these formats for wellness program compliance.
- Health-Conscious Consumers:Clean-label scrutiny drives repeat purchase decisions in conventional supermarket channels. EFSA fiber-content thresholds and FDA serving-size rigor shape label claim strategy for this cohort.
- Athletes:Macronutrient ratio specifications prioritize protein-to-carbohydrate balance. Sports nutrition distributors specify cluster density requirements for bagged formats.
- Weight Watchers:Calorie-controlled portion expectations align with measured cup servings in resealable bag formats. Digital tracking integration influences packaging transparency.
Health-Conscious Consumers anchor volume commitments. The steepest expansion trajectory belongs to Busy Professionals.
Distribution Channel:
Channel selection dictates margin retention, promotional calendar access, and private-label exposure risk.
- Supermarkets:Conventional grocery shelf resets favor better-for-you breakfast placement. Bob's Red Mill and KIND Snacks compete for end-cap positioning against retailer-owned alternatives.
- Online Retailers:Subscription models capture recurring revenue with reduced customer acquisition cost. Direct-to-employer corporate pantry programs bypass retail markup entirely.
- Health Food Stores:Staff-curated assortments reward heritage grain sourcing narratives. Pacific Northwest co-manufacturers leverage regional identity for placement.
- Specialty Shops:Limited SKU breadth demands premium pricing discipline. Airport and railway kiosk networks in Japan represent underpenetrated nodes.
Supermarkets retain the volume base. Online Retailers are climbing the fastest.
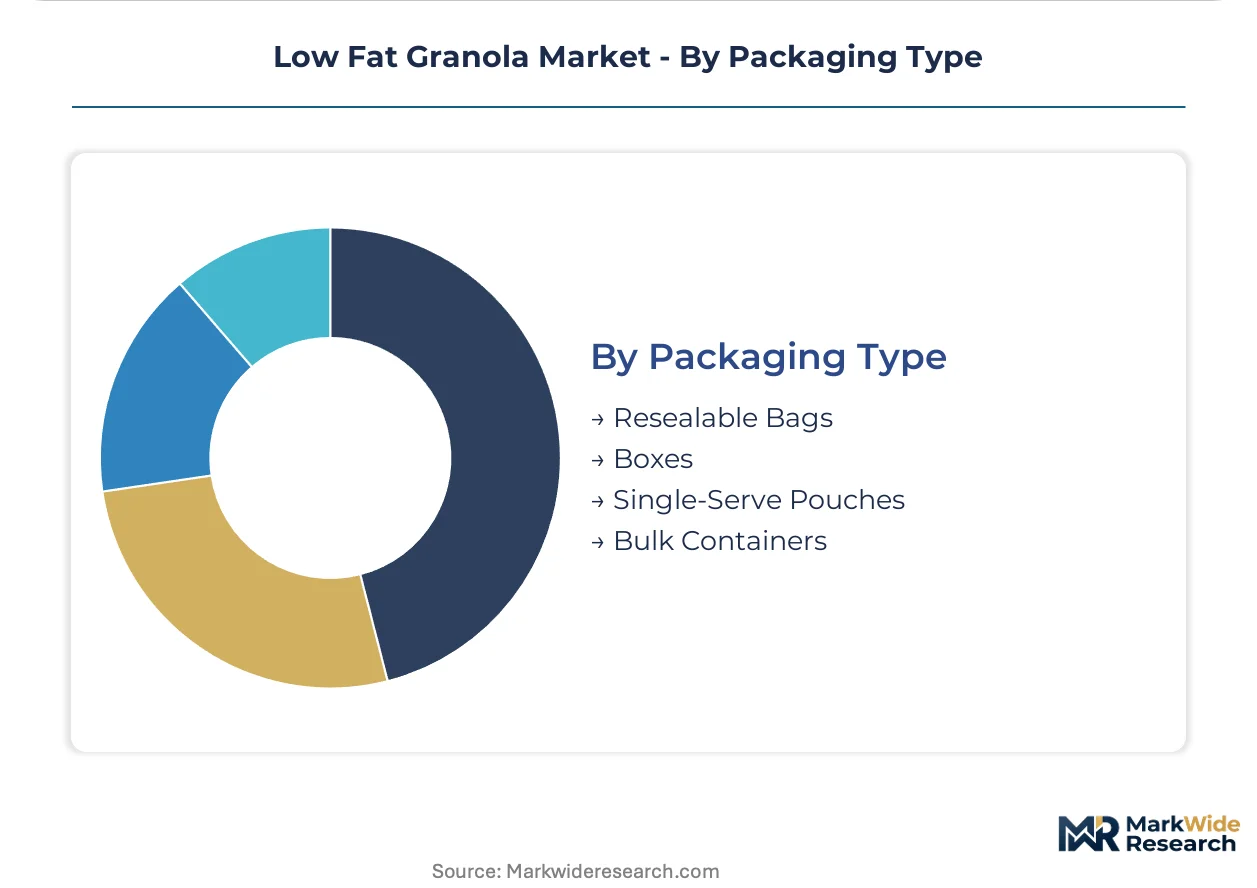
Packaging Type:
Volume scale and margin concentration diverge sharply across format specifications.
- Single-Serve Pouches:Convenience premiums in away-from-home consumption justify per-unit margin multiples. EU Green Deal biodegradable requirements accelerate material innovation for European-bound production.
- Resealable Bags:Multi-serve household formats balance freshness protection with portion flexibility. FDA serving-size labeling rigor complicates front-of-pack claim architecture.
- Bulk Containers:Foodservice and institutional procurement favor this format for corporate wellness program standardization. Annual volume commitments characterize B2B relationships.
- Boxes:Traditional retail packaging maintains presence in conventional grocery cereal aisles. Shelf stability requirements favor inner bag configurations.
Resealable Bags hold the established position. Single-Serve Pouches gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japanese and German retail channels where clean-label certification commands shelf placement premiums, while US mass-market volumes operate on compressed per-unit economics driven by corporate wellness procurement scale.
United States
FDA nutrition-labeling requirements and USDA organic certification standards shape formulation decisions for brands targeting federal feeding program eligibility. Corporate wellness mandates in Seattle and Austin tech campuses drive single-serve pouch standardization. Pacific Northwest co-manufacturers retrofit convection lines for reduced-oil baking cycles.
Germany
EFSA health claims guidelines tighten evidentiary requirements for satiety marketing on European-packaged products. Private-label substitution compresses branded price premiums through direct co-manufacturer sourcing. Bavarian and North Rhine-Westphalian retail chains expand biodegradable pouch SKU allocation under EU Green Deal directives.
Japan
METI standards influence clean-label definition thresholds for imported breakfast products. Airport and railway kiosk networks represent underpenetrated away-from-home consumption nodes with premium tolerance. Tokyo and Osaka metropolitan procurement departments consolidate breakfast-category suppliers into single-source annual contracts.
Canada
Health Canada and PMRA regulations govern allergen labeling and organic equivalency arrangements with US suppliers. Prairie oat milling capacity in Saskatchewan and Manitoba exposes formulations to weather-driven input volatility. Vancouver and Toronto health food retailers reward heritage grain sourcing narratives with staff-curated placement.
United Kingdom
Post-Brexit regulatory divergence from EFSA frameworks creates parallel compliance burdens for brands serving both UK and EU markets. London and Southeast England supermarket chains favor better-for-you breakfast shelf resets. Midlands-based contract manufacturers develop spray-dried fruit puree binding systems for reduced-fat cluster production.
Low Fat Granola Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and co-manufacturing roles. The vendor base organizes around three functional tiers: heritage grain specialists with certified organic supply chains, clean-label formulators leveraging fruit-based binding technologies, and private-label operators serving retailer-owned brand programs. Consolidation pressure runs through corporate pantry subscription models and direct-to-employer distribution channels. Strategic moves concentrate on backward integration into certified oat sourcing and co-manufacturer capacity acquisition.
Among heritage-positioned operators, Bob's Red Mill anchors the organic certification tier through Dakota and Saskatchewan grain elevator relationships. KIND Snacks exemplifies clean-label formulation strategy competing against private-label alternatives in conventional grocery end-cap placement. Nature's Path occupies a position within the gluten-free and allergen-segregated production segment, reflecting capital-intensive facility requirements for third-party validation timelines.
| Leading Market Players |
|---|
| Bob's Red Mill |
| KIND Snacks |
| Go Raw |
| Purely Elizabeth |
| Nature's Path |
| Brekky Mix |
| Paleonola |
| Udi's |
| Familia |
| Others |
Value Network & Pricing Analysis
Saskatchewan and Manitoba prairie oat milling clusters anchor North American supply capacity, with weather-driven input volatility transmitting directly into formulation cost structures and downstream pricing power for certified organic variants.
Pricing Analysis
The customization-premium spread between standard resealable bags and configured single-serve pouches runs wide, with convenience premiums in away-from-home channels justifying per-unit margin multiples. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic from conventional and private-label alternatives. Price differentiation hinges on certification grade and volume scale, with corporate pantry subscription models compressing retail markups. Cost compression in the branded tier is intensifying because German and Japanese retailer-owned brands source directly from co-manufacturers, eroding price premiums. Private-label buyers exhibit highest price sensitivity; wellness-program administrators in Seattle and Austin tech campuses show lowest sensitivity due to institutional procurement budgets.
Supply Chain Analysis
Pacific Northwest co-manufacturers hold contract-manufacturing concentration for reduced-oil baking retrofits, with Midwest and Canadian prairie facilities serving bulk institutional formats. Supply draws from United States, Canada, and Germany for oat milling, binding agent innovation, and biodegradable packaging compliance respectively. Raw material dependencies center on certified organic oats, spray-dried fruit purees, and compostable pouch films. Single-source vulnerability concentrates in Saskatchewan and Manitoba oat supply exposure to drought cycles. Distribution runs through foodservice distributors for corporate wellness programs and conventional grocery for retail volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
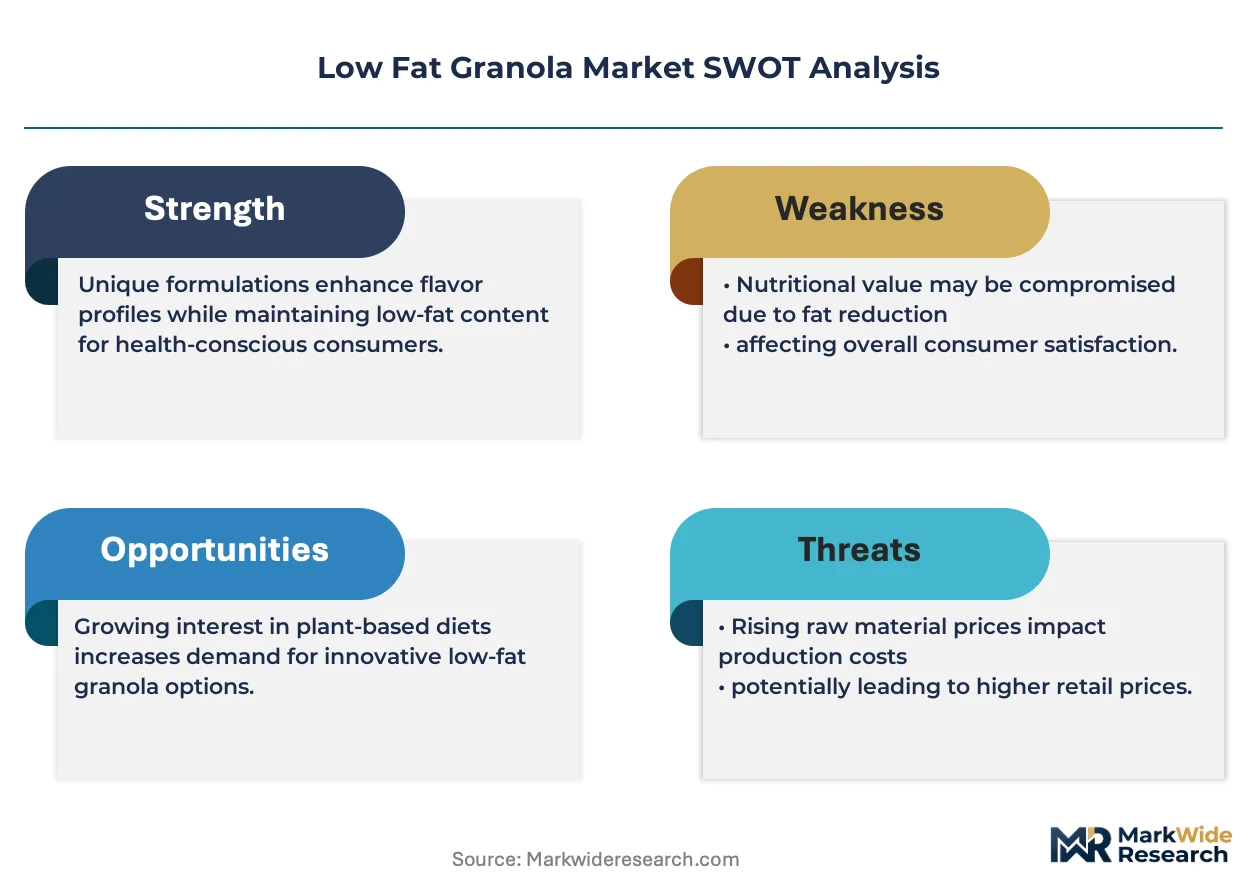
The low-fat granola market reads as a service-attach opportunity because direct-to-employer corporate pantry subscription models expand recurring revenue faster than single-transaction retail velocity.
For Market Incumbents: Insulate organic certification tier position through backward integration into Dakota and Saskatchewan grain elevator relationships, securing supply against weather-driven input volatility. Deepen channel control by locking multi-year corporate wellness contracts with Seattle and Austin tech campus feeding operations before private-label substitution accelerates. Facility segregation for gluten-free production lines serves as a defensive moat against emerging clean-label specialists. For New Entrants and Emerging Players: Pursue underpenetrated airport and railway kiosk networks in Japan, where premium tolerance for single-serve pouches exceeds conventional grocery economics. Target fruit-infused variants as the fastest-expanding product type, leveraging spray-dried binding technology to bypass oil-dependent cluster production. A direct-to-employer go-to-market angle bypasses retail slotting fees entirely. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because corporate pantry subscription models generate predictable B2B cash flows insulated from retail promotional cycles. Acquisition target archetype: mid-size co-manufacturers with certified organic supply chains and reduced-oil baking retrofit capacity. The signal to watch is consolidation of breakfast-category suppliers into single-source annual contracts among United States tech campus feeding operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Oat Sourcing | USDA organic certification secures federal feeding program eligibility and supply security. |
| Reduced-Oil Baking Retrofit Investment | Pacific Northwest co-manufacturers gain technical differentiation as EU clean-label standards tighten. |
| Corporate Pantry Subscription Launch | Direct-to-employer distribution captures recurring B2B revenue with reduced customer acquisition cost. |
| Biodegradable Pouch Material Innovation | EU Green Deal compliance unlocks shelf access in German and Dutch retail chains. |
| Gluten-Free Facility Segregation | Third-party validation timelines create defensive moats against emerging clean-label competitors. |
Research Methodology
Desk research of FDA nutrition-labeling guidance documents, USDA organic certification standards, and EFSA health claims databases preceded structured interviews with co-manufacturer operations directors, corporate wellness program administrators, and retail category buyers across United States, German, and Japanese markets. Secondary validation drew from Nielsen retail audit data, customs records for oat and grain trade flows, and SEC filings of publicly traded food manufacturers. Bottom-up volume modeling triangulated against top-down category sizing from syndicated market data.
Assumptions held fixed include current FDA serving-size labeling rigor, EU Green Deal packaging directive timelines, and corporate wellness program reimbursement standards across the analysis window. Segmentation dimensions modeled encompass product type, customer archetype, distribution channel, and packaging format. CAGRs derived from historical growth pattern extrapolation adjusted for identified catalyst and restraint trajectories. Forecast inputs incorporated oat supply concentration risk and fruit-infused binding technology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in commodity oat prices, freight logistics costs, or corporate wellness program funding levels would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and clean-label definition evolution. Quarterly review of oat futures pricing, biodegradable material cost indices, and corporate procurement consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Poland Snack Bar Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
UAE Snack Bar Market
Snacks
Granola Market
Snacks
Fiber Bars Market
Snacks
United Kingdom Energy Bar Market
Snacks
Fruit and Vegetable Chips Market
Snacks
High Carb Low Fat Snack Market
Snacks
Duck Neck (Chinese Snack) Market
Snacks
Crackers Market
Snacks
Europe Frozen Snacks Market
Snacks
Baked Chips Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Nutritional Bar Market
Snacks
Savory Snack Products Market
Snacks
Europe Energy Bar Market