
 South America Energy Bar Market | 2026-2036
South America Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
South America Energy Bar Market Analytics
Subscription-based replenishment services is hardening as a core revenue layer in the South America energy bar sector, shifting one-time purchases into recurring revenue streams. General Mills, Inc. leverages its multinational logistics backbone to sustain consistent cross-border supply into Brazilian retail chains. Probiotica Suplementos anchors its position through deep specialization in sports nutrition channels across Argentina and Chile. Nutrata competes aggressively on plant-based formulations, occupying a distinctive niche in the clean-label segment.
An energy bar is a shelf-stable, nutrient-dense food product typically formulated with protein isolates, carbohydrate binders, and lipid sources, compressed through cold extrusion or slab-forming processes to deliver portable caloric and macronutrient supplementation for active consumers. Protein bars dominate current value generation due to their alignment with bodybuilding and endurance sports culture, while low sugar bars represent the fastest-expanding structural category as ANVISA and regional health ministries tighten added-sugar disclosure rules. Meal replacement bars retain stable demand among urban professionals seeking convenience, though margin pools increasingly favor nutritional bars with functional ingredient claims such as adaptogens or probiotics.
ANVISA governs packaged food standards and nutritional claims in Brazil, the region's largest market, while Argentina's national food code and Chile's front-of-package warning label law shape formulation requirements across the Southern Cone. These frameworks elevate compliance costs for imported brands but simultaneously create protected terrain for local manufacturers who navigate certification pathways more efficiently. Stakeholders must monitor pending Mercosur harmonization proposals and evolving sugar taxation regimes to anticipate which formulation portfolios will retain market access.
Market Dynamics
ANVISA's tightening nutrition labeling requirements are compressing formulation cycles across Brazilian manufacturers, forcing rapid retooling of ingredient decks before enforcement deadlines hit.
Growth Catalysts
- ANVISA Sugar Disclosure Mandates:Front-of-package warning requirements for added sugars are accelerating clean-label reformulation across Brazilian energy bar portfolios.
- Fitness Channel Penetration:Gym culture expansion into secondary Argentine and Chilean cities is creating new distribution nodes for protein-focused SKUs.
- Cold Extrusion Advances:Improved shelf-stability from modified atmospheric packaging is extending product life without synthetic preservatives.
Market Restraints
- Whey Protein Import Dependence:Brazil and Argentina rely on North American dairy isolate supply chains exposed to currency volatility and tariff friction.
- Argentine Food Code Complexity:Provincial enforcement variations create compliance fragmentation that slows national product rollouts.
- Fresh Food Substitution:Traditional arepas and empanadas retain cost and cultural preference advantages in lower-income consumer segments.
Strategic Opportunities
- Subscription Replenishment Models:Direct-to-consumer auto-ship programs in São Paulo and Buenos Aires are converting one-time buyers into recurring revenue streams.
- Adaptogen-Infused Functional Bars:Maca and guaraná sourcing from Peruvian Andean growers supports differentiated positioning in premium channels.
- Mercosur Harmonization:Pending unified standards would eliminate redundant certification costs for manufacturers operating across Brazil, Argentina, Paraguay, and Uruguay.
Industry Challenges
- Food Technologist Scarcity:Specialized expertise in protein binding and texture optimization remains concentrated in São Paulo and Santiago labor markets.
- ANVISA Certification Timelines:Novel ingredient approvals now stretch eighteen to twenty-four months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Energy Bar Market |
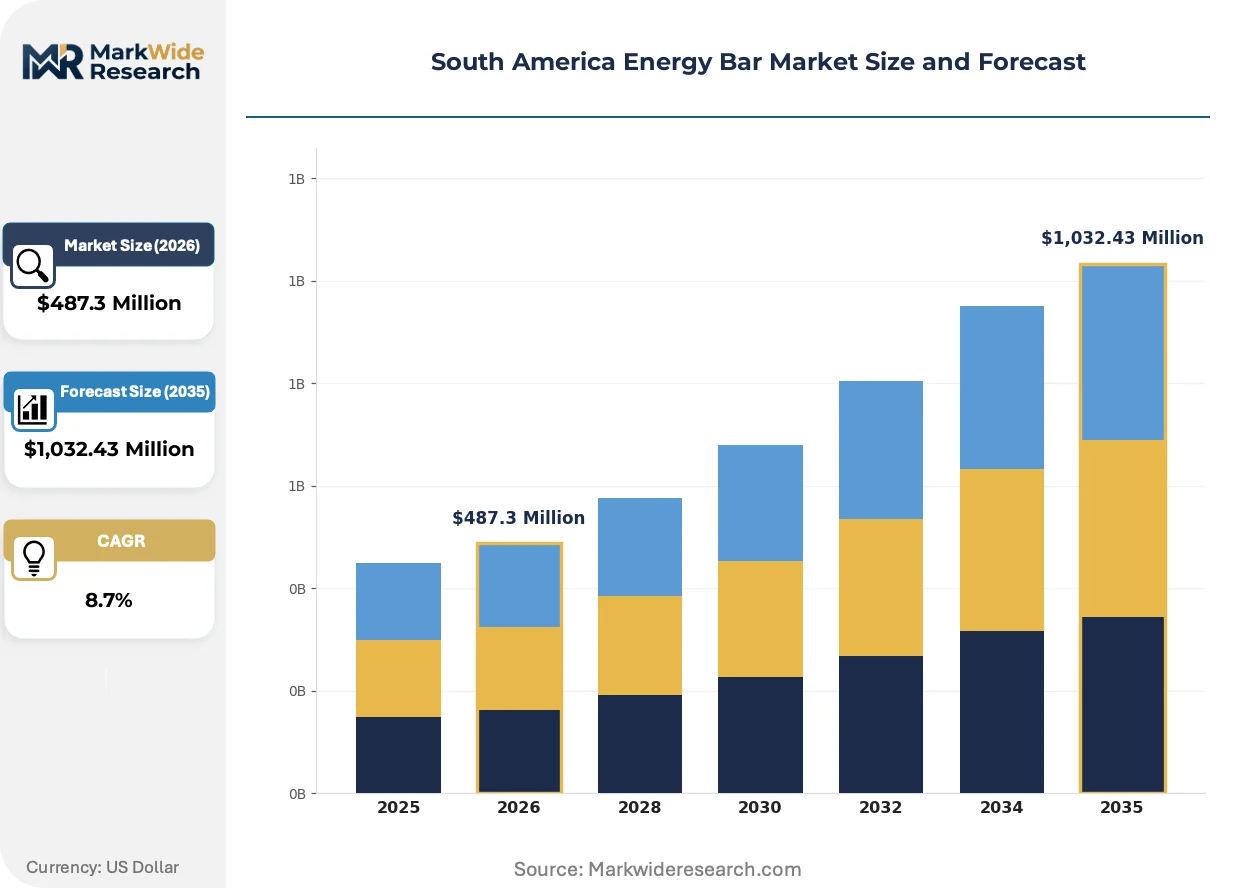
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Meal Replacement Bars, Low Sugar Bars, Nutritional Bars End User: Athletes, Fitness Enthusiasts, Health-Conscious Consumers, Students Ingredient Type: Nuts, Seeds, Chocolate, Fruits Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Health Food Shops |
| Companies Covered | Probiotica Suplementos, Nutrata, General Mills, Inc., biO2 Organic Comercio de Alimentos Ltda, Integralmedica Supplementos Nutricionais Ltda, Simply Good Foods Co. (Quest Nutrition), Puravida, Atlhetica Nutrition, Kellanova Co, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Energy Bar Market Evolving Landscape
Formulation science and distribution architecture are converging to reshape how energy bars reach South American consumers, with regulatory pressure acting as the primary accelerant.
Pea protein isolate is unifying plant-based and conventional protein bar production lines. Brazilian manufacturers are adopting twin-screw extrusion systems capable of handling both dairy and legume proteins interchangeably. This equipment flexibility is unifying supply chains that previously required segregated facilities, reducing capital barriers for clean-label diversification.
Chile's front-of-package warning label law is forcing sugar reduction across all packaged snack categories. Manufacturers must now reformulate or display prominent octagon warnings that depress retail velocity. Premium protein bars with naturally low glycemic loads are capturing shelf space previously occupied by conventional cereal bars in Santiago supermarkets.
Cross-border e-commerce platforms are compressing traditional wholesale distribution layers. Argentine consumers now purchase Brazilian-manufactured bars through Mercado Libre with direct warehouse fulfillment, bypassing importer markups. This channel shift is most pronounced in Mendoza and Córdoba provinces where specialty retail penetration remains thin.
South America Energy Bar Market Segmentation
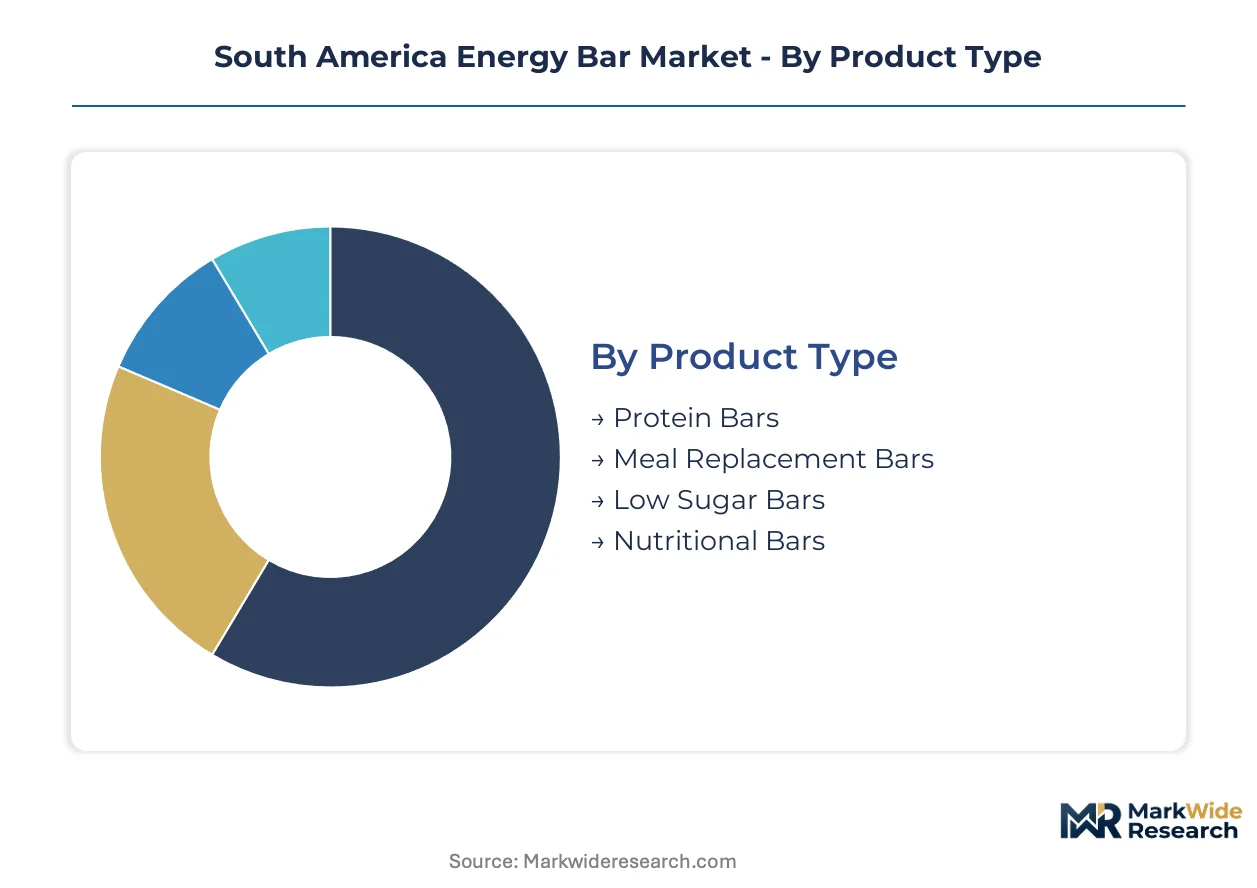
Energy bar manufacturers in South America navigate distinct demand profiles across formulation types, consumption occasions, and retail channels. Segmentation clarity determines where ANVISA compliance investments yield highest returns and which ingredient sourcing strategies align with regional agricultural capacity.
Product Type:
Formulation technology separates portable nutrition into functional tiers based on macronutrient density and processing method.
- Protein Bars:Cold-extruded matrices combining whey or pea isolates with carbohydrate binders deliver 15-25g protein per serving. São Paulo gym chains and Rio de Janeiro CrossFit boxes drive volume, with bodybuilding culture penetrating secondary cities across Paraná and Minas Gerais.
- Meal Replacement Bars:Higher caloric density (300-400 kcal) with balanced macro profiles targets urban professionals skipping sit-down meals. Buenos Aires financial district workers and Santiago corporate towers sustain demand despite fresh food competition from traditional arepas.
- Low Sugar Bars:Glycemic index below 35 through sugar alcohols and fiber enrichment. ANVISA front-of-package warning mandates accelerate reformulation toward this specification.
- Nutritional Bars:Broad-spectrum fortification with vitamins, minerals, and emerging functional ingredients like adaptogens. Peruvian maca and Brazilian guaraná sourcing supports premium positioning.
Protein bars lead on scale; low sugar bars lead on momentum.
End User:
Consumption occasion and performance aspiration shape purchasing behavior more than demographic profile alone.
- Athletes:Competitive cyclists, marathon runners, and footballers in Brazilian state leagues require batch-tested formulations with precise electrolyte ratios. Clubs in Porto Alegre and Belo Horizonte specify certified suppliers.
- Fitness Enthusiasts:Recreational gym-goers represent the steepest expansion trajectory as boutique fitness studios multiply in Córdoba, Mendoza, and Chile's Concepción metro.
- Health-Conscious Consumers:Clean-label seekers prioritize organic certification and non-GMO verification, concentrated in upper-middle neighborhoods of Santiago and Buenos Aires.
- Students:University populations in São Paulo's Butantã district and Buenos Aires' Belgrano barrio favor value-tier options for between-class consumption.
Fitness enthusiasts claim the fastest volume climb; athletes command the highest per-unit spend.
Ingredient Type:
Raw material sourcing geography determines cost structure and clean-label credibility for South American formulators.
- Nuts:Almonds and cashews from Brazil's Ceará and Rio Grande do Norte orchards provide protein and texture. Local sourcing avoids import tariff exposure that elevates Argentine manufacturing costs.
- Seeds:Chia from Paraguayan growers and quinoa from Bolivian highlands supply omega-3 fatty acids and complete amino acid profiles. Andean supply chains support premium export positioning.
- Chocolate:Cacao from Bahia's Atlantic Forest cooperatives enables single-origin claims. Bean-to-bar integration is accelerating among São Paulo artisanal manufacturers.
- Fruits:Açaí from Pará state and dried mango from Peru's Piura valley deliver antioxidant marketing hooks and natural sweetness buffers against added-sugar regulations.
Nuts dominate current formulation volumes; seeds are gaining share fastest on functional positioning.
Distribution Channel:
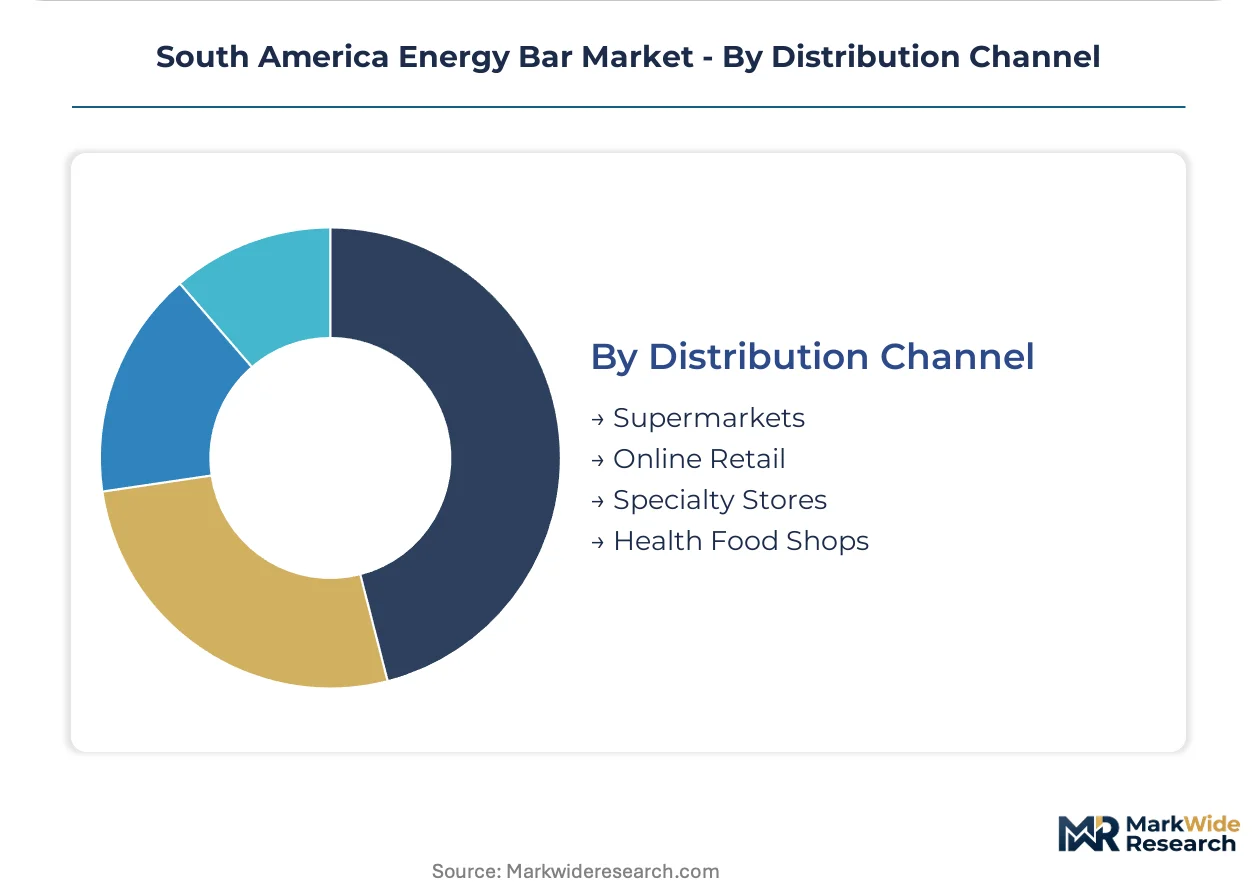
Channel selection determines margin capture and consumer education depth across South America's fragmented retail landscape.
- Supermarkets:Carrefour and GPA hypermarkets in Brazil's Southeast region move standard protein bars through high-velocity shelf placements. Slotting fees favor multinational portfolios with marketing co-investment capacity.
- Online Retail:Mercado Libre direct fulfillment compresses wholesale layers, particularly in Argentine provinces where specialty retail penetration remains thin. Subscription auto-ship models convert São Paulo buyers to recurring revenue.
- Specialty Stores:Running shops and cycling boutiques in Santiago's Las Condes and Buenos Aires' Palermo provide staff education and trial-sized sampling.
- Health Food Shops:Independent retailers in Florianópolis and Bariloche curate organic and plant-exclusive SKUs for discerning locals and tourist traffic.
Supermarkets anchor volume throughput; online retail commands the steepest growth slope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the largest addressable consumer base, while Argentina's regulatory complexity forces longer product development timelines. Chile's front-of-package warning system has accelerated clean-label migration faster than neighboring markets.
Brazil
São Paulo and Rio de Janeiro metropolitan corridors concentrate premium protein bar demand through gym chains and specialty retail. ANVISA's tightening nutrition labeling requirements compress formulation cycles for manufacturers operating in Minas Gerais and Paraná secondary cities. Cold extrusion facilities in São Paulo state are retooling to handle both dairy and plant-based proteins interchangeably.
Argentina
Buenos Aires financial district workers sustain meal replacement bar demand despite competition from traditional arepas and empanadas. Provincial enforcement variations under the national food code create compliance fragmentation that slows national rollouts from Córdoba and Mendoza production nodes. Cross-border e-commerce through Mercado Libre compresses wholesale layers for Argentine consumers accessing Brazilian-manufactured products.
Chile
Santiago's Las Condes district and corporate towers drive premium functional bar consumption among health-conscious professionals. Front-of-package octagon warning labels for added sugars force reformulation or depress retail velocity for conventional cereal bars. Specialty running shops and cycling boutiques in Concepción metro provide staff education and trial-sized sampling for endurance-focused SKUs.
Peru
Andean maca and guaraná sourcing from highland growers supports differentiated positioning in premium export channels. Lima's upper-middle neighborhoods concentrate clean-label seekers prioritizing organic certification and adaptogen fortification. Peruvian dried mango from Piura valley delivers antioxidant marketing hooks for regional formulation partners.
Colombia
Bogotá's boutique fitness studio expansion mirrors Argentine gym culture penetration patterns in secondary cities. Açaí from Pará state supply chains extend into Colombian formulation networks for natural sweetness buffers. Health food shops in Medellín curate plant-exclusive SKUs for discerning locals and tourist traffic from coffee region visitors.
South America Energy Bar Market Competitive Landscape
Top-tier vendors anchor multinational logistics backbones, while mid-tier regional specialists occupy channel-specific niches. The market structures around three tiers: global CPG conglomerates with cross-border supply chains, South American sports nutrition specialists with deep gym channel penetration, and local clean-label formulators with Andean ingredient sourcing advantages. Two dominant competitive moves are subscription-based replenishment service deployment and twin-screw extrusion equipment upgrades enabling protein line flexibility.
Among Brazil-based manufacturers, Nutrata occupies a position within the plant-based clean-label archetype, while Probiotica Suplementos anchors the sports nutrition specialist tier across Argentina and Chile. General Mills, Inc. represents the multinational CPG archetype with sustained cross-border supply into Brazilian retail chains.
| Leading Market Players |
|---|
| Probiotica Suplementos |
| Nutrata |
| General Mills, Inc. |
| biO2 Organic Comercio de Alimentos Ltda |
| Integralmedica Supplementos Nutricionais Ltda |
| Simply Good Foods Co. (Quest Nutrition) |
| Puravida |
| Atlhetica Nutrition |
| Kellanova Co |
| Others |
Value Network & Pricing Analysis
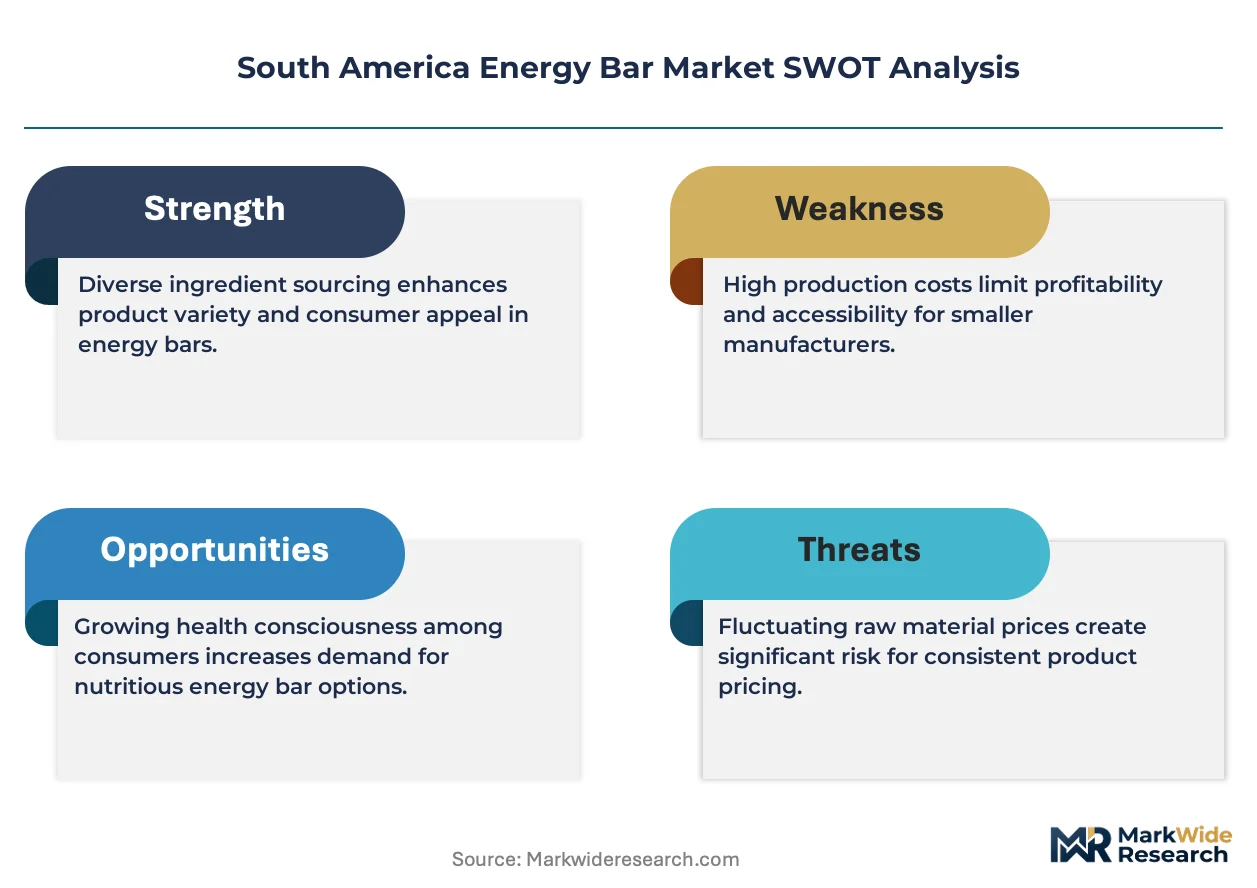
Family-owned mid-cap Brazilian manufacturers anchor supply-side discipline through intergenerational capital allocation that resists short-term price wars despite whey protein import volatility. Their ownership structure sustains pricing power in São Paulo's premium channel while funding cold extrusion upgrades that compress unit costs.
Pricing Analysis
Capacity additions in Minas Gerais and Paraná are reshaping price floors for standard protein bars as twin-screw extrusion equipment spreads. Three-tier pricing structure across premium, standard, and economy levels separates certified organic SKUs from conventional formulations and value-tier private label. Pricing pressure stems from ANVISA compliance investments that elevate fixed costs for smaller Brazilian producers. Health-conscious consumers in Santiago's Las Condes show lowest price sensitivity; students in Buenos Aires' university districts exhibit highest elasticity.
Supply Chain Analysis
Direct-to-specialty-retail channels handle premium buyer demand in Rio de Janeiro and Buenos Aires, while supermarket distributors manage high-velocity standard SKUs. Raw material sourcing concentrates in Brazil, Argentina, and Peru—whey isolates draw from North American dairy processors, pea protein from domestic legume processors, and Andean maca from Peruvian highland cooperatives. Single-source vulnerability in whey protein imports exposes Brazilian formulators to currency-driven cost spikes. Distribution runs through layered wholesale networks in Argentina, contrasting with direct retail partnerships dominant in Chile.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ANVISA's front-of-package sugar warning mandates force continuous reformulation investment that advantages scaled manufacturers with R&D bandwidth.
For Market Incumbents: To counter cross-border e-commerce compression of wholesale margins, secure exclusive shelf placements through marketing co-investment with Carrefour and GPA hypermarkets. Anchor defensibility by backward integration into Brazilian Ceará almond orchards and Bahia cacao cooperatives to neutralize import tariff exposure. For New Entrants and Emerging Players: Twin-screw extrusion flexibility serves as the technology-first wedge for plant-exclusive positioning in Florianópolis and Bariloche health food shops. Target underpenetrated secondary Argentine cities—Córdoba and Mendoza gym channels—through Mercado Libre direct fulfillment with subscription auto-ship conversion. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Brazilian manufacturers lacking ANVISA certification infrastructure but holding established retail relationships. Five-to-ten-year viability hinges on Mercosur harmonization execution; monitor pending unified standards proposals as the inflection signal for cross-border scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Twin-Screw Extrusion Equipment Upgrade | Unifies dairy and plant protein production lines for Brazilian manufacturers seeking clean-label diversification. |
| Subscription Auto-Ship Program Launch | Converts São Paulo and Buenos Aires one-time buyers into recurring revenue streams with higher lifetime value. |
| Andean Ingredient Sourcing Partnership | Secures Peruvian maca and guaraná supply for premium functional bar positioning in Santiago specialty channels. |
| ANVISA Pre-Certification Investment | Accelerates novel ingredient approval timelines that currently stretch eighteen to twenty-four months. |
| Mercado Libre Direct Fulfillment Integration | Bypasses Argentine importer markups in Mendoza and Córdoba provinces with thin specialty retail penetration. |
Research Methodology
Coverage spans Brazil, Argentina, Chile, Peru, and Colombia, with primary inputs from each national market. The approach combines structured interviews with brand managers at Brazilian manufacturers, category buyers at GPA and Carrefour, supply planners at Andean ingredient cooperatives, and regulatory affairs specialists navigating ANVISA certification pathways. Secondary validation draws from ANVISA registration databases, Chilean Ministry of Health front-of-package labeling filings, Mercosur harmonization proposal documents, and Nielsen retail audit data. Bottom-up SKU-level volume builds triangulate against top-down category expenditure estimates.
Granularity-level modeling operates at the intersection of formulation type, distribution channel, and metropolitan demand cluster. The analytical framework projects value and volume across the analysis window by segmenting protein bars, meal replacement bars, low sugar bars, and nutritional bars with distinct growth trajectories. CAGRs derive from trend extrapolation of gym channel penetration rates, ANVISA compliance cost absorption curves, and cross-border e-commerce velocity metrics.
The model holds under stable ANVISA enforcement timelines and continued Mercosur trade integration; deviation in regulatory delay extensions or currency volatility spikes would shift trajectory assumptions. Forecasts reflect documented base-case conditions with acknowledged sensitivity to whey protein import tariff fluctuations and provincial enforcement variations under Argentina's national food code. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
China Snack Bar Market
Snacks
Spain Energy Bar Market
Snacks
South America Snack Bar Market
Snacks
Salty Puffed Snacks Market
Snacks
Veggie Chips Market
Snacks
Spain Snack Bar Market
Snacks
UK Snack Market
Snacks
India Energy Bar Market
Snacks
Baked Chips Market
Snacks
Europe Extruded Snack Food Market
Snacks
Baked Savoury Snacks Market
Snacks
Protein Crisps Market
Snacks
Allergy-Free Snacks Market
Snacks
North America Fruit Snacks Market
Snacks
Snacks Market
Snacks
Low-Calorie Sweet Treats Market