
 Type-1 Diabetes Treatment Market | 2026-2036
Type-1 Diabetes Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Type-1 Diabetes Treatment Market Outlook
North American biomanufacturing expansion is reshaping supply security for analog insulin and automated delivery systems. Novo Nordisk leverages Danish fermentation expertise to sustain bulk active pharmaceutical ingredient output for global fill-finish networks. Eli Lilly and Company anchors North American glucagon-like peptide-1 innovation through Indiana-based recombinant protein facilities. Sanofi competes on European biosimilar insulin cost positioning while maintaining legacy basal insulin brand strength.
Type-1 diabetes treatment encompasses exogenous insulin replacement, automated glucose sensing, and algorithm-driven delivery systems engineered to maintain euglycemia in autoimmune pancreatic beta-cell destruction. Recombinant human insulin and insulin analogs remain the pharmacological backbone, with continuous glucose monitors providing interstitial fluid glucose readings every one to five minutes to inform dosing decisions. Insulin pumps command premium positioning through closed-loop integration with continuous glucose monitors, while pen devices retain volume leadership in daily multiple injection regimens across hospital and homecare settings. Subcutaneous administration dominates delivery economics, though intravenous routes persist in acute diabetic ketoacidosis management within critical care environments.
FDA premarket approval pathways and EMA centralized marketing authorizations govern device- drug combination products, with ISO 15197 standards enforcing glucose monitor accuracy thresholds that determine reimbursement eligibility. The EU Medical Device Regulation imposes post-market surveillance obligations on continuous glucose monitor manufacturers that extend clinical evidence requirements beyond legacy directives. Stakeholders must monitor evolving artificial pancreas interoperability standards and payer evidence requirements for automated insulin delivery prior to capital allocation decisions.
Market Dynamics
Closed-loop automated insulin delivery systems are compressing the gap between continuous glucose monitoring data and real-time therapeutic response, forcing manufacturers to integrate hardware, software, and algorithmic control into unified platforms rather than discrete device categories.
Growth Catalysts
- EMA Adaptive Pathway:The European Medicines Agency's accelerated assessment framework for novel diabetes devices compresses time-to-market for hybrid closed-loop systems targeting pediatric populations.
- Pediatric Homecare Migration:Hospital-to-home transitions in Germany, Japan, and the United States are expanding reimbursement for remote patient monitoring and caregiver-administered automated delivery.
- Interoperability Standards:IEEE 11073 and ISO 15197 harmonization is enabling sensor-pump data exchange across manufacturer ecosystems, reducing patient lock-in and switching costs.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Fermentation-based insulin bulk production clusters in Denmark and the United States, creating single-source vulnerability for global fill-finish networks.
- Reimbursement Heterogeneity:Japan's MHLW separates device and drug payment categories, complicating bundled pricing for integrated closed-loop systems versus discrete components.
- Technical Limitation:Current continuous glucose monitors require 10-15 minute lag between interstitial fluid glucose and actual blood glucose, limiting algorithm responsiveness during rapid metabolic shifts.
Strategic Opportunities
- Underpenetrated Geography:India's tier-2 and tier-3 cities present white space for pen-based analog insulin and basic continuous glucose monitors as CDSCO streamlines medical device registration.
- Technology Convergence:Integration of glucagon-ready dual-hormone pumps with machine learning hypoglycemia prediction algorithms addresses the "dead-in-bed" syndrome unmet need.
- Distribution Innovation:Direct-to-patient subscription models for disposable sensors and infusion sets bypass traditional hospital procurement in cash-pay markets.
Industry Challenges
- Algorithm Validation Burden:FDA premarket approval for adaptive learning insulin dosing requires multi-phase clinical trials demonstrating safety across age, BMI, and comorbidity variation.
- Legacy System Integration:Health systems running non-interoperable electronic health records face middleware development costs to incorporate real-time glucose data streams into clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Type-1 Diabetes Treatment Market |
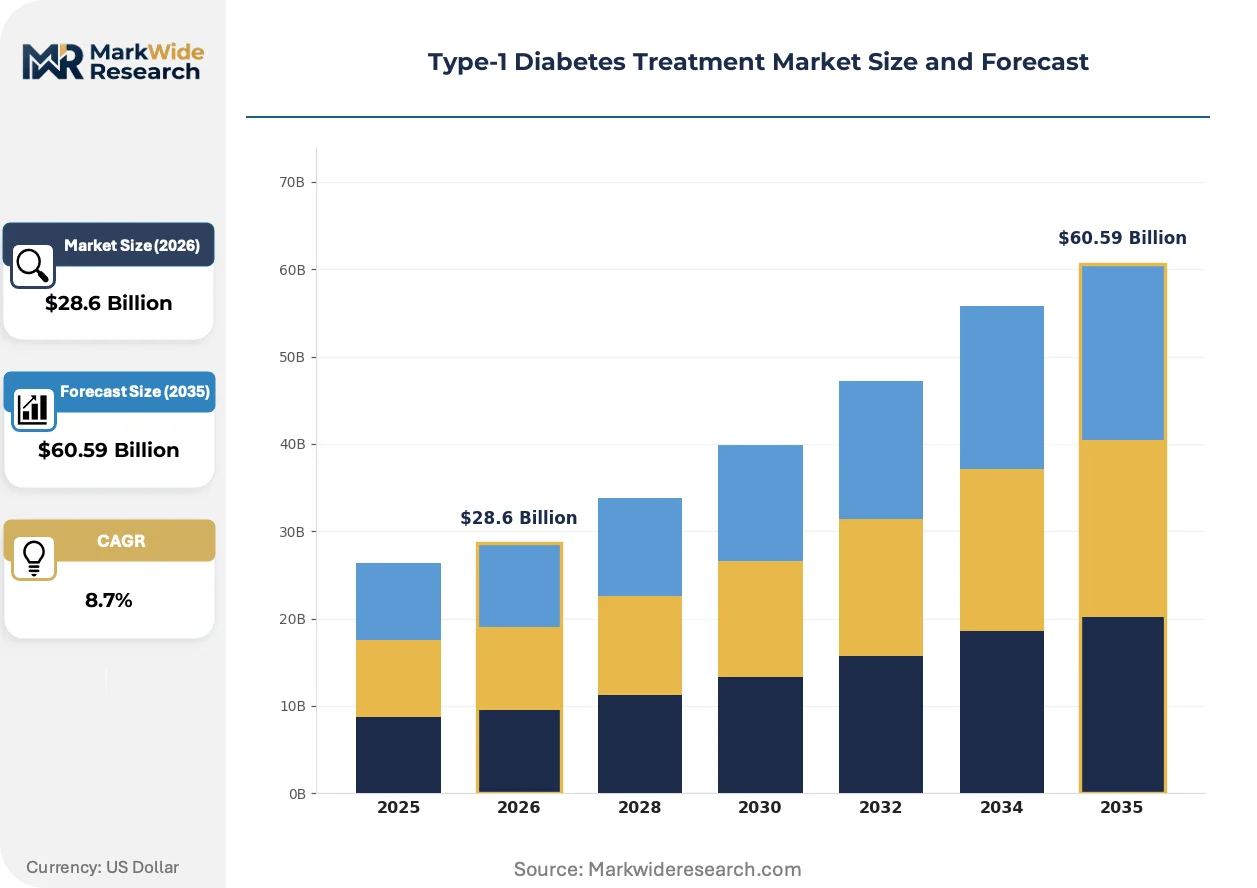
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Continuous Glucose Monitors, Insulin Pumps, Pen Devices Administration Route: Subcutaneous, Intravenous, Intramuscular, Oral End User: Hospitals, Clinics, Homecare, Pharmacies Distribution Channel: Retail, Online, Wholesalers, Direct Sales |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, AstraZeneca, MannKind Corporation, Zealand Pharma, Diamyd Medical, Vertex Pharmaceuticals, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Type-1 Diabetes Treatment Market Strategic Shifts
Algorithmic personalization is replacing fixed insulin-to-carbohydrate ratios as the dominant therapeutic paradigm, with machine learning models ingesting continuous glucose, activity, and nutritional data to generate patient-specific dosing recommendations.
Dual-hormone automated delivery systems combining insulin and glucagon in a single wearable platform are rendering obsolete single-hormone closed-loop systems that rely solely on insulin suspension to prevent hypoglycemia. Pediatric endocrinology practices in the United States and Germany are piloting these systems for nocturnal glucose control. The structural consequence is a shift from reactive hypoglycemia alarms to proactive glucagon micro-dosing, compressing the safety margin required for automated dosing algorithms.
EU Medical Device Regulation post-market surveillance obligations are extending clinical evidence requirements for continuous glucose monitor manufacturers beyond legacy directive timelines. Manufacturers must now submit periodic safety update reports and real-world performance data to notified bodies. The sensor segment faces the steepest compliance burden, with Germany and France requiring additional national health technology assessments for reimbursement maintenance.
Patients are consolidating purchasing decisions through integrated pharmacy-benefit managers that bundle sensors, pumps, and insulin under single formulary contracts. This channel consolidation displaces discrete device procurement through hospital outpatient clinics. The United States exhibits the most pronounced concentration, with three pharmacy benefit managers controlling access for the majority of commercially insured lives.
Type-1 Diabetes Treatment Market Segmentation
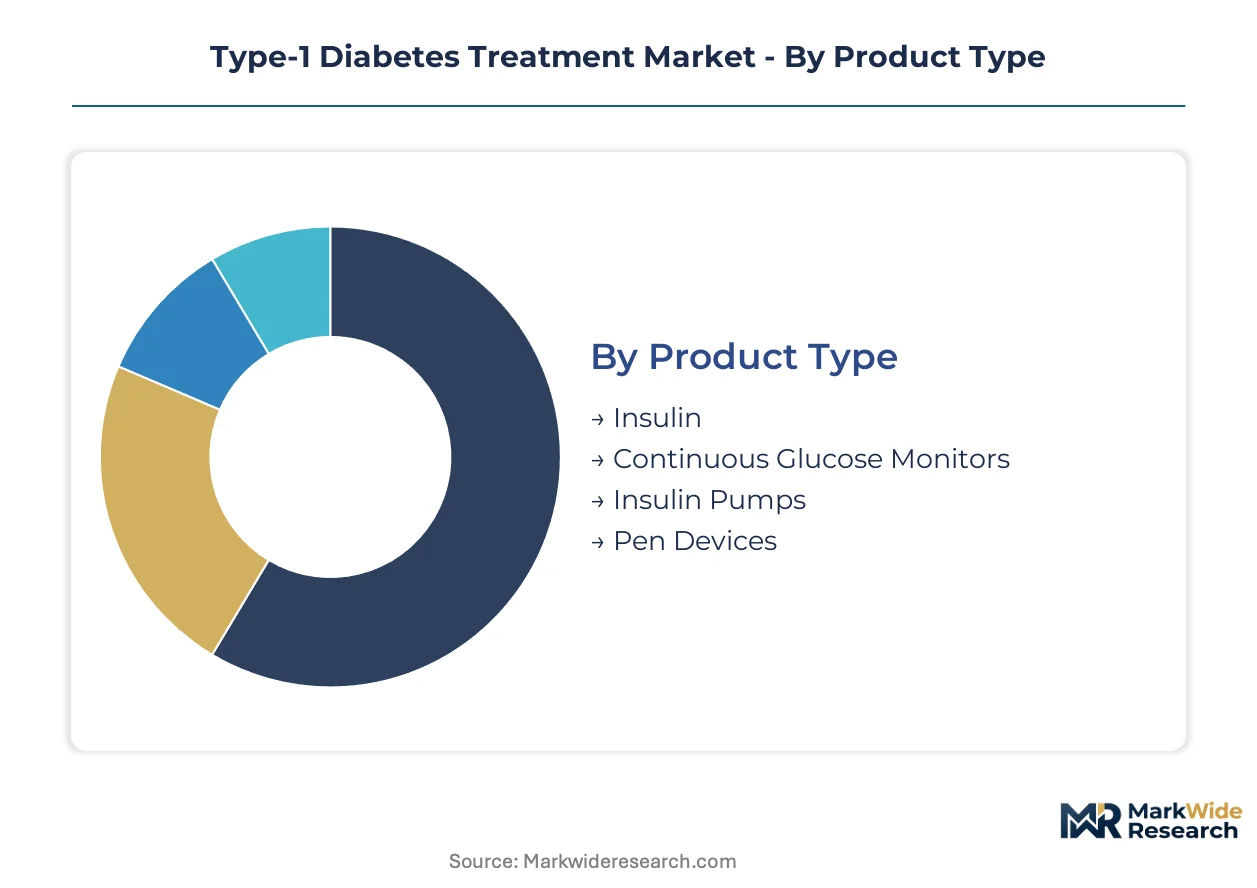
Product, delivery, and care-setting dimensions reveal divergent margin profiles across the Type-1 diabetes treatment landscape. Insulin pumps and continuous glucose monitors command premium positioning through algorithm integration, while pen devices and retail channels anchor volume economics in cost-sensitive segments.
Product Type:
Use-case spectrum spans intensive glycemic control in automated closed-loop systems to basic insulin replacement in resource-limited settings.
- Insulin:Recombinant human insulin and rapid-acting analogs constitute the pharmacological foundation for all Type-1 diabetes management protocols. Demand concentrates in the United States and Germany where pharmacy benefit managers negotiate analog insulin formulary placement against biosimilar alternatives.
- Continuous Glucose Monitors:Interstitial fluid sensors transmit glucose readings every one to five minutes to inform dosing algorithms and reduce hypoglycemic events. Adoption accelerates in pediatric homecare across Japan and the United States as FDA breakthrough device designations streamline reimbursement pathways.
- Insulin Pumps:Wearable infusion devices enable programmable basal rates and bolus dosing with closed-loop CGM integration.
- Pen Devices:Disposable and reusable injection systems dominate daily multiple injection regimens in hospital and ambulatory settings.
Established volume favors pen devices; emerging adoption favors continuous glucose monitors.
Administration Route:
Delivery economics stratify across acute intervention requirements and chronic self-management capabilities.
- Subcutaneous:Abdominal, thigh, and arm tissue deposition enables patient-administered insulin absorption with predictable pharmacokinetic profiles. This route anchors outpatient therapy in the United States, Germany, and Japan where reimbursement frameworks favor home-based administration.
- Intravenous:Direct vascular insulin delivery achieves immediate glycemic control in diabetic ketoacidosis and perioperative management. Demand concentrates in hospital critical care units across developed healthcare systems where rapid metabolic correction determines clinical outcomes.
- Intramuscular:Faster absorption than subcutaneous routes serves specific clinical scenarios requiring accelerated insulin onset.
- Oral:Investigational delivery platforms seek to bypass injection burden through gastrointestinal absorption enhancement technologies.
Subcutaneous administration maintains volume dominance; intravenous routes retain acute-care premium positioning.
End User:
Care setting migration is reshaping procurement authority from hospital purchasing committees to patient-directed selection.
- Homecare:Patient and caregiver-managed therapy encompasses automated insulin delivery, remote glucose monitoring, and telemedicine endocrinology consultations. Pediatric homecare adoption accelerates in Germany and the United States as hospital-to-home transitions expand reimbursement for remote patient monitoring technologies.
- Hospitals:Inpatient glycemic management protocols govern insulin dosing in surgical, medical, and critical care units. Demand concentrates in tertiary centers across Japan where MHLW device-drug payment separation complicates bundled closed-loop system procurement.
- Clinics:Outpatient endocrinology practices manage insulin titration and technology training.
- Pharmacies:Community dispensaries anchor pen device and analog insulin distribution in cash-pay markets.
Homecare represents the fastest-growing trajectory; hospitals retain high-acuity premium segments.
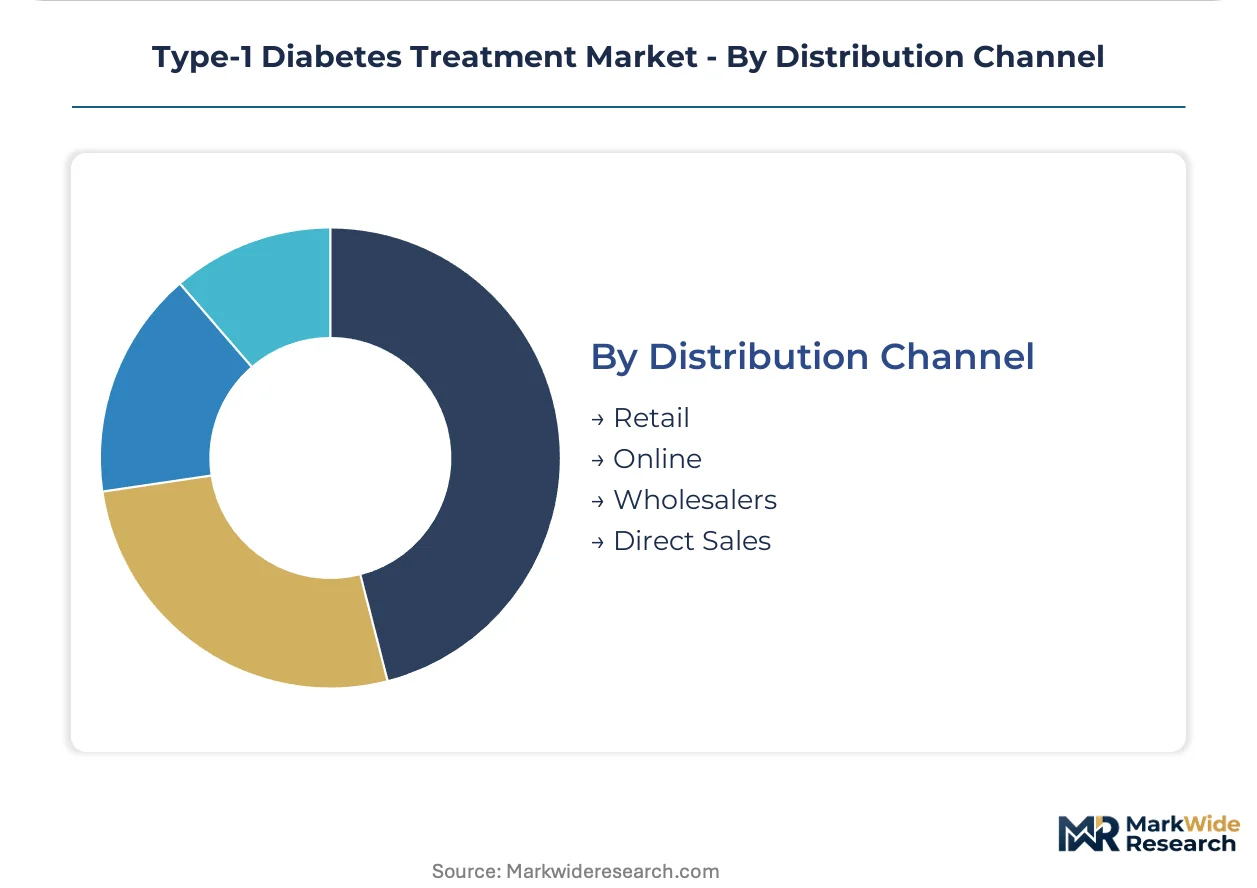
Distribution Channel:
Channel consolidation through integrated pharmacy benefit managers is displacing discrete device procurement.
- Retail:Brick-and-mortar pharmacies provide immediate insulin access and emergency supply replacement for established patients. Volume concentrates in the United States where three pharmacy benefit managers control formulary access for commercially insured lives.
- Online:Direct-to-patient subscription models for disposable sensors and infusion sets bypass traditional hospital procurement in cash-pay markets. Adoption accelerates in India's tier-2 and tier-3 cities as CDSCO streamlines medical device registration pathways.
- Wholesalers:National distributors manage cold-chain logistics for temperature-sensitive biologics.
- Direct Sales:Manufacturer field representatives support pump training and algorithm personalization.
Retail channels maintain insulin volume leadership; online platforms gain fastest traction in sensor and consumable segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish fermentation capacity anchors bulk insulin active pharmaceutical ingredient supply for global fill-finish networks. Novo Nordisk's Kalundborg facilities process recombinant proteins for worldwide distribution. Three additional markets concentrate device innovation, reimbursement policy, and manufacturing scale.
United States
Pharmacy benefit managers bundle sensors, pumps, and insulin under single formulary contracts for commercially insured lives. FDA breakthrough device designations compress premarket review timelines for hybrid closed-loop systems. Indianapolis anchors Eli Lilly's recombinant protein manufacturing for glucagon-like peptide-1 innovation.
Germany
Hospital-to-home transitions expand reimbursement for remote patient monitoring and caregiver-administered automated delivery. EMA adaptive pathway approvals accelerate pediatric access to novel hybrid closed-loop devices. Baden-Württemberg clusters continuous glucose monitor engineering talent and notified body expertise.
Japan
Pediatric endocrinology practices pilot dual-hormone automated delivery systems for nocturnal glucose control. MHLW separates device and drug payment categories, complicating bundled pricing for integrated closed-loop procurement. Tokyo-Osaka corridor concentrates metabolic device clinical trial infrastructure.
India
Tier-2 and tier-3 cities present white space for pen-based analog insulin and basic continuous glucose monitors. CDSCO streamlines medical device registration pathways for sensor and pump market entry. Maharashtra and Gujarat host emerging distribution hubs for direct-to-patient subscription models.
Type-1 Diabetes Treatment Market Competitive Environment
Integrated biopharmaceutical conglomerates and specialized metabolic device developers split the market into distinct capability zones. Three strategic archetypes dominate: fermentation-based bulk insulin producers with global fill-finish networks; algorithm-hardware integrators commanding closed-loop system premiums; and biosimilar cost-positioning specialists competing on European tender economics. Competitive moves concentrate on vertical integration into sensor manufacturing and strategic partnerships for dual-hormone pump development.
Within the fermentation-dominant tier, Novo Nordisk and Eli Lilly and Company exemplify supply-security strategies through captive bulk active pharmaceutical ingredient production. Sanofi occupies a position bridging legacy basal insulin brand strength with European biosimilar cost competition. These three anchors collectively represent the full spectrum of insulin sourcing economics from Danish fermentation expertise to North American recombinant protein innovation.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| MannKind Corporation |
| Zealand Pharma |
| Diamyd Medical |
| Vertex Pharmaceuticals |
| Merck |
| Others |
Value Chain & Pricing Dynamics
Copenhagen-Frankfurt air freight corridors carry temperature-sensitive insulin active pharmaceutical ingredients under cold-chain protocols, with per-kilogram logistics costs shaping margin allocation between Danish fermentation sites and German fill-finish operations. This freight-cost dynamic concentrates pricing power with bulk API producers while forcing downstream device manufacturers to differentiate through algorithm premiums rather than commodity insulin margins.
Pricing Analysis
FDA premarket approval pathways dictate the pricing tier structure for integrated closed-loop systems, separating premium hybrid devices with breakthrough device designation from standard insulin pumps lacking CGM interoperability. Price differentiation rests on ISO 15197 certification tier and algorithm personalization depth. Cost compression in sensor manufacturing is intensifying because of EU MDR post-market surveillance obligations extending clinical evidence requirements. Cash-pay markets in India exhibit highest price sensitivity; pediatric homecare segments in Germany and Japan show lowest sensitivity due to comprehensive reimbursement frameworks.
Supply Chain Analysis
Export-control restrictions on precision sensor manufacturing equipment limit continuous glucose monitor production expansion outside established jurisdictions. Fermentation-based insulin bulk production concentrates in Denmark and the United States, with recombinant protein engineering anchored in Indiana and North Carolina facilities. Supply chain risk centers on single-source vulnerability for glucagon-like peptide-1 analog precursors. Distribution runs through integrated pharmacy benefit managers in the United States and hospital procurement committees in Japan, with direct-to-patient subscription models emerging in Indian tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Type-1 diabetes treatment demand follows cyclical patterns tied to pediatric diagnosis incidence waves, with the current upswing driven by expanded newborn screening protocols across developed healthcare systems.
For Market Incumbents: Build regulatory data moats through continuous real-world evidence generation for adaptive dosing algorithms. Deepen backward integration into sensor manufacturing to reduce dependency on precision photonics suppliers. Defend against biosimilar insulin erosion by anchoring formulary placement through bundled closed-loop contracts with United States pharmacy benefit managers.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 cities through pen-based analog insulin paired with basic continuous glucose monitors as CDSCO registration pathways simplify. Target caregiver-administered automated delivery systems for pediatric homecare in Germany, where hospital-to-home transitions expand reimbursement eligibility. Pursue direct-to-patient subscription models bypassing traditional hospital procurement channels.
For Investors and Strategic Acquirers: Algorithm-hardware integrators with FDA breakthrough device designations represent the highest-conviction acquisition archetype for exposure to closed-loop premiumization. Long-term viability hinges on demonstrated interoperability across manufacturer ecosystems and sustained reimbursement maintenance under evolving EU MDR surveillance obligations. Monitor EMA adaptive pathway approval velocity as the key inflection signal for pediatric market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Hormone Pump Development | Addresses unmet hypoglycemia prevention need through proactive glucagon micro-dosing in nocturnal settings. |
| Sensor Manufacturing Scale-Up | Reduces dependency on single-source precision photonics suppliers for CGM electrode production. |
| Algorithm Personalization Investment | Machine learning models ingesting activity and nutritional data replace fixed insulin-to-carbohydrate ratios. |
| Pediatric Reimbursement Strategy | EMA adaptive pathway approvals compress time-to-market for hybrid closed-loop systems targeting children. |
| Interoperability Standards Adoption | IEEE 11073 harmonization enables sensor-pump data exchange across manufacturer ecosystems reducing patient lock-in. |
Study Parameters
The analysis maps insulin analogs, continuous glucose monitors, insulin pumps, and pen devices, each validated through endocrinologists, hospital purchasing committees, biomedical engineers, and pharmacy benefit manager formulary directors. Primary interviews with regulatory affairs specialists and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA centralized marketing authorization databases, ClinicalTrials.gov records, and CMS Medicare reimbursement data. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Assumptions held fixed include current FDA premarket review timelines and existing EU MDR post-market surveillance obligations, while reimbursement pathway evolution and interoperability standard adoption rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, administration route, end user care setting, and distribution channel, with geographic regulatory clusters treated as distinct forecast inputs. CAGRs derived from historical analog insulin volume growth and CGM adoption curve analysis, incorporating pediatric homecare migration rates and algorithm-driven device replacement cycles.
Sensitivities concentrate around FDA breakthrough device designation velocity, EMA adaptive pathway approval consistency, and Japanese MHLW device-drug bundling policy evolution. Forecasts reflect these documented assumptions and acknowledged risk factors. Material shifts in reimbursement heterogeneity or interoperability enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Europe Diabetes Care Devices Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
North America Insulin Infusion Pumps Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market