
 Global Wireless Sensors Network Market | 2026-2036
Global Wireless Sensors Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Sensors Network Market Analytics
The gap between premium and commodity tiers is hardening. High-reliability nodes with sub-millisecond latency and hardened security stacks now command fundamentally different procurement criteria than cost-optimized units for environmental logging. Texas Instruments leverages its integrated radio-plus-microcontroller portfolio to sustain design-win rates in process automation. Honeywell International anchors its position through backward integration into MEMS fabrication, while STMicroelectronics competes on silicon-level power optimization for battery-constrained nodes.
A wireless sensors network comprises distributed autonomous transducers that acquire physical or chemical data and relay it through multi-hop radio links to aggregation gateways or edge processors, typically operating in unlicensed ISM bands below 1 GHz or at 2.4 GHz with transmit powers under 100 mW. Its primary commercial purpose is eliminating wired infrastructure in monitoring scenarios where cabling costs exceed node economics or where mobility is essential. Temperature sensors lead unit shipments due to their ubiquity across industrial automation and cold-chain applications, while LoRa technology captures the fastest expansion by combining kilometer-range propagation with decade-long battery autonomy. Smart agriculture as an application dimension sits at the margin-accretion frontier where precision irrigation and livestock tracking justify premium node pricing.
The FCC governs spectrum allocation and emission limits for unlicensed operation in the United States, directly constraining available channels and power budgets for device designers. ETSI harmonizes parallel frameworks across Europe, with the Radio Equipment Directive mandating interoperability testing that shapes go-to-market timelines. The EU AI Act's risk-classification schema will increasingly govern sensor networks that feed automated decision systems, particularly in healthcare monitoring and smart city deployments. Stakeholders must monitor how spectrum reallocation proceedings and cybersecurity certification mandates in major economies reshape hardware roadmaps and regional deployment priorities.
Market Dynamics
The EU Green Deal's digitalization mandates are compressing deployment timelines for energy-efficient networked devices, forcing hardware roadmaps to prioritize sub-100 mW power budgets and interoperability certification before market entry.
Growth Catalysts
- LoRa propagation standards:Kilometer-range radio links with decade-long battery autonomy unlock precision agriculture deployments in water-stressed regions. Soil moisture tracking nodes in Brazil's Cerrado biome justify premium pricing through irrigation cost savings.
- FCC Part 15 rules:Unlicensed ISM band allocation below 1 GHz enables rapid field deployment without spectrum licensing delays. Industrial automation buyers in the United States leverage this for factory retrofit programs.
- Process automation retrofit cycles:Germany's industrial corridor is replacing wired condition monitoring with wireless nodes to eliminate cabling costs exceeding node economics in legacy facilities.
Market Restraints
- MEMS foundry concentration:Hardened sensor fabrication relies on a limited supplier base in East Asia, creating single-source vulnerability for high-reliability nodes.
- EU AI Act risk classification:Sensor networks feeding automated healthcare monitoring decisions face mandatory conformity assessment delays that extend go-to-market timelines by 8-14 months.
- Sub-GHz spectrum fragmentation:Regional channel allocation mismatches between ETSI harmonized bands and FCC allocations force hardware variants that inflate inventory carrying costs.
Strategic Opportunities
- Livestock tracking in Australia:Cattle ranching operations across Queensland and New South Wales represent underpenetrated demand for GPS-enabled ear-tag nodes with multi-year battery life.
- EU Cybersecurity Certification:The Radio Equipment Directive's forthcoming cybersecurity mandates create first-mover advantage for vendors pre-certifying hardware stacks before mandatory enforcement.
- Edge-AI sensor fusion:Convergence of MEMS accelerometers with on-device inference engines enables predictive maintenance without cloud dependency, opening premium pricing in rotating equipment monitoring.
Industry Challenges
- RF engineering talent scarcity:Multi-hop mesh protocol optimization requires specialized firmware expertise concentrated in semiconductor design hubs, constraining vendor scaling.
- Legacy SCADA integration:Brownfield industrial sites demand protocol translation gateways that add cost and failure points, complicating value proposition articulation.
- RoHS substance compliance:Solder alloy substitutions for lead-free mandates affect MEMS package hermeticity, requiring process requalification that delays volume ramps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Sensors Network Market |
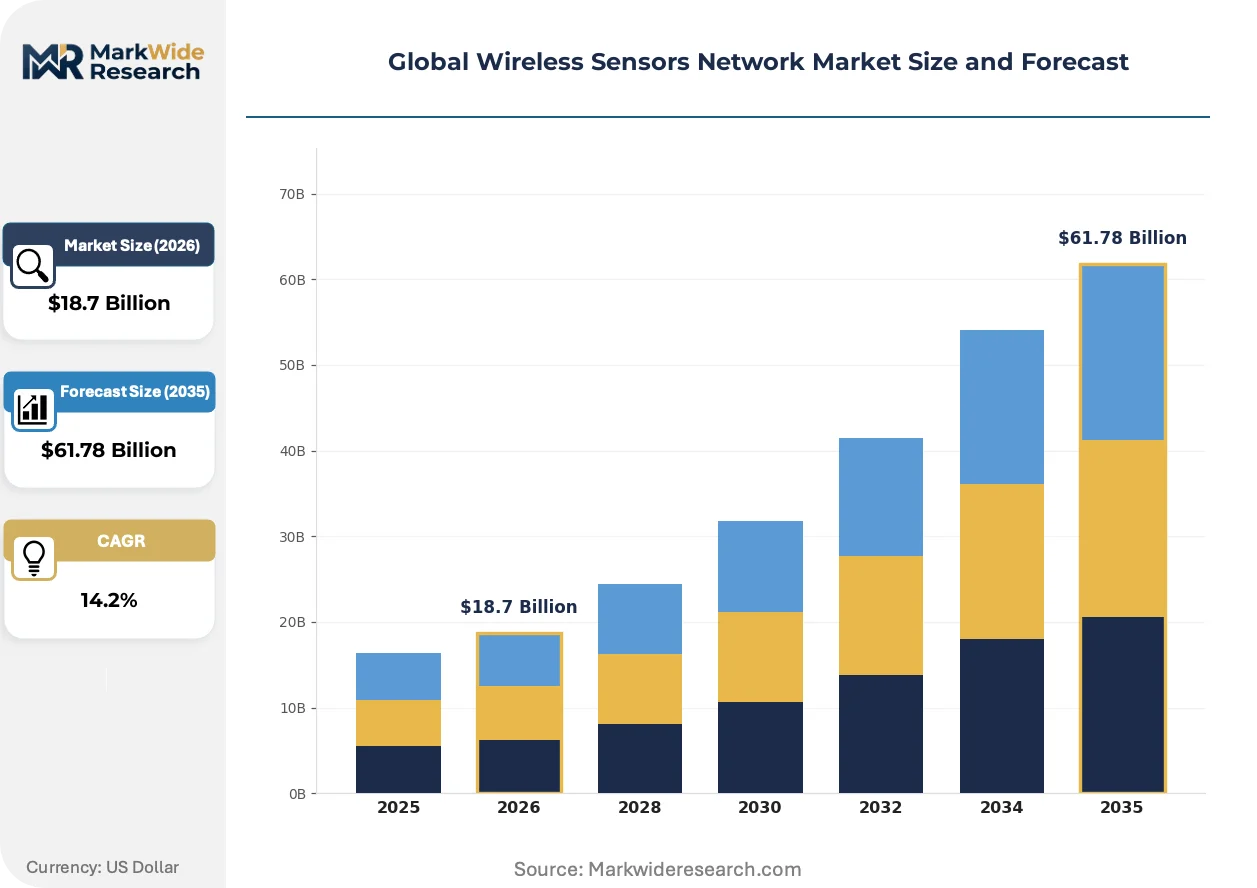
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Light Sensors, Humidity Sensors Application: Environmental Monitoring, Industrial Automation, Smart Agriculture, Healthcare Monitoring Technology: Wi-Fi, Zigbee, LoRa, Bluetooth End User: Manufacturing, Transportation, Healthcare, Smart Cities |
| Companies Covered | NXP Semiconductors, Texas Instruments, STMicroelectronics, Honeywell International, Siemens AG, ABB Ltd, Cisco Systems, Emerson Electric, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Sensors Network Market Evolving Landscape
Radio architecture decisions are fragmenting procurement criteria as buyers separate cost-optimized environmental logging from latency-critical automation use cases, creating divergent hardware optimization paths.
Mesh networking protocols with time-synchronized channel hopping are decentralizing data aggregation away from centralized gateways. Process automation buyers in chemical processing plants are adopting these stacks to eliminate single points of failure. The structural consequence is compressing gateway hardware margins while elevating node software value.
ETSI's Radio Equipment Directive now mandates interoperability testing that shapes European go-to-market timelines. Hardware vendors must pre-certify against harmonized standards before CE marking, adding front-loaded engineering cost. Industrial sensor suppliers are responding by consolidating variant counts to amortize certification overhead across higher volumes.
Buying committees in German automotive manufacturing are unbundling sensor hardware from installation services, treating node procurement as commodity while negotiating multi-year calibration contracts separately. This bifurcation is most visible in Baden-Württemberg's supplier ecosystem, where tier-one manufacturers now source nodes through distributor stock programs rather than direct vendor relationships.
Global Wireless Sensors Network Market Segmentation
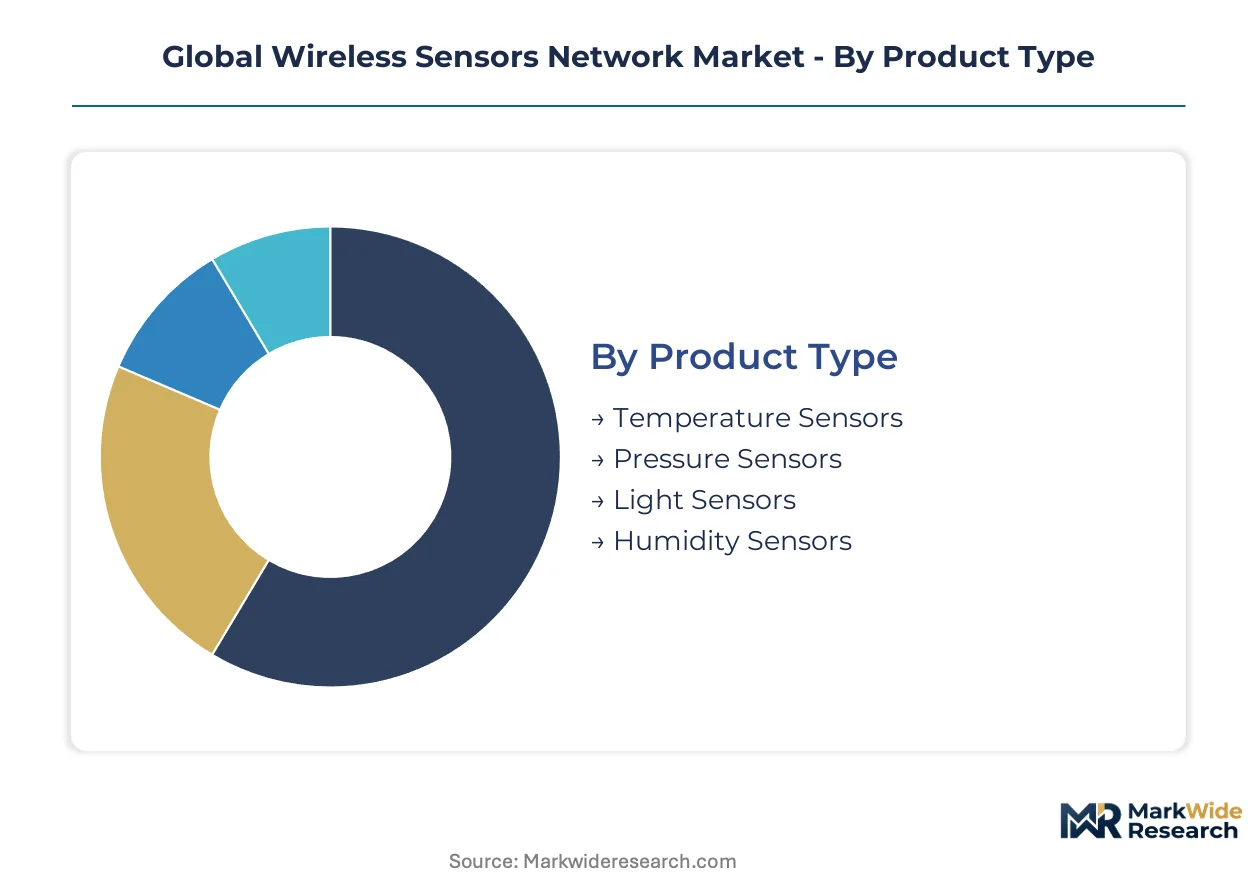
Segmentation in wireless sensors networks reveals how integration depth, power budgets, and protocol choices fragment procurement criteria across standalone environmental loggers versus embedded industrial control systems. Buyers separate cost-optimized nodes from latency-critical automation hardware, creating divergent supplier strategies.
Product Type:
Temperature and pressure sensors anchor embedded industrial systems where millisecond response times justify premium silicon, while humidity and light variants dominate standalone environmental deployments with relaxed latency tolerances.
- Temperature Sensors:Thermocouple and RTD-based nodes with ±0.1°C accuracy specifications. Demand concentrates in Germany's automotive manufacturing corridor where cold-chain validation and paint-cure monitoring require hardened thermal probes with IEC 60529 IP67 ratings.
- Pressure Sensors:MEMS capacitive and piezoresistive transducers measuring 0-100 bar ranges. Brazil's precision agriculture sector in Mato Grosso deploys soil pressure nodes for irrigation system optimization, with deployments accelerating under water-stress regulations.
- Light Sensors:Photodiode and ambient light sensing modules for daylight harvesting and crop growth monitoring. Greenhouse operators in the Netherlands integrate these with automated shade systems.
- Humidity Sensors:Capacitive polymer and resistive humidity detection elements. Museum conservation and pharmaceutical storage in Switzerland utilize calibrated units with drift compensation.
Volume placements concentrate in Temperature Sensors; the faster expansion belongs to Pressure Sensors.
Application:
Industrial automation and healthcare monitoring demand sub-100 millisecond latency with encrypted protocol stacks, while environmental monitoring and smart agriculture tolerate multi-second transmission intervals in exchange for decade-long battery autonomy.
- Industrial Automation:Condition monitoring for rotating equipment and process control loops requiring deterministic latency. Germany's Ruhr industrial basin retrofits wired systems with wireless nodes to eliminate conduit installation costs exceeding hardware economics.
- Smart Agriculture:Precision irrigation, livestock tracking, and soil analytics across water-stressed regions. Australia's Queensland cattle operations deploy GPS-enabled ear tags with LoRa backhaul, representing underpenetrated demand for multi-year battery nodes.
- Environmental Monitoring:Air quality, water quality, and meteorological sensing networks. Urban deployments in Singapore integrate particulate matter sensors with municipal data platforms.
- Healthcare Monitoring:Patient vital signs and elderly fall detection with regulatory-grade reliability. The EU AI Act's risk classification mandates conformity assessments extending deployment timelines for automated diagnostic feeds.
Industrial Automation captures the dominant revenue share; Smart Agriculture climbs the fastest as irrigation cost savings justify premium node pricing.
Technology:
Protocol selection determines whether nodes integrate as edge-AI endpoints with local inference or as dumb telemetry relays, with power budgets and range requirements driving architecture decisions.
- LoRa:Chirp spread spectrum modulation achieving 15-kilometer range at sub-50 mW transmit power. Brazil's Cerrado biome soil moisture networks leverage this for irrigation optimization without cellular subscription costs.
- Zigbee:Mesh networking with 2.4 GHz channel agility and 250 kbps throughput. Smart city streetlight controllers in Barcelona utilize Zigbee 3.0 for municipal infrastructure retrofits.
- Wi-Fi:High-throughput 802.11 variants for video-enabled surveillance and high-density sensor backhaul. Manufacturing floors in Michigan deploy Wi-Fi 6 for AGV coordination and real-time quality vision systems.
- Bluetooth:Low-energy 5.x implementations for short-range wearable and proximity applications. Hospital patient tags in Copenhagen use Bluetooth AoA for room-level location accuracy.
LoRa dominates unit shipments in agricultural and environmental segments; Zigbee maintains share in building automation where mesh resilience matters.
End User:
Manufacturing and smart cities procure through systems integrators with multi-year service contracts, while healthcare and transportation buyers separate hardware procurement from installation and calibration services.
- Manufacturing:Predictive maintenance and digital twin feedstock for asset-intensive production. Baden-Württemberg's automotive supplier ecosystem sources nodes through distributor stock programs rather than direct vendor relationships.
- Smart Cities:Integrated traffic, waste, and environmental sensing with municipal data platforms. Barcelona and Amsterdam deploy unified sensor backbones for multi-department analytics sharing.
- Healthcare:Clinical-grade patient monitoring with FDA and EMA regulatory pathways. Remote cardiac monitoring in the United States faces HIPAA encryption mandates and FDA 510(k) clearance requirements.
- Transportation:Fleet telematics, cargo condition monitoring, and infrastructure health sensing. Australian long-haul trucking operators adopt refrigerated container nodes with satellite failover.
Manufacturing absorbs the highest node volumes; Smart Cities expand most quickly as EU Green Deal digitalization mandates compress municipal procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's automotive supplier ecosystem drives Germany's industrial sensor procurement, where factory retrofit programs prioritize wireless condition monitoring over wired infrastructure replacement.
United States
FCC Part 15 rules governing unlicensed ISM bands below 1 GHz enable rapid field deployment without spectrum licensing delays. Michigan manufacturing floors deploy Wi-Fi 6 for AGV coordination and real-time quality vision systems. The EPA's emissions monitoring mandates accelerate environmental sensor networks in Houston's petrochemical corridor.
Germany
The Ruhr industrial basin retrofits wired condition monitoring systems with wireless nodes to eliminate conduit installation costs exceeding hardware economics. EU Green Deal digitalization mandates compress procurement timelines for energy-efficient networked devices. Stuttgart's automotive tier-one suppliers now source nodes through distributor stock programs rather than direct vendor relationships.
Brazil
Water-stress regulations accelerate precision agriculture deployments across Mato Grosso's soybean belt. ANVISA's medical device frameworks govern healthcare sensor imports while agriculture falls under separate ministry jurisdiction. Soil moisture tracking nodes in the Cerrado biome justify premium pricing through irrigation cost savings validated by local agronomy institutes.
Australia
Queensland cattle ranching operations represent underpenetrated demand for GPS-enabled ear-tag nodes with multi-year battery life. The TGA's regulatory pathways for connected medical devices create compliance templates that agricultural sensor vendors adapt. Sydney's smart city backbone integrates environmental sensing with municipal data platforms for multi-department analytics sharing.
China
MIIT's radio equipment type-approval requirements shape hardware roadmaps for export-oriented manufacturers. The Yangtze River Delta concentrates MEMS fabrication capacity serving both domestic industrial automation and export markets. Shenzhen's electronics ecosystem produces cost-optimized environmental logging nodes competing on silicon-level power optimization.
Global Wireless Sensors Network Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology stacks. MEMS foundry operators anchor supply security for high-reliability nodes while fabless semiconductor houses optimize radio-plus-microcontroller integration. The vendor base separates into three archetypes: integrated device manufacturers with captive fabrication, fabless specialists licensing process technology, and industrial conglomerates with backward integration into sensor packaging. Competitive moves concentrate on strategic partnerships for protocol certification and geographic expansion through distributor channel consolidation.
Within the integrated device manufacturer tier, Texas Instruments and NXP Semiconductors exemplify the radio-plus-microcontroller convergence strategy that sustains design-win rates in process automation. STMicroelectronics occupies a position emphasizing silicon-level power optimization for battery-constrained nodes. Honeywell International anchors the industrial conglomerate archetype through in-house production of MEMS transducers, representing backward integration into sensor fabrication that competing fabless houses cannot replicate without foundry partnerships.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Texas Instruments |
| STMicroelectronics |
| Honeywell International |
| Siemens AG |
| ABB Ltd |
| Cisco Systems |
| Emerson Electric |
| Analog Devices |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's digitalization mandates gate qualified supply and premium-tier pricing access by requiring sub-100 mW power budgets and interoperability certification before market entry, compressing margins for non-compliant vendors while elevating certified nodes in Germany's industrial corridor.
Pricing Analysis
Irrigation cost savings in water-stressed regions anchor value-based pricing for soil moisture nodes, with Brazil's Cerrado biome deployments justifying premium hardware through yield optimization returns. Three-tier pricing structure across premium, standard, and economy levels separates hardened industrial nodes with sub-millisecond latency from cost-optimized environmental loggers. Cost compression in the commodity tier intensifies because Shenzhen's electronics ecosystem floods channels with power-optimized silicon. Smart agriculture buyers exhibit highest price sensitivity, while pharmaceutical cold-chain operators accept premium positioning for regulatory-grade reliability.
Supply Chain Analysis
RF engineering talent scarcity in semiconductor design hubs constrains vendor scaling across Taiwan, South Korea, and the Yangtze River Delta. MEMS fabrication draws from specialized foundry capacity in East Asia, with sensor packaging resting on ceramic substrate and epoxy mold compound inputs. Single-source vulnerability for high-reliability nodes persists because hardened MEMS production concentrates among limited suppliers. Distribution runs through industrial distributors and systems integrators serving factory retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification schema creates a cost-of-compliance barrier that extends go-to-market timelines by 8-14 months for healthcare monitoring networks, entrenching pre-certified incumbents against undercapitalized challengers.
For Market Incumbents: To counter fabless competitors from Shenzhen's cost-optimized ecosystem, Texas Instruments and Honeywell International should deepen backward integration into MEMS fabrication while pre-certifying hardware stacks against ETSI's forthcoming cybersecurity mandates before mandatory enforcement locks out laggards. For New Entrants and Emerging Players: Cloud-based calibration services offer a digital-channel route to bypass distributor-controlled procurement in Baden-Württemberg's automotive supplier ecosystem. Australia's Queensland cattle ranching operations represent the most penetrable geography for GPS-enabled ear-tag nodes with LoRa backhaul, with livestock tracking presenting lower certification burdens than healthcare or automotive verticals. For Investors and Strategic Acquirers: First-mover pre-certification against EU Cybersecurity Certification mandates is the leading indicator that a vendor will capture margin-accretion opportunities in European smart city deployments. Acquisition targets should display captive MEMS fabrication or exclusive foundry partnerships, with spectrum reallocation proceedings in major economies serving as the critical inflection signal warranting ongoing watch.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Honeywell International's in-house transducer production secures supply continuity for high-reliability nodes serving FDA-regulated healthcare monitoring. |
| Pre-Certification for EU Cybersecurity Mandates | Early alignment with Radio Equipment Directive requirements creates first-mover advantage before mandatory enforcement reshapes European procurement criteria. |
| Protocol Certification Partnerships | Strategic alliances with LoRa Alliance and Zigbee Alliance accelerate interoperability validation for multi-hop mesh deployments in German chemical processing plants. |
| Geographic Expansion through Distributor Consolidation | Channel control in Brazil's Mato Grosso soybean belt captures precision agriculture demand accelerated by water-stress regulations. |
| Edge-AI Sensor Fusion Development | Convergence of MEMS accelerometers with on-device inference engines enables predictive maintenance pricing premiums in rotating equipment monitoring. |
Research Methodology
Independent corroboration across semiconductor design executives, industrial automation procurement leads, MEMS foundry operations managers, and systems integrators underwrites the qualitative findings in this study. Primary interviews with plant engineers in Germany's Ruhr basin and agronomists in Brazil's Cerrado biome combined with secondary validation from FCC Part 15 filings, ETSI harmonized standards documentation, and SEC 10-K disclosures from Texas Instruments and STMicroelectronics. Bottom-up node shipment estimates triangulated against top-down market value reconstructions across the analysis window.
Comparable-period anchoring to historical industrial automation retrofit cycles and smart agriculture adoption curves shaped the projection horizon. Segmentation dimensions modeled include sensor type, application latency requirements, protocol selection, and end-user procurement structure. CAGRs derived from unit economics analysis of battery-constrained versus mains-powered node categories, with LoRa propagation standards and EU Green Deal compliance timelines serving as industry-specific forecast inputs.
The model holds under stable spectrum allocation and certification pathway continuity; deviation in FCC reallocation proceedings or ETSI cybersecurity mandate acceleration would shift hardware roadmap priorities. Forecasts reflect assumptions regarding MEMS foundry capacity expansion and RF engineering talent pipeline development. A small set of named triggers—spectrum reallocation, EU AI Act enforcement timing, and RoHS substance compliance revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Global Rotation Laser Market
Sensors and Controls
Global Temperature Sensors Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Rangefinder Market