
 Two Wheeler Insurance Market | 2026-2036
Two Wheeler Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheeler Insurance Market Insights
Telematics is broadening risk-assessment precision across the two wheeler insurance landscape. Allstate Insurance Company leverages connected-device data to refine premium calculations for high-mileage riders. Bajaj Allianz General Insurance anchors its market position through extensive agent networks across tier-two and tier-three Indian cities. Progressive Casualty Insurance Company competes on usage-based models that reward low-risk behavior with dynamic pricing adjustments.
Two wheeler insurance constitutes a contractual risk-transfer instrument where insurers indemnify policyholders against financial losses arising from theft, collision, or third-party bodily injury involving motorcycles, scooters, or mopeds. Premium calculations integrate vehicle engine displacement, rider age and experience, geographic theft incidence, and claims history to determine actuarial exposure. Comprehensive policies dominate premium pools as owners seek protection beyond statutory minimums against own-damage and natural calamity risks. Online portals represent the fastest-expanding distribution channel, displacing traditional agent-dependent purchasing as digital-native riders prefer instant quote comparison and policy issuance.
The Insurance Regulatory and Development Authority of India mandates minimum third-party coverage and governs tariff structures for motor policies nationwide. State-level departments of insurance across the United States enforce solvency standards and market-conduct rules that shape product availability and pricing freedom. Stakeholders must monitor how embedded telematics partnerships and open-architecture data standards will redefine underwriting profitability and customer retention mechanics.
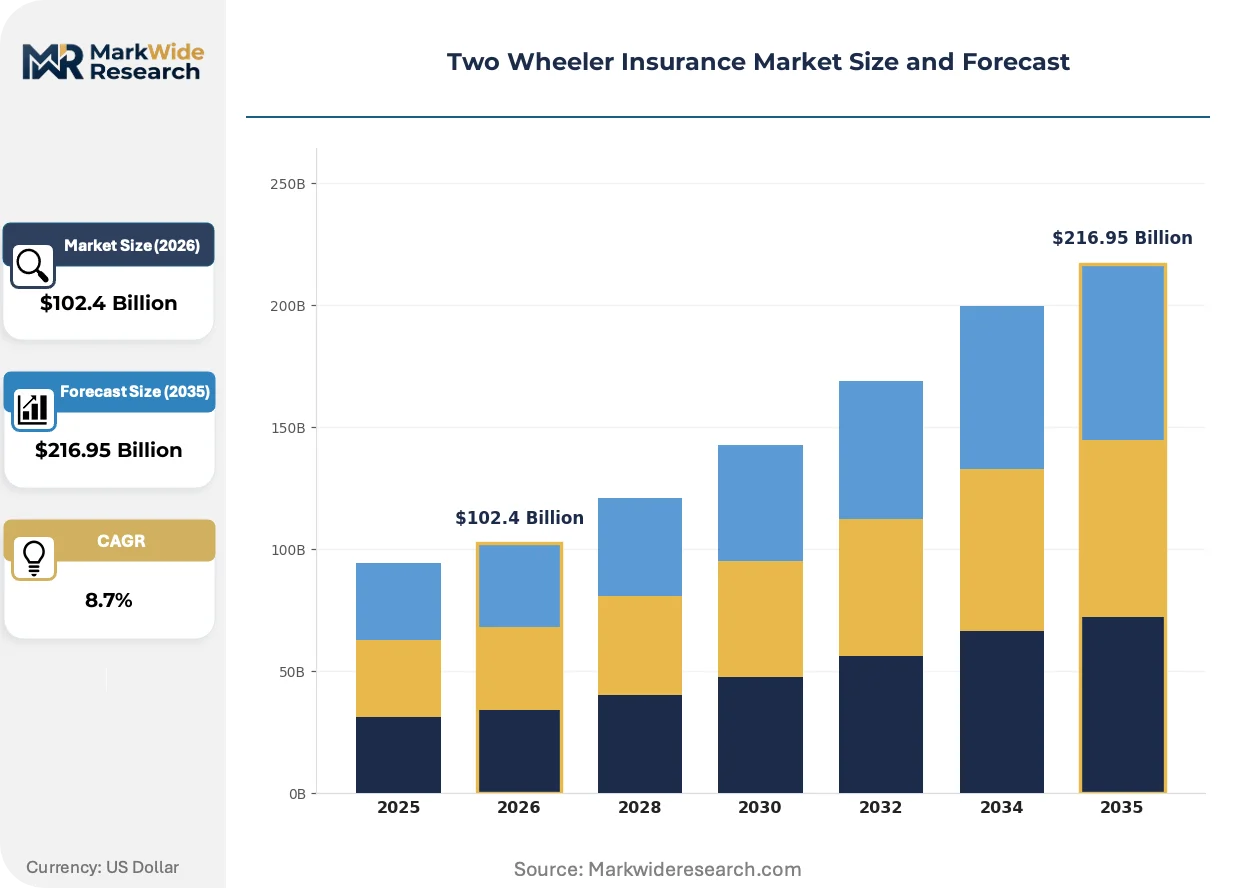
Market Dynamics
Telematics penetration is restructuring risk-assessment economics across motorcycle and scooter coverage, compressing traditional actuarial cycles and enabling real-time premium modulation based on actual riding behavior rather than static demographic proxies.
Growth Catalysts
- Gig-economy fleet expansion:Food-delivery and courier platforms in Indonesia, Vietnam, and Thailand are scaling commercial two-wheeler fleets, generating concentrated policy demand for commercial motor coverage with fleet-rated pricing structures.
- Motor Vehicles Act mandates:India's statutory third-party liability requirements under this federal legislation create non-discretionary purchase obligations, sustaining baseline policy volumes regardless of economic cycles.
- Connected-device data streams:Onboard diagnostics and GPS-enabled hardware are feeding granular mileage, braking, and acceleration telemetry into underwriting engines, sharpening loss-ratio predictability for high-exposure rider segments.
Market Restraints
- Semiconductor supply volatility:Telematics hardware production depends on microcontroller availability, with sourcing concentrated among Taiwanese and South Korean foundries exposed to geopolitical disruption.
- Legacy actuarial infrastructure:Established insurers in mature markets maintain decades-old policy-administration systems that resist API integration with real-time data feeds, delaying usage-based product rollout.
- Fraudulent claims prevalence:Staged accidents and inflated repair estimates in cash-based repair economies elevate loss ratios, compressing margins for comprehensive coverage products.
Strategic Opportunities
- Tier-two Indian city penetration:Agent networks in cities like Indore, Lucknow, and Coimbatore remain underserved by direct-to-consumer digital platforms, creating whitespace for hybrid distribution models.
- Climate-event parametric riders:Flood and cyclone exposure in Bangladesh and Philippines coastal zones enables index-triggered claim settlement products that bypass traditional loss-adjustment overhead.
- Embedded finance partnerships:OEM point-of-sale integrations with motorcycle manufacturers in Thailand and Vietnam can capture first-policy issuance at vehicle registration, locking in multi-year customer relationships.
Industry Challenges
- Telematics data-science talent scarcity:Underwriting teams lack sufficient actuaries trained in machine-learning model governance and connected-device signal interpretation.
- Cross-border regulatory fragmentation:ASEAN member states maintain divergent capital-reserve requirements and consumer-protection standards, complicating regional product harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheeler Insurance Market |
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $216.95 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Third Party, Comprehensive, Personal Accident, Liability Only Coverage Duration: 6 Months, 12 Months, Multi-Year, Short-Term Customer Type: Individual Owners, Corporate Fleets, Rental Services, Dealers Distribution Channel: Banks, Insurance Brokers, Online Portals, Direct Sales, Agents |
| Companies Covered | Allstate Insurance Company, Dairyland, State Farm Mutual Automobile Insurance, Liberty General Insurance Ltd., AXA, GEICO, Bajaj Allianz General Insurance, ACKO General Insurance Limited, Progressive Casualty Insurance Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheeler Insurance Market Trends and Innovations
Digital-native distribution channels are compressing policy-issuance cycles from days to minutes, while connected-device ecosystems are enabling dynamic risk-transfer mechanisms that decouple premium obligations from annual fixed schedules.
Artificial-intelligence-powered claims adjudication is absorbing document-verification and damage-assessment workflows previously handled by field adjusters. Mid-sized insurers in India and Southeast Asia are deploying computer-vision models trained on historical repair estimates to accelerate settlement timelines. This compression is reducing operational expense ratios and enabling same-day claim resolution for low-severity incidents.
India's Insurance Regulatory and Development Authority is tightening solvency-margin requirements and mandating standardized policy-wording disclosures for motor products. This regulatory pressure is forcing smaller regional underwriters to consolidate or exit, concentrating market share among carriers with sufficient capital buffers. Tier-one insurers are responding by diversifying into affiliated health and personal-accident riders to improve combined ratios.
Younger riders are bypassing traditional agent intermediaries entirely, completing purchase journeys through aggregator platforms that compare premiums across multiple underwriters instantaneously. This channel migration is most pronounced in Indian metropolitan markets and Indonesian urban centers, where smartphone penetration enables seamless digital identity verification and payment processing. Incumbent carriers are deploying proprietary apps with gamified safe-riding incentives to retain policyholders acquired through third-party channels.
Two Wheeler Insurance Market Segmentation
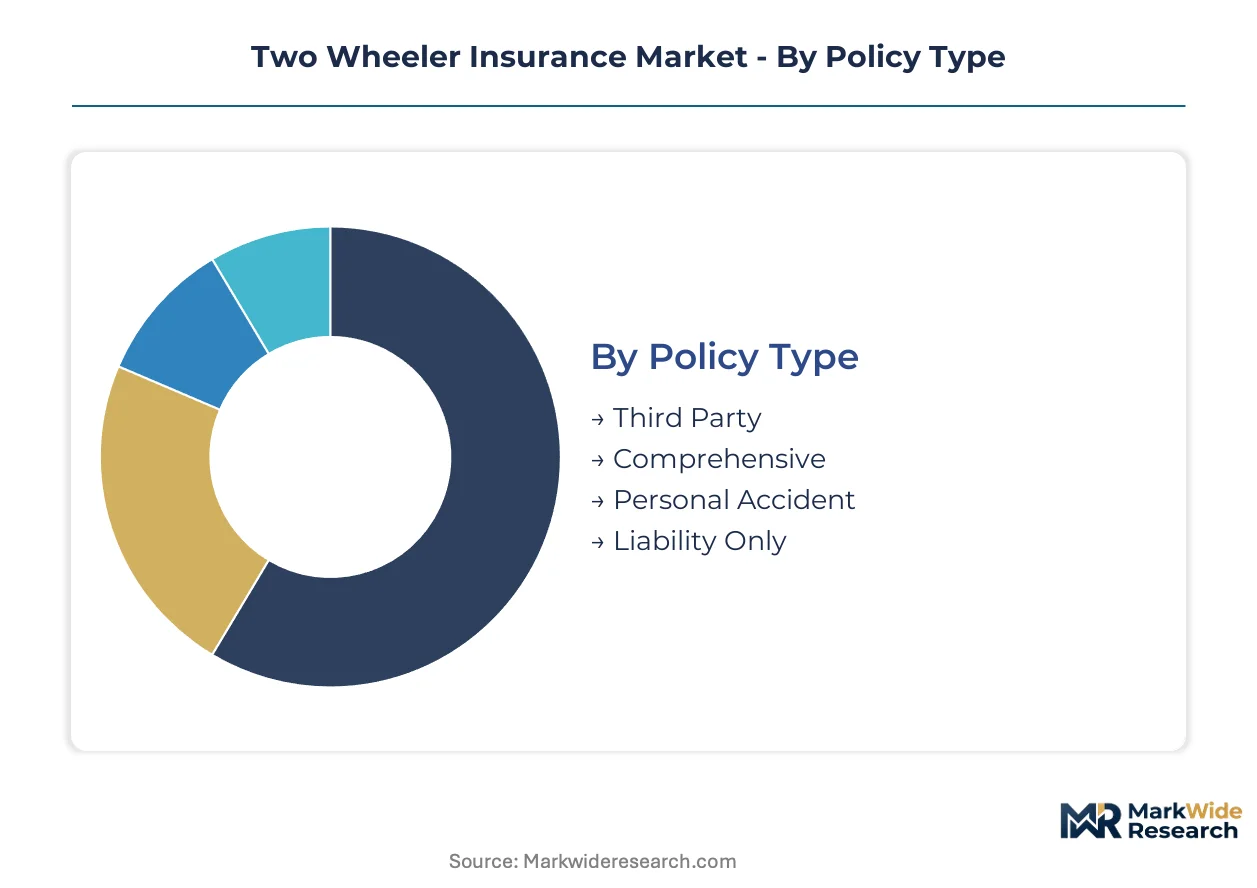
Risk-transfer preferences and purchase urgency vary sharply across rider profiles in two wheeler insurance. Policy construction, duration flexibility, and channel accessibility determine conversion rates and lifetime value for carriers competing across fragmented Asian markets.
Policy Type:
Premium outlays and legal exposure drive the initial coverage selection for motorcycle and scooter owners.
- Third Party:Statutory minimum coverage indemnifying bodily injury and property damage to external parties. India's Motor Vehicles Act mandates this baseline protection, sustaining volume across price-sensitive owner segments in tier-two and tier-three cities where comprehensive premiums strain household budgets.
- Comprehensive:Bundled protection spanning own-damage, theft, natural calamity, and third-party liability under single policy contracts. Demand concentrates among premium motorcycle owners in Thailand and Vietnam, where financing arrangements require full coverage and asset protection motives override cost minimization.
- Personal Accident:Rider-specific coverage for death or disability from road incidents, often purchased as mandatory add-on to statutory policies. Regulatory mandates in Indonesia and Philippines sustain attachment rates.
- Liability Only:Stripped-down protection covering third-party legal obligations without own-damage components. Fleet operators in Bangladesh and Sri Lanka deploy this structure to minimize per-unit coverage costs across high-unit-count commercial deployments.
Volume sits with Third Party; growth tilts toward Comprehensive.
Coverage Duration:
Cash-flow timing and regulatory compliance windows shape duration preferences across customer segments.
- 12 Months:Standard annual renewal cycles aligning with fiscal planning and traditional agent commission structures. Dominates individual owner purchases across Indian states where IRDAI-mandated third-party tariffs reset on annual basis.
- Multi-Year:Extended protection locking premium rates against tariff increases and eliminating renewal friction. Gaining traction among digitally-savvy owners in Indonesian metropolitan markets seeking price certainty and administrative convenience.
- 6 Months:Half-yearly contracts serving seasonal riders and temporary vehicle deployments. Concentrated in northern Indian states with pronounced monsoon riding patterns.
- Short-Term:Daily to monthly coverage for rental scooters and tourist motorcycle hires. Expanding in Thai and Vietnamese tourist corridors where international visitors seek temporary legal compliance.
Revenue concentrates in 12 Months; Multi-Year is climbing the fastest as digital platforms reduce friction for long-term commitments.
Customer Type:
Scale economies and claims frequency profiles differentiate profitability across buyer categories.
- Corporate Fleets:Aggregated coverage for delivery platforms, courier services, and corporate vehicle pools. Food-delivery operators in Indonesia, Vietnam, and Thailand negotiate fleet-rated pricing with loss-ratio guarantees, concentrating premium volume among tier-one carriers with actuarial capacity for large-account underwriting.
- Individual Owners:Single-policy purchasers of motorcycles and scooters for personal transportation. Fragmented across millions of small-ticket accounts in India, where agent networks retain influence in non-metropolitan districts.
- Rental Services:Commercial operators leasing two-wheelers on short-term basis. Emerging segment in Vietnamese urban centers with app-based scooter sharing.
- Dealers:Point-of-sale insurance attachments at vehicle registration. Thai and Vietnamese OEM partnerships embed first-policy issuance, capturing customers at acquisition moment.
Individual Owners dominate policy count; Corporate Fleets dominate premium density.
Distribution Channel:
Trust formation and purchase urgency determine channel selection across demographic cohorts.
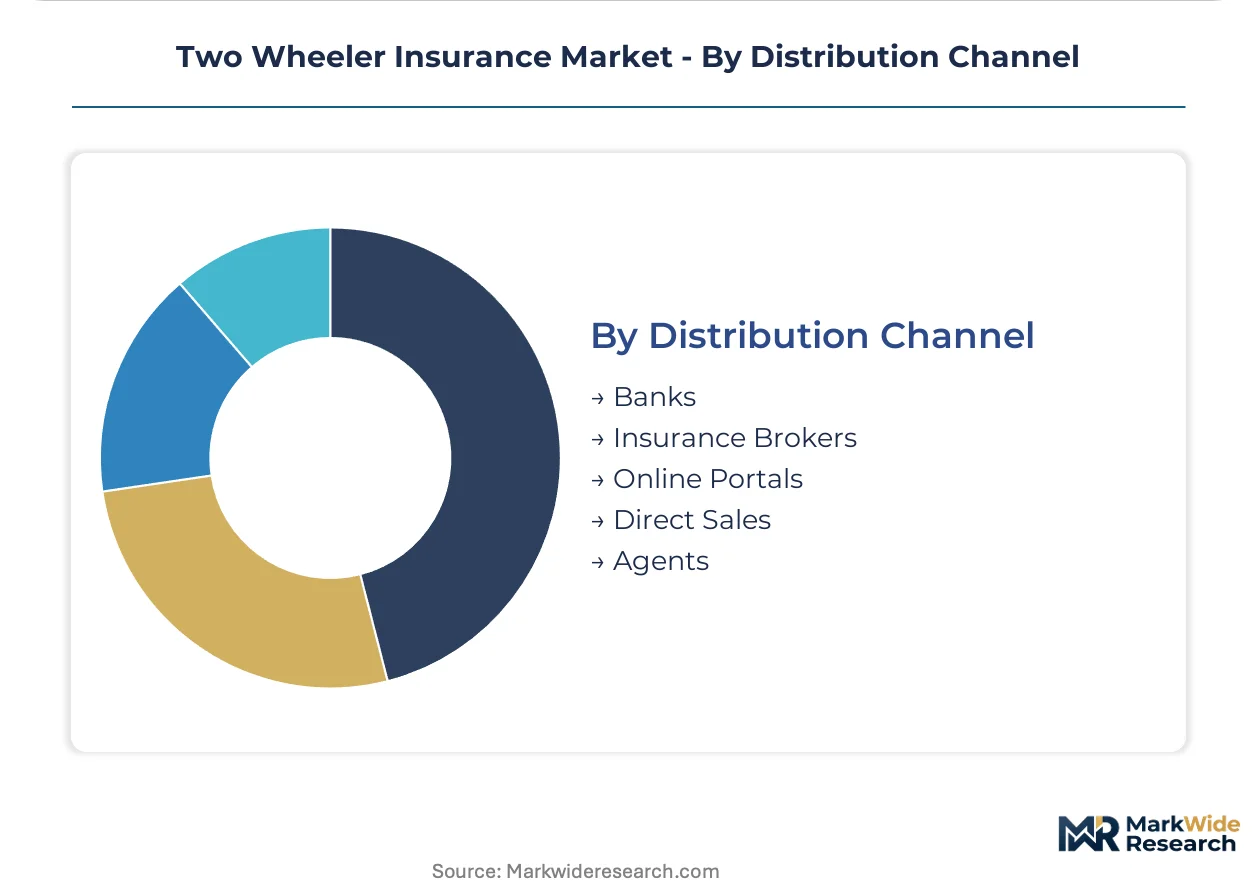
- Online Portals:Aggregator platforms and direct insurer websites enabling instant quote comparison and policy issuance. Smartphone penetration in Indian and Indonesian metropolitan markets accelerates migration from agent-dependent purchasing.
- Agents:Commission-compensated intermediaries providing face-to-face consultation and claims assistance. Retains dominance in tier-two and tier-three Indian cities where digital literacy gaps and documentation complexity sustain intermediary value.
- Insurance Brokers:Independent advisors serving commercial fleet accounts with complex coverage structuring. Concentrated in large-fleet negotiations across Bangkok and Jakarta corporate headquarters.
- Banks:Bancassurance partnerships attaching coverage to vehicle financing arrangements. Thai and Vietnamese auto lenders bundle policies with motorcycle loans, securing lien protection.
- Direct Sales:Insurer-proprietary channels bypassing intermediaries. Limited penetration outside digital-native customer segments.
Agents still hold volume; Online Portals are gaining share fastest among under-35 rider demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates two wheeler insurance demand through statutory mandates and fleet expansion, while Southeast Asian markets amplify growth through motorcycle ownership surges and gig-economy commercialization.
India
The Motor Vehicles Act sustains mandatory third-party coverage demand across tier-two and tier-three cities. The Insurance Regulatory and Development Authority governs tariff structures and solvency requirements nationwide. Indore, Lucknow, and Coimbatore clusters attract hybrid distribution models combining agent networks with digital platforms.
Indonesia
Food-delivery platforms scale commercial two-wheeler fleets, generating concentrated fleet-rated policy demand. The country's financial services authority oversees motor insurance capital reserve standards. Jakarta metropolitan corridors concentrate gig-economy rider density and telematics-enabled underwriting experimentation.
Vietnam
Motorcycle financing arrangements require comprehensive coverage, locking in premium policy attachment rates. The Ministry of Finance regulates motor vehicle insurance licensing and consumer protection frameworks. Ho Chi Minh City and Hanoi urban centers anchor OEM point-of-sale embedded finance partnerships.
Thailand
Tourism corridors drive short-term rental scooter coverage expansion for international visitors. The country's insurance commission enforces motor policy disclosure standards and claims settlement timelines. Bangkok commercial districts concentrate corporate fleet negotiations and broker-mediated large-account underwriting.
United States
Usage-based models reward low-risk riding behavior with dynamic premium adjustments, attracting digitally-native rider segments. State-level departments of insurance enforce solvency standards and market-conduct rules shaping product availability. Progressive carriers in metropolitan markets deploy connected-device ecosystems for real-time risk assessment.
Two Wheeler Insurance Market Competitive Landscape
Telematics partnerships dominate the current landscape as carriers restructure underwriting economics around real-time behavioral data. The market exhibits tiered consolidation with national incumbents, digital-native challengers, and regional specialists competing across distinct customer segments. Three strategic archetypes have emerged: legacy carriers with agent network scale, technology-first direct insurers, and fleet-specialist underwriters. Competitive intensity centers on embedded finance partnerships with OEMs and API-driven distribution platform integrations.
Within the legacy carrier tier, Allstate Insurance Company and State Farm Mutual Automobile Insurance exemplify established players with extensive intermediary networks. Progressive Casualty Insurance Company anchors the technology-forward segment through usage-based product architectures. Bajaj Allianz General Insurance represents the regional specialist archetype with concentrated presence in Indian tier-two and tier-three markets.
| Leading Market Players |
|---|
| Allstate Insurance Company |
| Dairyland |
| State Farm Mutual Automobile Insurance |
| Liberty General Insurance Ltd. |
| AXA |
| GEICO |
| Bajaj Allianz General Insurance |
| ACKO General Insurance Limited |
| Progressive Casualty Insurance Company |
| Others |
Pricing and Supply Chain Analysis
Family-owned agency networks across Indian tier-two cities anchor premium collection while compressing margins through commission stacking, a structure that simultaneously sustains rural coverage penetration and limits pricing flexibility for direct-to-consumer digital entrants. This ownership pattern ties supply chain remuneration to persistent intermediary layers even as telematics-enabled underwriting promises disintermediation.
Pricing Analysis
Volume concentrates in statutory third-party tiers where India's Motor Vehicles Act mandates minimum coverage, while margins accrue to comprehensive products with own-damage riders. Price differentiation rests on engine displacement brackets and geographic theft incidence rather than brand premium. Pricing pressure intensifies in commercial fleet segments as gig-economy platforms negotiate loss-ratio guarantees with tier-one carriers. Individual owners in Indonesian and Vietnamese metropolitan markets show highest price sensitivity, deferring to mandatory minimums, while financed motorcycle buyers in Thailand accept comprehensive premiums as loan conditionality.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet demand through embedded finance partnerships at Thai and Vietnamese motorcycle dealerships. Telematics hardware sourcing concentrates in Taiwan, South Korea, and mainland China foundries. Semiconductor microcontrollers and GPS modules constitute critical component dependencies. Single-source vulnerability in Taiwanese foundry capacity exposes underwriting infrastructure rollout timelines. Distribution runs through hybrid agent-digital networks in India, with aggregator platforms capturing metropolitan policy issuance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where India's Motor Vehicles Act and IRDAI solvency mandates erect capital barriers that protect established carriers with sufficient reserve buffers against undercapitalized challengers.
For Market Incumbents: Deepen telematics data integration to compress loss-ratio volatility before digital-native entrants achieve comparable actuarial precision. Consolidate agency networks in Indore, Lucknow, and Coimbatore clusters to preempt hybrid distribution challengers. Lock in multi-year fleet contracts with Indonesian food-delivery platforms to anchor premium density against price competition. For New Entrants and Emerging Players: The gap between premium comprehensive tiers and economy third-party minimums offers white-space for mid-market usage-based products targeting under-35 riders in Jakarta and Ho Chi Minh City urban corridors. Target short-term rental coverage in Thai tourist corridors where incumbent infrastructure remains thin. Pursue API-first distribution partnerships with motorcycle OEMs to capture first-policy issuance at registration. For Investors and Strategic Acquirers: IRDAI-mandated solvency margin tightening is the leading indicator that regional Indian underwriters will consolidate or exit, concentrating market share among capital-buffered survivors. Five-to-ten year viability favors carriers with embedded finance OEM relationships and proprietary telematics data lakes. Monitor ASEAN regulatory harmonization progress as signal for cross-border product scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Partnership Expansion | Progressive Casualty Insurance leverages connected-device data to refine dynamic premium modulation for high-mileage rider segments. |
| Embedded Finance Integration | Thai and Vietnamese OEM point-of-sale partnerships capture first-policy issuance at vehicle registration, locking multi-year relationships. |
| Hybrid Distribution Buildout | Bajaj Allianz General Insurance combines agent networks with digital platforms across underserved tier-two Indian city clusters. |
| Parametric Climate Rider Development | Flood and cyclone index-triggered products in Bangladesh and Philippines bypass traditional loss-adjustment overhead. |
| Fleet-Rated Commercial Underwriting | Indonesian food-delivery platforms negotiate concentrated policy demand with loss-ratio guarantees from tier-one carriers. |
Research Methodology
Independent corroboration across Insurance Regulatory and Development Authority of India tariff filings, Indonesian Financial Services Authority capital reserve disclosures, and Vietnamese Ministry of Finance licensing records underwrites the qualitative findings. Primary interviews with motor insurance underwriting heads, telematics platform engineers, and fleet procurement managers at Southeast Asian delivery platforms combined with secondary validation from ASEAN insurance commission reports and customs vehicle registration data. Bottom-up policy volume estimates triangulated against top-down premium pool assessments.
Rate-of-change decomposition across the analysis window segments growth by policy type, coverage duration, customer category, and distribution channel. Modeled dimensions include statutory versus voluntary coverage splits, annual versus multi-year contract preferences, individual owner versus corporate fleet profitability profiles, and agent versus digital channel migration patterns. CAGRs derived from regression analysis of historical premium volumes against motorcycle ownership penetration, regulatory mandate expansion, and telematics adoption curves. Forecast inputs incorporate gig-economy fleet scaling trajectories and semiconductor supply availability for connected-device deployment.
Inputs from IRDAI solvency filings and Thai Insurance Commission claims settlement databases were available through the study window; gaps in real-time telematics loss-ratio performance introduce uncertainty bands around usage-based product profitability assumptions. Forecasts reflect documented base-case assumptions regarding regulatory mandate continuity and connected-device adoption velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
Japan Motor Insurance Market
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
Canada Motor Insurance Market