
 Private Passenger Auto Insurance Market | 2026-2036
Private Passenger Auto Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Private Passenger Auto Insurance Market Insights
Telematics mandates in several US states is recalibrating the cost-of-entry calculus for new underwriters, forcing capital deployment toward data infrastructure before policy issuance. State Farm Group leverages its captive agency network to sustain pricing discipline across fragmented state jurisdictions. Progressive Insurance Group anchors its growth in usage-based insurance algorithms that compete on granularity rather than scale. Berkshire Hathaway Group differentiates through GEICO's direct-to-consumer channel, controlling acquisition costs without intermediary commissions.
Private passenger auto insurance covers privately owned vehicles against collision damage, liability claims, theft, and bodily injury through indemnity contracts priced via actuarial risk pools. Policies incorporate deductibles, coverage limits, and exclusions structured around vehicle class, driver history, and territorial rating factors to transfer financial risk from individuals to pooled capital reserves. Liability coverage dominates premium volume due to compulsory legal mandates across most jurisdictions, while online platforms represent the fastest-growing distribution channel as digital-native consumers bypass traditional agent relationships. Personal injury protection exhibits structural margin pressure from medical cost inflation, whereas comprehensive coverage commands stable pricing power tied to vehicle replacement values.
The National Association of Insurance Commissioners coordinates state-level solvency standards, while the Federal Insurance Office monitors systemic risk across state-regulated entities. State departments of insurance enforce rate filing requirements that shape product availability and pricing transparency. The Consumer Financial Protection Bureau examines claims-handling fairness, influencing operational compliance investments. Stakeholders must monitor emerging autonomous vehicle liability frameworks and their potential to dissolve traditional fault-based underwriting models.
Market Dynamics
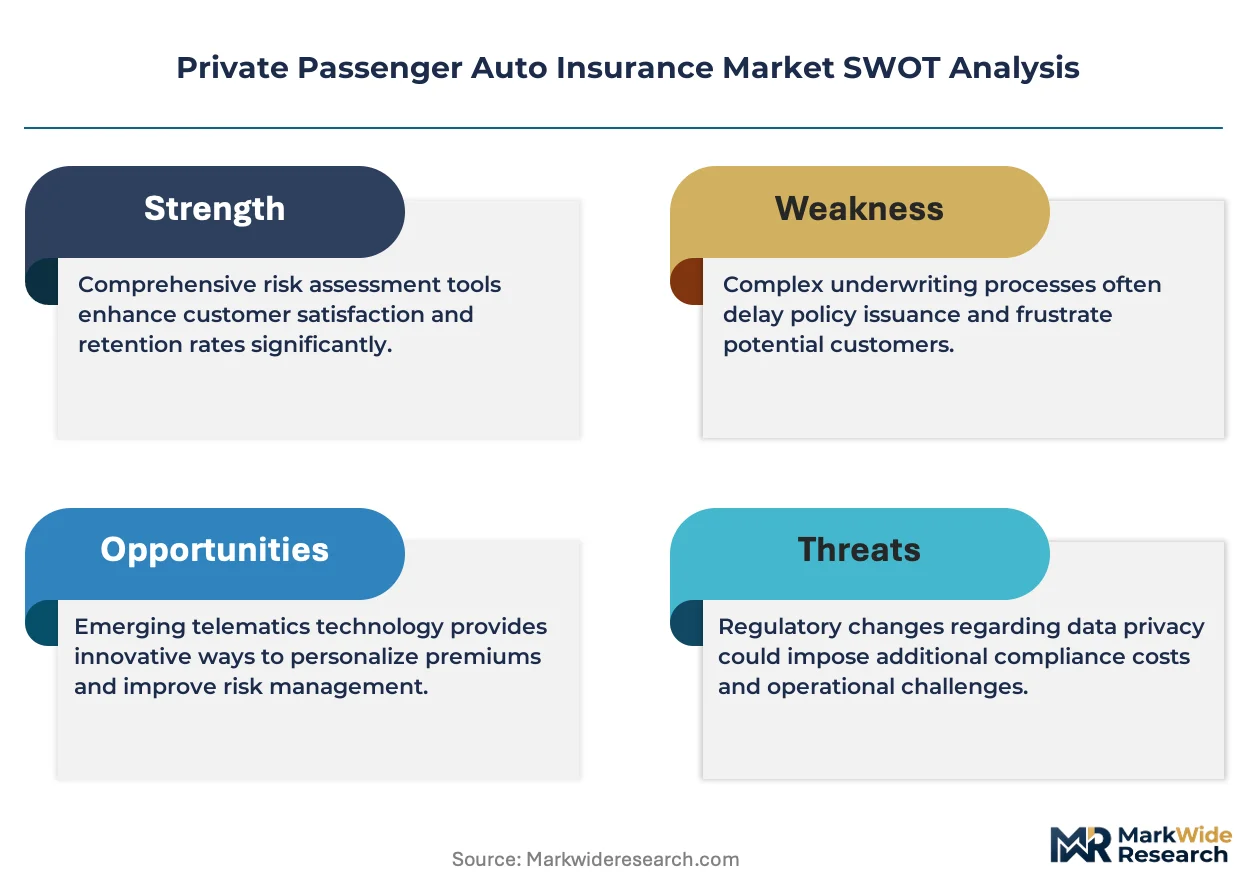
Telematics-based usage pricing is compressing traditional actuarial models by replacing annual premium pools with real-time risk calibration tied to actual driving behavior.
Growth Catalysts
- State-level telematics mandates:Several US jurisdictions now require insurers to offer usage-based options, expanding addressable pools beyond standard risk-rated contracts.
- Ride-hailing driver expansion:Gig economy platforms create demand for flexible, per-mile coverage that adapts to commercial and personal use switching.
- Embedded insurance APIs:Auto manufacturers integrate coverage at point-of-sale, capturing drivers before traditional agent channels.
Market Restraints
- Medical cost inflation:Personal injury protection faces structural margin erosion as healthcare provider billing outpaces premium rate filings.
- State regulatory fragmentation:Fifty separate rate approval processes force product customization that raises operational complexity and compliance overhead.
- Data infrastructure capex:Real-time telematics processing requires cloud and edge computing investments that smaller underwriters cannot amortize.
Strategic Opportunities
- Autonomous vehicle liability frameworks:Emerging fault determination standards for self-driving systems will create entirely new coverage categories.
- Digital-native distribution:Mobile-first platforms bypass captive agent networks, reducing customer acquisition costs for direct entrants.
- Climate-linked comprehensive pricing:Catastrophe modeling integration enables dynamic pricing tied to flood, hail, and wildfire exposure zones.
Industry Challenges
- Actuarial talent scarcity:Demand for data scientists with both statistical modeling and insurance domain expertise exceeds supply.
- Legacy system integration:Core policy administration platforms require expensive API layers to connect with modern telematics data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Passenger Auto Insurance Market |
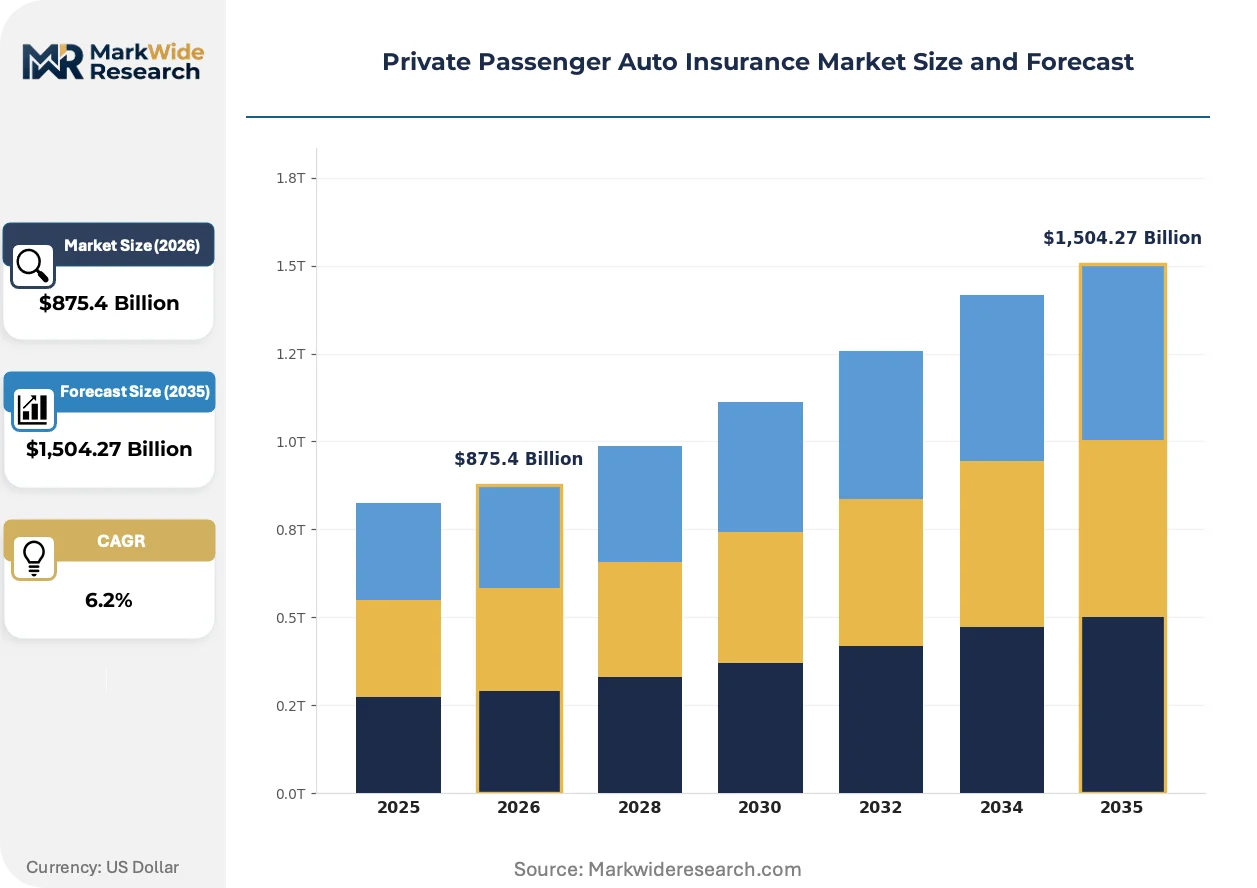
| Market Size in 2026 | $875.4 Billion |
| Market Size in 2035 | $1,504.27 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Liability, Collision, Comprehensive, Personal Injury Protection, Uninsured Motorist Coverage Level: Basic, Standard, Premium, Platinum, Gold Customer Type: New Drivers, Experienced Drivers, Senior Drivers, High-Risk Drivers, Fleet Operators Distribution Channel: Brokerage, Direct Sales, Online Platforms, Agents, Call Centers |
| Companies Covered | State Farm Group, Progressive Insurance Group, Berkshire Hathaway Group, Allstate Insurance Group, USAA Group, Farmers Insurance Group, Liberty Mutual Insurance Companies, Travelers Group, American Family Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Passenger Auto Insurance Market Trends and Innovations
Real-time data streams are replacing retrospective rating factors as the primary input for premium calculation and risk selection.
Artificial intelligence-driven claims processing is converging with computer vision damage assessment to compress settlement cycles from weeks to hours. Mid-sized regional carriers are adopting these tools fastest to offset scale disadvantages against national competitors. The technology is converging with mobile-first customer service platforms to eliminate adjuster dispatch for routine collision events.
The National Association of Insurance Commissioners has proposed standardized data formats for telematics sharing between insurers and state regulators. This framework would reduce compliance friction for multi-state operators while raising barriers for single-state specialists. Carriers operating across fragmented state jurisdictions face the steepest adaptation costs.
Digital-native consumers now expect instant quote comparison and policy binding without agent consultation. Direct-to-consumer platforms capture these buyers through mobile-optimized underwriting workflows that traditional agency networks cannot replicate. The shift is most pronounced among drivers under 35 in suburban and exurban zip codes.
Private Passenger Auto Insurance Market Segmentation
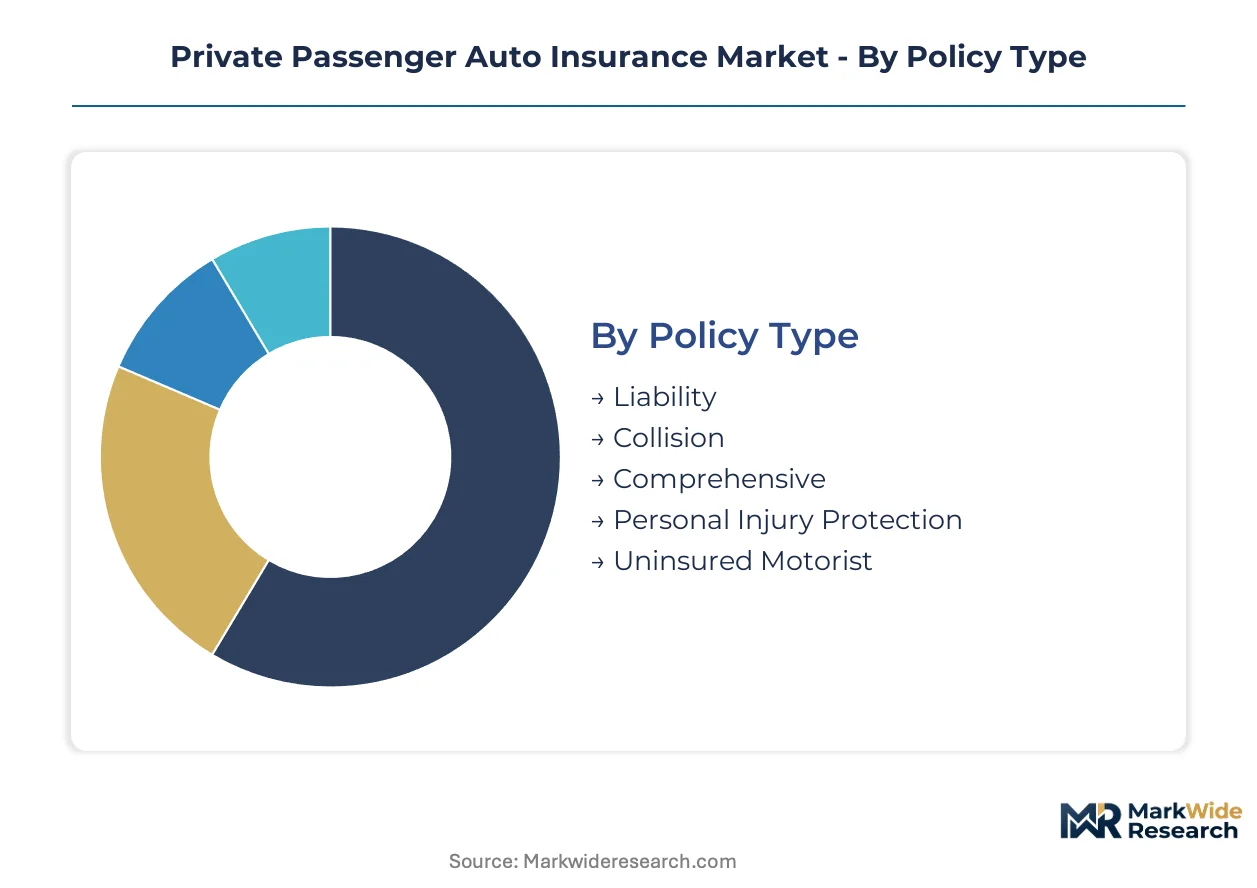
Segmentation in private passenger auto insurance determines pricing precision, capital allocation, and regulatory compliance burdens. Underwriters calibrate risk pools differently across policy types, coverage tiers, and distribution channels to match liability exposure with premium adequacy.
Policy Type:
Liability coverage carries mandatory state filing requirements through departments of insurance, while optional coverages face lighter regulatory touch. Collision and comprehensive policies require coordination with vehicle valuation databases and salvage yard networks.
- Liability:Bodily injury and property damage coverage satisfies compulsory insurance laws in all US jurisdictions. Demand concentrates among cost-conscious drivers in states with high minimum coverage thresholds, where premium pressure from state rate filings limits underwriting flexibility.
- Collision:Physical damage protection for policyholder vehicles regardless of fault. Fleet operators and financed-vehicle owners drive volume in suburban zip codes with higher accident frequency, where lenders require full coverage as loan conditions.
- Comprehensive:Non-collision perils including theft, vandalism, and weather damage. Climate-linked pricing models now integrate catastrophe exposure zones into territorial rating factors.
- Personal Injury Protection:No-fault medical coverage with structural margin pressure from healthcare provider billing inflation exceeding approved rate increases.
- Uninsured Motorist:Protection against at-fault drivers lacking coverage. State mandates vary widely, creating product availability gaps in jurisdictions with high uninsured vehicle rates.
Liability sits at the top of the volume ranking, with comprehensive climbing the fastest as vehicle replacement values rise and climate perils intensify.
Coverage Level:
Premium tiering reflects deductible gradients, claim service levels, and add-on feature bundles rather than core peril differences. Platinum and gold tiers require enhanced customer service infrastructure and faster claims cycle commitments.
- Basic:State-minimum liability limits with highest deductibles and stripped-down service. Price-sensitive segments in rural markets select this tier despite exposure to out-of-pocket costs exceeding asset protection.
- Standard:Moderate limits with balanced deductibles. The largest addressable pool, capturing middle-income households in suburban geographies seeking adequate protection without premium escalation.
- Premium:Elevated limits, lower deductibles, and priority claims handling. Affluent zip codes with newer vehicle fleets generate disproportionate share of premium volume.
- Platinum:Maximum limits, zero deductibles, and concierge service tiers. High-net-worth individuals in metropolitan markets value asset protection over premium minimization.
- Gold:Hybrid positioning between premium and platinum with specialized add-ons like rental reimbursement and roadside assistance bundling.
Standard coverage commands the largest premium pool, with platinum expanding most quickly among wealth-concentrated urban markets.
Customer Type:
Risk classification systems segment policyholders by driving experience, claim history, and vehicle usage patterns. Each cohort demands distinct pricing models and retention strategies.
- New Drivers:Inexperienced operators with elevated loss frequency. Telematics-based usage pricing allows carriers to segment this cohort more granularly than traditional age-based rating.
- Experienced Drivers:Clean-record middle-aged operators with lowest loss costs. Direct-to-consumer channels target this segment with price-comparison tools that bypass agent commissions.
- Senior Drivers:Age-65-plus operators with declining mileage but higher severity per mile. State Farm and regional carriers deploy specialized underwriting for this retention-focused segment.
- High-Risk Drivers:SR-22 filers and post-DUI operators requiring assigned-risk pool placement or non-standard carriers.
- Fleet Operators:Small commercial fleets with mixed personal-business usage. Gig economy platforms create demand for flexible per-mile coverage that switches between use types.
Experienced drivers generate the highest policy count, with fleet operators gaining share fastest as ride-hailing platforms expand driver recruitment.
Distribution Channel:
Channel selection determines acquisition cost structures, customer lifetime value, and regulatory compliance obligations. Captive agent networks require state licensing maintenance that direct channels bypass.
- Brokerage:Independent agents representing multiple carriers. Small-town and rural markets rely on broker relationships for complex coverage counseling.
- Direct Sales:Carrier-employed sales forces with exclusive product access. GEICO's direct-to-consumer model controls acquisition costs without intermediary commissions.
- Online Platforms:Digital quote comparison and instant binding. Drivers under 35 in suburban and exurban zip codes bypass traditional agent relationships through mobile-optimized workflows.
- Agents:Captive networks like State Farm's tied to single carrier. Sustains pricing discipline across fragmented state jurisdictions through localized market knowledge.
- Call Centers:Phone-based sales and service for non-digital customers. Retains relevance among senior demographics and complex multi-policy households.
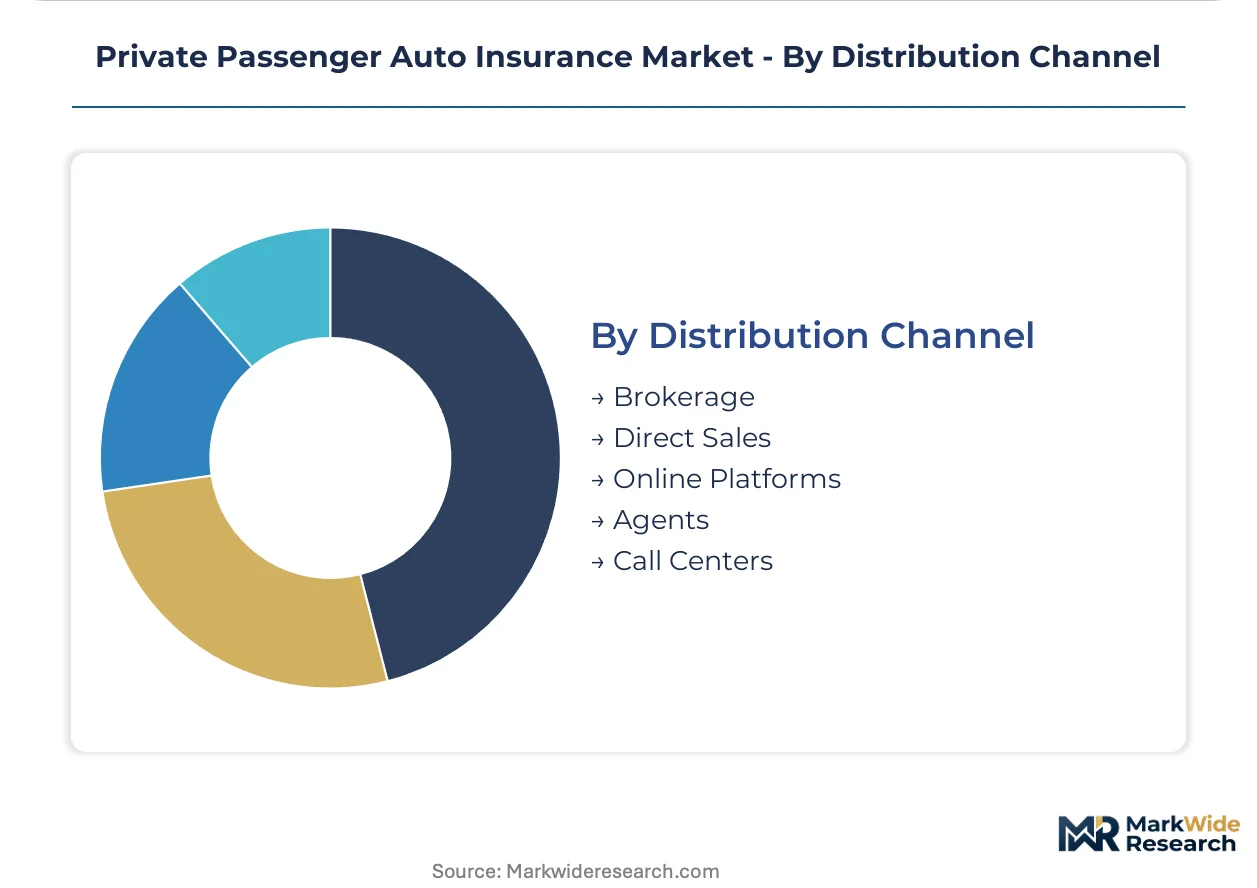
Agents still handle the highest policy volume, with online platforms climbing the fastest as digital-native consumers enter auto insurance markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Actuarial talent pools and data science clusters anchor geographic demand concentration. Underwriters locate pricing teams near metropolitan insurance hubs. State-level regulatory specialization shapes regional competitive positioning.
United States
Telematics mandates in California and New York expand usage-based insurance penetration. The National Association of Insurance Commissioners coordinates multi-state solvency standards. Hartford, Connecticut hosts legacy carrier headquarters clusters where pricing actuaries develop state-specific filing strategies.
Germany
Automotive manufacturer embedded insurance partnerships drive direct distribution growth. The Federal Financial Supervisory Authority enforces strict capital adequacy for motor vehicle liability. Munich and Frankfurt concentrate insurtech development labs refining real-time risk algorithms.
United Kingdom
Price comparison website dominance accelerates direct-to-consumer channel shift. The Prudential Regulation Authority supervises insurer solvency under Solvency II equivalence. London's Lloyd's syndicates experiment with autonomous vehicle liability coverage frameworks.
China
Electric vehicle fleet expansion creates demand for battery-specific coverage products. The China Banking and Insurance Regulatory Commission mandates telematics data sharing standards. Shanghai and Shenzhen host insurtech clusters developing usage-based pricing for ride-hailing platforms.
Japan
Aging driver demographics intensify demand for senior-focused underwriting products. The Financial Services Agency reviews autonomous vehicle liability classification rules. Tokyo concentrates non-life insurance headquarters where telematics partnerships with domestic automakers originate.
Private Passenger Auto Insurance Market Competitive Landscape
The competitive structure tilts toward captive agency networks with localized pricing discipline. National carriers deploy direct-to-consumer channels to bypass commission structures. Three archetypes dominate: scale-driven direct writers, agency-network incumbents, and regional specialists. Consolidation through mutual holding company reorganizations and telematics platform licensing agreements reshapes tier positioning.
Among US-based national carriers, State Farm Group, Progressive Insurance Group, and Berkshire Hathaway Group exemplify divergent channel strategies. State Farm represents the captive agency archetype with localized market knowledge. Progressive anchors the algorithmic pricing tier with usage-based insurance granularity. Berkshire Hathaway occupies the direct-to-consumer efficiency position through GEICO's commission-free acquisition model.
| Leading Market Players |
|---|
| State Farm Group |
| Progressive Insurance Group |
| Berkshire Hathaway Group |
| Allstate Insurance Group |
| USAA Group |
| Farmers Insurance Group |
| Liberty Mutual Insurance Companies |
| Travelers Group |
| American Family Insurance Group |
| Others |
Pricing and Supply Chain Analysis
Actuarial labor costs in Hartford, Connecticut and data infrastructure investments in cloud computing hubs cascade through premium tiers as carriers pass fixed technology deployment expenses to policyholders while telematics-enabled usage pricing fragments traditional annual contracts into granular per-mile segments.
Pricing Analysis
Bundled agency-commissioned products compete against unbundled direct-to-consumer offerings without intermediary fees. Three-tier pricing structure across premium, standard, and economy levels segments buyers by asset protection needs and service intensity. Price differentiation hinges on telematics data granularity and claims handling speed commitments. Pricing pressure stems from medical cost inflation in personal injury protection lines eroding statutory rate increase approvals. Price-sensitive segments cluster in state-minimum liability purchasers, while platinum-tier buyers exhibit minimal elasticity.
Supply Chain Analysis
State-level rate filing certifications and telematics data standard qualifications gate carrier market entry across fifty separate regulatory jurisdictions. Actuarial talent concentrates in Connecticut, Illinois, and California insurance hubs. Cloud infrastructure and vehicle valuation databases constitute critical upstream dependencies. Single-source vulnerability manifests in proprietary telematics platform licensing agreements that lock carriers into exclusive data partnerships. Distribution runs through captive agency networks, direct digital platforms, and embedded manufacturer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private passenger auto insurance functions as a stable compounder where compulsory liability mandates generate recurring premium inflows regardless of economic cycles.
For Market Incumbents: Extend telematics data advantages into adjacent mobility services before insurtech challengers capture usage-based pricing mindshare. Consolidate regional carriers in fragmented state markets to amortize compliance infrastructure across broader premium bases. Deepen captive agency relationships in suburban zip codes where digital-native competitors lack localized presence.
For New Entrants and Emerging Players: California's telematics data sharing mandate opens a window for algorithmic pricing specialists to enter without building proprietary sensor networks from zero. Target ride-hailing driver segments with per-mile coverage products that incumbent billing systems cannot flexibly administer. Pursue embedded insurance API partnerships with electric vehicle manufacturers at point-of-sale.
For Investors and Strategic Acquirers: Roll-up economics work for regional carriers with concentrated state footprints because telematics platform licensing costs create scale disadvantages for sub-billion-premium operators. Five-to-ten-year viability favors carriers with demonstrated rate filing approval velocity in restrictive jurisdictions. Monitor autonomous vehicle liability framework announcements as inflection indicators for coverage category expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Licensing | NAIC data format standardization reduces multi-state compliance friction for algorithmic pricing deployment. |
| Embedded Insurance API Integration | Automaker point-of-sale partnerships capture drivers before traditional agency channel engagement. |
| Captive Agency Network Expansion | Localized market knowledge sustains pricing discipline across fragmented state regulatory jurisdictions. |
| Usage-Based Algorithm Development | Real-time risk calibration displaces retrospective rating factors in premium calculation methodologies. |
| Climate-Linked Comprehensive Pricing | Catastrophe modeling integration enables dynamic territorial rating tied to flood and wildfire exposure zones. |
Research Methodology
Multiple input streams — regulatory filing databases, carrier financial disclosures, and telematics platform technical specifications — were reconciled through bottom-up and top-down triangulation. Primary interviews with pricing actuaries, state insurance department examiners, agency network managers, and insurtech product officers informed operational assumptions. Secondary validation drew from NAIC statistical compilations, state rate filing repositories, SEC 10-K insurance segment disclosures, and vehicle registration databases.
Data-stream reconciliation across the projection horizon applied policy type, coverage tier, customer risk classification, and distribution channel segmentation dimensions. CAGRs were derived from premium volume trajectories calibrated against vehicle fleet growth and telematics penetration curves. Forecast inputs incorporated state-level regulatory approval timelines and medical cost inflation assumptions.
Revisions become necessary when autonomous vehicle liability frameworks materialize or state telematics mandates expand beyond current jurisdictions. Forecasts reflect documented assumptions regarding rate filing approval velocity and loss cost trend stability. A model refresh is warranted upon material change in federal insurance preemption legislation or NAIC data standard adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
India Car Insurance Market