
 Taiwan Car Insurance Market | 2026-2036
Taiwan Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Car Insurance Market Insights
Modular coverage bundling is expanding across Taiwan's car insurance sector, allowing fleet managers and individual owners to combine liability, collision, and personal injury protection into tailored annual policies. Fubon Insurance leverages extensive agency networks to sustain dominance in northern Taiwan's urban corridors. Cathay Century Insurance anchors its position through digital-first distribution channels that streamline policy issuance for individual owners. Shinkong Insurance Co., Ltd. differentiates via specialized commercial fleet programs serving logistics and rental operators.
Taiwan car insurance constitutes a risk-transfer mechanism where insurers pool premiums from vehicle owners to cover collision damage, third-party liability, bodily injury, and theft-related losses under contractually defined terms and sum-assured limits. The product serves to restore economic position after traffic incidents while satisfying compulsory coverage mandates under Taiwan's Road Traffic Management and Penalty Act. Liability coverage leads policy volumes given statutory minimums, while comprehensive coverage generates the deepest margin pools due to higher premium multiples and selective underwriting. Collision coverage competes on claims efficiency, with insurers prioritizing repair-network density in Taipei and Taichung. Personal injury protection remains underpenetrated among individual owners despite rising medical cost inflation.
The Financial Supervisory Commission shapes market access through capital adequacy requirements and rate-filing protocols that constrain pricing freedom. Compulsory automobile liability insurance regulations enforced by the Ministry of Transportation and Communications establish baseline coverage thresholds that all underwriters must meet. Taiwan's Personal Data Protection Act imposes strict limits on telematics data collection, slowing usage-based insurance rollout. Stakeholders must monitor regulatory appetite for autonomous vehicle liability frameworks and decide whether to build actuarial capabilities ahead of anticipated rulemaking.
Market Dynamics
The Financial Supervisory Commission's tightening of mandatory liability requirements is forcing insurers to recalibrate capital reserves and pricing models while fleet operators accelerate coverage purchases to meet compliance deadlines.
Growth Catalysts
- Compulsory Automobile Liability Insurance:The Ministry of Transportation and Communications enforces baseline coverage thresholds that expand the addressable policy base as vehicle registrations climb in Taipei and Kaohsiung.
- Telematics-enabled underwriting:Usage-based insurance platforms allow insurers to segment risk more granularly, attracting safety-conscious fleet managers with dynamic premium adjustments.
- Commercial fleet densification:Logistics operators in Taichung and Tainan are consolidating vehicle assets under single-policy umbrellas, driving bulk premium growth.
Market Restraints
- Personal Data Protection Act constraints:Strict limits on telematics data collection prevent insurers from deploying real-time driving behavior analytics at scale.
- Repair network concentration:Certified collision centers cluster disproportionately in northern Taiwan, inflating claim costs and extending settlement timelines for policyholders in outlying counties.
- Medical cost inflation:Bodily injury claim severity rises faster than premium rate adjustments, compressing loss ratios for personal injury protection lines.
Strategic Opportunities
- Autonomous vehicle liability frameworks:Anticipated rulemaking from the Financial Supervisory Commission creates first-mover advantage for insurers building actuarial capabilities in algorithmic fault attribution.
- Eastern Taiwan penetration:Hualien and Taitung counties show rising vehicle density with limited insurer presence, offering greenfield distribution expansion.
- Modular policy bundling:Annual contracts combining liability, collision, and personal injury protection attract fleet managers seeking administrative simplification.
Industry Challenges
- Actuarial talent scarcity:Insurers struggle to recruit data scientists capable of modeling autonomous vehicle risk and usage-based pricing algorithms.
- Legacy system integration:Digital-first distribution channels require costly middleware development to connect with core policy administration platforms built decades prior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Car Insurance Market |
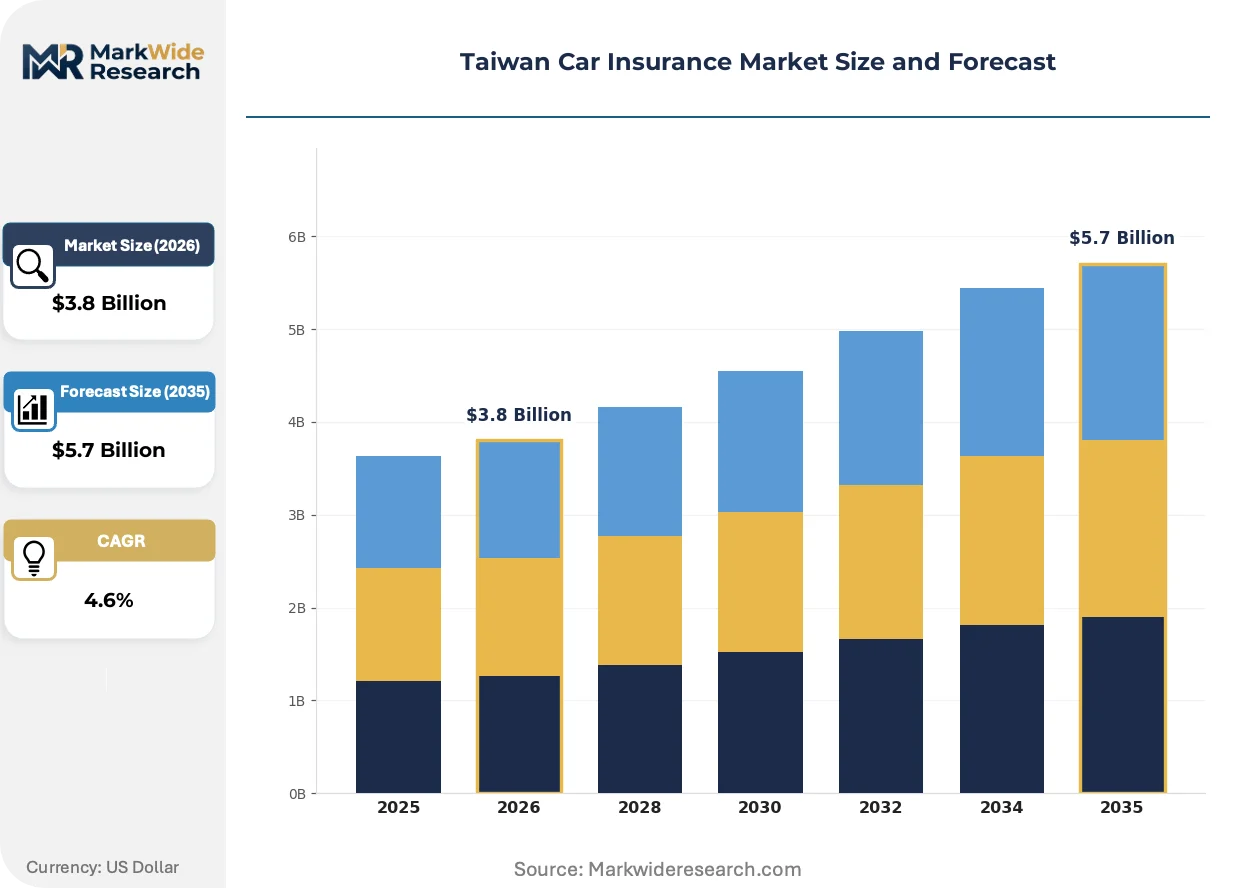
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Liability, Collision, Comprehensive, Personal Injury Protection Customer Type: Individual Owners, Fleets, Rental Services, Businesses Insurance Provider: Local Insurers, International Insurers, Brokers, Online Platforms Policy Duration: Short-Term, Long-Term, Annual, Multi-Year |
| Companies Covered | Shinkong Insurance Co., Ltd., Fubon Insurance, Chung Kuo Insurance Company Ltd, China Marine Insurance, Cathay Century Insurance, Taiwan Fire & Marine Insurance Company Ltd, Taian Insurance, Hua Nan Insurance, Hotai Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Car Insurance Market Trends and Innovations
Digital distribution channels and modular product architectures are compressing policy issuance cycles while regulatory pressure on data governance reshapes competitive capabilities.
Telematics platforms are expanding into Taiwan's car insurance sector as insurers deploy GPS-enabled devices to capture real-time driving behavior. Fleet operators in Kaohsiung's logistics corridor adopt these systems fastest, lured by premium discounts tied to safety scores. The technology is expanding into individual owner segments previously priced on static demographic factors alone.
Taiwan's Personal Data Protection Act imposes strict consent requirements and storage limits on driving behavior data collection. Insurers must architect anonymization pipelines and localized data residency, raising compliance costs. Digital-native underwriters respond by building privacy-by-design systems that limit third-party data sharing.
Channel disintermediation accelerates as individual owners bypass traditional agency networks for direct online policy issuance. Cathay Century Insurance captures this shift through streamlined digital platforms, while conventional agents in Taipei face commission compression. The behavior concentrates among younger demographics in New Taipei City and Taoyuan, where smartphone penetration and price transparency expectations run highest.
Taiwan Car Insurance Market Segmentation
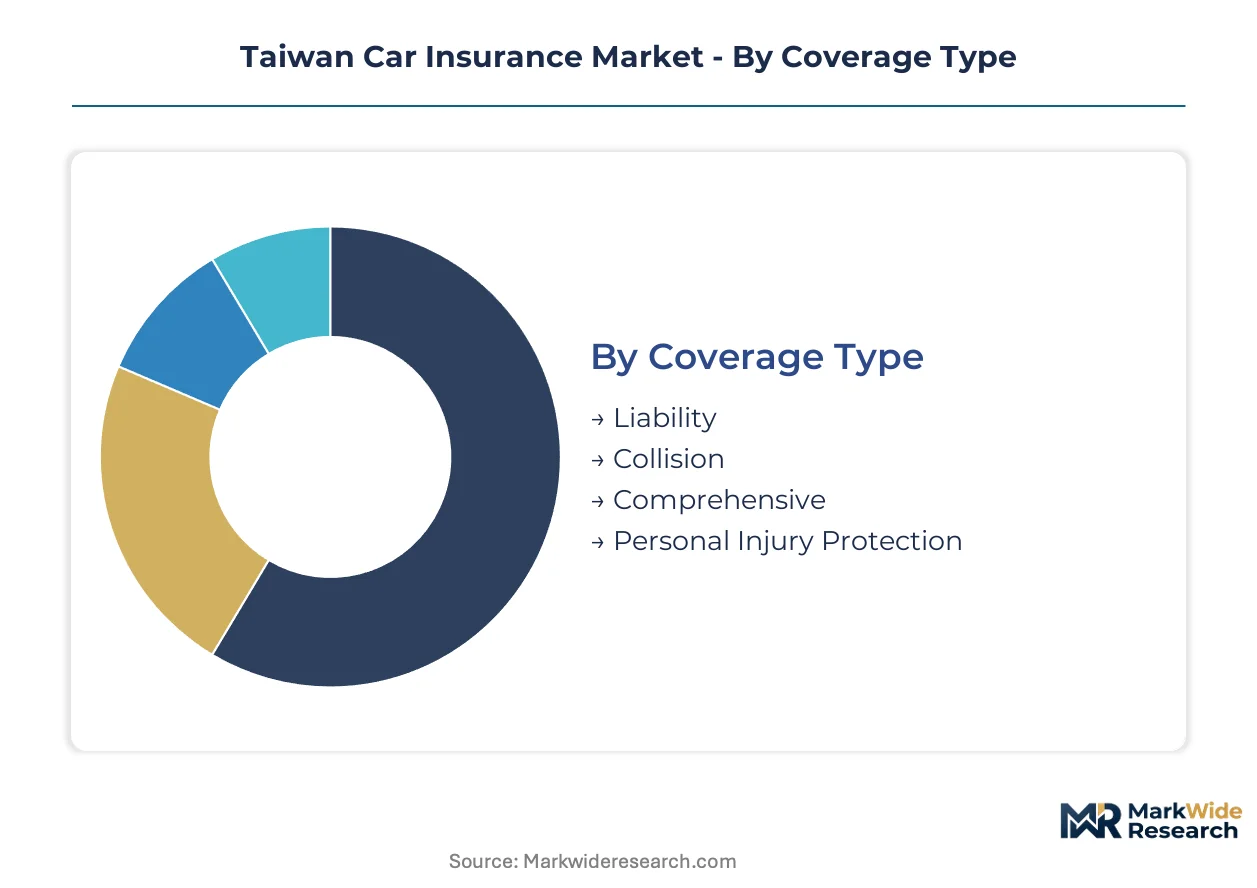
Segmentation in Taiwan's car insurance market reveals how regulatory mandates, customer risk profiles, and distribution economics create distinct competitive battlegrounds. Each dimension exposes different margin structures and capital requirements that shape insurer strategy.
Coverage Type:
Financial Supervisory Commission rate-filing protocols apply differentially across coverage types, with compulsory liability facing the tightest pricing constraints while comprehensive coverage allows more actuarial freedom.
- Liability:Statutory minimum coverage under Taiwan's Road Traffic Management and Penalty Act generates the highest policy volumes but thinnest margins. Fleet operators in Taipei and Kaohsiung bulk-purchase this coverage to satisfy tightened mandatory requirements from the Financial Supervisory Commission.
- Comprehensive:Bundled protection against theft, vandalism, and non-collision damage commands premium multiples three to four times liability rates. Selective underwriting in this segment concentrates among high-value vehicle owners in New Taipei City and Taoyuan.
- Collision:Damage repair coverage competes on claims efficiency and repair-network density. Certified collision centers cluster in northern Taiwan, creating geographic disparities in settlement speed.
- Personal Injury Protection:Medical cost reimbursement for occupants remains underpenetrated despite rising hospitalization expenses. Individual owners in outlying counties show lowest adoption rates.
Leading the category by volume: Liability. Growing fastest: Comprehensive.
Customer Type:
Risk concentration and policy administration costs vary sharply across customer types, with fleets offering scale economies that individual owners cannot match.
- Fleets:Logistics and rental operators consolidate hundreds of vehicles under single-policy umbrellas, generating bulk premium growth in Taichung and Tainan. Telematics-enabled underwriting attracts these customers with dynamic premium adjustments tied to safety scores.
- Individual Owners:Price-sensitive purchasers dominate this segment, increasingly bypassing agency networks for direct digital channels. Younger demographics in New Taipei City and Taoyuan drive channel disintermediation.
- Rental Services:Short-term vehicle utilization creates unique frequency-severity profiles requiring specialized loss modeling. This segment concentrates in urban tourism corridors.
- Businesses:Corporate vehicle pools demand modular coverage bundling that combines liability, collision, and personal injury protection into tailored annual contracts.
Highest premium per policy: Fleets. Steepest expansion trajectory: Individual Owners via digital channels.
Insurance Provider:
Capital adequacy requirements from the Financial Supervisory Commission create tiered market access, favoring established players with deep reserve bases.
- Local Insurers:Fubon Insurance and Cathay Century Insurance leverage extensive agency networks and digital-first platforms respectively. These firms dominate northern Taiwan's urban corridors through regulatory familiarity and repair-network relationships.
- International Insurers:Foreign capital participation faces constraints on branching licenses and rate-filing autonomy. Market presence concentrates in commercial specialty lines.
- Brokers:Independent intermediaries face commission compression as direct channels expand. Survival depends on complex commercial account service capabilities.
- Online Platforms:Digital-native distribution streamlines policy issuance for price-transparent younger demographics. Privacy-by-design systems address Personal Data Protection Act constraints on telematics deployment.
Deepest market penetration: Local Insurers. Gaining share fastest: Online Platforms.
Policy Duration:
Duration selection reflects customer liquidity preferences and insurer capital locking strategies, with longer terms reducing administrative churn but increasing interest rate risk exposure.
- Annual:Dominant contract structure enabling yearly coverage recalibration and rate adjustment. Fleet managers favor this duration for administrative alignment with fiscal planning cycles.
- Long-Term:Multi-year commitments lock in premium revenue and reduce acquisition cost amortization. Individual owners rarely select this option given price transparency expectations.
- Short-Term:Temporary coverage for vehicle transfers, seasonal fleet adjustments, or rental fleet rotations. Limited market presence outside specialty commercial applications.
- Multi-Year:Extended contracts with inflation-adjustment clauses appeal to risk-averse corporate purchasers seeking budget predictability.
Standard market practice: Annual. Expanding most quickly: Long-Term among fleet accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's car insurance production of risk capital concentrates in Taipei while consumption spreads across western corridor cities. The Financial Supervisory Commission regulates policy issuance from the capital as vehicle registrations climb in outlying counties.
Taipei City
Corporate headquarters and actuarial talent clusters drive underwriting capacity concentration in the capital. The Financial Supervisory Commission's rate-filing protocols require all insurers to maintain capital reserves accessible from Taipei-based operations. Certified collision repair networks and digital distribution platforms anchor northern Taiwan's insurance infrastructure here.
New Taipei City
Younger demographics with high smartphone penetration accelerate channel disintermediation away from traditional agencies. The Personal Data Protection Act shapes how digital-native platforms collect driving behavior data from this price-sensitive segment. Telematics-enabled policy issuance expands fastest among individual owners in this corridor.
Taichung
Logistics fleet consolidation under single-policy umbrellas generates bulk premium growth in central Taiwan. The Ministry of Transportation and Communications enforces compulsory automobile liability insurance thresholds that commercial operators must satisfy here. Repair network density lags northern Taiwan, extending claim settlement timelines.
Kaohsiung
Vehicle density and commercial fleet registrations create the second-largest policy volume concentration after Taipei. Fleet operators in the logistics corridor adopt telematics platforms fastest, lured by premium discounts tied to safety scores. The Financial Supervisory Commission's tightened mandatory liability requirements force accelerated coverage purchases here.
Hualien and Taitung Counties
Rising vehicle density with limited insurer presence offers greenfield distribution expansion opportunities in eastern Taiwan. The Road Traffic Management and Penalty Act applies uniform compulsory coverage mandates regardless of geographic remoteness. Repair network scarcity inflates claim costs and creates service gaps for policyholders.
Taiwan Car Insurance Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Taiwan's tiered car insurance market. Capital adequacy requirements from the Financial Supervisory Commission favor established players with deep reserve bases, creating barriers for new entrants. Three strategic archetypes dominate: local insurers with agency network scale, digital-first platforms with streamlined issuance, and specialized commercial fleet underwriters. Competitive moves concentrate on repair-network density expansion and telematics partnership formation.
Within the local insurer tier, Fubon Insurance and Cathay Century Insurance exemplify divergent distribution strategies. Fubon leverages extensive agency networks to sustain dominance in northern Taiwan's urban corridors, while Cathay Century anchors its position through digital-first channels that streamline policy issuance. Shinkong Insurance Co., Ltd. occupies a specialized position serving commercial fleet programs for logistics and rental operators. These three represent how capital reserves, regulatory familiarity, and repair-network relationships shape competitive positioning under Financial Supervisory Commission oversight.
| Leading Market Players |
|---|
| Shinkong Insurance Co., Ltd. |
| Fubon Insurance |
| Chung Kuo Insurance Company Ltd |
| China Marine Insurance |
| Cathay Century Insurance |
| Taiwan Fire & Marine Insurance Company Ltd |
| Taian Insurance |
| Hua Nan Insurance |
| Hotai Insurance |
| Others |
Pricing and Supply Chain Analysis
Fleet operator consolidation under single-policy umbrellas is forcing insurers to restructure premium calculation frameworks and repair-network contracting, compressing margins in liability lines while concentrating pricing power among carriers with certified collision center density in northern Taiwan.
Pricing Analysis
Margin tightening in compulsory liability coverage reflects Financial Supervisory Commission rate-filing constraints that limit actuarial freedom. Pricing stratifies across comprehensive, collision, and personal injury protection tiers based on repair-network proximity and telematics data availability. Cost-down pressure on liability lines accelerates because fleet buyers bulk-purchase coverage to satisfy tightened mandatory requirements. Individual owners in New Taipei City and Taoyuan show highest price sensitivity, while logistics operators prioritize claims efficiency over premium minimization.
Supply Chain Analysis
Freight cost inflation across the Taiwan Strait affects replacement parts availability and claim settlement timelines for insurers dependent on mainland component sourcing. Actuarial talent and telematics hardware draw from Taiwan, Japan, and South Korea. Supply chain risk centers on single-source vulnerability for GPS-enabled underwriting devices. Distribution runs through agency networks in Taipei, direct digital platforms in New Taipei City, and specialized fleet brokers in Taichung and Kaohsiung.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's car insurance sector is transitioning from static demographic pricing to telematics-enabled dynamic underwriting, with legacy agency distribution giving way to digital-first platforms.
For Market Incumbents: Anticipate channel disintermediation by accelerating repair-network density expansion in Taichung and Tainan to offset commission compression in northern Taiwan. Build actuarial capabilities in algorithmic fault attribution ahead of Financial Supervisory Commission autonomous vehicle liability rulemaking. Vertical integration into telematics data partnerships offers defensive positioning against digital-native entrants. For New Entrants and Emerging Players: Telematics-first distribution platforms offer white-space entry in Hualien and Taitung counties where incumbent presence remains limited. Target younger demographics in New Taipei City with privacy-by-design systems that satisfy Personal Data Protection Act constraints. Pursue modular policy bundling for small logistics operators seeking administrative simplification. For Investors and Strategic Acquirers: The window for entry favors digital-native platforms with established telematics partnerships and localized data residency architecture. Long-term viability hinges on regulatory navigation capabilities and repair-network relationships rather than pure price competition. Monitor Financial Supervisory Commission capital adequacy requirement adjustments as the primary inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables dynamic premium adjustments tied to safety scores for Kaohsiung logistics fleets. |
| Repair Network Expansion | Reduces claim settlement timelines in central Taiwan where certified collision centers lag northern density. |
| Privacy-by-Design System Development | Addresses Personal Data Protection Act constraints while capturing price-sensitive New Taipei City demographics. |
| Autonomous Vehicle Actuarial Capability Buildout | Creates first-mover positioning ahead of anticipated Financial Supervisory Commission liability frameworks. |
| Modular Policy Architecture Launch | Attracts fleet managers seeking administrative simplification across liability, collision, and personal injury lines. |
Research Methodology
Multi-period observation of premium rate filings, vehicle registration patterns, and telematics adoption curves anchored the trend analysis, supplemented by interviews with insurance underwriting executives, Financial Supervisory Commission regulatory affairs specialists, fleet procurement managers, and collision repair network operators. Secondary validation drew from Financial Supervisory Commission rate-filing databases, Ministry of Transportation and Communications vehicle registration statistics, and Personal Data Protection Act compliance disclosures. Bottom-up policy volume estimates triangulated against top-down premium pool calculations derived from regulatory capital reserve reports.
Input-output matrices modeled coverage type, customer segment, distribution channel, and regional vehicle density across the projection horizon. CAGRs were derived from segmented growth trajectory analysis incorporating compulsory liability mandate expansion, telematics penetration curves, and fleet consolidation patterns. Industry-specific forecast inputs included repair-network capacity constraints and medical cost inflation assumptions for bodily injury protection lines.
Several conditions sit outside the modeled scope, including autonomous vehicle liability framework finalization timing and potential Personal Data Protection Act amendments affecting telematics data retention. Forecasts reflect assumptions about regulatory enforcement continuity and fleet operator consolidation pace. Stakeholders should weight assumptions against their own operating context and monitor Financial Supervisory Commission rulemaking calendars for revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Motor Insurance Market