
 Saudi Arabia Motor Insurance Market | 2026-2036
Saudi Arabia Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Motor Insurance Market Analytics
Saudi Arabia is narrowing the gap between conventional underwriting and data-driven risk pricing as digital infrastructure expands across the Kingdom. Tawuniya leverages its established agency network to sustain market presence in commercial motor lines. Walaa Cooperative Insurance Company anchors its competitive stance through specialized fleet coverage programs. Allianz Saudi Fransi differentiates via advanced claims analytics platforms.
Saudi Arabia motor insurance constitutes a regulated financial service providing indemnity against vehicle damage, third-party liability, and bodily injury, with policies structured around actuarial risk pools and SAMA-mandated minimum coverage thresholds. The product serves to restore economic position after traffic incidents while enforcing legal compliance for road users. Comprehensive policies dominate premium value due to broader protection scope, while third-party liability retains volume leadership among price-sensitive individual drivers. Fleet owners represent the fastest-growing customer type as logistics sector expansion accelerates commercial vehicle registration.
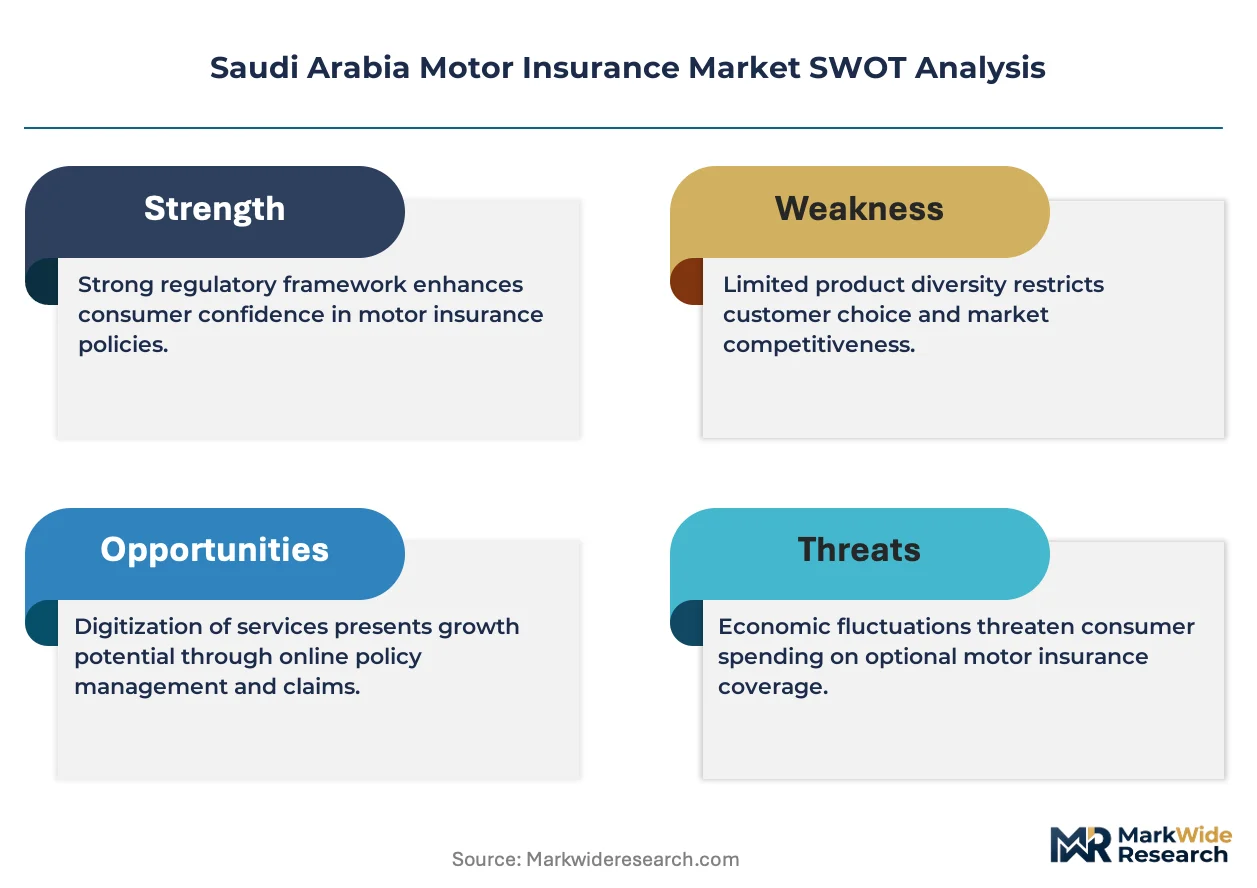
SAMA enforces unified policy wording and minimum coverage standards that standardize product offerings while capping premium variability. The Saudi central bank's regulatory sandbox permits telematics-based pricing experiments, enabling usage-adjusted premiums. Stakeholders must monitor how SAMA's evolving capital adequacy rules and potential compulsory coverage extensions reshape competitive economics.
Market Dynamics
SAMA's telematics integration mandate is compressing traditional underwriting cycles while forcing insurers to rebuild pricing engines around real-time driving data streams.
Growth Catalysts
- Logistics Fleet Expansion:Commercial vehicle registration accelerates as e-commerce fulfillment networks multiply across the Kingdom. Fleet operators now constitute the fastest-growing policyholder category.
- SAMA Regulatory Sandbox:The central bank's experimental framework permits usage-based insurance pilots. Insurers test dynamic premium adjustment tied to actual vehicle telemetry.
- Riyadh-Jeddah Corridor Density:Urban vehicle concentration in these two metropolitan zones sustains premium volume growth. Accident frequency in dense traffic environments maintains claims-driven policy renewal cycles.
Market Restraints
- Telematics Infrastructure Gaps:Rural coverage outside major urban corridors limits sensor deployment. Insurers face uneven data quality across the Kingdom's expansive geography.
- Actuarial Talent Scarcity:Shortage of professionals combining statistical modeling with Arabic-language regulatory interpretation. Training pipelines have not matched SAMA's accelerated digital mandates.
- Unified Policy Pricing Floors:SAMA-mandated minimum coverage standards compress premium variability. Competitive differentiation narrows to service execution rather than risk-based pricing.
Strategic Opportunities
- Eastern Province Commercial Hubs:Dammam and Khobar industrial zones show underpenetrated fleet coverage relative to vehicle stock. Specialized cargo and heavy-transport policies remain thinly distributed.
- Telematics-AI Convergence:Machine learning models processing real-time driver behavior data enable predictive claims prevention. Early adopters capture loss-ratio advantages before market standardization.
- Neom and Giga-Project Construction Fleets:Mega-development sites generate concentrated commercial vehicle demand. Project-specific coverage bundling creates sticky multi-year policy relationships.
Industry Challenges
- Legacy Core System Modernization:Established insurers operate on policy administration platforms incompatible with real-time data ingestion. Migration timelines conflict with SAMA's accelerated compliance deadlines.
- Cross-Functional Data Integration:Telematics streams must reconcile with existing claims databases and reinsurance reporting. Siloed IT architectures impede unified customer risk profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Motor Insurance Market |
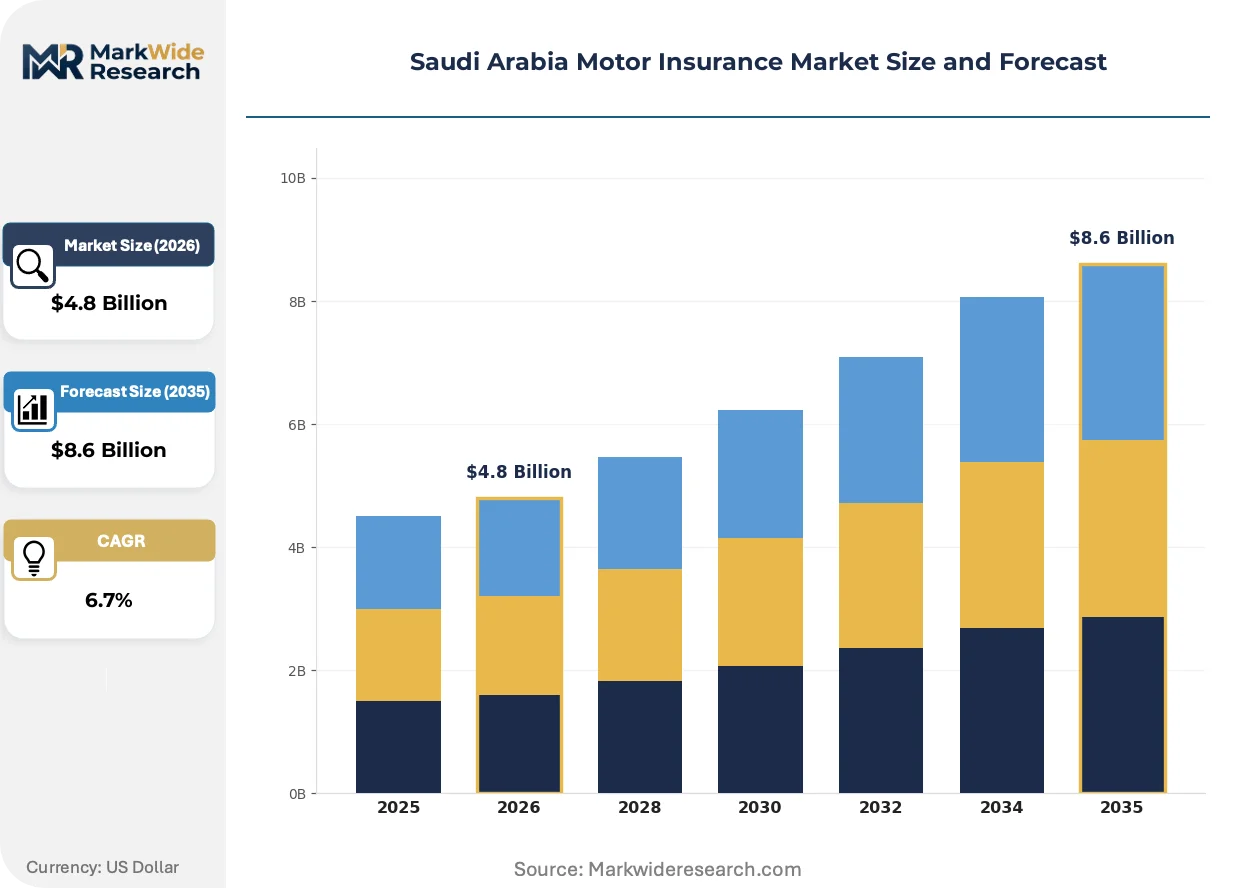
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
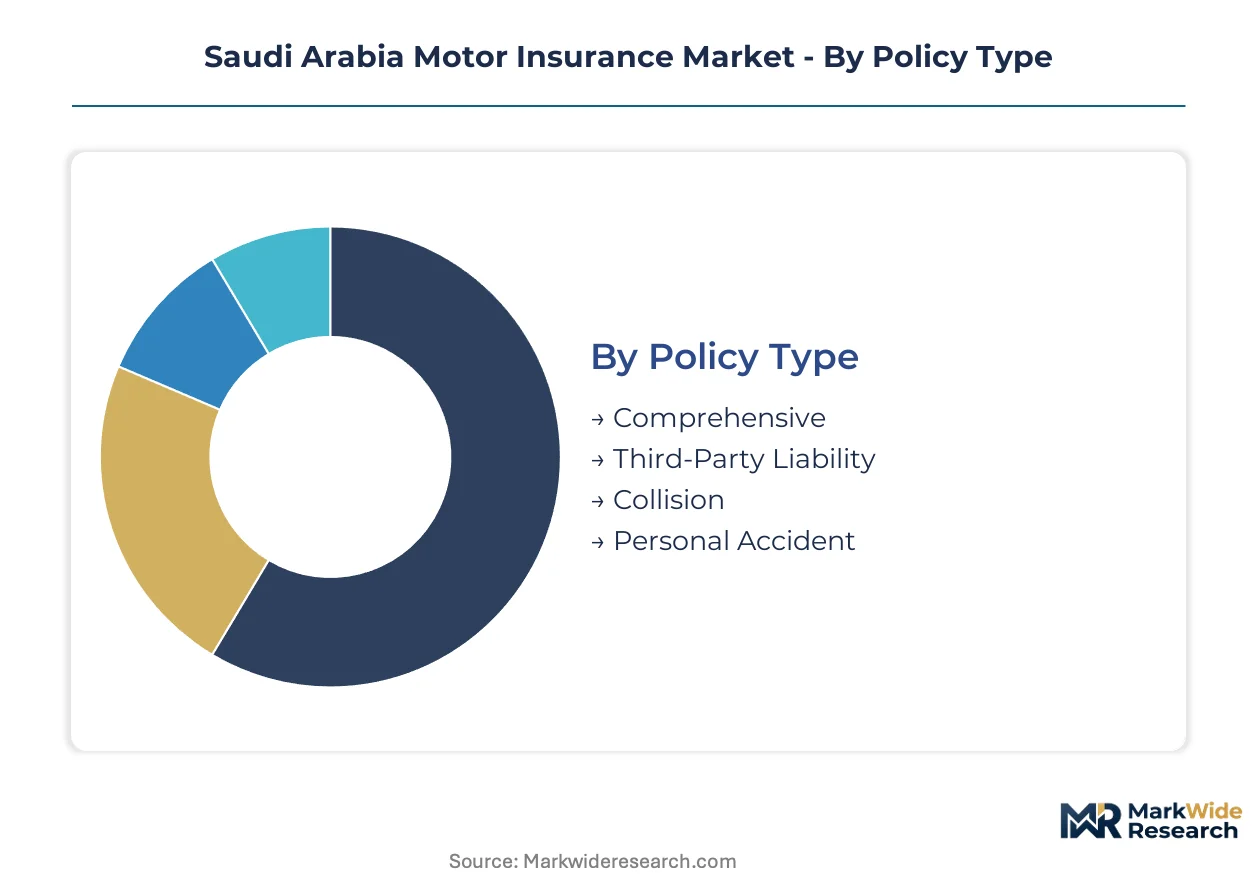
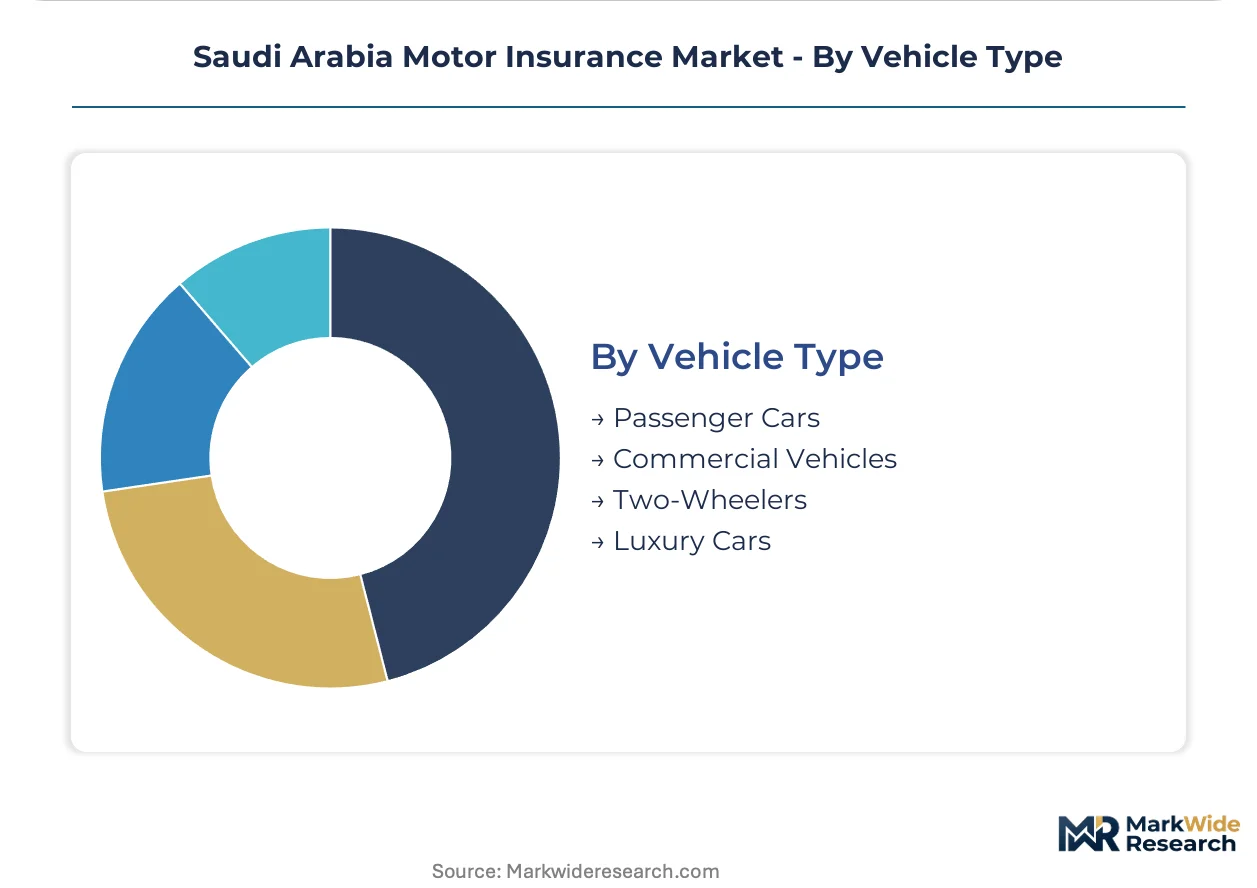
| Segmentation | Policy Type: Comprehensive, Third-Party Liability, Collision, Personal Accident Customer Type: Individual Drivers, Fleet Owners, Corporate Clients, Young Drivers Coverage Area: Urban Areas, Rural Areas, Highways, International Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Luxury Cars |
| Companies Covered | Walaa Cooperative Insurance Company, Allianz Saudi Fransi Cooperative Insurance Company, Tawuniya, AXA Cooperative Insurance Co., Rezayat Group, Al Rajhi Takaful, MedGulf, Salama Cooperative Insurance Co., Bupa Arabia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Motor Insurance Market Evolving Landscape
Digital infrastructure deployment across Saudi Arabia is collapsing the lag between risk occurrence and price adjustment, compressing traditional annual policy cycles into dynamic, data-responsive instruments.
Telematics hardware is hybridizing conventional motor insurance with real-time risk monitoring. Fleet operators in the logistics sector adopt connected vehicle platforms at accelerating rates. This convergence enables insurers to segment premiums by actual driving behavior rather than static demographic proxies.
SAMA's unified policy framework mandates standardized coverage wording while permitting experimental pricing models. The regulation creates parallel tracks: baseline compliance products and sandbox-tested usage-adjusted alternatives. Commercial lines show strongest response, with fleet managers negotiating telemetry-linked premium schedules.
Buyer procurement patterns favor bundled service relationships over transactional annual renewal. Corporate fleet managers consolidate insurance with maintenance and telematics providers. This consolidation concentrates purchasing power among logistics operators with multi-hundred vehicle portfolios.
Saudi Arabia Motor Insurance Market Segmentation
SAMA's unified policy framework compresses product differentiation, forcing insurers to compete through segment-specific service execution rather than coverage innovation. Telematics mandates are reshaping how each customer type experiences risk assessment and premium adjustment.
Policy Type:
Use-case spectrum spans from baseline legal compliance to full financial protection against vehicle damage and bodily injury.
- Comprehensive:Bundles own-damage, third-party liability, and personal accident coverage into single contracts. Riyadh and Jeddah individual owners drive demand as vehicle values and repair costs escalate in dense urban corridors.
- Third-Party Liability:SAMA-mandated minimum coverage satisfying legal road-use requirements. Price-sensitive individual drivers across the Kingdom sustain volume leadership despite narrower protection scope.
- Collision:Narrow coverage targeting vehicle-to-vehicle damage excluding theft, fire, or natural perils. Fleet operators in logistics corridors favor this for controlled-risk commercial deployments.
- Personal Accident:Medical expense and disability indemnity for drivers and passengers. Corporate client procurement increasingly bundles this with fleet policies for employee duty-of-care compliance.
Established volume favors Third-Party Liability; emerging adoption favors Comprehensive.
Customer Type:
Cost tier differentiation separates transactional individual purchasers from relationship-driven commercial accounts with negotiating leverage.
- Individual Drivers:Single-vehicle policyholders purchasing annual coverage through agency networks or direct digital channels. Riyadh-Jeddah corridor density concentrates premium volume alongside elevated accident frequency.
- Fleet Owners:Multi-vehicle commercial operators managing centralized insurance procurement. Logistics sector expansion across the Kingdom is accelerating policy uptake among this category.
- Corporate Clients:Non-logistics businesses insuring executive vehicles and staff transportation pools. Eastern Province industrial zones show rising penetration as foreign investment flows into Dammam and Khobar.
- Young Drivers:Demographic segment facing elevated risk-rated premiums due to actuarial accident propensity. SAMA's telematics sandbox offers pathways to behavior-adjusted pricing for this cost-burdened group.
Individual Drivers anchor current premium volume; Fleet Owners are gaining share fastest as commercial registration accelerates.
Coverage Area:
Geographic application determines risk pool composition and claims service infrastructure requirements.
- Urban Areas:Policies covering Riyadh, Jeddah, Dammam, and Khobar metropolitan zones. Dense traffic and higher repair costs sustain elevated premium levels relative to rural counterparts.
- Rural Areas:Coverage extending across Kingdom provinces beyond major city limits. Telematics infrastructure gaps limit dynamic pricing deployment and complicate claims verification.
- Highways:Corridor-specific policies addressing long-distance commercial transit risks. Logistics fleet operators prioritize this for inter-city cargo movements between the Eastern Province and Red Sea ports.
- International:Cross-border coverage for vehicles operating in neighboring GCC states. Corporate and luxury vehicle segments drive limited demand given regulatory complexity and bilateral agreement requirements.
Urban Areas dominate premium concentration; Highways show steepest expansion trajectory as logistics networks multiply.
Vehicle Type:
Customer type and margin profile vary sharply across passenger, commercial, and specialty vehicle classes.
- Passenger Cars:Standard private vehicles comprising the volume base of individual motor insurance. Comprehensive coverage penetration runs highest in this segment among Riyadh and Jeddah middle-income households.
- Commercial Vehicles:Trucks, vans, and buses serving logistics, construction, and distribution sectors. Fleet owner procurement is concentrating coverage growth in this category across Neom and giga-project sites.
- Two-Wheelers:Motorcycles and scooters with distinct risk profiles and lower average insured values. Young driver demographics and delivery gig economy roles sustain niche demand in urban centers.
- Luxury Cars:High-value vehicles requiring specialized underwriting and repair network access. Jeddah's affluent districts and corporate executive fleets generate concentrated premium density.
Passenger Cars retain volume leadership; Commercial Vehicles are climbing the fastest as fleet registration outpaces private vehicle growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMA anchors motor insurance demand across the Kingdom through mandatory unified policy standards and telematics integration mandates that reshape underwriting economics. Urban concentration in Riyadh and Jeddah drives premium volumes, while logistics corridor expansion into the Eastern Province and NEOM construction zones accelerates commercial fleet registration.
Riyadh
Vehicle density in the capital sustains the highest premium concentration nationwide. SAMA's regulatory sandbox permits usage-based insurance pilots among Riyadh-based fleet operators. King Abdullah Financial District houses insurers rebuilding pricing engines around real-time telemetry streams.
Eastern Province
Dammam and Khobar industrial zones generate concentrated commercial vehicle demand from logistics and petrochemical transport fleets. SAMA capital adequacy rules apply uniformly, yet local insurers face uneven telematics infrastructure outside metropolitan cores. Jubail industrial city anchors heavy-transport coverage growth as construction materials flow to giga-project sites.
Western Region
Jeddah's affluent districts drive comprehensive coverage penetration among luxury vehicle owners. The Red Sea port corridor sustains inter-city cargo transit policies linking to Mecca and Medina. Makkah Region's pilgrimage transport operators negotiate specialized fleet arrangements during seasonal demand spikes.
NEOM Northwest
The linear city construction site generates project-specific commercial vehicle coverage at scale. SAMA permits experimental policy bundling for captive construction fleets operating within the development zone. Oxagon industrial city anchors multi-year sticky relationships as insurers integrate with project logistics consortia.
Saudi Arabia Motor Insurance Market Competitive Landscape
Established domestic insurers and international joint ventures split the market along regulatory compliance depth versus technology platform sophistication lines. SAMA's unified policy framework compresses product differentiation, forcing competition into service execution and data infrastructure layers. Three archetypes dominate: cooperative insurers leveraging agency networks, international partnerships importing analytics capabilities, and Takaful operators serving Shariah-compliant segments. Consolidation pressure intensifies through strategic partnerships linking telematics providers with underwriting platforms, while geographic expansion into underpenetrated Eastern Province hubs reshapes territorial economics.
Within the cooperative tier, Tawuniya and Walaa Cooperative Insurance Company exemplify network-scale domestic players. Allianz Saudi Fransi Cooperative Insurance Company anchors the international partnership archetype, representing advanced claims analytics positioning. These three occupy distinct strategic positions without overlapping capability claims.
| Leading Market Players |
|---|
| Walaa Cooperative Insurance Company |
| Allianz Saudi Fransi Cooperative Insurance Company |
| Tawuniya |
| AXA Cooperative Insurance Co. |
| Rezayat Group |
| Al Rajhi Takaful |
| MedGulf |
| Salama Cooperative Insurance Co. |
| Bupa Arabia |
| Others |
Value Network & Pricing Analysis
Undercapacity in actuarial talent pipelines across Riyadh and Jeddah is compressing pricing flexibility as insurers compete for limited underwriting expertise. SAMA's unified policy floors cap premium variability while telematics deployment costs reshape supplier economics.
Pricing Analysis
Riyadh-Jeddah corridor premiums sustain a 40-60% spread over Eastern Province and rural counterparts due to accident frequency and repair cost density. Three-tier pricing structure across premium, standard, and economy levels dominates, with fleet volume scale and telematics adoption status as primary differentiation drivers. Cost compression in third-party liability tiers is intensifying because SAMA-mandated minimums prevent risk-based undercutting. Individual drivers in rural zones exhibit highest price sensitivity; logistics fleet operators with telemetry-linked contracts show lowest.
Supply Chain Analysis
Extended payment terms from telematics hardware vendors to insurers now stretch 90-120 days as device manufacturers absorb working capital pressure. Supply concentrates in China for sensor modules, South Korea for semiconductor components, and domestic Saudi assembly for localized device configuration. Raw material dependencies span lithium-ion power cells, GPS chipsets, and cellular communication modules. Single-source vulnerability runs through Chinese sensor suppliers subject to export licensing variability. Distribution runs through Tawuniya and Walaa agency networks for individual policies, direct enterprise sales for fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gap between SAMA's digital mandates and available Arabic-speaking actuarial talent is constraining competitive response speed. Insurers who close this capability gap through targeted recruitment or partnership structures will capture pricing precision advantages.
For Market Incumbents: Build data moats through exclusive telematics-AI integration partnerships before sandbox standardization erodes differentiation. Consolidate Eastern Province agency presence in Dammam and Khobar to preempt fleet operator procurement consolidation. Threat: International partnerships importing analytics capabilities. Lever: Backward integration into captive telematics data processing infrastructure. For New Entrants and Emerging Players: Pursue white-space fleet coverage in Neom construction zones and Jubail industrial city heavy-transport segments. Eastern Province commercial hubs offer lowest competitive density relative to vehicle stock. Go-to-market angle: Project-specific multi-year bundling with construction logistics consortia. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet operators with telemetry-linked premium schedules and sticky multi-year policy relationships. Long-term viability favors insurers with demonstrated SAMA sandbox participation and core system modernization runway. Target acquisition archetype: Mid-tier cooperative insurers with agency network scale but legacy IT constraints. Signal to watch: SAMA capital adequacy rule tightening on non-compliant core systems.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-AI Platform Integration | Machine learning models processing SAMA-sanctioned driving data enable predictive claims prevention advantages. |
| Eastern Province Agency Expansion | Dammam and Khobar industrial zones show underpenetrated fleet coverage relative to commercial vehicle stock. |
| Neom Project Coverage Bundling | Oxagon industrial city anchors multi-year sticky relationships with captive construction fleet operators. |
| Core System Modernization | Migration to real-time data ingestion platforms resolves conflict with SAMA's accelerated compliance deadlines. |
| Actuarial Talent Partnership | University and vocational pipelines addressing Arabic-language statistical modeling scarcity reduce underwriting cycle compression. |
Research Methodology
A spread of perspectives from SAMA regulatory affairs officers, fleet procurement managers at logistics operators, telematics platform engineers, and cooperative insurance underwriting directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SAMA circular archives, Saudi Central Bank statistical releases, and commercial vehicle registration databases. Bottom-up policy volume estimates triangulated against top-down premium pool calculations from regulatory filings.
Demand-supply balance framing anchored the analytical framework, with fleet registration velocity and telematics penetration rates as primary demand-side variables against actuarial capacity and licensed insurer count on the supply side. Segmentation dimensions spanned policy type, customer archetype, coverage geography, and vehicle class. CAGRs derived from logistic curve fitting to historical premium growth and projected fleet expansion across the analysis window. Industry-specific inputs included SAMA sandbox participant rosters and giga-project construction timelines.
Sensitivities concentrate around SAMA regulatory timeline acceleration, telematics infrastructure deployment delays outside urban corridors, and logistics sector growth volatility. Forecasts reflect documented assumptions on regulatory stability and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
Motorcycle Insurance Market