
 Canada Motor Insurance Market | 2026-2036
Canada Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Motor Insurance Market Outlook
Ontario's underwriting capacity is narrowing as climate-related claims frequency strains regional actuarial reserves. Intact Insurance leverages proprietary telematics data to refine risk segmentation across provincial portfolios. Desjardins General Insurance Group anchors its position through integrated banking-insurance cross-selling in Quebec. Economical Insurance competes via mutual ownership structure appeal in rural and agricultural vehicle segments.
Canada motor insurance constitutes a contractual risk-transfer mechanism indemnifying policyholders against financial loss from vehicle damage, bodily injury, or third-party liability, with premiums calibrated through actuarial modeling of driving behavior, vehicle classification, and territorial rating factors. The primary commercial purpose centers on restoring capital position after insurable motor events while satisfying mandatory coverage thresholds set by provincial regulators. Liability Coverage dominates policy issuance volumes due to statutory minimum requirements across all provinces, while Comprehensive Coverage captures disproportionate margin contribution from newer vehicle portfolios with higher replacement valuations. Broker distribution channels sustain premium flow in complex commercial fleet accounts where risk engineering demands personalized placement, though Online Platforms accelerate in standard personal auto segments.
Health Canada collaborates with provincial insurance regulators to align injury claim protocols with healthcare cost containment objectives, while the Office of the Superintendent of Financial Institutions imposes capital adequacy thresholds that constrain carrier expansion velocity. Provincial rate boards in Ontario, British Columbia, and Alberta directly approve or modify premium filings, embedding political sensitivity into pricing autonomy. Stakeholders must monitor how autonomous vehicle liability frameworks evolve under federal transport safety consultations and whether provincial no-fault expansion redistributes litigation cost structures.
Market Dynamics
Telematics-enabled usage-based pricing is collapsing traditional territorial rating models as insurers capture real-time driving behavior data, forcing carriers to rebuild actuarial infrastructure around continuous risk monitoring rather than static demographic proxies.
Growth Catalysts
- Vehicle Electrification Mandates:Federal zero-emission vehicle sales targets are expanding insurable asset bases across commercial fleets and personal auto segments, requiring new coverage formulations for battery replacement and charging infrastructure liability.
- Provincial Rate Regulation Reforms:Ontario's Financial Services Regulatory Authority is streamlining prior-approval processes, compressing filing-to-market timelines for innovative product structures.
- Connected Fleet Telematics:Commercial operators in Alberta's oil sands logistics corridors are adopting embedded vehicle sensors, generating granular loss data that supports experience-rated premium structures.
Market Restraints
- Climate Loss Volatility:Catastrophic weather events in British Columbia's Fraser Valley are depleting provincial catastrophe reserves, constraining reinsurance capacity for regional personal auto portfolios.
- Actuarial Talent Concentration:Predictive modeling expertise clusters in Toronto and Montreal, creating hiring bottlenecks for carriers expanding telematics programs in prairie provinces.
- Legacy System Technical Debt:Core policy administration platforms at established insurers lack API architectures, delaying real-time data integration from IoT devices.
Strategic Opportunities
- Autonomous Vehicle Liability Frameworks:Federal transport safety consultations are defining product liability boundaries between manufacturers and insurers, opening coverage white space for software failure and sensor malfunction risks.
- Parametric Weather Products:Index-based hail and flood coverage for agricultural vehicles in Saskatchewan is bypassing traditional claims adjustment costs through satellite-triggered payouts.
- Embedded Insurance Distribution:Electric vehicle manufacturers are integrating coverage at point-of-sale through direct API partnerships, capturing first-mover relationships with new vehicle buyers.
Industry Challenges
- Cross-Provincial Data Harmonization:Quebec's distinct civil law tradition and privacy frameworks complicate national telematics data pooling, fragmenting risk segmentation capabilities.
- Capital Intensity of IoT Infrastructure:Real-time claims prevention systems require sustained investment in edge computing networks and cybersecurity protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Motor Insurance Market |
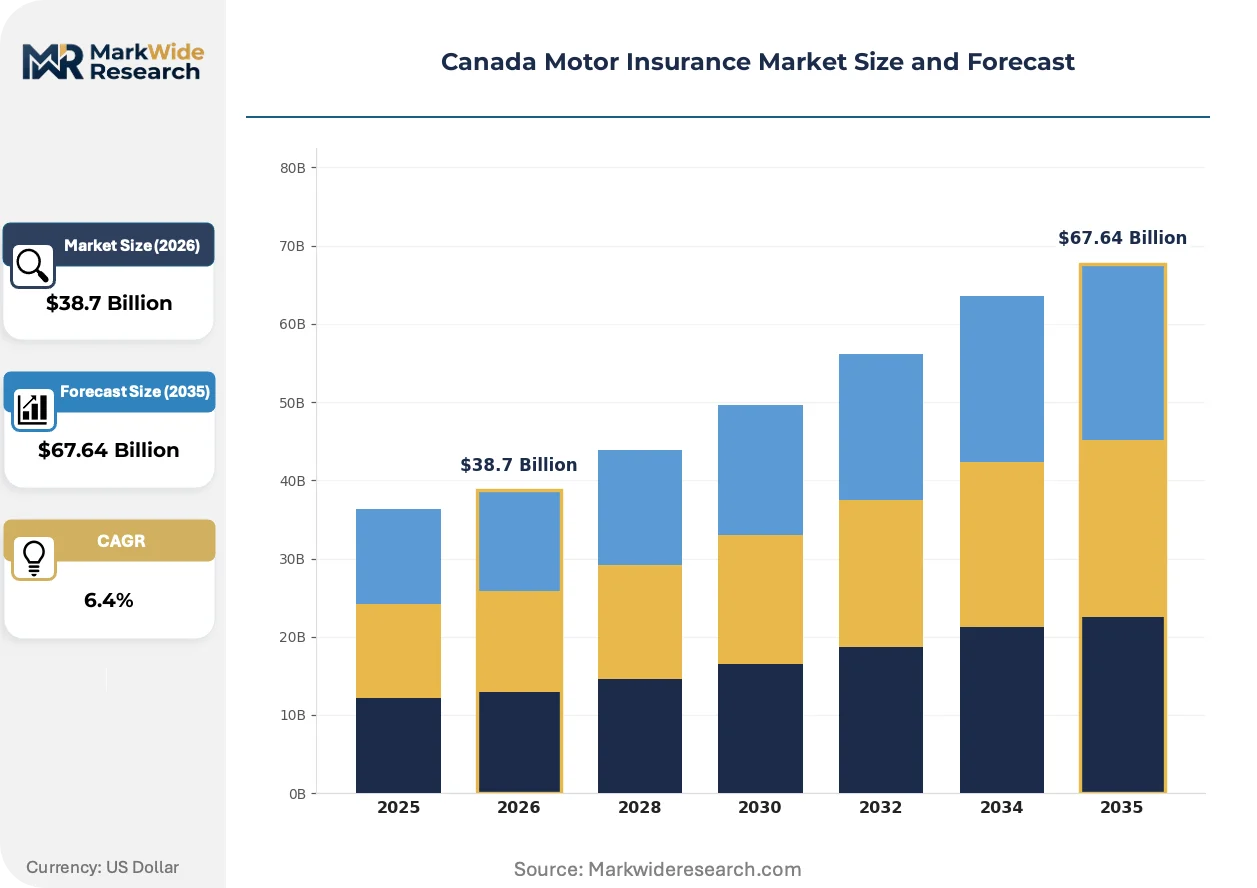
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Liability Coverage, Collision Coverage, Comprehensive Coverage, No-Fault Coverage Customer Type: Individual, Fleet Owner, Commercial, Non-Standard Distribution Channel: Direct Sales, Agents, Brokers, Online Platforms Coverage Limit: Low Limit, Medium Limit, High Limit, Custom Limit |
| Companies Covered | Aviva Canada, Economical Insurance, Intact Insurance, Wawanesa, The Personal, The Co-operators, TD Insurance, belairdirect, Desjardins General Insurance Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Motor Insurance Market Strategic Shifts
Behavioral data capture and algorithmic pricing are dismantling century-old insurance operating models, compressing the gap between risk occurrence and capital response while redistributing value between carriers, distributors, and policyholders.
AI-powered claims triage is collapsing traditional adjuster workflows by automating damage assessment through computer vision analysis of smartphone-submitted photos. Personal auto carriers in Ontario are deploying these systems for low-severity collisions, compressing settlement cycles from weeks to hours. The structural consequence is a workforce pivot toward complex liability disputes and fraud investigation while routine physical damage processing becomes fully algorithmic.
Health Canada's alignment of injury claim protocols with provincial healthcare cost containment is reshaping accident benefits structures in Ontario and Alberta. The industrial consequence is a shift toward preferred provider networks and treatment caps for minor injuries. Commercial fleet accounts are most affected, responding by expanding self-insured retentions and negotiating direct healthcare provider contracts.
Subscription-based mobility coverage is displacing annual policy structures as ride-share drivers and car-sharing participants demand episodic protection. Digital managing general agents are capturing this demand through mobile-first platforms that activate coverage by the hour. British Columbia's dense urban corridors exhibit the strongest adoption, where vehicle ownership rates are declining fastest among younger demographics.
Canada Motor Insurance Market Segmentation
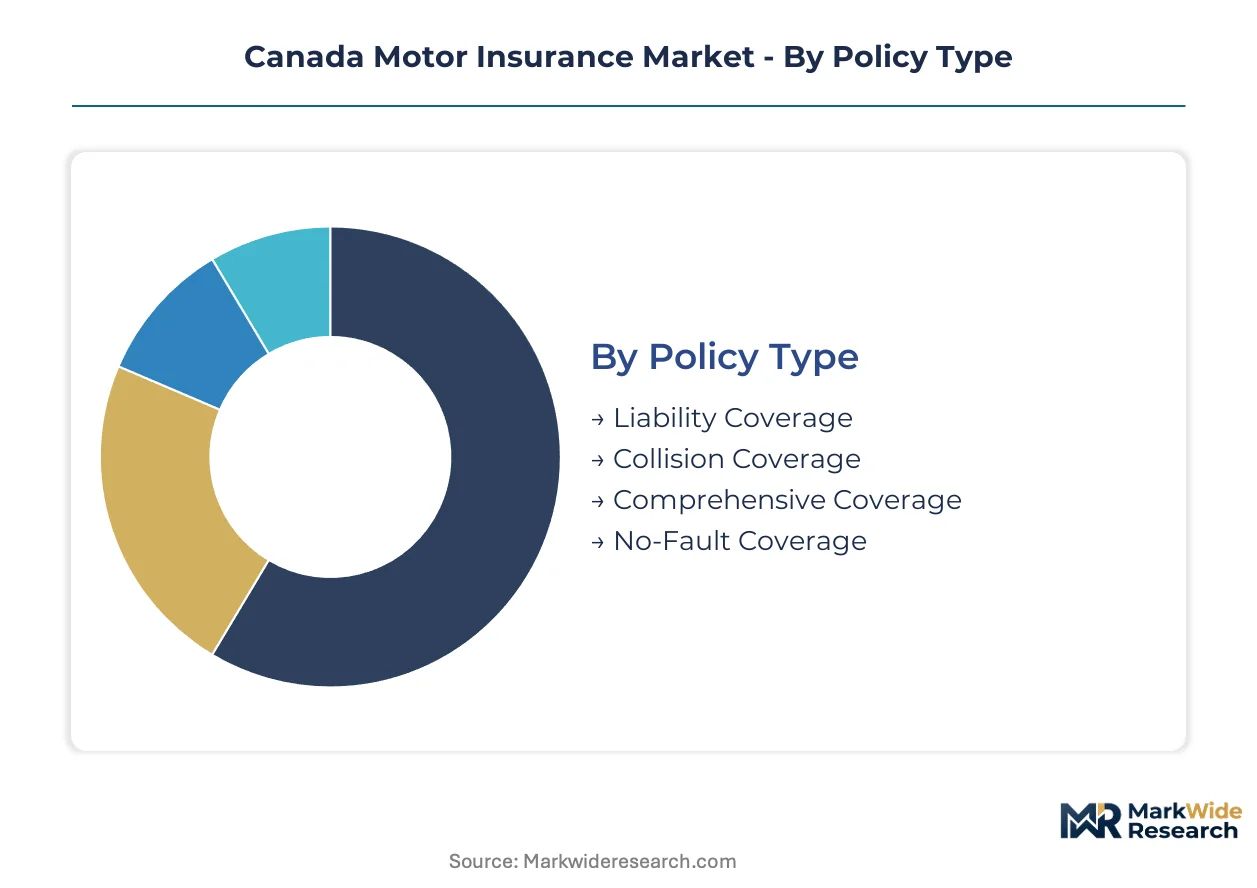
Motor insurance segmentation in Canada determines capital allocation precision, with policy type and distribution channel configurations directly shaping loss ratio performance across provincial regulatory environments.
Policy Type:
After-sales service intensity varies sharply by policy type, with liability and comprehensive segments demanding divergent claims handling infrastructure and customer touchpoint frequencies.
- Liability Coverage:Statutorily mandated minimum protection against third-party bodily injury and property damage claims. Demand concentrates in Ontario's Greater Toronto Area where dense vehicle ownership elevates collision frequency and litigation exposure.
- Comprehensive Coverage:Non-collision protection encompassing theft, vandalism, weather damage, and fire loss. Replacement cost valuations for newer vehicles in British Columbia's high-value urban corridors drive premium margin contribution disproportionate to policy volume.
- Collision Coverage:Physical damage protection for at-fault accidents with deductible structures. Commercial fleet operators in Alberta's oil sands logistics corridors prioritize this coverage for heavy-duty vehicle replacement cycles.
- No-Fault Coverage:First-party accident benefits limiting litigation rights in exchange for faster claim resolution. Quebec's civil law tradition anchors this structure, with Ontario's Financial Services Regulatory Authority monitoring expansion feasibility.
Liability Coverage holds the largest share; momentum sits with Comprehensive Coverage.
Customer Type:
Premium calibration complexity escalates across customer tiers, with fleet and commercial segments requiring dedicated risk engineering resources absent from standard personal lines.
- Individual:Personal auto policyholders representing standardized risk pools rated through territorial and demographic proxies. Telematics adoption is expanding most quickly among this segment in Ontario and British Columbia urban corridors.
- Commercial:Corporate vehicle operators with complex liability exposures and multi-jurisdictional coverage requirements. Alberta's energy sector logistics operations generate concentrated demand for specialized commercial auto formulations.
- Fleet Owner:Multi-vehicle operators with experience-rated premium structures tied to loss history and safety program documentation. Saskatchewan's agricultural equipment fleets anchor regional carrier specialization.
- Non-Standard:High-risk drivers excluded from standard markets due to conviction history or coverage lapses. Provincial residual market mechanisms in Ontario and Alberta absorb this volume through assigned risk pools.
Individual policies dominate volume; Commercial accounts deliver steepest expansion trajectory.
Distribution Channel:
Channel economics fragment across complexity thresholds, with broker networks sustaining premium flow where risk engineering demands personalized placement expertise.
- Brokers:Independent intermediaries placing complex commercial fleet accounts and non-standard risks. Ontario's regulatory framework preserves broker commission structures despite direct channel competitive pressure.
- Online Platforms:Digital-first distribution capturing standard personal auto segments through algorithmic quoting and policy issuance. British Columbia's younger demographics exhibit strongest adoption of mobile-first purchasing.
- Agents:Exclusive or captive representatives tied to single carriers with limited product portfolios. Quebec's integrated banking-insurance cross-selling networks leverage this channel for Desjardins distribution.
- Direct Sales:Carrier-owned channels bypassing intermediary commissions for price-competitive standard risks. Intact Insurance deploys proprietary telematics data to refine direct-to-consumer targeting.
Brokers retain largest commercial share; Online Platforms are gaining share fastest.
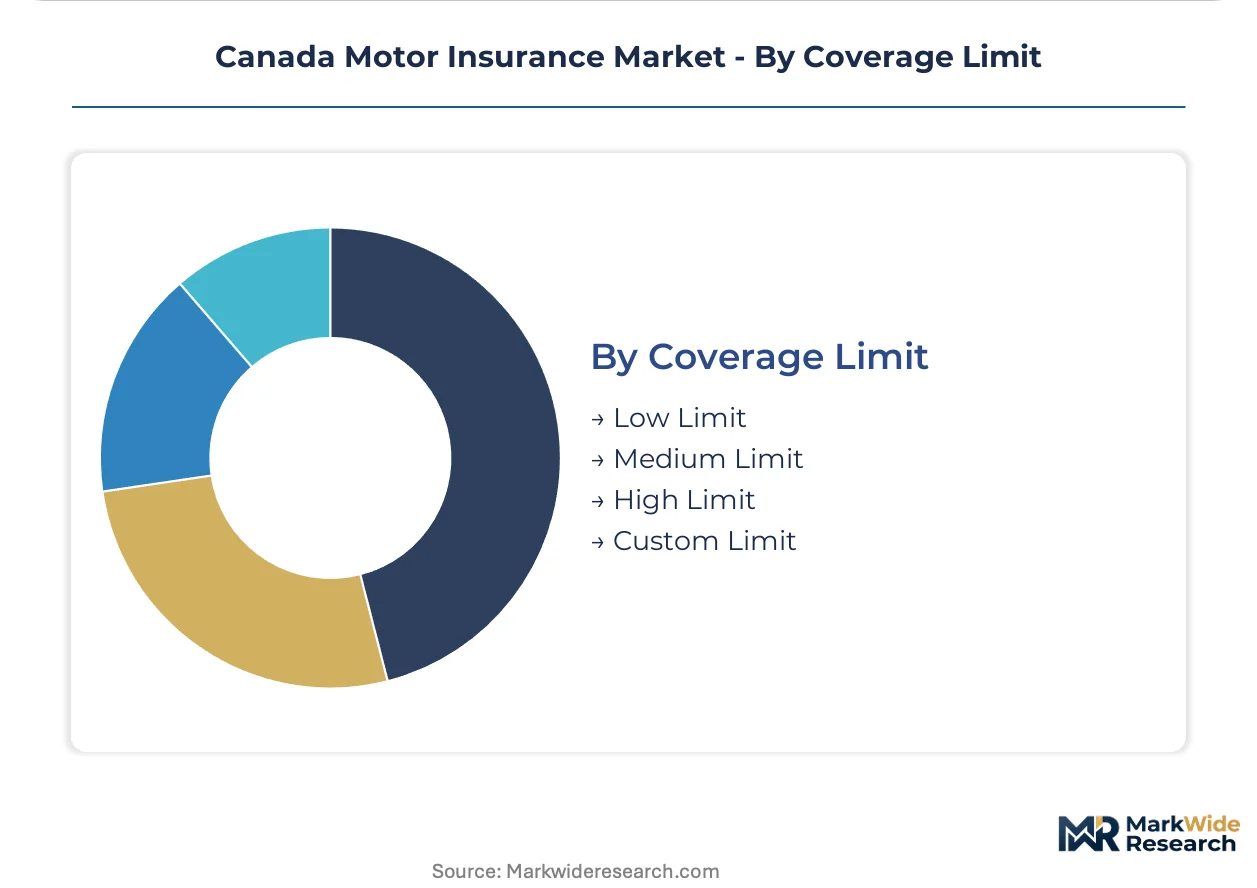
Coverage Limit:
Limit selection correlates with asset valuation and litigation environment exposure, with custom structures emerging for specialized commercial risks.
- High Limit:Elevated liability thresholds protecting against catastrophic loss exposure. High-net-worth individuals in Vancouver and Toronto metropolitan areas anchor demand for umbrella auto coverage.
- Custom Limit:Tailored structures negotiated for commercial fleets with unique risk profiles. Alberta's heavy haulage operators require limit configurations aligned with contractually mandated insurance requirements.
- Medium Limit:Standard protection tiers balancing premium affordability with asset coverage adequacy. Provincial rate boards in Ontario and Alberta approve these filings most frequently.
- Low Limit:Minimum statutory requirements satisfying mandatory coverage thresholds. Price-sensitive segments in rural Saskatchewan and Manitoba concentrate here.
Medium Limit structures dominate policy issuance; Custom Limit configurations show strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Office of the Superintendent of Financial Institutions anchors national capital adequacy standards while provincial rate boards in Ontario, British Columbia, and Alberta govern premium approval processes. Regional divergence in regulatory frameworks and risk exposure profiles shapes carrier expansion strategies.
Ontario
Dense vehicle ownership in the Greater Toronto Area elevates collision frequency and litigation exposure. The Financial Services Regulatory Authority streamlines prior-approval processes for innovative product filings. Toronto's concentration of actuarial talent supports telematics program development for usage-based pricing models.
Quebec
Desjardins General Insurance Group leverages integrated banking-insurance cross-selling networks. The province's civil law tradition anchors no-fault accident benefit structures distinct from common law jurisdictions. Montreal serves as the hub for French-language policy administration and customer service operations.
British Columbia
Catastrophic weather events in the Fraser Valley deplete provincial catastrophe reserves and constrain reinsurance capacity. The Insurance Corporation of British Columbia manages mandatory basic coverage through public sector mechanisms. Vancouver's high-value urban corridors drive disproportionate comprehensive coverage margins from newer vehicle portfolios.
Alberta
Commercial fleet operators in oil sands logistics corridors generate concentrated demand for specialized heavy-duty vehicle formulations. The provincial rate board approves medium-limit filings most frequently for standard risk tiers. Calgary anchors regional carrier operations and risk engineering resources for energy sector accounts.
Canada Motor Insurance Market Competitive Environment
Diversified national carriers and mutual ownership structures split the market between scale-driven pricing power and policyholder-aligned governance models. The competitive terrain exhibits moderate consolidation with tiered specialization across personal lines, commercial fleets, and non-standard risks. Strategic archetypes include integrated financial conglomerates, mutual insurers, and direct-to-consumer specialists. Dominant competitive moves encompass telematics data partnerships and embedded insurance API integrations with electric vehicle manufacturers.
Within the mutual ownership tier, Economical Insurance and Wawanesa exemplify policyholder-governed structures that compete through rural and agricultural vehicle segment specialization. Intact Insurance occupies a position as the scale-driven archetype leveraging proprietary telematics infrastructure for direct channel refinement. Desjardins General Insurance Group represents the integrated financial conglomerate model through Quebec-centric banking-insurance cross-selling networks.
| Leading Market Players |
|---|
| Aviva Canada |
| Economical Insurance |
| Intact Insurance |
| Wawanesa |
| The Personal |
| The Co-operators |
| TD Insurance |
| belairdirect |
| Desjardins General Insurance Group |
| Others |
Value Chain & Pricing Dynamics
Toronto's concentration of actuarial talent and telematics infrastructure anchors pricing power for carriers deploying usage-based models, while provincial rate boards in Ontario and British Columbia constrain premium autonomy through prior-approval mechanisms that compress filing-to-market timelines.
Pricing Analysis
Ontario's Greater Toronto Area exhibits wider premium spreads than prairie provinces due to elevated collision frequency and litigation exposure. Pricing stratifies across comprehensive, liability, and no-fault tiers with differentiation driven by vehicle replacement valuations and territorial risk ratings. Cost compression in standard personal auto lines is intensifying because telematics-enabled insurers capture behavioral data that collapses traditional demographic proxies. Fleet operators show least price sensitivity due to experience-rated structures, while non-standard residual market participants face highest effective rates.
Supply Chain Analysis
Canada's federal privacy framework and provincial data localization requirements restrict cross-border telematics data flows, limiting carrier access to global risk pooling infrastructure. Supply concentration rests on domestic technology partnerships in Ontario and Quebec, with reinsurance capacity drawing from London and Bermuda markets for catastrophic weather exposure. Raw material dependencies include cloud computing infrastructure, IoT sensor hardware, and predictive modeling software licenses. Single-source vulnerability sits with concentrated reinsurance capacity for British Columbia's Fraser Valley catastrophe exposure. Distribution runs through broker networks for commercial accounts and direct channels for standard personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from embedded insurance partnerships where electric vehicle manufacturers integrate coverage at point-of-sale, bypassing traditional carrier distribution and capturing first-mover relationships with new vehicle buyers.
For Market Incumbents: Pre-empt embedded insurance displacement by securing API partnerships with vehicle manufacturers before point-of-sale integration solidifies. Acquire telematics data assets in Ontario and British Columbia to refine risk segmentation ahead of autonomous vehicle liability framework finalization. Vertical integration into claims prevention services through edge computing networks reinforces differentiation against manufacturer-captive insurers.
For New Entrants and Emerging Players: Establish a beachhead in subscription-based mobility coverage for ride-share and car-sharing participants in British Columbia's dense urban corridors where vehicle ownership declines fastest among younger demographics. Target parametric weather products for Saskatchewan agricultural equipment fleets as index-based hail and flood coverage bypasses traditional claims adjustment costs. Deploy mobile-first platforms that activate coverage by the hour to capture episodic protection demand.
For Investors and Strategic Acquirers: Long-term, this sits as a data-asset play because telematics infrastructure and proprietary risk segmentation capabilities compound competitive moats as autonomous vehicle liability redistributes value between manufacturers and insurers. Target carriers with established IoT device integrations and provincial regulatory relationships. Watch federal transport safety consultations on software failure liability allocation as the inflection signal for coverage white space expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Partnership | Proprietary driving behavior capture enables usage-based pricing refinement against territorial rating models. |
| Embedded Insurance API Integration | Point-of-sale coverage activation with electric vehicle manufacturers secures first-mover buyer relationships. |
| Parametric Product Development | Satellite-triggered payouts for agricultural weather risks bypass traditional claims adjustment infrastructure costs. |
| Autonomous Vehicle Liability Framework Positioning | Federal transport safety consultations define software failure coverage boundaries between carriers and manufacturers. |
| Cross-Provincial Data Harmonization | Quebec's civil law tradition complicates national telematics pooling; resolution unlocks segmentation scale advantages. |
Study Parameters
The analysis maps liability coverage, comprehensive coverage, collision coverage, and no-fault coverage segments, each validated through primary interviews with underwriting executives, actuarial directors, broker network managers, and provincial regulatory affairs officers, combined with secondary validation through Office of the Superintendent of Financial Institutions capital adequacy filings, provincial rate board premium approval databases, Health Canada injury protocol alignments, and federal transport safety consultation records, with bottom-up policy volume estimates triangulated against top-down carrier premium disclosures.
Forecast assumptions hold fixed the current provincial regulatory frameworks and federal zero-emission vehicle mandate trajectories while varying telematics adoption rates, autonomous vehicle deployment timelines, and climate loss severity parameters across the analysis window. Segmentation dimensions modeled include policy type, customer tier, distribution channel, coverage limit configuration, and provincial regulatory cluster. CAGRs derive from actuarial reserve growth projections and premium filing momentum, with inputs from vehicle electrification penetration curves and commercial fleet expansion patterns in Alberta's energy corridors.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting insurer investment income or reinsurance pricing cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and catastrophic weather frequency. Material shifts in federal autonomous vehicle liability frameworks or provincial no-fault expansion decisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
Indonesia Motor Insurance Market