
 Japan Car Insurance Market | 2026-2036
Japan Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Car Insurance Market Insights
Modular policy bundling is expanding across the Japan car insurance landscape as insurers unbundle traditional comprehensive packages into selectable coverage components. Tokio Marine & Nichido Fire Insurance Co., Ltd. leverages its extensive agency network to sustain dominance in corporate fleet accounts. Sompo Japan Insurance Inc. differentiates through digital-first distribution and telematics integration. Mitsui Sumitomo Insurance Co., Ltd. anchors its position with advanced risk-assessment capabilities and long-standing relationships with Japan's automotive manufacturers.
Japan car insurance constitutes a regulated financial product providing indemnity against vehicle damage, third-party liability, and personal injury resulting from traffic incidents, with policy terms typically structured around standardized premium calculation tables incorporating vehicle type, driver history, and regional risk coefficients. The primary purpose centers on risk transfer for vehicle owners while ensuring statutory liability compliance under Japan's compulsory automobile liability insurance system. Comprehensive coverage leads policy type segmentation due to its bundling of collision, theft, and liability protections into single contracts. Online distribution channels represent the fastest-growing segment as Rakuten General Insurance Co., Ltd. and SBI Insurance Co., Ltd. compete on platform convenience and price transparency. Corporate customer segments command concentrated margin pools given fleet scale and multi-year contract structures.
PMDA oversight intersects with Japan car insurance through medical cost benchmarks embedded in personal accident coverage calculations, while METI guidelines shape digital insurance platform standards and data governance. Japan's FSA enforces solvency requirements and consumer protection rules that dictate product design and sales conduct across all licensed insurers. Stakeholders must monitor evolving telematics data privacy standards and autonomous vehicle liability frameworks as these technologies redefine risk attribution and premium modeling.
Market Dynamics
Japan's Ministry of Land, Infrastructure, Transport and Tourism is tightening safety mandates for commercial vehicles, forcing fleet operators to expand coverage purchases and accelerating demand for telematics-integrated policies across corporate and individual segments.
Growth Catalysts
- Commercial Vehicle Safety Mandates:Japan's Ministry of Land, Infrastructure, Transport and Tourism regulations are compelling fleet operators to purchase expanded coverage, directly lifting policy volumes in the commercial segment.
- Telematics Integration:Usage-based insurance models leveraging real-time driving data are attracting corporate buyers seeking premium optimization through verified risk profiles.
- Tokyo Urban Density:The capital's concentrated vehicle population creates natural demand clusters for digital-first distribution and personalized coverage components.
Market Restraints
- Regulatory Friction from METI Guidelines:Japan's Ministry of Economy, Trade and Industry standards for digital insurance platforms impose compliance costs that constrain smaller entrants' platform development timelines.
- Input Cost Volatility in Medical Benchmarking:PMDA medical cost benchmarks embedded in personal accident coverage create premium calculation uncertainty when healthcare inflation diverges from actuarial assumptions.
- Supply Concentration in Agency Networks:Established insurers' captive distribution channels limit price transparency and compress margin available to direct-to-consumer challengers.
Strategic Opportunities
- Autonomous Vehicle Liability Frameworks:Emerging regulatory definitions of fault attribution in self-driving incidents will create first-mover advantages for insurers developing specialized coverage products.
- Telematics-Privacy Convergence:Japan's evolving data governance standards for driving behavior data present white space for insurers offering privacy-guaranteed usage-based models.
- Modular Policy Unbundling:Selectable coverage components allow insurers to capture previously unserved segments seeking stripped-down liability-only or theft-specific protection.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of professionals skilled in telematics data modeling and autonomous vehicle risk assessment constrains product development velocity.
- Legacy System Integration Complexity:Incumbent insurers' core policy administration platforms require substantial reconfiguration to support real-time premium adjustment from connected vehicle feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Car Insurance Market |
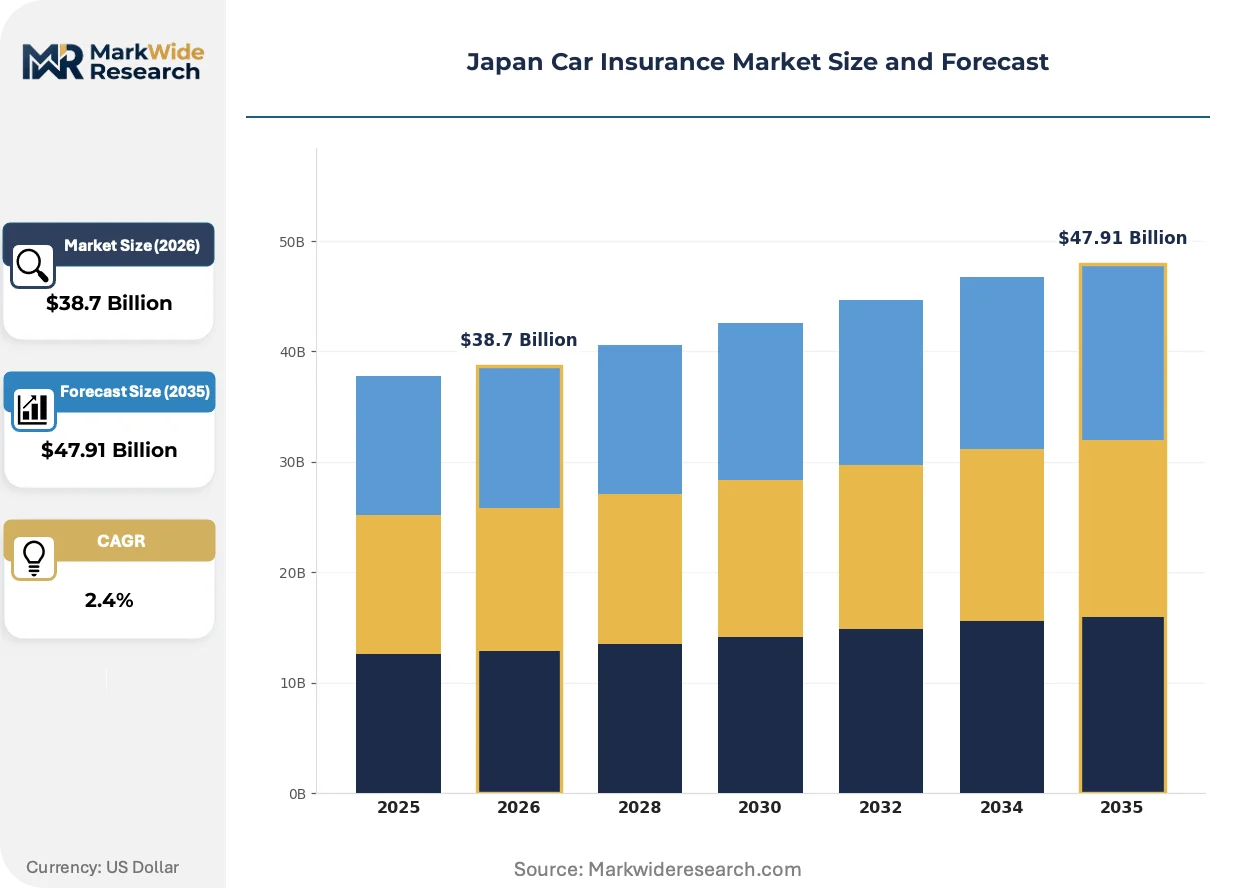
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $47.91 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Third Party, Comprehensive, Fire and Theft, Personal Accident Customer Segment: Individual, Corporate, Fleet, Commercial Coverage Type: Liability Coverage, Collision Coverage, Comprehensive Coverage, Uninsured Motorist Coverage Distribution Channel: Online, Agents, Brokers, Direct Sales |
| Companies Covered | Tokio Marine & Nichido Fire Insurance Co., Ltd., Sompo Japan Insurance Inc., Mitsui Sumitomo Insurance Co., Ltd., Aioi Nissay Dowa Insurance Co., Ltd., Sony Assurance Inc., SBI Insurance Co., Ltd., Rakuten General Insurance Co., Ltd., Mitsui Direct General Insurance Co., Ltd., AXA General Insurance Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Car Insurance Market Trends and Innovations
Digital distribution platforms and connected vehicle data streams are fundamentally restructuring how policies are priced, sold, and serviced across Japan's insurance landscape.
Telematics-integrated underwriting is overtaking traditional risk-pooling methods in commercial fleet segments. Corporate buyers with large vehicle deployments are adopting real-time monitoring systems that transmit driving behavior data directly to insurers. This technology is compressing premium variance between high-performing and average-risk fleets, forcing standard insurers to develop comparable data capabilities or cede market position.
METI guidelines on digital insurance platform standards are reshaping data governance requirements across the industry. Japan's Ministry of Economy, Trade and Industry mandates now specify minimum security protocols for customer information handling and cross-platform data portability. Online distribution channels are most affected, with Rakuten General Insurance and SBI Insurance accelerating platform investments to maintain compliance leadership.
Corporate procurement of multi-year fleet contracts is fragmenting into annual renewable structures with embedded usage-based adjustments. Large fleet operators are negotiating shorter terms to retain flexibility as vehicle electrification and autonomous technology alter risk profiles. This pattern is most visible among logistics and delivery companies operating dense urban routes in Osaka and Nagoya metropolitan corridors.
Japan Car Insurance Market Segmentation
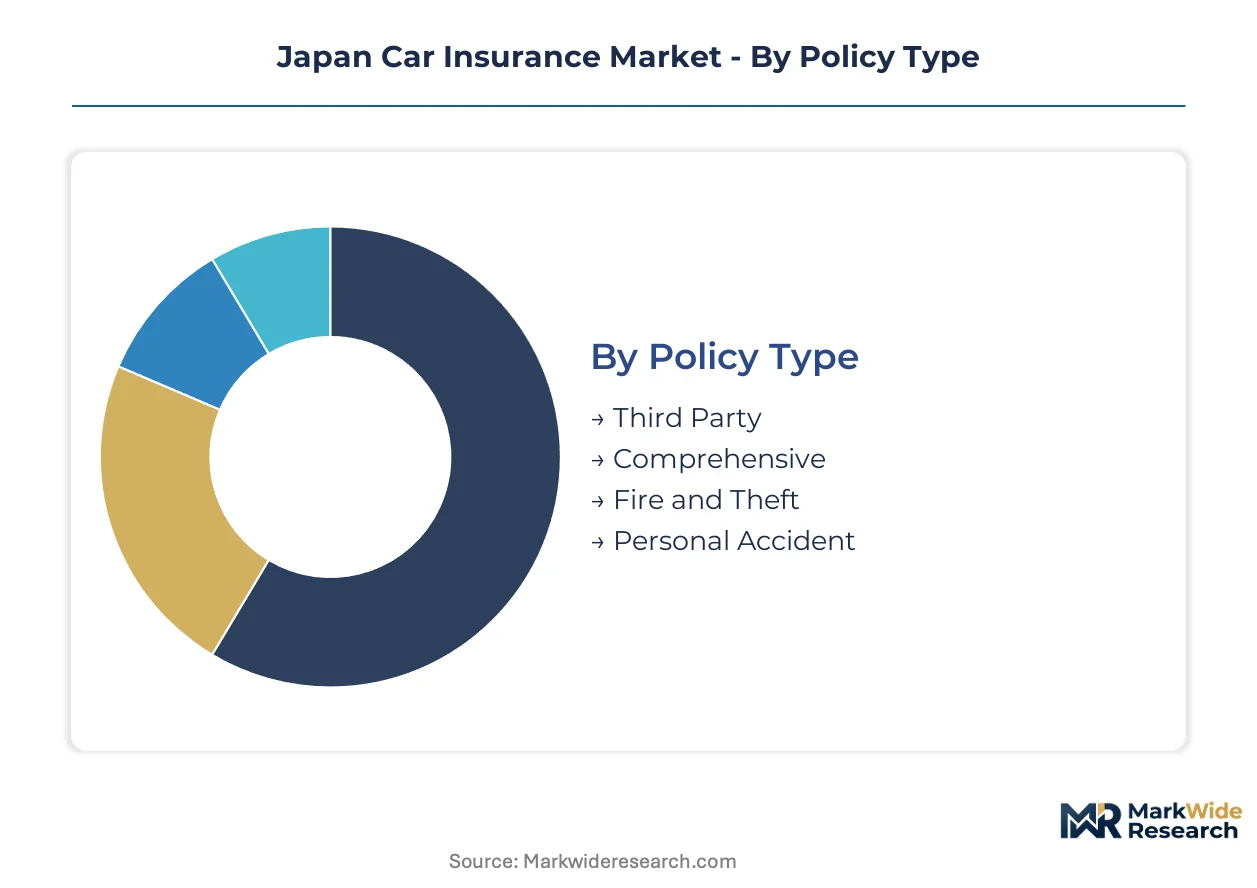
Japan's car insurance market fragments along four structural dimensions that determine pricing precision, distribution economics, and regulatory exposure. Each segmentation axis reveals distinct margin pools and competitive intensity patterns across Tokyo's dense urban corridors and regional prefectures.
Policy Type:
The customization-to-standardization spectrum stretches from mandatory minimum coverage to fully configurable bundled protection, with regulatory mandates anchoring the standardized end and optional riders extending toward personalization.
- Third Party:Statutory coverage satisfying Japan's compulsory automobile liability insurance requirements. Demand concentrates among individual vehicle owners in rural prefectures where premium minimization overrides protection breadth, constrained by MLIT enforcement of minimum coverage floors.
- Comprehensive:Bundled collision, theft, and liability protection within single contracts. Corporate fleet operators in Osaka and Nagoya metropolitan corridors drive concentration, seeking administrative simplicity and multi-vehicle discount structures.
- Fire and Theft:Named-peril coverage excluding collision damage. Compact vehicle owners in Tokyo's dense parking environments favor this stripped-down option.
- Personal Accident:Medical cost indemnity tied to PMDA treatment benchmarks. Motorcycle commuters and commercial drivers populate this segment.
Most installed capacity flows through Comprehensive. Expansion is steepest in Personal Accident as medical cost inflation outpaces standard liability pricing.
Customer Segment:
Volume concentration tilts toward individual purchasers while margin density clusters in institutional accounts with multi-year contract structures and telematics integration potential.
- Individual:Single-vehicle owners purchasing annual renewable policies. Tokyo's 23 wards generate disproportionate quote volume through digital channels, with Rakuten General Insurance and SBI Insurance capturing platform-native demographics.
- Corporate:Multi-vehicle entities with centralized procurement. Fleet scale in Aichi Prefecture's automotive supplier clusters supports negotiated rate structures and embedded risk management services.
- Fleet:Dedicated vehicle pools with real-time monitoring infrastructure. Logistics operators along the Tomei Expressway corridor adopt usage-based adjustments fastest.
- Commercial:Mixed-use vehicles spanning personal and business operation. Sole proprietors in Fukuoka and Sapporo metropolitan areas populate this ambiguous classification.
Corporate and Fleet segments command concentrated margin pools. Individual purchasers are expanding most quickly through smartphone-native distribution platforms.
Coverage Type:
Cost tier stratification separates statutory minimums from premium protection layers, with liability coverage anchoring entry pricing and comprehensive options capturing upgrade revenue.
- Liability Coverage:Third-party bodily injury and property damage protection. Mandatory status ensures universal penetration across all prefectures.
- Collision Coverage:Own-vehicle damage indemnity regardless of fault. Leased vehicle contracts in Tokyo and Osaka mandate this protection tier.
- Comprehensive Coverage:All-risk protection bundling collision, theft, fire, and natural disaster exposure. High-value vehicle owners in premium Tokyo districts select this tier.
- Uninsured Motorist Coverage:Protection against at-fault parties lacking adequate liability limits. Rural Hokkaido and Tohoku regions show elevated attachment rates given higher uninsured driver incidence.
Liability Coverage carries universal installation. Comprehensive Coverage is gaining share fastest as vehicle replacement costs climb and lender requirements tighten.
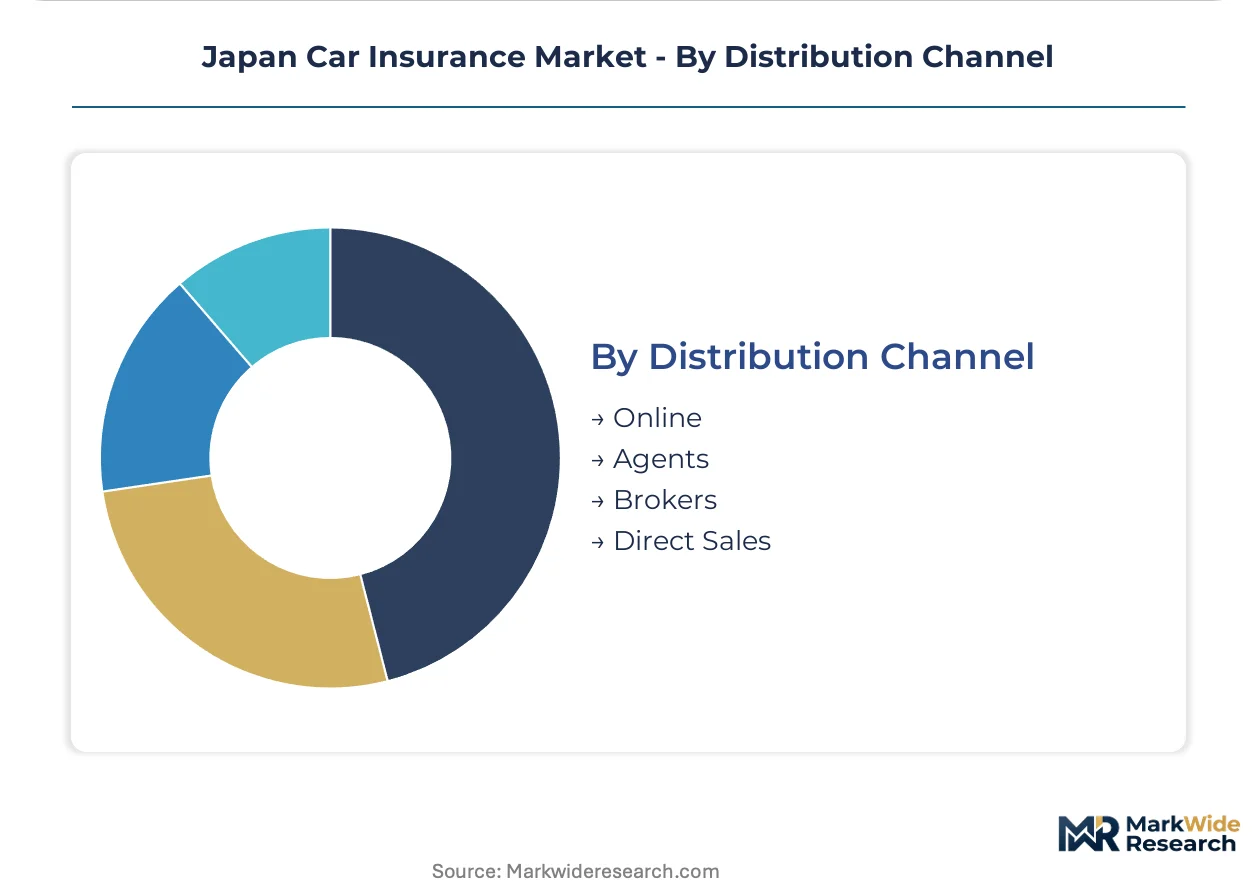
Distribution Channel:
Customer type and geography dictate channel selection, with urban density favoring digital platforms and relationship-heavy commercial accounts sustaining agency networks.
- Online:Platform-based quote comparison and policy issuance. METI digital governance standards shape competitive dynamics, with compliance investments separating viable entrants from marginal players.
- Agents:Captive and independent representatives with localized relationship networks. Tokio Marine & Nichido Fire Insurance leverages this channel for corporate fleet dominance in Nagoya industrial zones.
- Brokers:Independent intermediaries accessing multiple insurer panels. Mid-market commercial accounts in Kobe and Hiroshima metropolitan areas favor broker-facilitated coverage structuring.
- Direct Sales:Insurer-employed representatives bypassing intermediary commissions. Sompo Japan Insurance deploys direct channels for telematics-integrated policy conversion.
Agent networks retain largest installed capacity. Online channels are expanding most quickly as smartphone penetration and price transparency expectations reshape purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's compulsory automobile liability insurance system originated in 1955, establishing the foundational regulatory architecture that governs coverage mandates today. The industry scaled through post-war motorization waves, with Tokyo's metropolitan density becoming the primary laboratory for product innovation and distribution experimentation.
Kanto/Tokyo
Telematics-integrated policies concentrate in Tokyo's 23 wards, where smartphone-native distribution platforms capture individual purchasers seeking usage-based premium optimization. METI digital governance standards shape platform development requirements for online insurers operating in this corridor. Corporate fleet operators along the Keihin industrial belt negotiate multi-year contracts with embedded risk management services.
Kansai/Osaka
Comprehensive coverage bundles dominate corporate procurement in Osaka and Kyoto prefectures, where automotive supplier clusters drive negotiated rate structures for multi-vehicle accounts. MLIT commercial vehicle safety mandates accelerate telematics adoption among logistics operators. The Osaka Bay maritime-industrial zone sustains demand for mixed-use commercial policies spanning personal and business vehicle operation.
Chubu/Nagoya
Aichi Prefecture's automotive manufacturing concentration anchors corporate fleet insurance demand, with captive agency networks maintaining relationships with tier-one suppliers. Tokio Marine & Nichido Fire Insurance leverages localized representation to sustain dominance in industrial accounts. The Tomei Expressway corridor generates concentrated usage-based policy experimentation among long-haul logistics operators.
Kyushu
Fukuoka's metropolitan expansion drives individual policy growth through digital channels, with price-sensitive purchasers favoring stripped-down liability coverage. Rural prefectures in Kyushu exhibit elevated uninsured motorist coverage attachment rates. Commercial mixed-use vehicles populate ambiguous classification segments among sole proprietors in regional construction and agriculture sectors.
Hokkaido
Severe weather exposure and sparse road infrastructure elevate comprehensive coverage penetration in Hokkaido's urban centers. Higher uninsured driver incidence in rural sub-regions drives demand for supplemental motorist protection. Sapporo's metropolitan insurance market mirrors national digital distribution trends while retaining stronger agency network presence than southern prefectures.
Japan Car Insurance Market Competitive Landscape
The competitive structure tilts toward established domestic insurers with captive distribution networks. Three strategic archetypes dominate: traditional insurers with agency infrastructure, digital-native challengers with platform-based distribution, and automotive-aligned underwriters with manufacturer relationships. Competitive moves concentrate on telematics capability acquisition and modular product unbundling rather than price-driven displacement.
Among established domestic insurers, Tokio Marine & Nichido Fire Insurance Co., Ltd. and Sompo Japan Insurance Inc. exemplify the agency-network archetype, occupying positions sustained by corporate fleet relationships and localized representation. Mitsui Sumitomo Insurance Co., Ltd. anchors the manufacturer-aligned tier. Digital challengers Rakuten General Insurance Co., Ltd. and SBI Insurance Co., Ltd. represent platform-native distribution, competing on quote transparency and smartphone-native purchasing workflows. Sony Assurance Inc. occupies a hybrid position bridging technology infrastructure and insurance product design.
| Leading Market Players |
|---|
| Tokio Marine & Nichido Fire Insurance Co., Ltd. |
| Sompo Japan Insurance Inc. |
| Mitsui Sumitomo Insurance Co., Ltd. |
| Aioi Nissay Dowa Insurance Co., Ltd. |
| Sony Assurance Inc. |
| SBI Insurance Co., Ltd. |
| Rakuten General Insurance Co., Ltd. |
| Mitsui Direct General Insurance Co., Ltd. |
| AXA General Insurance Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Fleet operators' procurement of telematics-integrated policies is forcing insurers to restructure distribution economics and compress legacy commission structures. This demand-side shift concentrates pricing power with data-enabled underwriters while squeezing traditional agency-reliant players.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Japan's car insurance landscape, with premium tiers attaching manufacturer-aligned risk assessment and standard tiers competing on digital distribution efficiency. Price differentiation rests on telematics verification status and fleet scale volume discounts. Cost compression in economy tiers is intensifying because direct-to-consumer challengers strip out intermediary commissions. Individual purchasers in Tokyo's 23 wards exhibit highest price sensitivity, while corporate fleet accounts in Aichi Prefecture prioritize risk management bundling over premium minimization.
Supply Chain Analysis
Direct-to-fleet channels handle hyperscale buyer demand through embedded telematics partnerships, while agency networks retain individual and small commercial accounts. Distribution runs through Japan's domestic insurer infrastructure, with captive agency relationships concentrated in Nagoya and Osaka industrial corridors. Raw material dependencies include connected vehicle data feeds, cloud computing infrastructure for real-time premium adjustment, and PMDA medical cost benchmarks for personal accident coverage. Single-source vulnerability in telematics platform providers creates concentration risk as insurers hinge on limited specialized technology vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's car insurance market offers margin expansion through telematics-enabled risk selection and modular product unbundling that captures previously unserved segments. Cost-down drivers in digital distribution and data-driven underwriting support premium-tier migration.
For Market Incumbents: To counter digital-native challengers eroding individual policy volumes, Tokio Marine and Sompo Japan must deepen captive agency control in Nagoya and Osaka fleet corridors while accelerating legacy core system modernization to support real-time premium adjustment from connected vehicle feeds. For New Entrants and Emerging Players: Stripped-down liability-only coverage for price-sensitive individual purchasers in Fukuoka and Sapporo represents the most penetrable white space. Privacy-guaranteed usage-based models targeting data-wary urban commuters offer differentiated positioning against incumbent telematics offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with automotive-aligned underwriters possessing manufacturer data partnerships and embedded distribution through dealership channels. Long-term viability favors insurers with demonstrated telematics actuarial capability and modular product architecture. The signal to watch is MLIT regulatory guidance on autonomous vehicle liability attribution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time driving data feeds from Toyota and Honda connected vehicles enable dynamic premium adjustment. |
| Modular Product Unbundling | Selectable coverage components capture sole proprietors in Kyushu seeking stripped-down theft protection. |
| Agency Network Digitization | METI-compliant digital platforms preserve Tokio Marine's corporate fleet dominance in Chubu manufacturing clusters. |
| Autonomous Vehicle Liability Product Development | First-mover positioning on MLIT fault attribution frameworks captures emerging self-driving risk pools. |
| Privacy-Guaranteed Usage-Based Model Launch | Data governance differentiation attracts smartphone-native demographics in Tokyo's 23 wards. |
Research Methodology
Coverage spans Japan's Kanto, Kansai, Chubu, Kyushu, and Hokkaido regions, with primary inputs from each territory combined with secondary validation. Interviews with insurance product development executives, fleet procurement managers, telematics platform engineers, and METI regulatory affairs specialists informed demand-side and supply-side dynamics. Secondary sources included FSA solvency filings, MLIT commercial vehicle safety mandate documentation, PMDA medical cost benchmark publications, and insurer annual reports. Bottom-up policy volume estimates triangulated against top-down premium pool calculations derived from regulatory filings.
Segmentation-level modeling addressed policy type, customer segment, coverage tier, and distribution channel dimensions across the projection horizon. Vehicle class, propulsion architecture, and fleet scale variables shaped premium and volume outputs. CAGRs were derived from trend extrapolation anchored to historical regulatory filing data and scenario-weighted telematics adoption curves. Forecast inputs incorporated MLIT enforcement intensity assumptions and PMDA medical inflation trajectories.
Underlying measurement precision varies by segment; corporate fleet and comprehensive coverage categories carry tighter precision than emerging personal accident and usage-based policy segments due to established reporting requirements. Forecasts reflect documented assumptions regarding telematics penetration rates and autonomous vehicle regulatory timelines. Periodic stress-testing of base assumptions is recommended given potential revision from METI data governance standard changes or MLIT liability framework updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Japan Motor Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market