
 Automotive Insurance Market | 2026-2036
Automotive Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Insurance Market Analysis
Actuarial talent scarcity is reorganizing how carriers price risk and deploy capital across product lines. Progressive leverages proprietary driving data to sustain pricing precision in usage-based segments. State Farm anchors its market presence through captive agency networks that control local distribution density. Allianz competes on cross-border fleet expertise, extending its reach into multinational corporate accounts.
Automotive insurance constitutes a risk-transfer contract indemnifying policyholders against financial loss from vehicle damage, bodily injury, or third-party liability, with premiums calibrated through statistical mortality tables, telematics-derived behavioral scores, and repair cost indices. Its primary commercial purpose lies in restoring capital position after stochastic loss events while enabling vehicle ownership and fleet operations. Liability coverage dominates premium volume in mature markets where statutory minimums mandate purchase, while usage-based and pay-as-you-drive policy types capture the fastest expansion as connected vehicle data streams enable dynamic pricing. Insurtechs are reshaping margin pools by stripping acquisition costs from traditional broker channels and embedding policies at point-of-sale through OEM partnerships.
The National Association of Insurance Commissioners coordinates state-level rate filing standards across the United States, while the EU AI Act imposes algorithmic accountability on automated underwriting systems in Europe. These frameworks shape product design by mandating explainability in pricing models and restricting granular demographic segmentation. Stakeholders must monitor regulatory divergence between jurisdictions that favor telematics innovation and those imposing strict data privacy limits on driving behavior collection.
Market Dynamics
Telematics-enabled underwriting is compressing traditional actuarial cycles and forcing carriers to rebuild pricing infrastructure around real-time behavioral data streams rather than retrospective loss tables.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for automated claims processing are accelerating carrier investment in explainable pricing models.
- Embedded OEM partnerships:Electric vehicle manufacturers are integrating insurance at point-of-sale, stripping broker acquisition costs from distribution economics.
- Fleet telematics penetration:Commercial operators in the United States are expanding coverage purchases as usage-based risk assessment enables dynamic premium calibration.
Market Restraints
- Actuarial talent scarcity:Specialized pricing expertise concentrates among legacy carriers, constraining new entrants' ability to model telematics-derived risk scores accurately.
- GDPR data friction:European privacy limits on driving behavior collection restrict granular segmentation that telematics underwriting requires.
- Repair cost volatility:Advanced driver-assistance system sensors and electric vehicle battery packs are inflating severity distributions unpredictably.
Strategic Opportunities
- Underpenetrated commercial fleets in India:Regulatory push for mandatory third-party liability creates whitespace for telematics-enabled fleet products.
- Cross-border corporate accounts:Multinational risk managers seek unified coverage spanning multiple jurisdictions with consistent data standards.
- Usage-based policy convergence:Pay-as-you-drive models are merging with connected vehicle platforms to enable real-time premium adjustment.
Industry Challenges
- Legacy system integration complexity:Incumbent policy administration platforms require costly rearchitecture to ingest streaming telematics data.
- Model governance staffing gaps:EU AI Act accountability mandates demand personnel who bridge actuarial science with algorithmic auditing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Insurance Market |
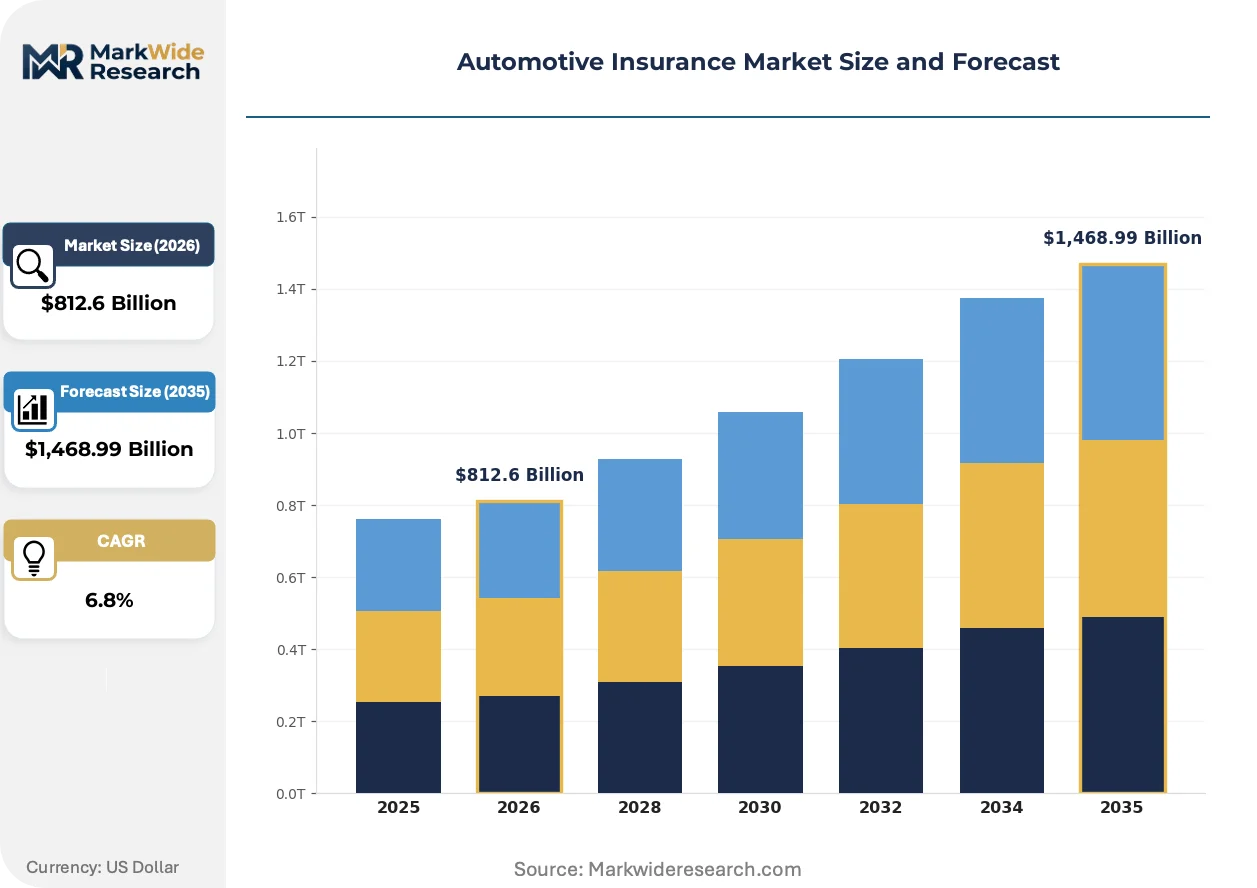
| Market Size in 2026 | $812.6 Billion |
| Market Size in 2035 | $1,468.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Liability, Collision, Comprehensive, Personal Injury Protection Policy Type: Standard, Usage-Based, Pay-As-You-Drive, Fleet Customer Segment: Individual Owners, Small Businesses, Corporate Fleets, Rental Services Insurer Type: Direct Writers, Brokers, Insurtechs, Traditional Insurers |
| Companies Covered | State Farm, Progressive, GEICO, Allstate, USAA, Liberty Mutual, Farmers, Travelers, Allianz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Insurance Market Emerging Trajectories
Real-time data infrastructure is displacing static rating factors across personal and commercial lines, compressing the interval between risk exposure measurement and price adjustment.
Machine learning models trained on telematics-derived behavioral signals are displacing traditional mortality table approaches in personal auto pricing. Mid-size carriers lacking proprietary data assets are licensing third-party driving scores to remain competitive. The structural consequence is margin compression for insurers dependent on undifferentiated risk pools.
The EU AI Act imposes documentation and human oversight requirements on automated underwriting systems deployed in Europe. Carriers must maintain technical files demonstrating algorithmic fairness and enable supervisory authority audits. Personal lines segments with high automation penetration are absorbing compliance costs through slower product iteration cycles.
Fleet procurement patterns are consolidating around integrated risk management platforms that bundle telematics hardware with coverage. Traditional broker channels face disintermediation as direct OEM and fleet management system integrations capture placement decisions. This shift is most visible in the United States where large commercial operators centralize vendor relationships through procurement departments rather than distributed agent networks.
Automotive Insurance Market Segmentation
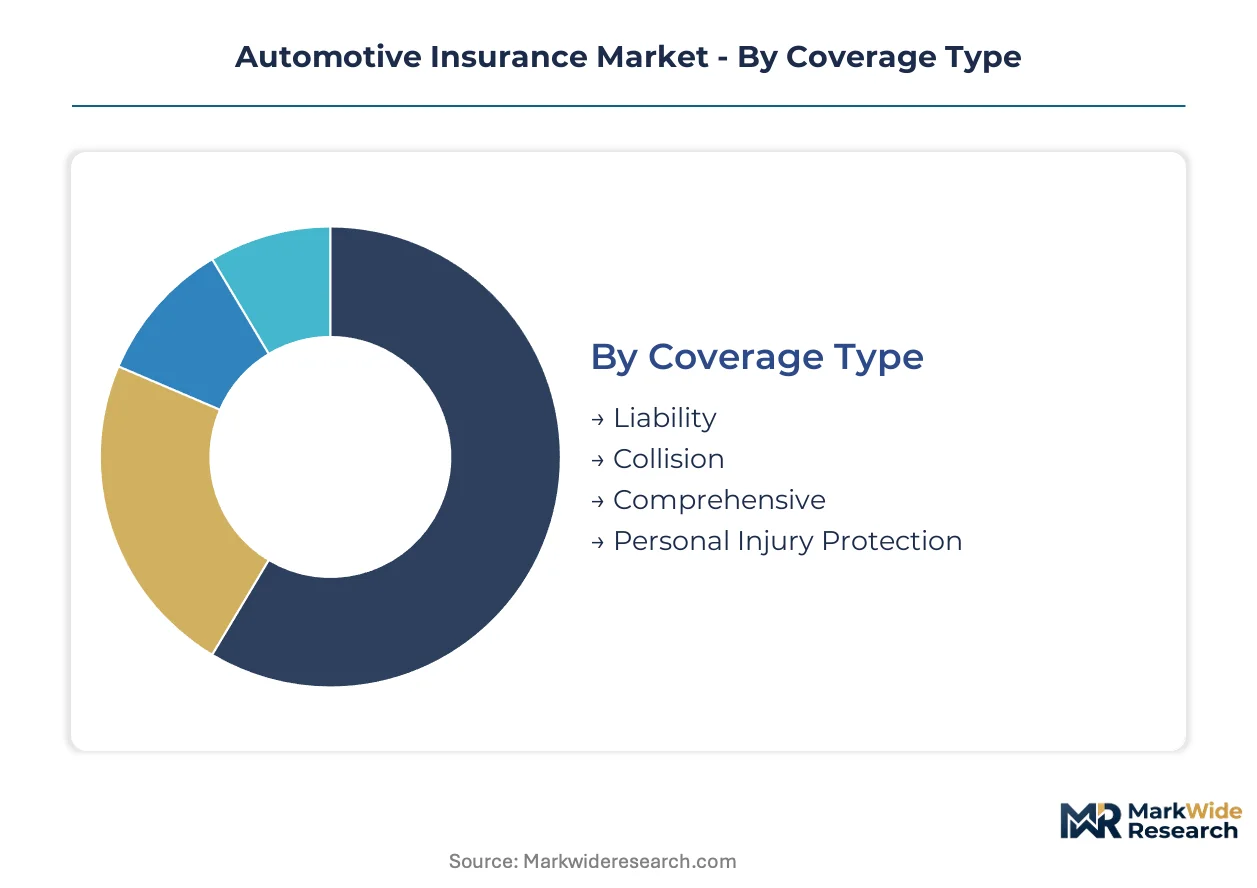
Segmentation in automotive insurance determines how capital flows between risk pools and which distribution channels capture margin. Telematics penetration and regulatory frameworks reshape which segments expand fastest.
Coverage Type:
Liability coverage commands the deepest margin pools across mature markets where statutory minimums mandate purchase.
- Liability:Statutorily mandated coverage indemnifying third-party bodily injury and property damage. Premium volume concentrates in the United States where state minimums drive universal purchase, though rate adequacy pressures mount from litigation cost inflation.
- Collision:Physical damage coverage for policyholder vehicles regardless of fault. Demand clusters among financed vehicle owners where lenders require protection, with severity distributions shifting unpredictably as advanced driver-assistance system sensors inflate repair costs.
- Comprehensive:Non-collision peril coverage spanning theft, vandalism, and weather damage. Theft risk algorithms now incorporate vehicle tracking data, narrowing loss differentials between urban and rural geographies.
- Personal Injury Protection:No-fault medical and wage-loss coverage operating in select US jurisdictions. Regulatory fragmentation limits carrier appetite, with no-fault states experiencing fraud-driven premium spirals.
The dominant share belongs to Liability, while Collision is closing the gap fastest as vehicle complexity drives financed-vehicle coverage requirements.
Policy Type:
Usage-based products concentrate growth investment as telematics infrastructure matures and acquisition economics improve.
- Standard:Fixed-premium annual contracts priced through retrospective loss tables and demographic proxies. Retention rates exceed telematics alternatives, though pricing precision lags real-time behavioral alternatives.
- Usage-Based:Dynamic premium calibration through continuous driving behavior monitoring. Expansion accelerates in the United States where Progressive and State Farm deploy proprietary data assets, compressing traditional actuarial cycles.
- Pay-As-You-Drive:Mileage-linked pricing with periodic odometer verification or GPS logging. Low-mileage urban owners in European cities favor this structure, though GDPR friction constrains granular segmentation.
- Fleet:Consolidated coverage for commercial vehicle pools with centralized risk management. Procurement centralization through fleet management systems is stripping broker intermediation from placement economics.
Standard policies retain volume leadership, yet Usage-Based offerings are expanding most quickly as connected vehicle platforms enable seamless data integration.
Customer Segment:
Corporate fleet procurement patterns determine where distribution investment flows, with centralized vendor relationships favoring direct carrier partnerships.
- Individual Owners:Personal vehicle coverage purchased through agent networks or direct channels. Price sensitivity dominates retention, with switching costs eroding as comparison platforms proliferate.
- Small Businesses:Commercial auto coverage for proprietors and light-duty operators. Underwriting complexity exceeds personal lines, yet premium scale falls below dedicated fleet products.
- Corporate Fleets:Large-scale commercial operators with centralized risk management functions. Telematics-enabled loss control programs drive placement decisions, with integrated platform vendors capturing vendor consolidation.
- Rental Services:Short-term vehicle fleet coverage with high turnover exposure. Loss frequency challenges persist in urban operations, though usage-based structures align premium with actual utilization.
Individual Owners maintain the largest risk pool, while Corporate Fleets are gaining share fastest as telematics penetration deepens commercial underwriting sophistication.
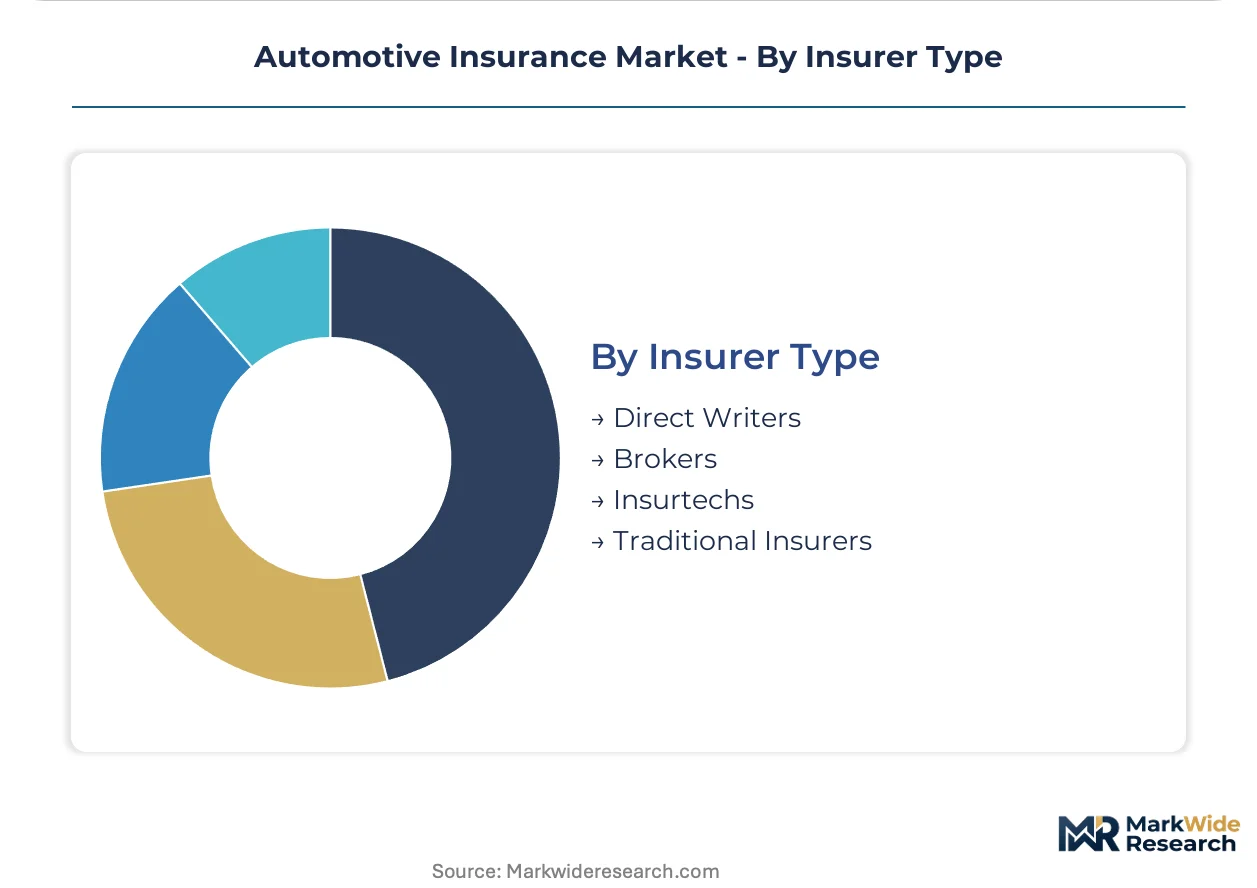
Insurer Type:
Channel economics fragment as embedded partnerships and direct platforms capture premium flow from traditional intermediation.
- Direct Writers:Carriers selling coverage through proprietary channels without independent agent intermediation. GEICO and Progressive in the United States demonstrate scale advantages in customer acquisition cost efficiency.
- Brokers:Independent intermediaries placing coverage across multiple carrier panels. Commission compression threatens economics as embedded point-of-sale alternatives displace traditional placement.
- Insurtechs:Technology-native carriers leveraging digital distribution and algorithmic underwriting. Lemonade and Root in the United States strip legacy infrastructure costs, though profitability remains elusive.
- Traditional Insurers:Established carriers with legacy policy administration platforms and captive agency networks. State Farm's local distribution density anchors retention, though system rearchitecture demands strain capital deployment.
Traditional Insurers hold the dominant position, though Insurtechs are climbing the fastest as embedded OEM partnerships reshape customer acquisition pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telematics penetration varies sharply by geography. United States carriers leverage proprietary driving data for dynamic pricing, while European markets grapple with GDPR constraints on behavioral data collection. Asian markets show divergent patterns between mature regulatory frameworks and emerging mandatory coverage regimes.
United States
Embedded insurance partnerships with electric vehicle manufacturers are accelerating policy issuance at point-of-sale. State-level rate filing standards coordinated by the National Association of Insurance Commissioners create regulatory fragmentation that favors carriers with compliance scale. Progressive and State Farm dominate usage-based segments through proprietary telematics platforms deployed across Texas, California, and Florida metropolitan corridors.
Germany
Cross-border fleet expertise concentrates premium volume among multinational corporate accounts seeking unified coverage standards. The KBA enforces strict vehicle-type approval protocols that influence insurance risk classification for imported electric vehicle models. Munich and Frankfurt anchor the continental reinsurance hub that retrocedes automotive risk across European jurisdictions.
China
Mandatory third-party liability expansion drives premium growth as vehicle ownership penetrates inland provinces. SAMR oversight of algorithmic pricing models intensifies documentation requirements for automated underwriting systems. Shanghai and Beijing clusters host domestic insurtechs developing connected vehicle data partnerships with state-owned automotive manufacturers.
United Kingdom
Comparison platform proliferation erodes switching costs for individual owners while compressing acquisition margins across direct writers. The Financial Conduct Authority scrutinizes loyalty pricing practices that penalize long-tenured policyholders. London's Lloyd's market structures specialty coverage for autonomous vehicle trial fleets operating in Oxford and Cambridge testing zones.
India
Regulatory push for mandatory third-party liability creates whitespace for telematics-enabled fleet products targeting underpenetrated commercial operators. The Insurance Regulatory and Development Authority mandates solvency ratios that constrain new entrant capital deployment. Maharashtra and Gujarat industrial corridors concentrate commercial fleet density where usage-based risk assessment gains initial traction.
Automotive Insurance Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with direct writers commanding customer acquisition efficiency and traditional insurers defending retention through captive distribution networks. The market structure consolidates around carriers with proprietary data assets and those with local agency density. Three archetypes dominate: telematics-native underwriters, embedded partnership platforms, and legacy carriers with rearchitecting policy systems. Competitive moves concentrate on OEM integration partnerships and real-time data infrastructure deployment.
Among United States-based carriers, State Farm and Progressive exemplify divergent strategic positions within the direct-to-consumer tier. State Farm anchors market presence through captive agency networks controlling local distribution density across suburban and rural geographies. Progressive represents the telematics-native archetype, leveraging proprietary driving data to sustain pricing precision in usage-based segments. Allianz occupies a position as the cross-border specialist, extending fleet expertise into multinational corporate accounts requiring consistent coverage standards across European and Asian jurisdictions.
| Leading Market Players |
|---|
| State Farm |
| Progressive |
| GEICO |
| Allstate |
| USAA |
| Liberty Mutual |
| Farmers |
| Travelers |
| Allianz |
| Others |
Supply Flow & Price Mechanics
Embedded insurance partnerships replacing traditional broker channels simultaneously reshape distribution geography toward OEM-dominated clusters and compress acquisition cost structures that historically anchored pricing power. This substitution dynamic concentrates margin control with vehicle manufacturers while forcing carriers to rebuild pricing infrastructure around point-of-sale data integration rather than retrospective risk tables.
Pricing Analysis
Long-term fleet service contracts dominate commercial placement, while personal lines fragment between annual fixed-premium policies and real-time usage-based structures. Price differentiation hinges on telematics data granularity and repair network density, with premium tiers separating proprietary data-rich carriers from undifferentiated risk pool competitors. Pricing pressure intensifies as embedded distribution strips broker commissions from acquisition economics. Individual owners exhibit highest price sensitivity, while corporate fleets prioritize integrated loss control programs over premium minimization.
Supply Chain Analysis
Telematics hardware chokepoints in Taiwan and South Korea constrain carrier deployment timelines for usage-based products. Semiconductor components for vehicle sensors, lithium-ion battery monitoring systems, and GPS logging devices draw from concentrated East Asian manufacturing. Single-source vulnerability persists where proprietary driving score algorithms depend on exclusive data partnerships. Distribution runs through captive agency networks in suburban United States markets and direct OEM integrations in electric vehicle sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive insurance sits in early-cycle expansion as telematics penetration accelerates from novelty to infrastructure standard, with fleet procurement centralization and embedded point-of-sale partnerships driving adoption velocity beyond traditional actuarial adoption curves.
For Market Incumbents: Fortify proprietary data moats through exclusive OEM telemetry partnerships that lock out competitor access to driving behavior streams. Deepen vertical integration into fleet management software platforms to capture placement decisions before broker intermediation occurs. State Farm's captive agency density and Progressive's telematics infrastructure exemplify divergent defensive architectures against insurtech disintermediation.
For New Entrants and Emerging Players: Small-business commercial coverage gaps where underwriting complexity exceeds personal lines but premium scale falls below dedicated fleet products offer accessible white-space entry. India's underpenetrated commercial fleet market presents regulatory tailwinds through mandatory third-party liability expansion. License third-party driving scores to bypass actuarial talent scarcity while building proprietary data assets through direct telematics hardware deployment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed insurtechs that have scaled customer acquisition without achieving underwriting profitability. Long-term viability favors carriers with demonstrated telematics pricing precision and embedded partnership pipelines over pure-play digital distributors. Monitor EU AI Act compliance cost absorption as an inflection indicator separating sustainable algorithmic underwriters from regulatory-lagged competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| OEM Embedded Partnership | Progressive's point-of-sale integration with electric vehicle manufacturers strips broker acquisition costs from distribution economics. |
| Telematics Platform Deployment | Real-time driving data infrastructure enables dynamic premium calibration that compresses traditional actuarial cycles. |
| Fleet Management System Integration | Centralized procurement through vendors like Samsara captures commercial placement decisions from distributed agent networks. |
| EU AI Act Compliance Investment | Explainable pricing model documentation satisfies algorithmic accountability mandates while creating regulatory moats against undercapitalized entrants. |
| Cross-Border Fleet Expertise Expansion | Allianz's multinational corporate account capabilities leverage consistent data standards across European and Asian jurisdictions. |
Methodological Framework
The analysis maps liability coverage, collision protection, comprehensive peril coverage, and usage-based policy structures, each validated through actuarial directors, fleet procurement officers, telematics platform engineers, and insurance regulatory specialists. Primary interviews with pricing executives at direct writers and captive agency network managers cross-reference secondary validation through NAIC rate filing databases, EU AI Act technical documentation, vehicle production registration data, and SEC insurer financial disclosures. Bottom-up policy volume estimates triangulate against top-down premium pool calculations.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation across coverage type, policy structure, customer segment, and insurer channel, with propulsion architecture and telematics penetration rate as automotive-specific dimensions. CAGRs derive from fitted growth curves applied to baseline premium volumes, incorporating fleet telematics adoption velocity, embedded partnership expansion timelines, and regulatory mandate implementation schedules as industry-specific forecast inputs.
Forecasts assume regulatory continuity in United States state-level rate filing regimes and EU algorithmic accountability frameworks; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as GDPR enforcement patterns on driving behavior collection and NHTSA autonomous vehicle liability frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Japan Motor Insurance Market
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
China Motor Insurance Market