
 Malaysia Motor Insurance Market | 2026-2036
Malaysia Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
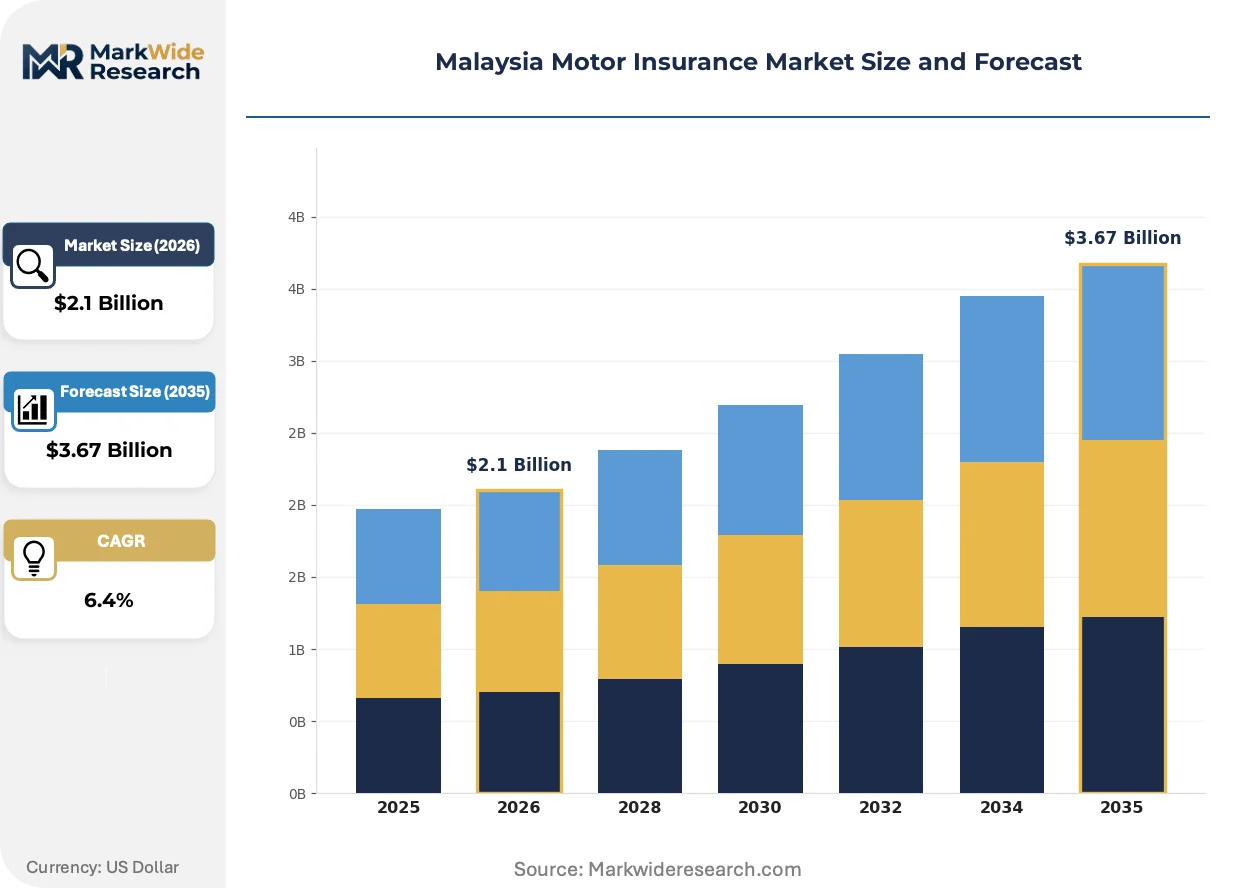
Malaysia Motor Insurance Market Outlook
Kuala Lumpur's digital insurer licensing wave is repositioning competitive dynamics in Malaysian motor coverage. MSIG Malaysia leverages its established agency network to sustain market presence across Peninsula Malaysia. Allianz Malaysia anchors its portfolio through comprehensive product specialization and direct online distribution investments. Etiqa Malaysia differentiates via takaful-compliant motor offerings that compete for Shariah-sensitive policyholders.
Motor insurance constitutes a contractual risk transfer mechanism indemnifying vehicle owners against collision, theft, fire, and third-party liability losses, with premiums calibrated through actuarial assessment of driver history, vehicle age, engine capacity, and geographic risk zones. The product generates statutory compliance utility through Road Transport Act 1987 mandatory coverage requirements while providing financial protection against asset depreciation and legal exposure. Comprehensive coverage dominates premium value pools due to broader peril inclusion and higher sum insured thresholds, while Pay-Per-Mile products attract low-mileage urban commuters in Kuala Lumpur and Penang where usage-based telematics penetration deepens. Fleet Owners represent a concentrated demand segment where brokers control placement and negotiate volume-rated terms.
Bank Negara Malaysia governs premium rating through graduated detariffication frameworks, while the Road Transport Department enforces compulsory third-party coverage at vehicle registration and renewal checkpoints. PIAM's industry code binds member insurers to claims handling standards and dispute resolution protocols that shape customer retention economics. Stakeholders must monitor BNM's evolving risk-based capital requirements and the competitive response of digitally native distributors as tariff freedom extends across more coverage tiers.
Market Dynamics
Bank Negara Malaysia's graduated detariffication framework is dismantling decades-old premium rate controls, forcing insurers to develop proprietary risk-pricing engines and recalibrate distribution economics across Peninsula Malaysia.
Growth Catalysts
- Ride-sharing fleet expansion:Grab and regional mobility platforms are scaling insured vehicle pools, creating concentrated demand for commercial motor coverage with telematics integration.
- Bank Negara Malaysia's phased liberalization:The central bank's removal of tariff floors on comprehensive coverage tiers permits risk-based pricing that rewards safer driver profiles.
- Klang Valley vehicle density:Kuala Lumpur and Selangor account for disproportionate policy volumes, concentrating distribution investment and claims infrastructure in this corridor.
Market Restraints
- Actuarial data scarcity:Limited historical loss data for newly liberalized coverage segments complicates risk-pricing model calibration.
- Third-party administrator concentration:Claims handling and repair network dependencies concentrate in legacy panel workshops, constraining cost control.
- Flood peril exposure:Peninsular Malaysia's monsoon patterns generate catastrophic loss accumulation in low-lying districts, compressing reinsurance capacity.
Strategic Opportunities
- East Malaysia penetration gap:Sabah and Sarawak exhibit lower insurance density per registered vehicle, presenting white-space distribution expansion.
- Takaful motor convergence:Shariah-compliant product architecture attracts Muslim policyholder segments underserved by conventional offerings.
- Usage-based insurance via telematics:Pay-Per-Mile products align premiums with actual kilometers driven, capturing low-mileage urban commuter segments.
Industry Challenges
- Legacy system integration:Incumbent insurers face friction connecting modern telematics platforms to decades-old policy administration systems.
- Certified actuarial talent scarcity:The profession's limited pipeline constrains pricing team expansion needed for detariffication readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Motor Insurance Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Comprehensive, Third Party, Third Party Fire and Theft, Pay-Per-Mile Customer Type: Individual Policyholders, Fleet Owners, Commercial Drivers, Ride-Sharing Operators Distribution Channel: Direct Sales, Agents, Brokers, Online Platforms Coverage Type: Liability Coverage, Personal Accident Coverage, Property Damage Coverage, Theft Coverage |
| Companies Covered | Zurich Malaysia, MSIG Malaysia, Allianz Malaysia, AIG Malaysia, Liberty General Insurance, Etiqa Malaysia, Tokio Marine Malaysia, Takaful Malaysia, Generali Malaysia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Motor Insurance Market Strategic Shifts
Telematics-enabled risk assessment and digital distribution channels are compressing traditional agency economics while enabling granular driver-behavior pricing that was impossible under fixed tariff regimes.
Embedded telematics hardware is modularizing motor insurance product architecture. Insurers now bundle black-box devices with policy issuance, capturing real-time speed, braking, and mileage data. Fleet operators and ride-sharing platforms adopt these solutions fastest. The technology is modularizing coverage into discrete, behavior-triggered micro-policies that unbundle annual contracts into adjustable monthly subscriptions.
Bank Negara Malaysia's risk-based capital framework is tightening solvency requirements for motor underwriters. The regulation forces insurers to hold additional capital against catastrophe-exposed portfolios. Comprehensive coverage writers in flood-prone districts face the steepest capital charges, accelerating geographic risk selection and portfolio rebalancing toward safer inland territories.
Policyholder acquisition behavior is fragmenting across digital touchpoints. Younger vehicle owners in Kuala Lumpur and Penang now initiate quotes through aggregator platforms rather than captive agent relationships. Direct-to-consumer channels displace branch-based sales for renewal business. This shift concentrates marketing spend on search and social platforms, compressing agent commission pools while raising customer acquisition cost transparency.
Malaysia Motor Insurance Market Segmentation
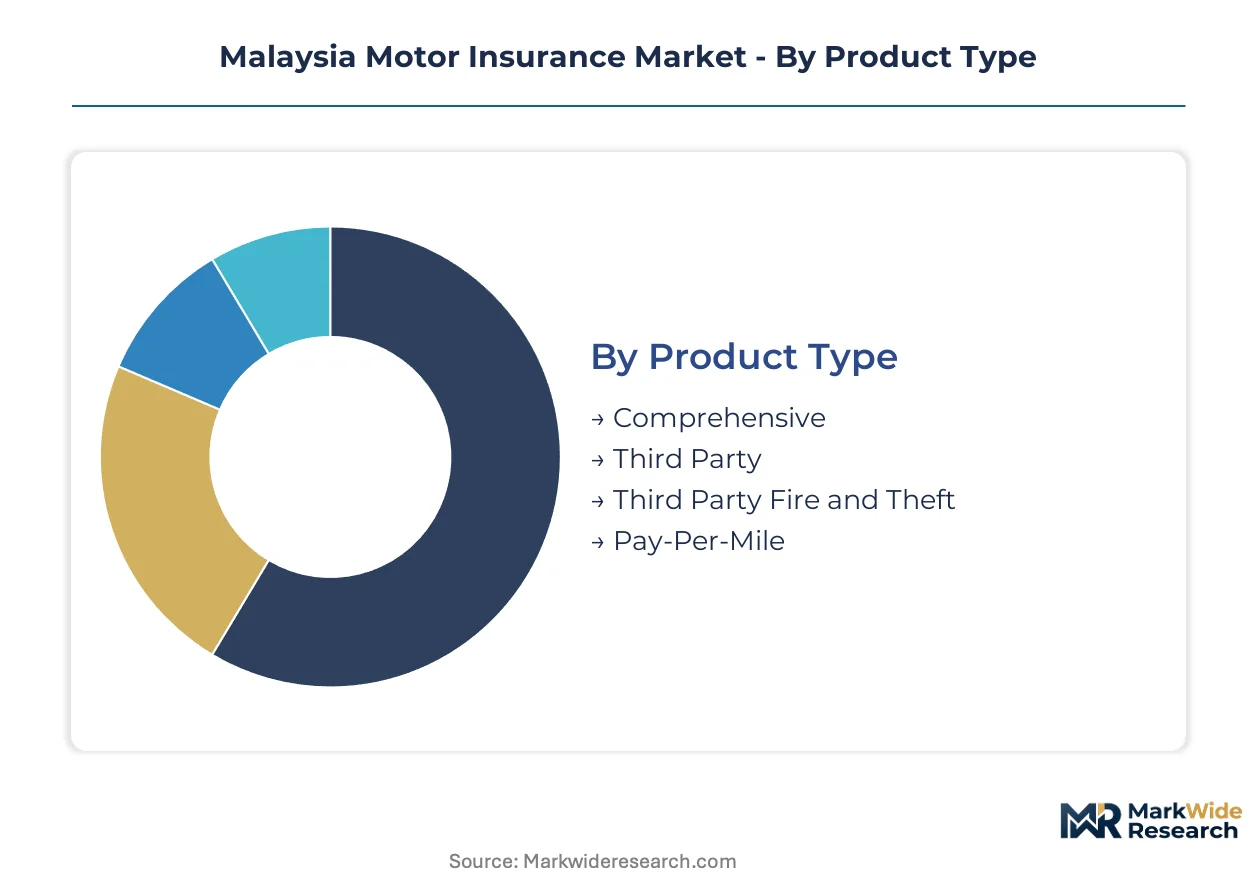
Motor insurance segmentation in Malaysia reflects divergent risk profiles across vehicle usage patterns and distribution economics. Understanding these divisions enables insurers to calibrate pricing engines and capital allocation under Bank Negara Malaysia's detariffication framework.
Product Type:
Replacement cycles for motor coverage accelerate as vehicle owners reassess protection needs following tariff liberalization and telematics availability.
- Comprehensive:This tier bundles collision, theft, fire, and third-party liability into a single contract with higher sum insured thresholds. Demand concentrates among new vehicle owners in the Klang Valley corridor, where financing requirements and asset protection priorities drive policy selection.
- Third Party:Statutory minimum coverage satisfying Road Transport Act 1987 mandates without own-damage protection. Cost-conscious owners of aging vehicles in secondary cities select this tier, though rising litigation exposure erodes its economic appeal.
- Third Party Fire and Theft:Intermediate coverage adding fire and theft protection to mandatory liability. Moderate-income policyholders in Penang and Johor Bahru favor this balance between premium outlay and peril breadth.
- Pay-Per-Mile:Usage-based contracts where premiums scale with actual kilometers driven via telematics verification. Low-mileage urban commuters in Kuala Lumpur and Penang are adopting this model fastest as smartphone-enabled mileage tracking reduces friction.
Volume placements concentrate in Comprehensive; the faster expansion belongs to Pay-Per-Mile.
Customer Type:
Margin structures diverge sharply across buyer concentration and negotiation leverage.
- Individual Policyholders:Fragmented retail demand spanning private car owners seeking personal asset protection. Digital quote aggregation is displacing agent relationships among younger demographics in metropolitan centers.
- Fleet Owners:Concentrated commercial buyers managing multiple vehicles under single master policies with volume-rated terms. Brokers control placement for this segment, extracting commission efficiencies from consolidated negotiations.
- Commercial Drivers:Taxi and delivery operators requiring specialized coverage for higher mileage exposure and passenger liability. Claims frequency in this segment pressures underwriting margins.
- Ride-Sharing Operators:Platform-mediated demand from Grab and regional mobility services scaling insured vehicle pools. Telematics integration is mandatory for this segment, enabling real-time risk monitoring.
Revenue concentration sits with Individual Policyholders; Ride-Sharing Operators are climbing the fastest.
Distribution Channel:
Channel economics are restructuring as digital acquisition costs become transparent and agent commissions compress.
- Direct Sales:Insurer-owned branches and call centers handling policy origination and renewal. Incumbent players with established branch networks in Selangor maintain presence through this channel.
- Agents:Tied representatives earning commission on policy placement. This traditional channel retains strength in semi-urban districts where digital literacy gaps persist.
- Brokers:Independent intermediaries serving commercial accounts and complex risk placements. Fleet and commercial motor business flows predominantly through this channel.
- Online Platforms:Aggregators and direct digital channels enabling quote comparison and instant purchase. Kuala Lumpur and Penang vehicle owners initiate coverage through these platforms with increasing frequency.
Policy flow still dominates through Agents; Online Platforms are gaining share fastest.
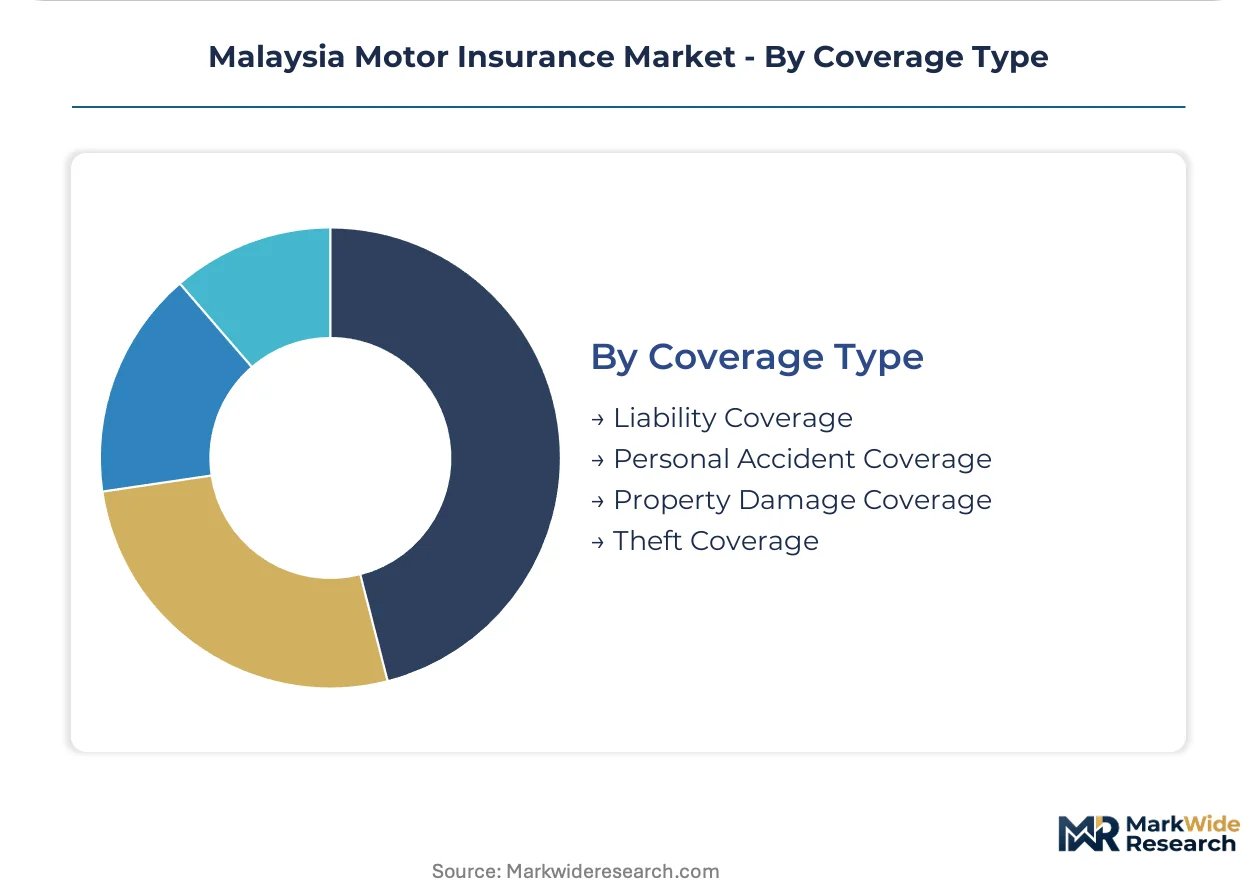
Coverage Type:
Capital requirements under Bank Negara Malaysia's risk-based framework vary by peril exposure and loss accumulation potential.
- Liability Coverage:Mandatory protection against third-party bodily injury and property damage claims. This foundational component underlies every motor policy issued in Malaysia.
- Personal Accident Coverage:Medical expense and disability benefits for insured drivers and passengers. Urban policyholders in high-traffic corridors add this rider more frequently.
- Property Damage Coverage:Indemnification for collision-related vehicle repair or total loss. Comprehensive policyholders in flood-prone districts face reinsurance capacity constraints on this peril.
- Theft Coverage:Protection against vehicle theft and unauthorized conversion. Higher incidence rates in specific geographic zones drive risk-based pricing differentiation.
Attachment frequency is highest for Liability Coverage; Personal Accident Coverage shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum refining capacity along Peninsular Malaysia's western coast anchors the nation's motor insurance demand geography. Bank Negara Malaysia's regulatory jurisdiction extends across thirteen states and three federal territories, with policy density tracking vehicle registration clusters.
Selangor
Vehicle registration volumes in Shah Alam and Petaling Jaya drive the highest policy issuance rates nationwide. Bank Negara Malaysia's detariffication framework permits risk-based pricing differentiation across this corridor. The Klang Valley logistics hub concentrates commercial fleet coverage placement through broker-mediated negotiations.
Kuala Lumpur
Digital-native insurers target metropolitan vehicle owners through smartphone-enabled quote platforms. The central bank's licensing regime for digital insurers enables new entrants to bypass traditional branch infrastructure. Telematics adoption concentrates in downtown commuter segments seeking usage-based premium structures.
Johor
Cross-border vehicle flows between Johor Bahru and Singapore generate specialized coverage requirements for commercial operators. The Iskandar Malaysia development corridor attracts fleet investment from logistics operators seeking regional distribution positioning. Flood peril exposure in southern districts elevates reinsurance costs for comprehensive coverage writers.
Penang
Manufacturing employment density in Bayan Lepas and George Town sustains individual policyholder demand. Pay-Per-Mile products gain traction among island residents with constrained commuting distances. The state's digital infrastructure supports aggregator platform penetration for policy comparison.
Sarawak
Insurance density per registered vehicle lags Peninsular averages, presenting distribution expansion opportunities. The state's dispersed settlement patterns challenge traditional agency network economics. Kuching's urban concentration offers the most viable entry point for digital distribution models targeting underpenetrated segments.
Malaysia Motor Insurance Market Competitive Environment
Established insurers occupy the standard tier; emerging digital entrants pursue direct-to-consumer channels and telematics-enabled pricing. The market exhibits moderate consolidation with incumbent players controlling agency networks while new licenses disrupt distribution economics. Three archetypes dominate: legacy insurers with branch infrastructure, takaful-compliant specialists serving Shariah-sensitive segments, and digitally native distributors leveraging aggregator platforms. Competitive moves center on telematics partnership formation and geographic portfolio rebalancing away from catastrophe-exposed districts.
Among the established tier, MSIG Malaysia, Allianz Malaysia, and Etiqa Malaysia occupy positions reflecting distinct strategic orientations. MSIG Malaysia represents the agency-network archetype with Peninsula-wide presence. Allianz Malaysia exemplifies comprehensive product specialization with direct online distribution investments. Etiqa Malaysia anchors the takaful-compliant segment, competing for Muslim policyholder preference through Shariah-aligned product architecture. These three entities illustrate the competitive positioning spectrum available under Bank Negara Malaysia's evolving regulatory framework.
| Leading Market Players |
|---|
| Zurich Malaysia |
| MSIG Malaysia |
| Allianz Malaysia |
| AIG Malaysia |
| Liberty General Insurance |
| Etiqa Malaysia |
| Tokio Marine Malaysia |
| Takaful Malaysia |
| Generali Malaysia |
| Others |
Value Chain & Pricing Dynamics
Certified actuarial talent concentration in the Klang Valley widens pricing-tier spreads between digitally native insurers and legacy branch-network operators, as labor-cost differentials translate into premium-rate competitiveness across Peninsula Malaysia.
Pricing Analysis
Warranty-style service bundling separates premium-tier motor coverage from stripped-back economy offerings, with comprehensive policies incorporating roadside assistance, windscreen protection, and agency repairs while basic third-party coverage excludes all ancillary benefits. Pricing stratifies across premium, standard, and economy tiers based on driver telematics scores and vehicle age depreciation curves. Cost compression in the economy tier is intensifying because digital aggregators expose rate differentials to price-sensitive individual policyholders. Fleet owners demonstrate the lowest price sensitivity due to broker-negotiated volume terms, while aging-vehicle owners in secondary cities exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for salvage vehicle disposal and parts harvesting concentrate in Selangor-based panel workshops, creating geographic chokepoints in claims fulfillment. Claims handling draws from Malaysia's legacy workshop networks, parts distributors in Thailand and Singapore, and imported replacement components from Japan and South Korea. Single-source vulnerability pervades the certified repair panel system, where Bank Negara Malaysia accreditation limits workshop eligibility. Distribution runs through insurer-owned branches, tied agent networks, and emerging digital aggregators reaching policyholders directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around insurers with proprietary risk-pricing engines, as Bank Negara Malaysia's detariffication exposes undercapitalized players unable to price risk accurately.
For Market Incumbents: Anticipate margin compression from digital entrants by accelerating telematics platform deployment and consolidating agency networks in flood-exposed districts. Secure backward integration into claims repair through panel workshop equity stakes. Defensive priority rests on proprietary data assets that refine risk-pricing models faster than competitors. For New Entrants and Emerging Players: Enter via white-space distribution in Sabah and Sarawak, where insurance density per registered vehicle lags Peninsular averages by substantial margins. Target low-mileage urban commuters in Penang and Kuala Lumpur with smartphone-enabled Pay-Per-Mile offerings. Go-to-market leverage concentrates on aggregator platform partnerships that bypass legacy agent economics. For Investors and Strategic Acquirers: Re-rating potential sits with takaful-compliant specialists given Shariah-sensitive policyholder segments underserved by conventional offerings. Long-term viability favors insurers with balanced geographic portfolios avoiding catastrophe-exposed southern districts. Monitor Bank Negara Malaysia's risk-based capital requirement adjustments as the inflection signal for sector consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables real-time driver behavior monitoring for risk-based premium calibration under detariffication. |
| Takaful Product Architecture Expansion | Captures Muslim policyholder preference through Shariah-compliant fund structures and profit-sharing mechanisms. |
| East Malaysia Distribution Buildout | Addresses insurance density gaps in Sabah and Sarawak through digital-first channel deployment. |
| Flood Risk Portfolio Rebalancing | Reduces capital charges under Bank Negara Malaysia's risk-based framework by exiting catastrophe-exposed districts. |
| Claims Panel Workshop Consolidation | Secures cost control through captive repair network capacity in high-volume Klang Valley corridors. |
Study Parameters
Independent corroboration across primary interviews with motor underwriters, claims operations directors, and insurance brokerage principals underwrites the qualitative findings, validated against Bank Negara Malaysia regulatory circulars, PIAM industry statistics, Road Transport Department vehicle registration databases, and insurer financial disclosures. Bottom-up policy volume estimates triangulate with top-down premium pool calculations.
Rate-of-change decomposition separates volume growth from pricing evolution across the analysis window, modeling product type segmentation by coverage tier and telematics adoption, customer type by fleet concentration and ride-sharing platform scale, and distribution channel by digital penetration rates. CAGRs derive from fitted trend extrapolation calibrated to historical premium growth patterns and vehicle registration projections. Forecast inputs incorporate detariffication phase timing and flood peril reinsurance capacity assumptions.
Revisions become necessary when Bank Negara Malaysia accelerates tariff liberalization schedules, catastrophic flood events compress reinsurance availability, or digital aggregator platforms achieve dominant market share in policy origination. Practitioners should monitor regulatory circulars on risk-based capital requirements and telematics partnership announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
France Motor Insurance Market