
 Motor Insurance Market | 2026-2036
Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Insurance Market Intelligence
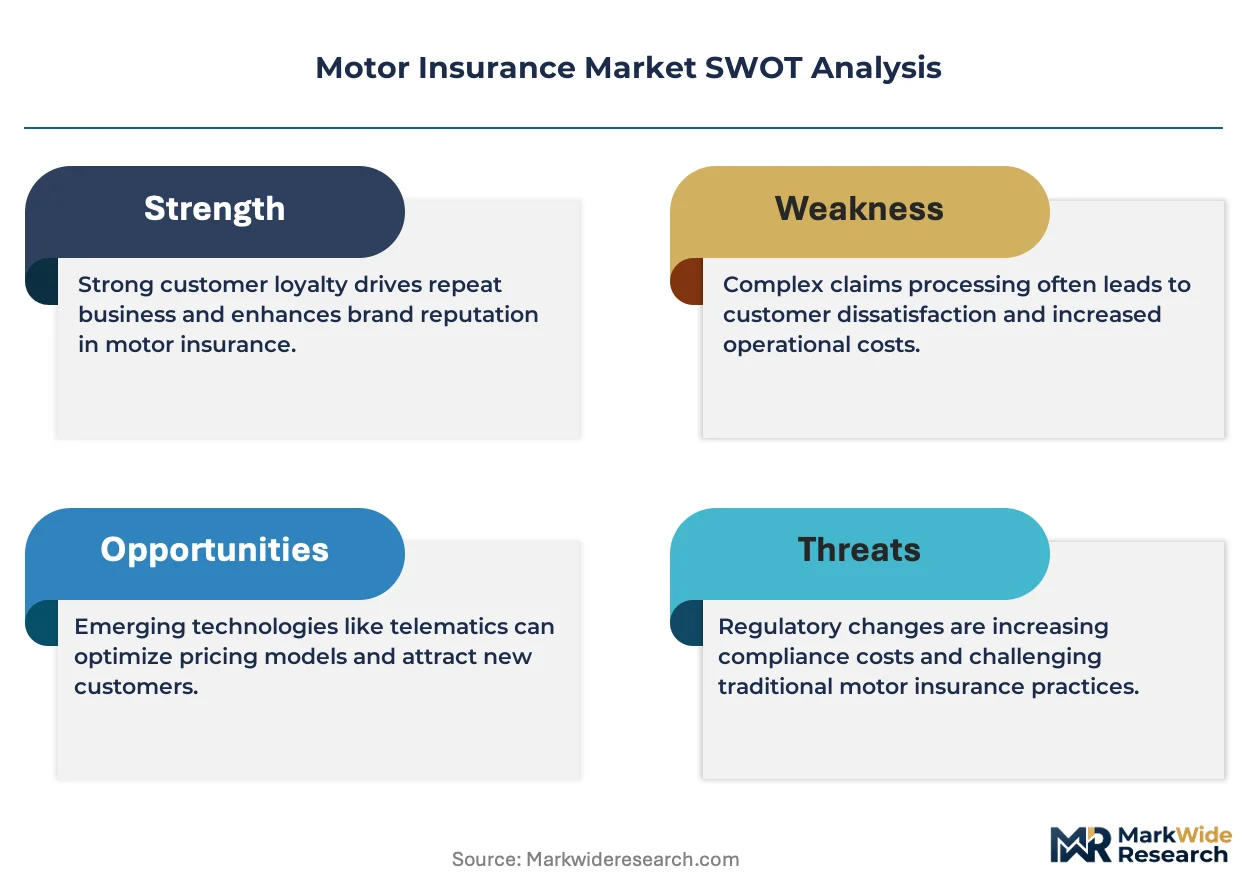
A shortage of actuarial data scientists proficient in telematics and AI-driven risk modeling is unwinding traditional pricing advantages for slow-moving incumbents. Progressive leverages proprietary driving-behavior algorithms to sustain direct-to-consumer growth. State Farm anchors its position through captive agency networks and brand recognition in personal auto lines. Berkshire Hathaway (GEICO) competes aggressively on price through minimal overhead and digital-first policy issuance.
Motor insurance is a risk-transfer contract indemnifying policyholders against financial loss from vehicle damage, theft, or liability, priced through probabilistic assessment of driver behavior, vehicle characteristics, and geographic exposure. Its primary commercial purpose is to pool and redistribute collision and liability risk across large populations while ensuring solvency for claim obligations. Comprehensive coverage dominates premium volumes in mature markets due to lender mandates and asset-protection requirements, while third-party liability remains the regulatory baseline across emerging economies. Electric vehicle policies represent the fastest-growing segment as battery replacement costs and specialized repair networks command differentiated pricing structures.
The National Association of Insurance Commissioners coordinates state-level rate filings and capital requirements, while the EU's Solvency II framework governs reserve adequacy and risk disclosure for European underwriters. China's Banking and Insurance Regulatory Commission mandates telematics data standards and directs premium rate liberalization for commercial auto lines. Stakeholders must monitor evolving autonomous-vehicle liability frameworks and decide whether to build in-house predictive analytics capabilities or partner with insurtech platforms as self-driving fleets reshape fault attribution.
Market Dynamics
Telematics integration is compressing traditional pricing cycles as real-time driving data replaces historical actuarial tables, forcing incumbents to rebuild core underwriting infrastructure around continuous risk monitoring rather than annual policy renewals.
Growth Catalysts
- Commercial Fleet Electrification:Logistics operators in the United States, China, and Germany are scaling electric vehicle deployments, creating demand for specialized battery-damage coverage and charging-infrastructure liability products.
- EU AI Act Compliance:Automated underwriting algorithms in European markets face new transparency mandates, accelerating investment in explainable risk-scoring models that satisfy regulatory audit requirements.
- Usage-Based Pricing Models:Pay-per-mile and behavior-adjusted premiums are attracting cost-conscious urban drivers in dense metropolitan zones where annual mileage has declined post-pandemic.
Market Restraints
- Battery Replacement Cost Volatility:Lithium carbonate price swings and semiconductor shortages for battery management systems are compressing margins on electric vehicle comprehensive coverage.
- Actuarial Data Scientist Scarcity:The talent pipeline for professionals combining statistical modeling with telematics engineering remains constrained in North American and Western European labor markets.
- Autonomous Vehicle Liability Ambiguity:Fault attribution frameworks for Level 3-4 automation remain unresolved across multiple state-level jurisdictions in the United States, freezing product development timelines.
Strategic Opportunities
- India's Telematics Mandate Expansion:The country's banking and insurance regulator is liberalizing commercial auto rate filings, opening entry paths for usage-based products in a traditionally price-regulated market.
- Cyber-Physical Convergence:Integration of vehicle-to-infrastructure communication with insurance platforms enables real-time crash prevention incentives and dynamic premium adjustment.
- Embedded Insurance Distribution:Original equipment manufacturers are pre-loading coverage at point-of-sale, bypassing traditional agency channels and capturing first-mover relationships with new vehicle buyers.
Industry Challenges
- Legacy Core System Modernization:Mainframe-based policy administration platforms at established carriers require multi-year migration programs to support real-time telematics data ingestion.
- Cross-Border Data Governance:GDPR restrictions on driver-behavior data transfer complicate pan-European fleet coverage for multinational logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Insurance Market |
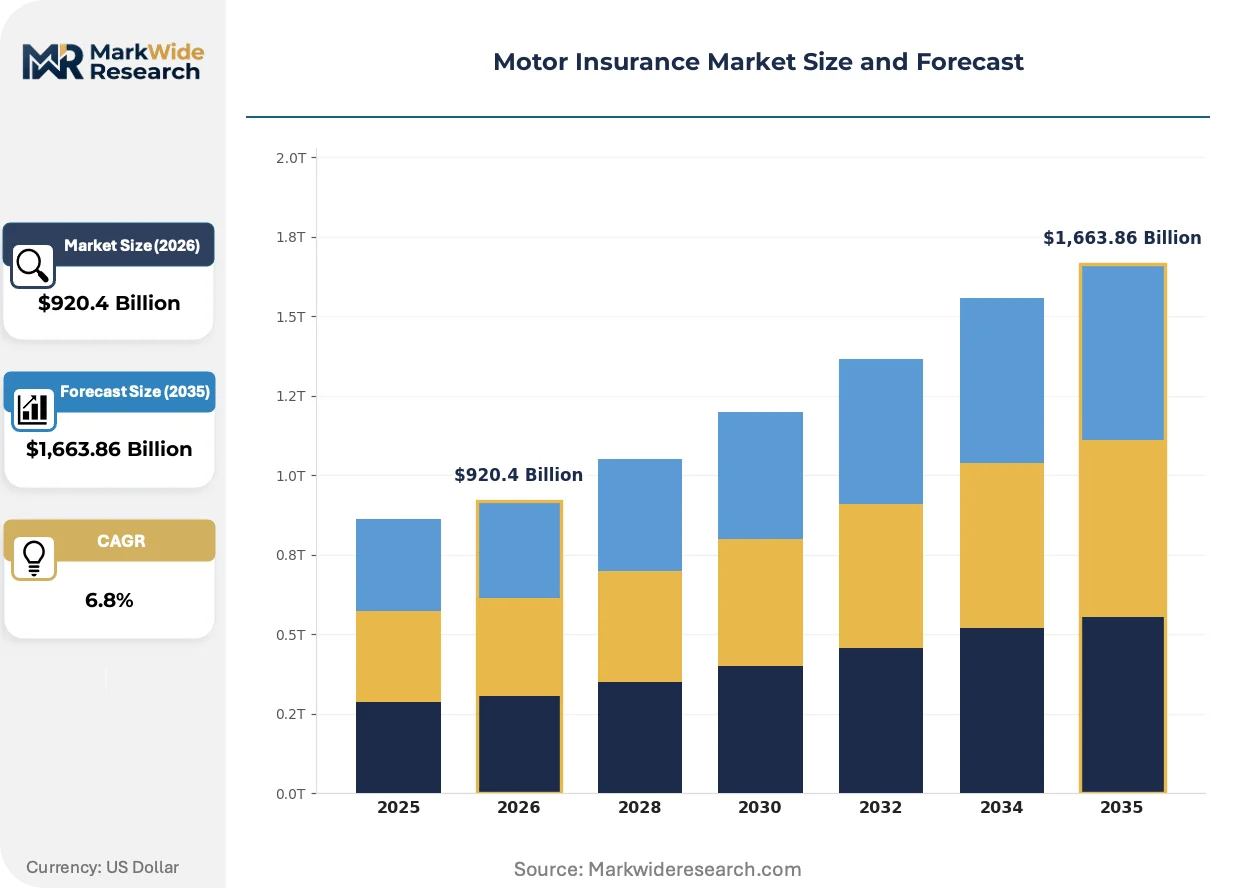
| Market Size in 2026 | $920.4 Billion |
| Market Size in 2035 | $1,663.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Comprehensive, Third-Party, Third-Party Fire & Theft, Personal Injury Protection Policyholder Type: Individual, Business, Fleet, Government Vehicle Type: Passenger Cars, Motorcycles, Commercial Vehicles, Electric Vehicles Claim Process: Online, Hybrid, Traditional, Immediate Settlement |
| Companies Covered | Allstate, Amica, State Farm, Travelers, Nationwide, Progressive, USAA, Liberty Mutual, Berkshire Hathaway (GEICO), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Insurance Market Strategic Shifts & Innovations
Connected-vehicle architectures are dissolving the boundary between automotive hardware and financial services, enabling insurers to intervene before losses occur rather than merely indemnifying after the fact.
Edge-computing telematics devices are miniaturizing to cigarette-lighter form factors, slashing installation costs for aftermarket deployment. Small fleet operators and individual policyholders now access granular driving-behavior feedback without professional hardware integration. This compression is expanding addressable market penetration beyond factory-installed connected-car platforms.
China's Banking and Insurance Regulatory Commission has mandated standardized telematics data formats for commercial auto lines, forcing proprietary systems toward interoperability. Domestic insurers must retrofit existing platforms to ingest unified sensor outputs from heterogeneous vehicle fleets. The directive accelerates consolidation around shared data infrastructure and reduces vendor lock-in for fleet buyers.
Subscription-based coverage models are displacing traditional annual contracts among urban millennials and gig-economy drivers. Digital-native platforms offer pause-and-resume protection aligned with intermittent vehicle use, capturing share from incumbents wedded to fixed-term policy structures. This behavioral pivot is most pronounced in German and United States metropolitan corridors where car ownership rates are declining but per-trip insurance needs persist.
Motor Insurance Market Segmentation
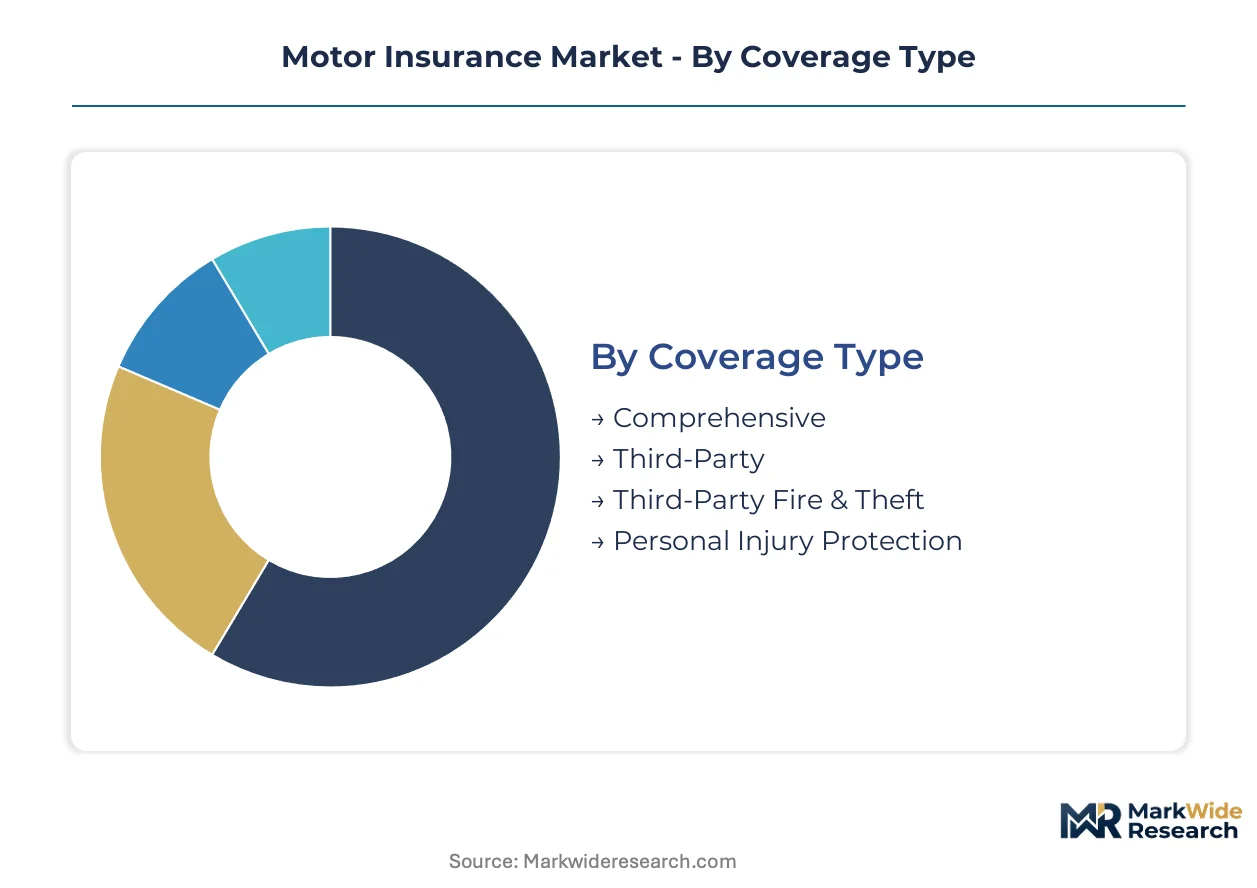
Motor insurance segmentation reveals distinct margin architectures across coverage structures and customer archetypes. Underwriters allocate capital differently across these boundaries, with telematics penetration and loss ratios varying substantially by segment composition.
Coverage Type:
Margin pools concentrate in comprehensive products where lender mandates and asset-protection requirements sustain premium density, while liability-only lines compete on price with thinner spreads.
- Comprehensive:Bundles collision, theft, and third-party liability into unified protection. Demand clusters in Germany and the United States where financing institutions mandate full coverage for leased vehicles and battery replacement costs for electric fleets drive pricing differentiation.
- Third-Party:Statutory minimum coverage satisfying legal driving requirements. Volume concentrates across emerging economies where regulatory baselines dominate purchasing decisions and price sensitivity compresses carrier margins.
- Third-Party Fire & Theft:Mid-tier protection adding property damage coverage to baseline liability. Appeals to used-vehicle owners in urban United States corridors seeking partial asset protection without comprehensive premiums.
- Personal Injury Protection:Medical expense coverage regardless of fault attribution. Mandated in specific United States state jurisdictions with no-fault regulatory frameworks.
Comprehensive holds installed capacity. Third-Party is rotating up the share rankings in cost-sensitive segments.
Policyholder Type:
Customer acquisition economics diverge sharply between fragmented individual pools and concentrated fleet accounts with scale-negotiated terms.
- Individual:Dispersed policyholders purchasing through direct-to-consumer digital channels or captive agency networks. Telematics-enabled behavior-adjusted pricing is gaining traction fastest among urban millennials in United States metropolitan zones.
- Business:Small and medium enterprises covering commercial vehicle operations. Demand aligns with logistics sector expansion and contractor vehicle utilization across German Mittelstand manufacturing clusters.
- Fleet:Multi-vehicle operators with centralized policy administration and loss control programs. China's logistics electrification is driving specialized battery-damage coverage procurement at scale.
- Government:Municipal and state vehicle pools with procurement through structured tender processes. Compliance with public-sector transparency mandates shapes carrier selection criteria.
Fleet is rotating up the share rankings. Individual retains premium volume leadership.
Vehicle Type:
Technical risk profiles and repair network specialization create divergent underwriting approaches across propulsion and vehicle class boundaries.
- Passenger Cars:Standard private automobile coverage with mature actuarial data and established repair networks. Telematics penetration is highest in this segment across United States and German markets.
- Motorcycles:Two-wheeler protection with elevated injury severity factors and seasonal usage patterns. Demand concentrates in urban Asian corridors and Mediterranean European markets with high two-wheeler density.
- Commercial Vehicles:Heavy-duty truck and van coverage with specialized cargo liability components. China's regulatory mandate for standardized telematics data formats is reshaping fleet underwriting infrastructure.
- Electric Vehicles:Battery-specific coverage addressing thermal runaway risks and specialized repair protocols. This segment is expanding most quickly as lithium-ion replacement costs and semiconductor-dependent battery management systems command differentiated pricing structures.
Passenger Cars holds installed capacity. Electric Vehicles is rotating up the share rankings.
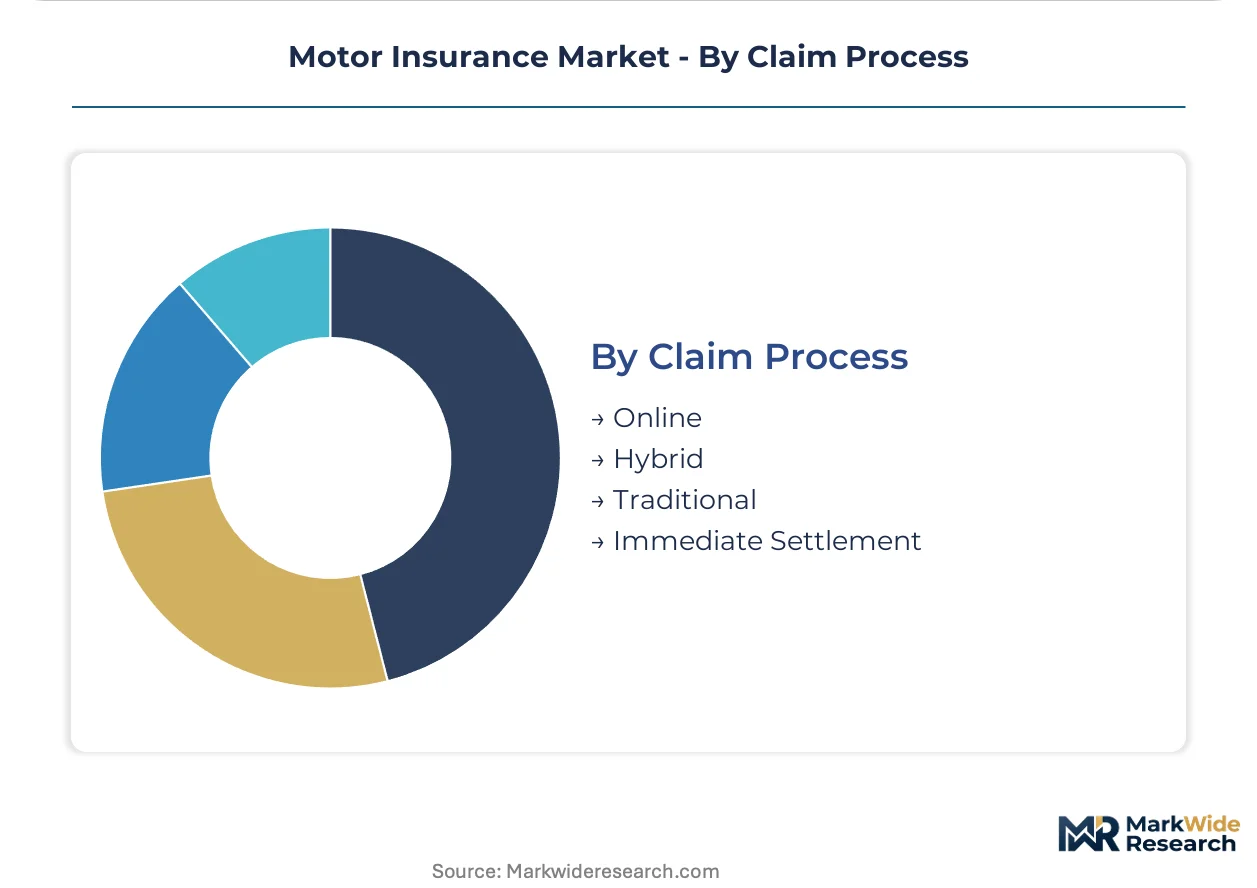
Claim Process:
Operational cost structures and customer retention correlate with settlement speed and digital integration depth.
- Online:Fully digitized first-notice-of-loss through payment disbursement. Preferred by digital-native policyholders in United States and German urban markets where smartphone-based documentation accelerates resolution.
- Hybrid:Digital intake with human adjuster review for complex claims. Balances efficiency with fraud detection requirements across mid-market segments.
- Traditional:Phone or in-person claim initiation with physical inspection protocols. Retains preference among older demographics and high-value comprehensive claims requiring adjuster verification.
- Immediate Settlement:Automated payment triggered by telematics crash detection without manual review. Pilot deployments focus on low-severity collisions in connected-vehicle fleets with verified sensor data.
Traditional holds installed capacity. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Association of Insurance Commissioners anchors the United States regulatory framework, while China's Banking and Insurance Regulatory Commission and Germany's KBA drive telematics standardization across their respective markets. Premium volumes concentrate where connected-vehicle deployment and fleet electrification advance fastest.
United States
Commercial fleet electrification and usage-based pricing adoption are reshaping underwriting economics. The National Association of Insurance Commissioners coordinates state-level rate filings and capital requirements. Texas and California logistics corridors are driving specialized battery-damage coverage procurement at scale.
China
Logistics network expansion and electric vehicle fleet mandates are accelerating premium growth. The Banking and Insurance Regulatory Commission mandates standardized telematics data formats for commercial auto lines. Yangtze River Delta manufacturing clusters are retrofitting underwriting platforms to ingest unified sensor outputs.
Germany
Connected-vehicle deployment and subscription-based coverage models are displacing traditional annual contracts. KBA regulations govern vehicle-type approval and safety data integration with insurance platforms. Bavarian automotive clusters are piloting real-time crash prevention incentives through vehicle-to-infrastructure communication.
India
Telematics mandate expansion and commercial auto rate liberalization are opening entry paths for usage-based products. The Insurance Regulatory and Development Authority directs premium rate deregulation for commercial lines. Maharashtra and Gujarat logistics hubs are procuring specialized fleet coverage as electrification scales.
United Kingdom
Behavior-adjusted premiums and digital-first distribution are gaining traction among urban policyholders. The Financial Conduct Authority governs consumer protection and algorithmic transparency in automated underwriting. London metropolitan corridors are driving pause-and-resume subscription models for intermittent vehicle use.
Motor Insurance Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with direct-to-consumer platforms and captive agency networks occupying distinct competitive positions. The market structure reflects a bifurcation between price-driven digital operators and relationship-heavy traditional channels. Strategic archetypes include telematics-native underwriters, brand-anchored personal line specialists, and minimal-overhead direct writers. Competitive moves center on proprietary algorithm development and embedded insurance partnerships with original equipment manufacturers.
Within the direct-to-consumer tier, Progressive and Berkshire Hathaway (GEICO) represent contrasting approaches to price competition and digital acquisition. State Farm anchors the captive agency archetype through exclusive producer networks. Among military-affiliated specialists, USAA occupies a position serving defined demographic segments with differentiated service models.
| Leading Market Players |
|---|
| Allstate |
| Amica |
| State Farm |
| Travelers |
| Nationwide |
| Progressive |
| USAA |
| Liberty Mutual |
| Berkshire Hathaway (GEICO) |
| Others |
Cost & Logistics Intelligence
Annual policy renewals lock in premium visibility for carriers while binding policyholders to fixed-rate structures that lag real-time risk shifts. This contract pattern concentrates pricing power with underwriters possessing telematics infrastructure, as Progressive and State Farm leverage continuous data streams to adjust rates faster than competitors tethered to historical actuarial tables.
Pricing Analysis
Long-term policy contracts dominate personal auto lines, though subscription-based models are gaining share among urban millennials seeking pause-and-resume flexibility. Price differentiation rests on telematics penetration and repair network density, with comprehensive coverage commanding spreads over liability-only tiers due to battery replacement cost volatility. Pricing pressure stems from lithium carbonate swings and semiconductor shortages compressing electric vehicle margins. Cost-conscious individual policyholders in emerging markets exhibit highest price sensitivity, while fleet operators prioritize loss control programs over premium minimization.
Supply Chain Analysis
Inventory cycles for telematics hardware have compressed to eight-week horizons as edge-computing devices miniaturize for aftermarket deployment. Component sourcing concentrates in China, Taiwan, and South Korea for semiconductor-dependent battery management systems and sensor arrays. Supply chain risk centers on single-source vulnerability for lithium-ion cell procurement amid export licensing uncertainty. Distribution runs through captive agency networks for traditional carriers and embedded OEM partnerships for digital-native platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics fragmentation creates specialized entry paths as usage-based pricing dissolves the one-size-fits-all policy archetype, enabling niche underwriters to capture defined behavioral segments.
For Market Incumbents: Secure proprietary algorithm development through in-house data science recruitment or insurtech acquisition, as actuarial talent scarcity threatens pricing precision. Fortify captive agency relationships against embedded insurance distribution partnerships that OEMs are forging at point-of-sale. For New Entrants and Emerging Players: Anchor in India's commercial auto rate liberalization corridor, where regulatory opening for usage-based products meets underserved fleet electrification demand. Target gig-economy driver segments with per-trip subscription models, leveraging smartphone-native documentation to bypass hardware installation barriers. For Investors and Strategic Acquirers: Capital is best deployed toward telematics-native underwriters with demonstrated loss-ratio improvement and scalable data infrastructure. Monitor autonomous vehicle liability framework resolution as the inflection signal determining which carriers can deploy capital into self-driving fleet coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Progressive's driving-behavior algorithms sustain direct-to-consumer growth through real-time risk scoring. |
| Embedded Insurance Partnership | OEM pre-loaded coverage captures first-mover relationships with electric vehicle buyers at point-of-sale. |
| Battery-Damage Coverage Specialization | Specialized products address thermal runaway risks and semiconductor-dependent repair protocols for electric fleets. |
| Usage-Based Pricing Launch | Pay-per-mile models attract cost-conscious urban drivers in dense metropolitan zones with declining annual mileage. |
| Cross-Border Fleet Coverage Expansion | GDPR-compliant data architecture enables pan-European logistics coverage for multinational operators. |
Research Approach
Initial hypotheses were tested against primary input from underwriting executives, telematics platform engineers, fleet procurement managers, and regulatory affairs specialists at state insurance departments, then refined against secondary validation from NAIC rate filing databases, EU Solvency II disclosure reports, CBIRC regulatory circulars, connected-vehicle production data, and SEC 10-K insurance segment disclosures. Bottom-up policy volume estimates were triangulated with top-down premium pool calculations across coverage types and policyholder segments.
Variance decomposition across the projection horizon isolates telematics penetration rates, electric vehicle fleet adoption curves, and autonomous vehicle liability framework evolution as primary forecast drivers. Segmentation modeling spans coverage structure, policyholder archetype, vehicle propulsion architecture, and claim process digitization depth. CAGRs were derived from regression-adjusted trend extrapolation anchored to observed premium density shifts in United States, China, and Germany corridor markets.
Decision-makers should treat outputs as directional under assumptions of continued telematics regulatory standardization and stable lithium supply chain function; material deviation in battery cost trajectories or autonomous liability resolution timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Japan Motor Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market