
 Indonesia Motor Insurance Market | 2026-2036
Indonesia Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Motor Insurance Market Foresight
OJK's Bancassurance and Digital Channel Distribution certification cycle is collapsing the intermediary landscape, forcing smaller brokers toward insurtech partnerships or exit. PT Asuransi Astra Buana leverages its captive dealership network to dominate new-vehicle policy attachment. Zurich Asuransi Indonesia sustains pricing discipline through advanced telematics underwriting models. MSIG Insurance Indonesia anchors commercial fleet accounts with multi-year loss-control contracts.
Indonesia motor insurance constitutes risk-transfer contracts covering physical damage, third-party bodily injury, and theft exposure for two-wheel and four-wheel vehicles operating on public roads. Policies incorporate sum insured calculations based on vehicle age, engine displacement, and regional claims density tables, with compulsory third-party liability forming the statutory baseline. Comprehensive coverage leads policy type segmentation due to financier-mandated requirements for leased and collateralized vehicles. Ride-sharing services represent the fastest-expanding customer type as Gojek and Grab driver fleets require commercial-grade endorsements. Budget premium tiers attract motorcycle owners in rural coverage areas where disposable income limits policy selection.
OJK supervises capital adequacy and product filing standards, while the Financial Services Authority's sandbox framework permits algorithmic pricing experiments. Indonesia's Road Traffic Law and regional police accident documentation protocols shape claims verification workflows and loss reserve requirements. Stakeholders must monitor OJK's evolving digital-first distribution rules and the central bank's real-time payment infrastructure integration for premium collection and settlement efficiency.
Market Dynamics
OJK's digital distribution mandates are compressing the traditional broker layer while telematics adoption rewrites risk assessment protocols across Indonesian motor portfolios.
Growth Catalysts
- Compulsory TPL enforcement:OJK's third-party liability mandates expand the addressable policy base as enforcement tightens in secondary cities.
- Logistics fleet expansion:E-commerce fulfillment networks and ride-hailing platforms scale commercial vehicle assets requiring comprehensive coverage endorsements.
- Telematics penetration:Usage-based pricing models reduce adverse selection and attract digitally native customer segments in Greater Jakarta.
Market Restraints
- Claims cost inflation:Medical expense escalation and spare parts import dependency erode loss ratios for comprehensive coverage tiers.
- Agent channel concentration:Rural distribution remains captive to traditional broker networks resistant to digital onboarding protocols.
- Data infrastructure gaps:Real-time vehicle telemetry requires 4G/5G coverage that remains uneven outside Java's primary corridors.
Strategic Opportunities
- Eastern Indonesia penetration:Sulawesi and Papua present underinsured motorcycle populations with rising disposable income trajectories.
- Embedded insurance integration:OEM dealership systems and ride-hailing driver apps offer direct policy attachment at point of vehicle transaction.
- BI Fast payment rails:Bank Indonesia's real-time settlement infrastructure enables instant premium collection and claims disbursement.
Industry Challenges
- Actuarial talent scarcity:Telematics underwriting demands data science capabilities that outpace local university pipeline output.
- Legacy system integration:Core policy administration platforms require API overhauls to support usage-based pricing algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Motor Insurance Market |
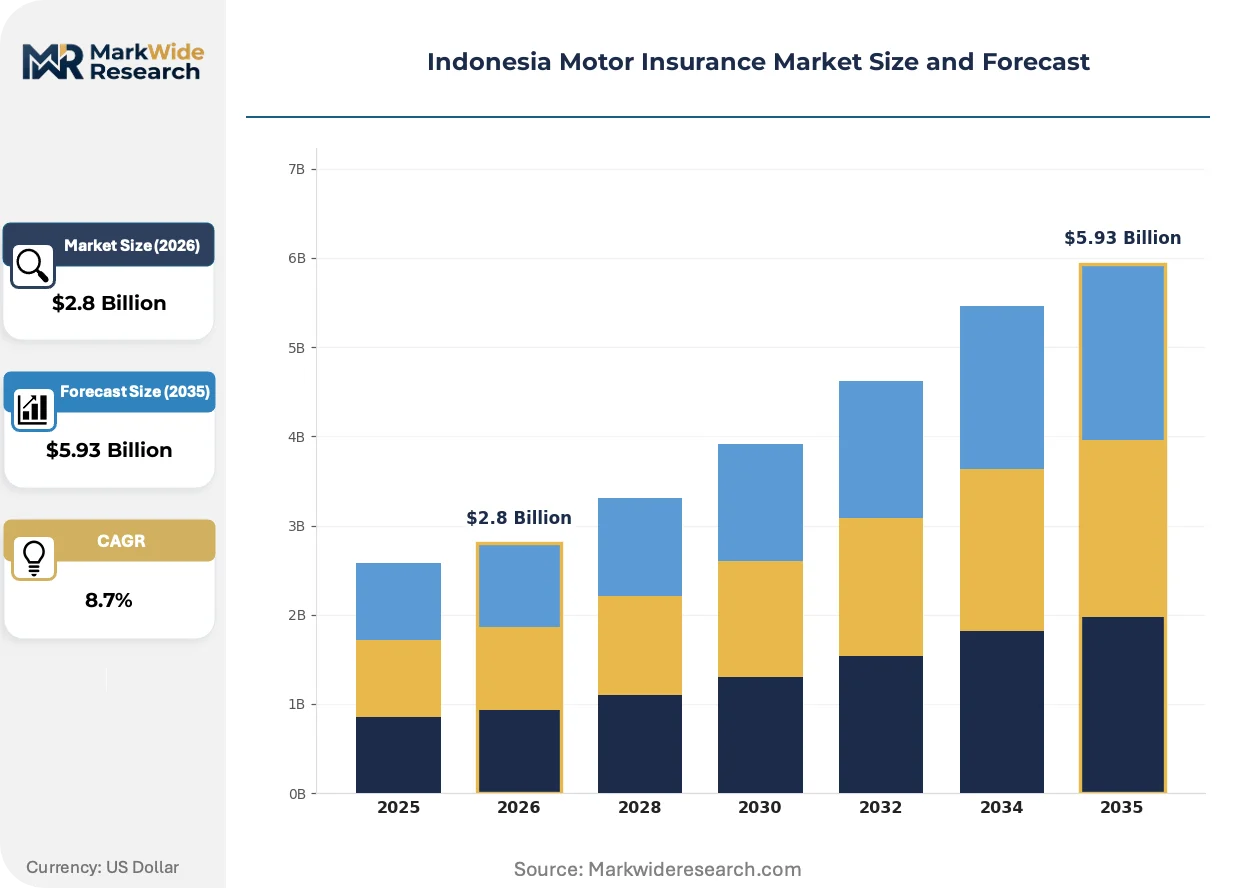
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third Party Liability, Collision, Personal Accident Premium Tier: High-End, Mid-Range, Budget, Discounted Customer Type: Individual Owners, Commercial Fleets, Corporate Clients, Ride-Sharing Services Coverage Area: Urban Areas, Rural Areas, National, Others |
| Companies Covered | PT Jasa Raharja (Persero), Zurich Asuransi Indonesia, PT Asuransi Astra Buana, MSIG Insurance Indonesia, Oona Indonesia, Asuransi Sinar Mas, Allianz Utama Indonesia, AXA Mandiri Financial Services, PT Asuransi Central Asia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Motor Insurance Market Shifts & Advancements
Telematics deployment and regulatory digitization are restructuring how risk is priced, distributed, and serviced across Indonesian motor portfolios.
Usage-based insurance platforms are decomposing traditional annual premium models into granular per-kilometer or per-trip pricing structures. Commercial fleet operators in logistics and ride-hailing segments are adopting these systems fastest, drawn by cash-flow alignment with revenue cycles. This granularity is compressing cross-subsidization between high-mileage and low-mileage policyholders, forcing repricing of standard comprehensive products.
OJK's sandbox framework permits algorithmic pricing experiments that bypass historical tariff restrictions. Insurtech entrants leverage this regulatory latitude to test dynamic risk scoring against traditional vehicle-age tables. The experiments concentrate in Greater Jakarta and Surabaya, where data density supports predictive model validation before broader licensing.
Digital-first distribution is displacing branch-heavy acquisition models as OJK mandates electronic policy issuance. Insurers are unbundling agent commissions and redirecting spend toward embedded partnerships with automotive marketplaces and fintech wallets. The shift is most visible in motorcycle coverage, where Gojek and Grab driver onboarding flows integrate compulsory TPL as a frictionless checkpoint.
Indonesia Motor Insurance Market Segmentation
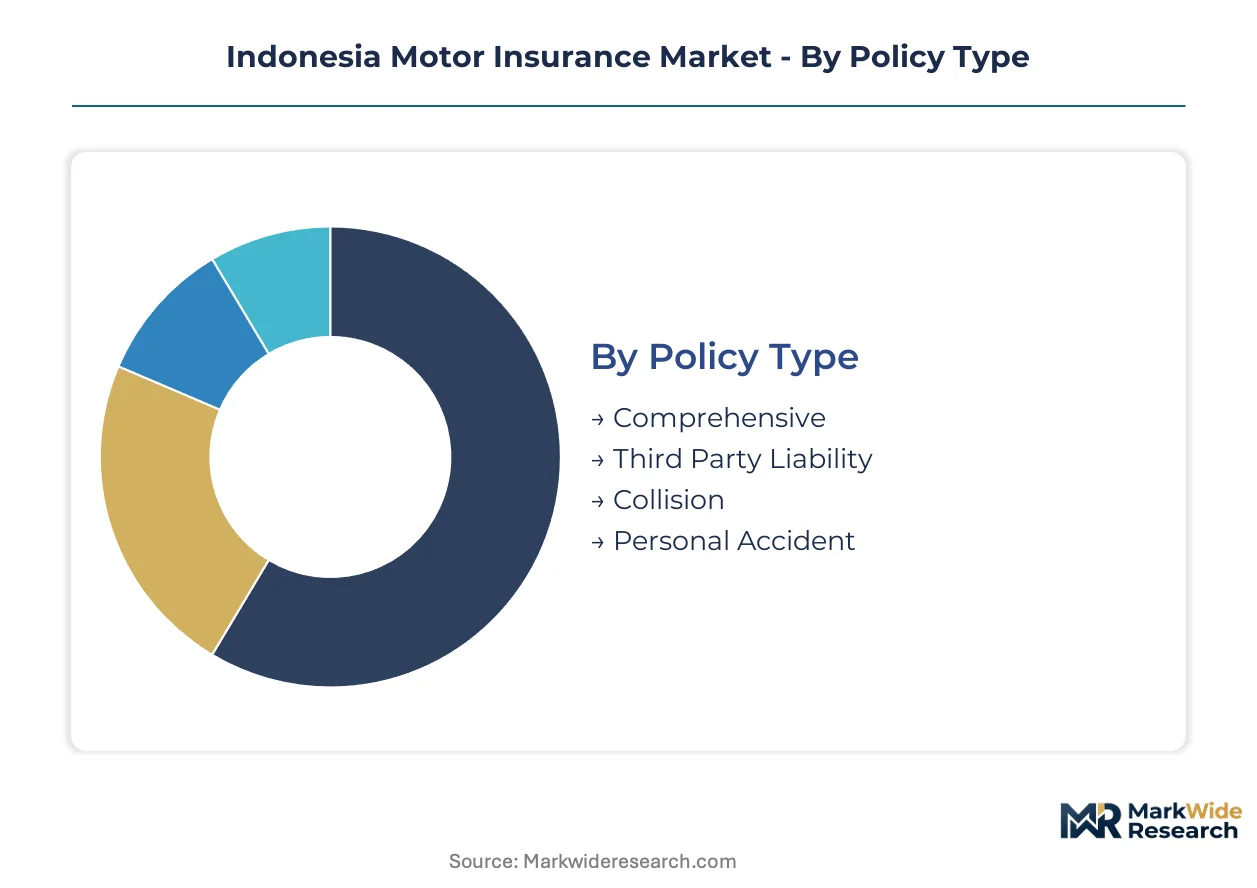
Segmentation in Indonesia's motor insurance market reveals how OJK's compulsory TPL mandates and digital distribution rules reshape competitive priorities across policy structures. Understanding these divisions exposes where traditional comprehensive products face erosion from embedded alternatives and telematics-enabled offerings.
Policy Type:
Substitution pressure concentrates most intensely on standard comprehensive products as embedded insurance at OEM dealerships and ride-hailing platforms bypass traditional policy acquisition.
- Comprehensive:Bundles physical damage, theft, and third-party liability under single contract terms, with financier-mandated attachment for leased vehicles driving concentration in Greater Jakarta and Surabaya's collateralized auto markets. OJK's capital adequacy requirements favor established insurers with loss reserve depth for this coverage tier.
- Third Party Liability:Statutory minimum coverage enforced through OJK mandates, with enforcement tightening in secondary cities expanding the addressable base beyond Java. Medical expense escalation and spare parts import dependency erode loss ratios for insurers lacking telematics-enabled risk selection.
- Collision:Covers vehicle-to-vehicle and single-vehicle accident damage excluding theft or non-collision perils, appealing to aging vehicle owners outside financier-mandated comprehensive requirements.
- Personal Accident:Provides bodily injury coverage for drivers and passengers independent of vehicle damage claims, with demand clustering in commercial fleet accounts seeking layered protection.
Comprehensive retains volume leadership; Third Party Liability holds the steepest expansion curve as enforcement widens.
Premium Tier:
Cost stratification across premium tiers mirrors Indonesia's pronounced income inequality, with motorcycle-dominated rural markets compressing toward budget endpoints while Jakarta's luxury vehicle pool sustains high-end pricing.
- High-End:Serves luxury vehicle segments and high-net-worth individuals with expanded coverage limits, concierge claims service, and OEM-certified repair networks concentrated in Jakarta's premium automotive dealerships.
- Mid-Range:Balances coverage breadth with affordability for mass-market four-wheel owners, representing the contested middle where digital-first insurtechs and traditional insurers clash for policyholder acquisition.
- Budget:Dominates motorcycle coverage across rural Java and Eastern Indonesia where disposable income constraints limit policy selection to compulsory TPL minimums.
- Discounted:Promotional pricing tied to telematics adoption or multi-policy bundling, gaining traction among digitally native customer segments in Greater Jakarta's usage-based insurance experiments.
Budget commands absolute policy count; Discounted is climbing the fastest as BI Fast payment rails enable dynamic pricing experiments.
Customer Type:
Application-specific risk profiles diverge sharply between individual usage patterns and commercial fleet operations, with the latter demanding loss-control contracts and multi-year pricing stability.
- Individual Owners:Encompasses private vehicle and motorcycle holders seeking annual coverage renewal, with digital onboarding penetration highest among younger policyholders in urban centers.
- Commercial Fleets:Logistics operators and delivery networks scaling vehicle assets under e-commerce fulfillment expansion, requiring comprehensive endorsements and centralized policy administration.
- Corporate Clients:Employee vehicle programs and executive fleet arrangements with customized coverage structures and dedicated account management relationships.
- Ride-Sharing Services:Gojek and Grab driver fleets requiring commercial-grade endorsements, with embedded insurance integration at driver onboarding flows transforming acquisition economics.
Individual Owners retain volume leadership; Ride-Sharing Services holds the steepest expansion curve as platform fleets scale.
Coverage Area:
Geographic segmentation reflects Indonesia's archipelagic infrastructure reality, where claims verification workflows and repair network density vary dramatically between Java's primary corridors and Eastern provinces.
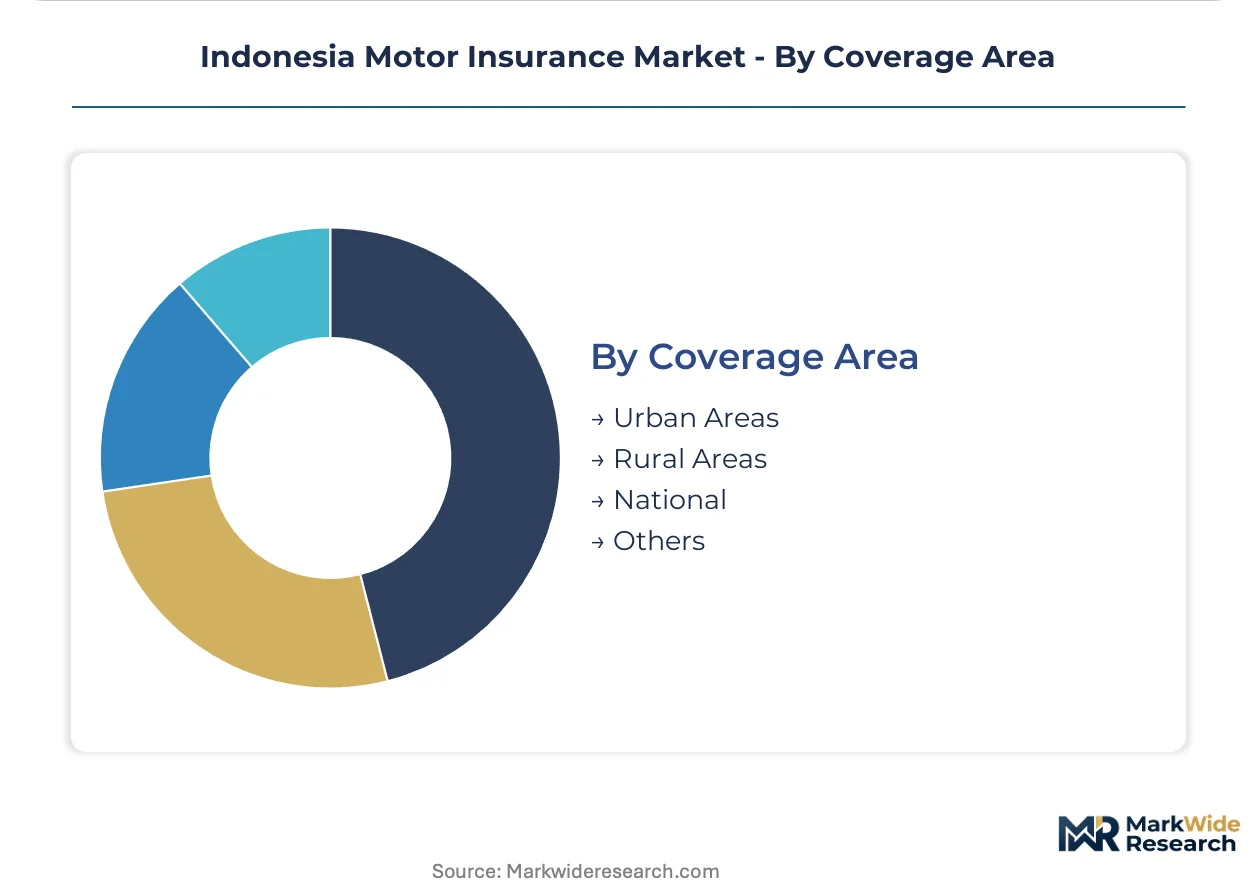
- Urban Areas:Concentrates premium volume in Greater Jakarta, Surabaya, and Bandung where vehicle density, accident rates, and 4G/5G telemetry coverage support advanced pricing models.
- Rural Areas:Spans Java's agricultural zones and outer island provinces where traditional broker networks resist digital protocols and motorcycle TPL dominates policy issuance.
- National:Territory-agnostic coverage for commercial fleets and high-mobility individuals, commanding premium loadings for Eastern Indonesia's sparse repair infrastructure.
- Others:Specialized territorial arrangements including cross-border coverage for Borneo's Malaysia-Indonesia transit corridors and Papua's resource extraction vehicle pools.
Urban Areas retains volume leadership; National holds the steepest expansion curve as fleet operators seek territory-unified protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OJK's compulsory TPL enforcement and digital distribution mandates are redistributing premium volumes across Indonesia's archipelagic markets, with infrastructure density and vehicle ownership patterns determining competitive access.
Greater Jakarta
Commercial fleet operators and ride-hailing platforms concentrate vehicle assets in Jakarta, Bogor, Depok, Tangerang, and Bekasi. OJK's sandbox framework permits algorithmic pricing experiments here before broader licensing. Telematics-enabled usage-based products penetrate fastest in this corridor where 4G/5G coverage supports real-time telemetry.
East Java
Surabaya anchors premium volumes through high vehicle density and accident rates sustaining comprehensive coverage demand. Financier-mandated policies for leased vehicles dominate Surabaya's collateralized auto markets. Traditional broker networks retain grip in rural hinterlands where digital onboarding meets resistance.
Central Java
Semarang and Yogyakarta manufacturing zones generate commercial fleet demand from logistics operators serving e-commerce fulfillment networks. OJK's enforcement tightening expands compulsory TPL addressable base beyond Java's primary cities. Budget-tier motorcycle coverage dominates policy issuance in agricultural zones.
Sulawesi
Makassar and Manado present underinsured motorcycle populations with rising disposable income trajectories. Sparse repair infrastructure and uneven data coverage constrain telematics deployment. Traditional agent channels remain captive to rural distribution protocols resistant to digital transformation.
Papua
Resource extraction vehicle pools in Timika and Jayapura require territory-agnostic national coverage with premium loadings for infrastructure gaps. Cross-border transit corridors into Papua New Guinea create specialized territorial arrangements. Claims verification workflows face documentation protocol challenges from regional police capacity constraints.
Indonesia Motor Insurance Market Competitive Landscape
Player mix skews toward diversified financial conglomerates with captive distribution networks and specialized general insurers with loss-control expertise. Market structure concentrates around three archetypes: automotive group captives leveraging dealership attachment points, diversified global insurers with telematics underwriting capabilities, and domestic multi-line carriers with government account relationships. Dominant competitive moves include embedded insurance integration at OEM transaction points and multi-year loss-control contracting for commercial fleet accounts.
Among automotive-captive insurers, PT Asuransi Astra Buana leverages its dealership network to dominate new-vehicle policy attachment. Zurich Asuransi Indonesia represents the global specialist archetype with advanced telematics underwriting models. MSIG Insurance Indonesia anchors the domestic multi-line tier with commercial fleet loss-control contracts. These three exemplify how distribution control, pricing sophistication, and account tenure respectively secure competitive position.
| Leading Market Players |
|---|
| PT Jasa Raharja (Persero) |
| Zurich Asuransi Indonesia |
| PT Asuransi Astra Buana |
| MSIG Insurance Indonesia |
| Oona Indonesia |
| Asuransi Sinar Mas |
| Allianz Utama Indonesia |
| AXA Mandiri Financial Services |
| PT Asuransi Central Asia |
| Others |
Supply & Pricing Matrix
Thirty-to-forty-five-day claims settlement cycles in Greater Jakarta compress working capital requirements for insurers while amplifying pricing power for those with integrated repair networks and BI Fast payment infrastructure.
Pricing Analysis
Certification level under OJK's Bancassurance and Digital Channel Distribution rules creates the primary spread between premium tiers. Contract-based annual pricing dominates comprehensive coverage for leased vehicles, while usage-based per-kilometer models penetrate ride-hailing fleets. Price differentiation rests on telematics adoption and loss-control contract tenure. Cost compression in budget-tier motorcycle TPL is intensifying because spare parts import dependency erodes margins. Rural individual owners exhibit highest price sensitivity; commercial fleet operators with multi-year contracts show lowest.
Supply Chain Analysis
Jakarta-Surabaya repair network density underwrites national coverage pricing for Eastern Indonesia policies. Parts sourcing concentrates in Japan, South Korea, and Thailand for OEM-certified components, with aftermarket alternatives from China and India feeding budget-tier claims. Raw material dependencies span steel alloys, electronic sensors, and imported paint finishes. Single-source vulnerability runs through proprietary telematics hardware from limited suppliers. Distribution runs through captive dealership networks, independent broker channels, and embedded ride-hailing app integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as e-commerce logistics fleet expansion drives commercial premium volumes after pandemic-era contraction.
For Market Incumbents: Shield comprehensive product margins by deepening captive repair network integration and accelerating telematics-enabled risk selection. OJK's digital distribution mandates threaten traditional broker commissions; counter by securing exclusive embedded partnerships with Astra Group dealerships and Gojek driver onboarding flows.
For New Entrants and Emerging Players: Differentiate on algorithmic pricing precision validated through OJK's sandbox framework. Sulawesi and Papua's underinsured motorcycle populations present the most penetrable geography; enter through mobile-first TPL distribution partnerships with regional banks lacking in-house insurance capabilities.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because OJK's capital adequacy requirements and compliance certification cycles favor scaled balance sheets over fragmented broker networks. Target domestic multi-line carriers with government fleet account tenure and nascent telematics capabilities. Watch BI Fast payment rail adoption rates as the signal for claims efficiency inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Deployment | Enables usage-based pricing for Gojek and Grab commercial fleets in Greater Jakarta. |
| OJK Sandbox Certification | Permits algorithmic pricing experiments bypassing historical tariff restrictions. |
| Embedded Insurance Integration | Captures policy attachment at Astra dealership transaction points. |
| BI Fast Payment Rail Adoption | Accelerates premium collection and claims settlement velocity. |
| Eastern Indonesia Distribution Partnership | Unlocks Sulawesi and Papua motorcycle TPL expansion through regional banking channels. |
Research Methodology
A spread of perspectives from underwriting directors, actuarial heads, OJK regulatory officers, and commercial fleet procurement managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against OJK circulars, BI Fast infrastructure disclosures, and regional insurance association statistical releases. Bottom-up policy volume estimates triangulated against top-down premium aggregate data.
Segmentation dimensions modeled span policy type, premium tier, customer archetype, and geographic coverage area across the projection horizon. CAGRs derive from loss ratio trend analysis, telematics penetration curves, and regulatory enforcement phase-in schedules. Forecast inputs incorporate OJK digital distribution mandate compliance timelines and e-commerce logistics fleet expansion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained BI Fast adoption and stable OJK regulatory enforcement would require recalibration. Forecasts reflect assumptions about telematics hardware cost curves and spare parts import tariff stability. Practitioners should keep alternative scenarios live as OJK sandbox licensing velocity and Eastern Indonesia infrastructure buildout evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Canada Motor Insurance Market