
 Vietnam Motor Insurance Market | 2026-2036
Vietnam Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Motor Insurance Market Analytics
Market Context
A widening capital-reserve gap between state-linked and foreign-backed carriers is reorganizing competitive hierarchy in Vietnam's motor insurance sector. Bao Viet Insurance Corporation leverages its expansive agency network to sustain dominance in rural provinces where agent density exceeds foreign rivals. Tokio Marine Insurance Vietnam Co. Ltd. anchors its position through advanced actuarial modeling that differentiates pricing across risk tiers. PVI competes on petroleum-sector fleet relationships, while MSIG Insurance (Vietnam) Co. Ltd. specializes in digital-first distribution channels targeting urban motorcycle owners.
Technical Definition and Segments
Vietnam motor insurance constitutes a risk-transfer contract indemnifying policyholders against financial loss from vehicle damage, third-party bodily injury, or theft, with compulsory third-party liability mandated by law for all registered vehicles operating on public roads. The product serves primarily to protect asset values and satisfy legal obligations while providing collision coverage, personal accident benefits, and fire protection as optional extensions. Comprehensive coverage commands the thickest margin pool as affluent owners of passenger cars and electric vehicles seek full-protection policies beyond statutory minimums. Motorcycle policies generate the highest absolute premium volume given Vietnam's fleet of over seventy million two-wheelers, though per-unit margins remain compressed due to intense price competition. Corporate and fleet owner segments represent the fastest-growing customer category as logistics operators centralize coverage under negotiated master policies.
Regulatory Framework
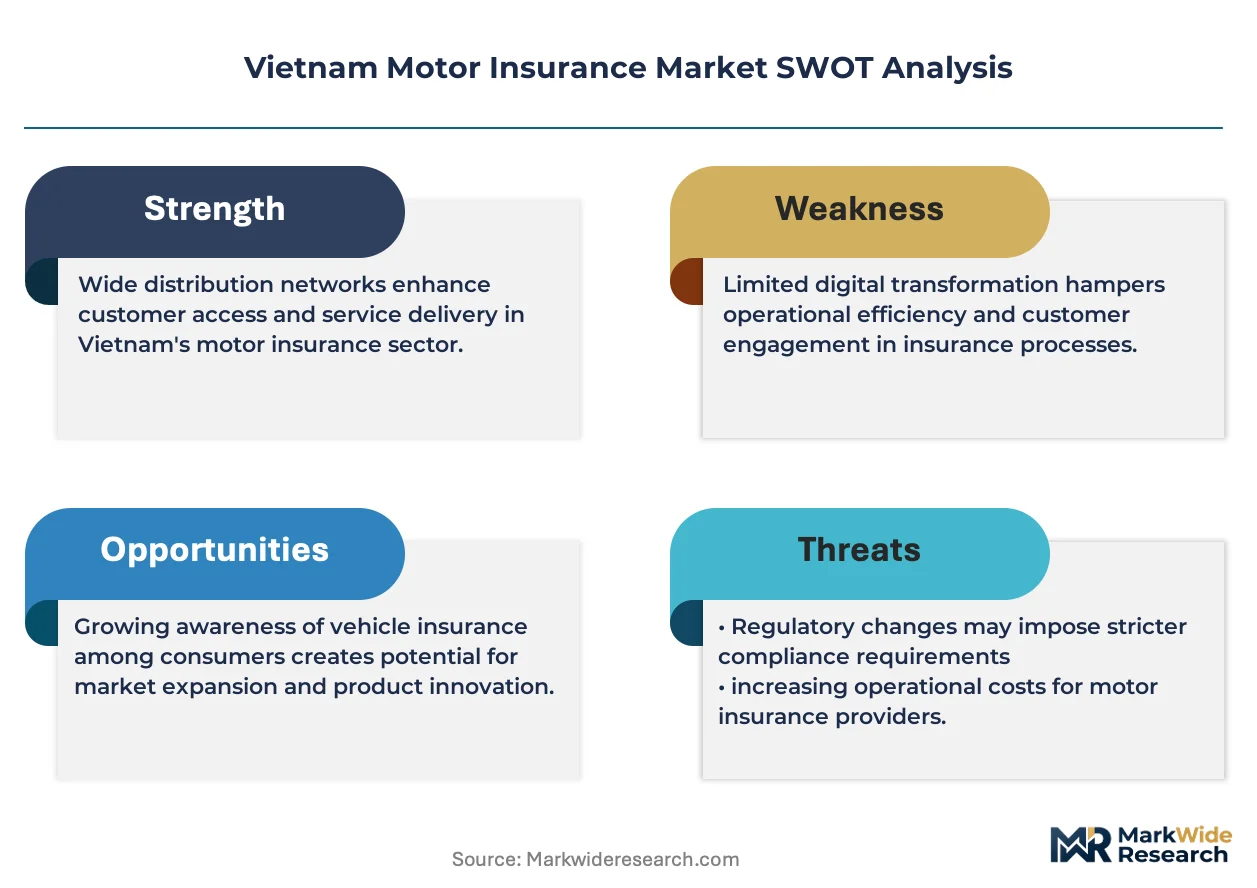
The Ministry of Finance and Vietnam Insurance Association supervise solvency requirements and compulsory motor insurance rate tables, while the National Financial Supervisory Commission monitors market conduct and claims settlement practices. Decree 03/2021/ND-CP strengthened enforcement mechanisms, linking vehicle registration renewal to proof of active third-party liability coverage and expanding penalties for uninsured operation. Stakeholders must monitor how proposed amendments to the Law on Insurance Business reshape foreign ownership caps and digital distribution licensing, as these provisions will determine whether incumbent state-linked insurers retain structural advantages or face accelerated competitive pressure from technology-enabled entrants.
Market Dynamics
Decree 03/2021/ND-CP is tightening enforcement of compulsory motor insurance across Vietnam, linking registration renewal to active coverage and expanding penalties for uninsured operation. This regulatory pressure is compressing informal risk pools and accelerating formalization of the seventy-million-vehicle fleet.
Growth Catalysts
- Urban Motorcycle Commuters:Ho Chi Minh City and Hanoi account for the densest vehicle concentrations, where accident frequency and asset protection needs sustain premium volume growth.
- Decree 03/2021/ND-CP:Vietnam's Ministry of Finance mandates proof of third-party liability for registration renewal, converting previously uninsured operators into policyholders.
- Logistics Fleet Centralization:Corporate operators are consolidating coverage under master policies, expanding negotiated commercial accounts beyond individual retail sales.
Market Restraints
- Compressed Per-Unit Margins:Motorcycle policies generate volume but face intense price competition among state-linked and foreign-backed carriers, limiting profitability on the dominant product line.
- Rural Agency Network Concentration:Bao Viet Insurance Corporation maintains expansive agent density in provinces outside major cities, creating distribution barriers for digital-first competitors.
- Actuarial Data Asymmetry:Foreign insurers with advanced risk modeling capabilities capture preferred risk tiers, leaving state-linked carriers with adverse selection in standard segments.
Strategic Opportunities
- Electric Vehicle Penetration:Affluent owners of battery-powered passenger cars seek full-protection comprehensive policies beyond statutory minimums, opening premium-margin segments.
- Digital Distribution Licensing:Proposed amendments to the Law on Insurance Business may enable technology-enabled entrants to bypass traditional agency networks in urban centers.
- Petroleum-Sector Fleet Relationships:Energy infrastructure operators require specialized commercial coverage, creating sticky accounts with multi-year contract potential.
Industry Challenges
- Claims Settlement Infrastructure:The National Financial Supervisory Commission monitors market conduct, yet processing capacity lags behind policy growth, creating customer friction.
- Legacy System Integration:State-linked carriers face technical debt when connecting traditional agency networks to emerging digital distribution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Motor Insurance Market |
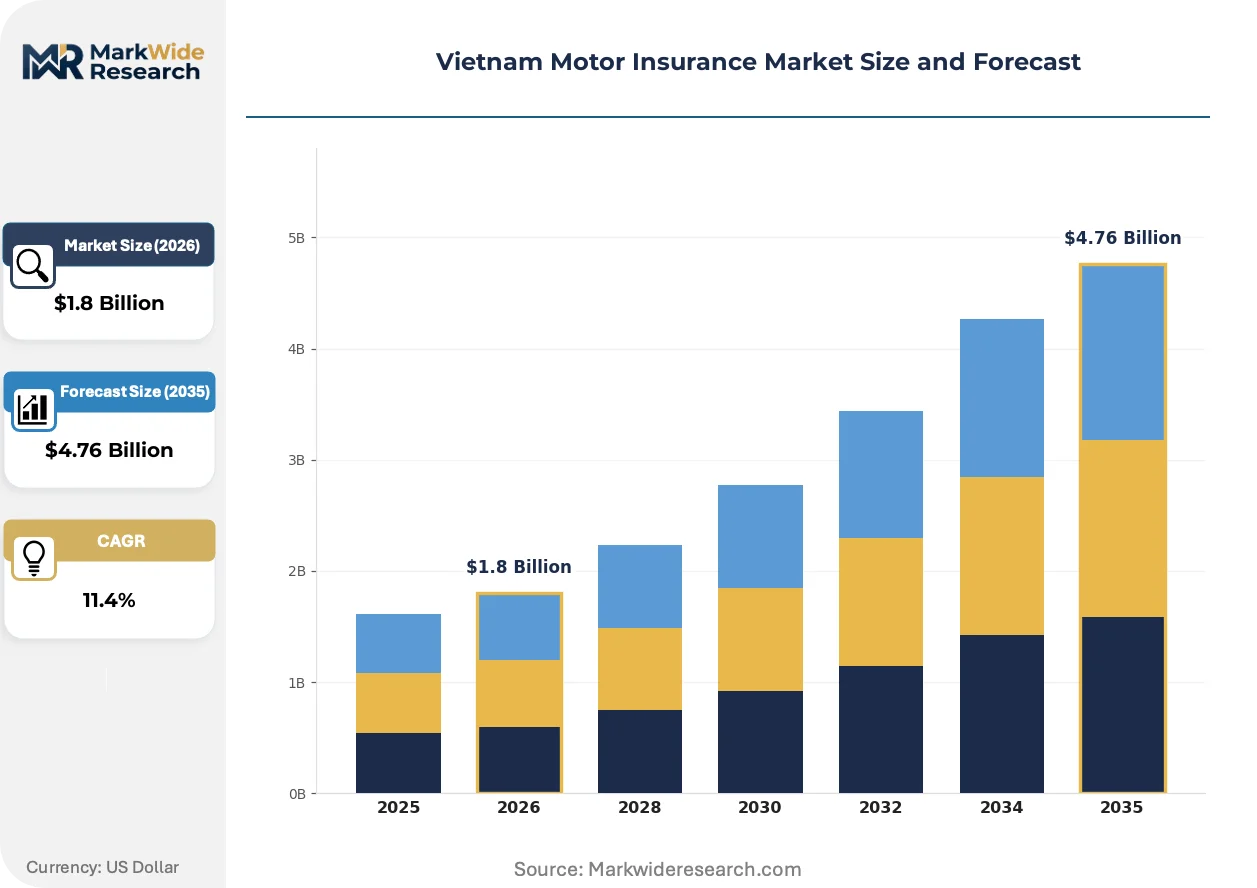
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Third Party Liability, Comprehensive, Fire and Theft, Personal Accident Vehicle Type: Passenger Car, Motorcycle, Commercial Vehicle, Electric Vehicle Customer Type: Individual, Fleet Owner, Corporate, Government Distribution Channel: Broker, Direct Sales, Online, Agents |
| Companies Covered | Post & Telecommunication Insurance Corporation (PTI), Liberty Insurance Ltd., PetroVietnam Insurance (PVI), MSIG Insurance (Vietnam) Co. Ltd., AIG Vietnam Insurance Co. Ltd., Bao Viet Insurance Corporation, BIDV Insurance Corporation (BIC), Tokio Marine Insurance Vietnam Co. Ltd., Bao Minh Insurance Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Motor Insurance Market Evolving Landscape
Telematics-enabled risk assessment is fragmenting traditional pricing models across Vietnam's motor insurance sector. Three developments are restructuring how carriers underwrite, distribute, and compete.
Usage-based insurance technology is fragmenting actuarial assumptions that previously relied on static demographic proxies. Tokio Marine Insurance Vietnam and MSIG Insurance are piloting smartphone-integrated driving behavior monitoring for urban motorcycle owners. This data granularity is fragmenting risk pools into micro-segments, compressing cross-subsidies between safe and hazardous drivers.
Decree 03/2021/ND-CP is tightening enforcement mechanisms that link vehicle registration renewal to proof of active third-party liability coverage. The Ministry of Finance expanded penalties for uninsured operation, converting informal vehicle operators into formal policyholders. Motorcycle owners in Ho Chi Minh City and Hanoi face the strictest compliance scrutiny, driving digital policy issuance through mobile platforms.
Aggregator platforms are compressing distribution margins that previously sustained extensive agent networks. Urban motorcycle owners increasingly compare quotes through digital marketplaces before purchase, displacing traditional agency relationships. This channel shift concentrates price transparency in metropolitan Vietnam, where smartphone penetration and digital literacy enable platform adoption.
Vietnam Motor Insurance Market Segmentation
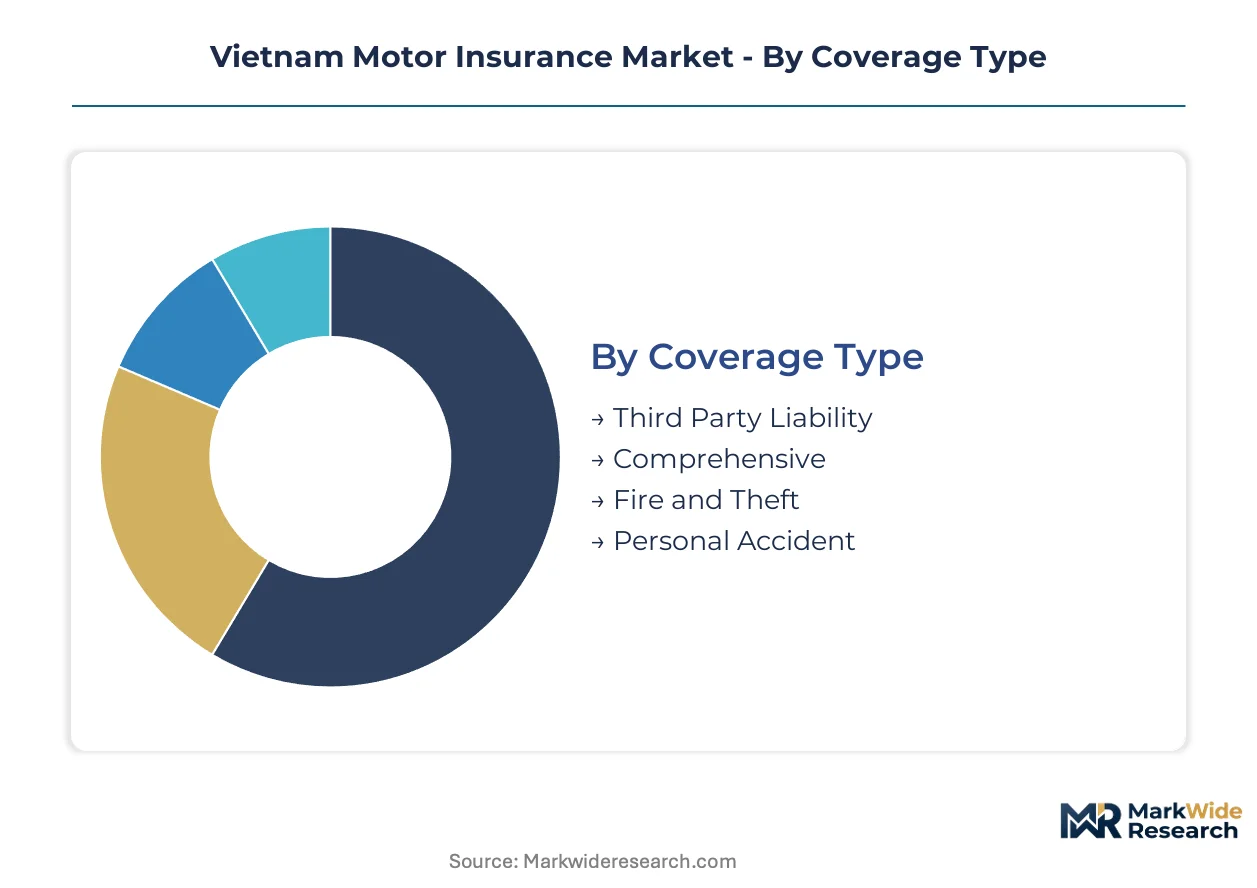
Vietnam's motor insurance segmentation reflects the collision between regulatory mandates and evolving mobility patterns. Coverage categories, vehicle types, and distribution channels each face distinct substitution pressures as digital platforms and alternative risk-transfer mechanisms reshape customer behavior.
Coverage Type:
Third-party liability faces the strongest substitution threat from informal risk pools and self-insurance arrangements among price-sensitive motorcycle owners, while comprehensive coverage commands loyalty through asset protection value.
- Third Party Liability:Statutorily mandated coverage indemnifies against bodily injury and property damage to third parties. Ho Chi Minh City and Hanoi drive enforcement compliance, where vehicle density and traffic police presence convert uninsured operators into policyholders under Decree 03/2021/ND-CP.
- Comprehensive:Full-protection policies covering own-vehicle damage, theft, and collision attract affluent passenger car and electric vehicle owners seeking asset value preservation. Urban centers concentrate demand as rising disposable incomes expand the addressable base beyond statutory minimums.
- Fire and Theft:Optional extension targeting commercial vehicle operators and fleet owners in petroleum-sector logistics.
- Personal Accident:Rider protection add-on gaining traction among motorcycle commuters facing elevated injury risk.
Third-party liability anchors the volume base while comprehensive coverage gains share at the steepest rate.
Vehicle Type:
Pricing stratification across vehicle categories mirrors risk differentiation and repair cost structures, with motorcycle policies facing the most acute margin compression.
- Motorcycle:Dominant vehicle class with over seventy million registered units generating the highest absolute premium volume. Ho Chi Minh City and Hanoi concentrate fleet density, though per-unit margins remain thin due to intense price competition among state-linked and foreign-backed carriers.
- Passenger Car:Four-wheeled private vehicles command thicker margins as owners seek comprehensive protection for higher asset values. Urban affluent households drive policy uptake, with telematics-enabled pricing pilots emerging among technology-forward insurers.
- Commercial Vehicle:Fleet operators in logistics and petroleum sectors consolidate coverage under negotiated master policies.
- Electric Vehicle:Battery-powered passenger cars attract full-protection comprehensive demand from early-adopter households.
Motorcycle policies anchor the volume base while electric vehicle coverage expands most quickly as battery-powered adoption accelerates.
Customer Type:
Procurement patterns diverge sharply between individual retail purchasers and institutional buyers with centralized negotiation leverage.
- Individual:Retail policyholders purchasing single-vehicle coverage through agent networks or digital platforms. Urban motorcycle commuters in Hanoi and Ho Chi Minh City dominate this segment, where aggregator platforms are displacing traditional agency relationships.
- Fleet Owner:Logistics operators managing multiple commercial vehicles under unified coverage arrangements. Petroleum-sector relationships create sticky accounts with multi-year contract potential and specialized risk requirements.
- Corporate:Non-logistics enterprises centralizing employee vehicle coverage under group policies.
- Government:Public sector fleet procurement through mandated tender processes.
Individual customers anchor the volume base while fleet owners climb the fastest as logistics centralization accelerates.
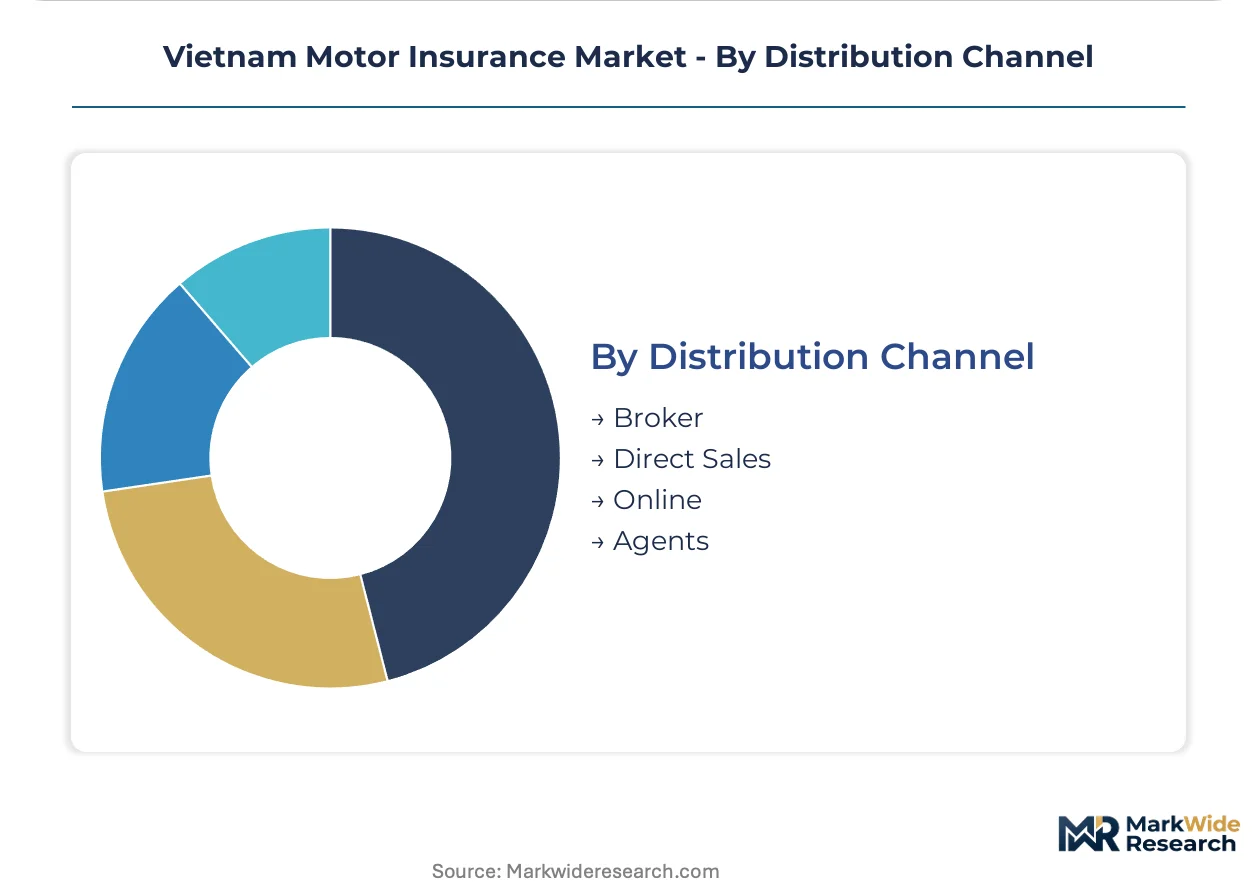
Distribution Channel:
Channel economics are restructuring as digital penetration fragments the agency-network dominance that state-linked carriers historically leveraged.
- Agents:Traditional intermediary networks maintain rural province penetration where Bao Viet Insurance Corporation exceeds foreign rivals in representative density. Legacy system integration challenges constrain technology-enabled competitors in these territories.
- Online:Direct digital issuance and policy management targeting smartphone-enabled urban motorcycle owners. Ho Chi Minh City and Hanoi concentrate adoption, where proposed amendments to the Law on Insurance Business may expand licensing scope for technology-enabled entrants.
- Broker:Independent intermediaries serving commercial and corporate accounts with negotiated terms.
- Direct Sales:Carrier-owned channels bypassing intermediaries for cost efficiency.
Agent networks anchor the volume base while online distribution gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across Vietnam's motor insurance landscape. Urban motorcycle commuters in major metros exhibit high sensitivity to premium differentials, while affluent passenger car owners in emerging districts prioritize comprehensive coverage regardless of cost.
Ho Chi Minh City
Vehicle density and accident frequency concentrate premium volume in Vietnam's commercial capital. The Ministry of Finance enforces Decree 03/2021/ND-CP through registration renewal checkpoints, converting uninsured operators into policyholders. District 1 and District 7 host the densest aggregator platform adoption, where smartphone-enabled quote comparison displaces traditional agency relationships.
Hanoi
Traffic police presence and administrative enforcement sustain compulsory coverage compliance in the northern hub. The National Financial Supervisory Commission monitors claims settlement practices here with particular scrutiny. Cau Giay and Hai Ba Trung districts concentrate digital-first insurer penetration among young motorcycle commuters.
Da Nang
Rising disposable incomes expand comprehensive policy uptake among passenger car owners in this central coastal city. Provincial authorities implement vehicle registration linkage to insurance coverage with moderate enforcement intensity. The Hai Chau and Son Tra districts attract telematics-enabled pricing pilots from technology-forward carriers.
Dong Nai Province
Industrial corridor logistics operators centralize fleet coverage under negotiated master policies near Bien Hoa city. The Ministry of Transport coordinates with insurers on commercial vehicle safety inspections tied to policy validity. Nhon Trach district hosts petroleum-sector fleet concentrations requiring specialized risk arrangements.
Binh Duong Province
Manufacturing zone expansion drives corporate vehicle coverage growth in this southern industrial belt. Provincial finance departments enforce third-party liability mandates through enterprise registration systems. Thu Dau Mot city anchors agent network density where state-linked carriers maintain rural penetration advantages.
Vietnam Motor Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Vietnam's motor insurance sector. Foreign-backed carriers deploy advanced actuarial modeling and digital distribution platforms, while state-linked insurers leverage expansive agency networks for cost-efficient rural penetration. Three archetypes dominate: technology-enabled precision underwriters, scale-driven state-linked incumbents, and petroleum-sector relationship specialists. Competitive dynamics center on digital licensing expansion and fleet account consolidation under master policies.
Among foreign-backed precision underwriters, Tokio Marine Insurance Vietnam Co. Ltd. and MSIG Insurance (Vietnam) Co. Ltd. exemplify the technology-enabled archetype, while PetroVietnam Insurance (PVI) occupies a position within the energy-sector relationship tier. Bao Viet Insurance Corporation anchors the state-linked scale archetype with representative density advantages in provincial territories outside major urban centers.
| Leading Market Players |
|---|
| Post & Telecommunication Insurance Corporation (PTI) |
| Liberty Insurance Ltd. |
| PetroVietnam Insurance (PVI) |
| MSIG Insurance (Vietnam) Co. Ltd. |
| AIG Vietnam Insurance Co. Ltd. |
| Bao Viet Insurance Corporation |
| BIDV Insurance Corporation (BIC) |
| Tokio Marine Insurance Vietnam Co. Ltd. |
| Bao Minh Insurance Corporation |
| Others |
Value Network & Pricing Analysis
Annual premium contracts lock in coverage commitments for Vietnamese motorcycle owners while capping insurer exposure to claims volatility. This structure binds policyholders to fixed-rate obligations across twelve-month terms, enabling carriers to project revenue streams and manage reserve adequacy against the seventy-million-vehicle fleet.
Pricing Analysis
After-sales service revenue from claims processing and policy renewals drives lifetime customer value beyond initial premium capture. Three-tier pricing structure across premium, standard, and economy levels stratifies motorcycle coverage in Ho Chi Minh City and Hanoi, where accident frequency and enforcement intensity concentrate demand. Cost compression in economy tiers intensifies because state-linked carriers compete aggressively for volume share among price-sensitive urban commuters. Fleet owners in petroleum-sector logistics exhibit the lowest price sensitivity, negotiating multi-year master policies with embedded service guarantees.
Supply Chain Analysis
Just-in-time policy issuance dominates digital distribution channels serving smartphone-enabled motorcycle owners, while strategic stockpiling of actuarial reserve capital anchors solvency compliance. Reinsurance capacity draws from Singapore, Japan, and regional Lloyd's syndicates to backstop Vietnamese carrier exposures. Raw material dependencies center on claims settlement infrastructure, medical cost inflation indices, and spare parts procurement networks. Single-source vulnerability concentrates in Bao Viet's rural agency network, where representative density exceeds foreign rivals. Distribution runs through hybrid channels blending legacy agent relationships with emerging aggregator platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's motor insurance sector is entering a cyclical recovery phase as Decree 03/2021/ND-CP enforcement converts informal vehicle operators into formal policyholders, expanding the addressable base beyond historical penetration ceilings.
For Market Incumbents: Shield rural province dominance by hardening Bao Viet's agent network exclusivity through technology-enabled productivity tools rather than headcount expansion. Deepen backward integration into claims settlement infrastructure to reduce third-party processing friction that erodes customer retention. Prioritize certification investment in telematics-enabled risk modeling to match Tokio Marine's precision underwriting capabilities before foreign carriers capture preferred risk tiers. For New Entrants and Emerging Players: Differentiate on digital-first distribution targeting urban motorcycle commuters in District 1 and District 7 of Ho Chi Minh City, where aggregator platform adoption displaces traditional agency relationships. Penetrate the electric vehicle comprehensive coverage segment in Da Nang's Hai Chau district, where affluent early adopters seek full-protection policies beyond statutory minimums and incumbent presence remains thin. Deploy smartphone-integrated policy issuance as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward petroleum-sector fleet relationship specialists with sticky multi-year contract structures and specialized risk expertise. Long-term viability hinges on regulatory licensing expansion under proposed Law on Insurance Business amendments that may enable technology-enabled entrants to bypass traditional agency networks. Watch for inflection when digital distribution licensing thresholds cross implementation, signaling accelerated competitive pressure on state-linked incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Enabled Risk Pricing | Tokio Marine and MSIG pilots fragment actuarial assumptions through smartphone driving behavior monitoring. |
| Digital Distribution Licensing | Proposed Law on Insurance Business amendments may expand technology-enabled entrant access to urban centers. |
| Fleet Account Consolidation | Logistics operators in Dong Nai and Binh Duong centralize coverage under negotiated master policies. |
| Electric Vehicle Coverage Expansion | Da Nang and Hanoi early adopters seek comprehensive protection for battery-powered passenger cars. |
| Rural Agency Network Technology Integration | State-linked carriers face technical debt connecting legacy representatives to emerging digital platforms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with insurance product managers, agency network directors, claims processing executives, and regulatory affairs specialists at the Ministry of Finance. Secondary validation drew from Vietnam Insurance Association statistical releases, National Financial Supervisory Commission market conduct reports, Decree 03/2021/ND-CP regulatory filings, and vehicle registration databases. Bottom-up policy volume estimates triangulated against top-down premium projections across the analysis window.
Across the modeling period, forecasts incorporate coverage type segmentation, vehicle class stratification, customer type procurement patterns, and distribution channel evolution. CAGRs were derived from regression analysis of historical premium growth correlated with enforcement intensity metrics and fleet expansion trajectories. Model inputs include motorcycle ownership density indices, electric vehicle adoption curves, and logistics fleet centralization rates.
Material uncertainties — regulatory amendments to foreign ownership caps, digital licensing scope, and claims inflation volatility — sit outside the modeled envelope. Forecasts reflect assumptions about sustained Decree 03/2021/ND-CP enforcement and stable reinsurance capacity availability. Revision becomes warranted when telematics adoption rates or aggregator platform penetration cross thresholds that fundamentally restructure distribution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
Indonesia Motor Insurance Market