
 Japan Motor Insurance Market | 2026-2036
Japan Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Motor Insurance Market Foresight
Telematics-driven usage-based insurance is reshaping how Japanese carriers price risk and manage claims workflows. Tokio Marine & Nichido Fire Insurance leverages extensive agent networks to sustain traditional distribution dominance in rural prefectures. MS&AD Insurance Group Holdings anchors its competitive stance through advanced data analytics platforms that refine loss ratios. Rakuten General Insurance competes aggressively on digital-first customer acquisition, while Sompo Japan Insurance specializes in commercial fleet solutions for enterprise clients.
Japan motor insurance constitutes a contractual risk-transfer mechanism covering physical damage, third-party liability, and personal injury arising from vehicle operation, with policies structured around statutory minimums and supplemental voluntary coverage tiers. The product serves to indemnify policyholders against financial losses from traffic incidents while ensuring legal compliance with Japan's Automobile Liability Security Act. Compulsory policy types retain structural importance as the legally mandated foundation, though comprehensive coverage generates superior margin pools through broader risk transfer and cross-selling opportunities. Online distribution channels represent the fastest-growing segment as smartphone penetration and regulatory sandbox approvals from Japan's Financial Services Agency accelerate direct-to-consumer platform adoption.
METI's digital transformation guidelines and the Financial Services Agency's insurtech sandbox framework together shape product innovation timelines and market entry pathways for technology-enabled underwriters. JIS standards for vehicle safety systems indirectly influence claim frequency assumptions embedded in actuarial models. Stakeholders must monitor how autonomous vehicle liability frameworks evolve under Japan's Road Traffic Act amendments and whether captive supply of telematics data from domestic automakers alters competitive dynamics between traditional carriers and platform-native entrants.
Market Dynamics
Telematics integration is compressing traditional risk assessment cycles across Japan's motor insurance sector, forcing carriers to rebuild pricing models around real-time driving data rather than static demographic proxies. METI's digital transformation guidelines accelerate this structural shift by mandating interoperability standards for vehicle-connected platforms.
Growth Catalysts
- Commercial Fleet Expansion:Logistics operators across Honshu and Kyushu are consolidating vehicle procurement, creating concentrated demand pools for bundled coverage products with telematics-enabled loss prevention services.
- METI Sandbox Framework:Japan's Ministry of Economy, Trade and Industry has established regulatory pathways for insurtech platforms to trial usage-based pricing models, lowering barriers for technology-native entrants.
- Smartphone Penetration:Direct-to-consumer distribution channels are capturing policyholder relationships previously held by agent networks, particularly among younger demographics in metropolitan prefectures.
Market Restraints
- Agent Network Entrenchment:Rural prefectures retain deep dependency on face-to-face policy issuance, creating friction for digital-first distribution models seeking national scale.
- Telematics Data Access:Domestic automakers maintain captive control over vehicle-generated data streams, limiting carrier independence in risk model development.
- Compulsory Coverage Margins:Statutory minimum policies under Japan's Automobile Liability Security Act operate under regulated rate structures that constrain underwriting profitability.
Strategic Opportunities
- Autonomous Vehicle Liability:Road Traffic Act amendments will require new coverage frameworks for driver-assist and self-driving systems, creating first-mover advantages for specialized product developers.
- Kyushu Logistics Corridors:Underpenetrated commercial fleet markets in southern Japan offer expansion potential as port modernization drives freight volume concentration.
- Cross-Selling Integration:Property and casualty carriers can bundle motor coverage with home insurance through unified digital platforms, capturing household-level risk relationships.
Industry Challenges
- Actuarial Talent Scarcity:Traditional pricing teams lack expertise in machine learning model validation, creating execution gaps as carriers deploy AI-driven underwriting engines.
- Legacy System Integration:Core policy administration platforms require costly middleware development to connect with telematics data pipelines and mobile distribution interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Motor Insurance Market |
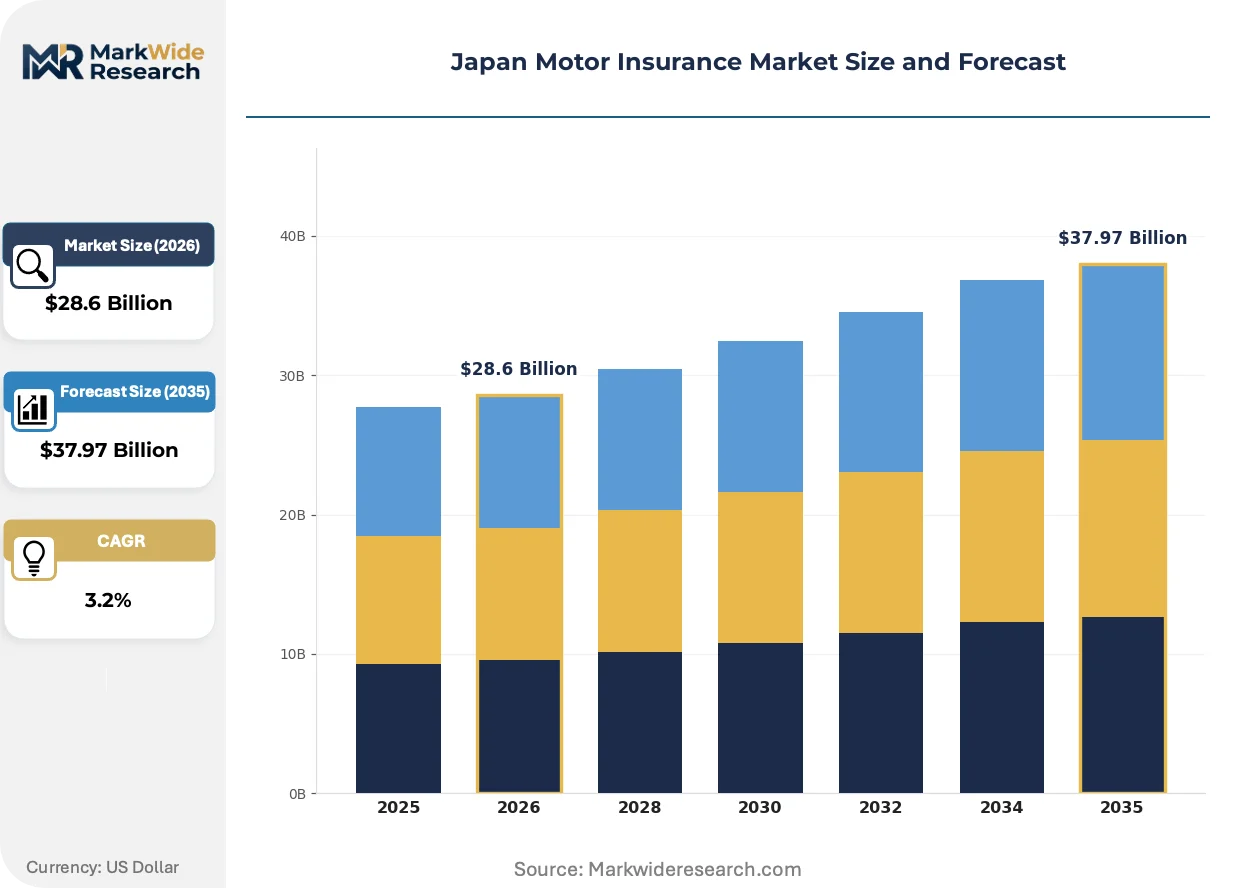
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $37.97 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Compulsory, Third Party, Comprehensive, Collision Coverage Level: Full, Partial, Limited, Excess Customer Type: Individual, Fleet, Commercial, Affinity Group Distribution Channel: Direct, Agents, Brokers, Online |
| Companies Covered | Aioi Nissay Dowa Insurance Co., Ltd., SBI Insurance Co., Ltd., Tokio Marine & Nichido Fire Insurance Co., Ltd., Sony Assurance Inc., Rakuten General Insurance Co., Ltd., Sompo Japan Insurance Inc., Mitsui Direct General Insurance Co., Ltd., Chubb Insurance Japan, MS&AD Insurance Group Holdings, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Motor Insurance Market Shifts & Advancements
Japanese motor carriers are rebuilding their technology stacks around data-centric risk assessment, abandoning decades-old pricing methodologies in favor of dynamic, behavior-linked models. This transformation spans product design, distribution architecture, and regulatory engagement.
Usage-based insurance platforms are migrating from experimental pilots to standard product offerings across major metropolitan prefectures. Commercial fleet operators in the Greater Tokyo Area are adopting these programs fastest, driven by fuel cost visibility and driver safety incentives. Real-time premium adjustment is compressing traditional annual policy cycles into monthly or per-mile billing structures.
METI's insurtech sandbox approvals are reshaping product launch timelines by permitting controlled market trials outside standard filing requirements. Carriers can now test telematics-linked pricing with limited policyholder cohorts before full regulatory submission. Digital-native competitors are exploiting this pathway to outpace incumbent product development cycles.
Younger policyholders are abandoning agent-mediated purchasing in favor of smartphone-completed transactions, particularly for voluntary coverage add-ons. Direct-to-consumer platforms are capturing this behavioral shift through simplified quote engines and instant policy issuance. Rural-urban divides persist, with metropolitan buyers leading channel migration while prefectural agent networks retain loyalty among older demographics.
Japan Motor Insurance Market Segmentation
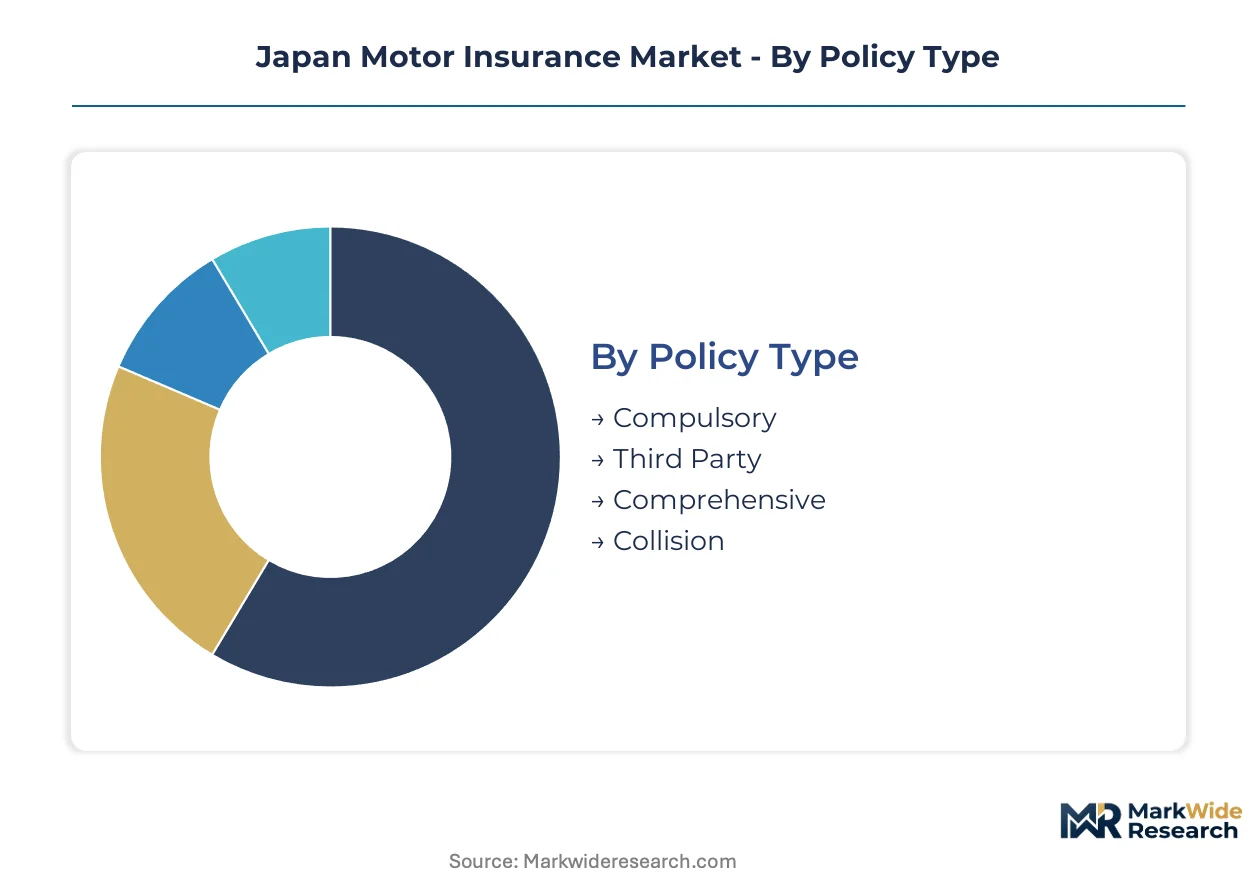
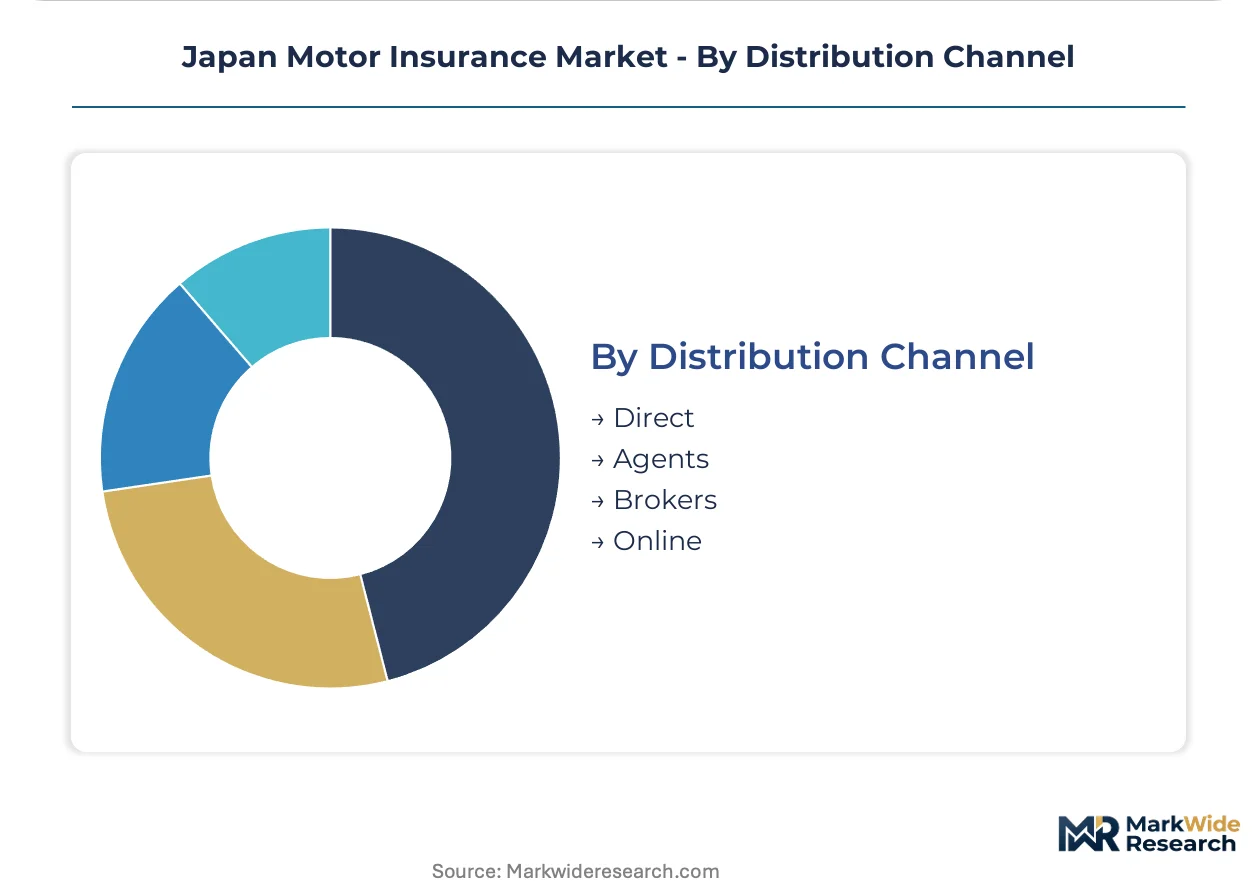
Japan's motor insurance market segments across policy structures, coverage depth, buyer categories, and distribution pathways. Each dimension shapes pricing mechanics, underwriting complexity, and carrier competitive positioning within METI's regulated framework.
Policy Type:
Policy structures span the use-case spectrum from statutory minimums to full asset protection, with each tier carrying distinct regulatory treatment and margin profiles.
- Compulsory:Statutorily mandated coverage under Japan's Automobile Liability Security Act establishes baseline third-party protection. Rural prefectures generate concentrated demand as older vehicle fleets require basic compliance without supplemental tiers.
- Third Party:Voluntary liability extensions beyond statutory floors address bodily injury and property damage to others. Fleet operators in the Greater Tokyo Area adopt this tier fastest as commercial registration requirements intensify.
- Comprehensive:Full-spectrum coverage combining liability, collision, and theft protection into unified contracts.
- Collision:Physical damage protection limited to policyholder vehicle repair costs, excluding third-party exposures.
Established volume favors Compulsory; emerging adoption favors Third Party.
Coverage Level:
Premium stratification follows buyer risk appetite and asset valuation, with cost tiers determining claim settlement protocols and deductible structures.
- Full:Zero-deductible protection with guaranteed OEM parts replacement and rental vehicle provisions. High-net-worth households in Osaka and Nagoya prefectures concentrate demand here, driven by luxury vehicle ownership and concierge service expectations.
- Partial:Moderate deductible thresholds with aftermarket parts allowances and capped rental benefits. Young professionals in Fukuoka and Sapporo favor this tier as smartphone-enabled quote comparison reduces friction for mid-market selection.
- Limited:High-deductible, narrow peril coverage with minimal auxiliary services.
- Excess:Catastrophic-layer protection activating above primary policy limits.
Margin concentration sits with Full; volume expansion tracks Partial.
Customer Type:
Buyer categories reflect vehicle ownership scale, operational purpose, and group affiliation, with each segment demanding specialized underwriting expertise and service infrastructure.
- Individual:Single-vehicle households purchasing personal transportation coverage through agent or digital channels. Metropolitan prefectures show fastest channel migration toward direct platforms as smartphone penetration climbs among younger demographics.
- Fleet:Multi-vehicle commercial operators requiring centralized policy administration and telematics integration. Logistics corridors across Honshu and Kyushu drive concentrated demand as port modernization expands freight volumes.
- Commercial:Single-vehicle business registrations including tradespeople and delivery services.
- Affinity Group:Employer-sponsored or association-linked coverage pools leveraging collective bargaining for rate concessions.
Underwriting sophistication concentrates in Fleet; policy count expansion favors Individual.
Distribution Channel:
Pathway architecture determines customer acquisition economics and relationship durability, with channel mix shifting under regulatory sandbox approvals and demographic turnover.
- Direct:Carrier-owned platforms bypassing intermediaries through call centers and proprietary websites. Rakuten General Insurance and digital-native entrants exploit this channel to capture younger policyholders in Tokyo and Yokohama metropolitan zones.
- Agents:Exclusive and independent representatives maintaining face-to-face policy issuance and claims advocacy. Rural prefectures retain deep dependency here as older demographics prize relationship continuity over price optimization.
- Brokers:Independent intermediaries comparing multiple carrier offerings for commercial accounts.
- Online:Third-party aggregators and insurtech platforms enabling instant quote comparison and policy binding.
Retention strength anchors with Agents; acquisition velocity climbs fastest through Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's motor insurance flows concentrate through domestic logistics corridors linking Honshu manufacturing clusters to Kyushu port facilities, with premium generation tracking vehicle density across metropolitan prefectures.
Kanto/Tokyo
The Greater Tokyo Area generates the highest premium volumes nationwide, driven by extreme vehicle density and commercial fleet concentration. METI's digital transformation guidelines accelerate telematics adoption among logistics operators headquartered in Tokyo and Yokohama. Chiba and Kanagawa prefectures host expanding distribution center networks that demand bundled fleet coverage with real-time risk monitoring.
Kansai/Osaka
Osaka Prefecture anchors western Japan's motor insurance demand through heavy commercial vehicle registration and port-related freight activity. The Financial Services Agency's insurtech sandbox approvals enable Osaka-based carriers to trial usage-based pricing models. Kyoto and Hyogo prefectures support this cluster with manufacturing supply chains requiring specialized commercial coverage.
Chubu/Nagoya
Aichi Prefecture's automotive manufacturing ecosystem creates concentrated demand for corporate fleet insurance and supplier logistics coverage. Toyota Motor Corporation's headquarters presence shapes local carrier product development around just-in-time delivery risk profiles. Nagoya's port modernization drives freight volume expansion and corresponding commercial policy growth.
Kyushu
Fukuoka Prefecture leads southern Japan's underpenetrated commercial fleet market as port infrastructure upgrades attract logistics investment. METI's regional development initiatives support telematics integration for trucking operators serving Honshu-Kyushu freight corridors. Saga and Nagasaki prefectures present expansion opportunities as manufacturing supply chains extend southward.
Hokkaido
Hokkaido's severe winter conditions sustain demand for comprehensive physical damage coverage with specialized peril provisions. Sapporo's urban density contrasts with rural prefectures where agent-mediated distribution retains dominance. Cold-weather accident frequency supports premium pricing power for carriers with localized underwriting expertise.
Japan Motor Insurance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Japan's motor insurance sector, creating a tiered structure where scale advantages fragment along distribution and technology vectors. Tokio Marine & Nichido Fire Insurance and MS&AD Insurance Group Holdings anchor the upper tier through extensive agency networks and data analytics infrastructure. Three strategic archetypes dominate: legacy carriers with captive agent systems, digital-native platforms exploiting smartphone distribution, and commercial fleet specialists embedding telematics services. Competitive moves center on METI sandbox partnerships for usage-based product trials and cross-selling integration with property coverage lines.
Among Japan-based incumbents, Tokio Marine & Nichido Fire Insurance, MS&AD Insurance Group Holdings, and Sompo Japan Insurance occupy positions within the traditional carrier archetype, each representing different strategic emphases on rural agency penetration versus metropolitan digital adoption. Rakuten General Insurance exemplifies the digital-native challenger model, while Sony Assurance Inc. anchors technology-forward positioning. These five entities collectively illustrate the competitive spectrum from legacy distribution dominance to platform-native customer acquisition, with no single player commanding decisive share across all segments and channels.
| Leading Market Players |
|---|
| Aioi Nissay Dowa Insurance Co., Ltd. |
| SBI Insurance Co., Ltd. |
| Tokio Marine & Nichido Fire Insurance Co., Ltd. |
| Sony Assurance Inc. |
| Rakuten General Insurance Co., Ltd. |
| Sompo Japan Insurance Inc. |
| Mitsui Direct General Insurance Co., Ltd. |
| Chubb Insurance Japan |
| MS&AD Insurance Group Holdings, Inc. |
| Others |
Supply & Pricing Matrix
Domestic automakers' captive control over telematics data streams concentrates upstream value capture in Japan's motor insurance sector, forcing carriers to compete for margin pools in distribution architecture and risk model differentiation rather than raw data ownership.
Pricing Analysis
Current-generation telematics-enabled usage-based products command premium positioning against prior-generation demographic-rated policies and emerging next-generation autonomous vehicle coverage frameworks. Three-tier pricing structure across premium concierge, standard digital, and economy agent-mediated tiers dominates the market, with price differentiation driven by real-time data integration depth and METI sandbox certification status. Pricing pressure stems from digital-native entrants compressing acquisition costs in metropolitan prefectures. Fleet operators show lowest price sensitivity due to loss prevention value capture, while individual rural buyers remain most cost-conscious.
Supply Chain Analysis
Technology service providers including domestic telematics platform developers and cloud infrastructure operators hold concentrated contract-manufacturing relationships with major carriers. Geographic supply concentration centers on Japan, with secondary dependencies on US-based analytics software and Taiwanese sensor component suppliers. Raw material dependencies include telematics hardware modules, data processing infrastructure, and AI underwriting engines. Single-source vulnerability runs through domestic automaker data gatekeeping. Distribution runs through exclusive agent networks in rural prefectures and direct digital platforms in metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's motor insurance market presents a defensive-moat structure anchored in regulatory entrenchment, where METI sandbox approvals and agent network licensing create substantial barriers against unlicensed platform-native competitors.
For Market Incumbents: Insulate core profitability by deepening vertical integration into proprietary telematics data partnerships with domestic automakers, countering the threat of platform-native entrants exploiting FSA sandbox pathways for rapid product iteration. Prioritize certification investment in METI-approved usage-based pricing models to maintain regulatory entrenchment against digital challengers. For New Entrants and Emerging Players: Kyushu's underpenetrated commercial fleet corridors represent the most penetrable entry point, particularly Fukuoka Prefecture's logistics modernization zones where incumbent agent networks retain weaker coverage density. Mid-market individual buyers in Sapporo and Sendai metropolitan areas offer secondary white-space opportunity through smartphone-first distribution angles unburdened by legacy relationship expectations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital distribution platforms possessing FSA sandbox approvals but lacking scale to challenge incumbent data analytics capabilities. Long-term viability across the projection horizon hinges on autonomous vehicle liability framework positioning. The signal to watch is Road Traffic Act amendment timing for driver-assist coverage mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time data pipelines from Toyota and Honda vehicle fleets enable dynamic risk repricing. |
| METI Sandbox Partnership | Regulatory pre-approval accelerates usage-based product launches ahead of standard filing timelines. |
| Agent Network Digitalization | Hybrid face-to-face and smartphone-enabled issuance captures rural retention with metropolitan efficiency. |
| Autonomous Vehicle Liability Development | First-mover positioning in driver-assist coverage frameworks under amended Road Traffic Act provisions. |
| Cross-Selling Platform Unification | Integrated motor and property coverage through Rakuten-style digital ecosystems captures household-level relationships. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with insurance product development executives, agency network managers, commercial fleet procurement officers, and FSA regulatory affairs specialists; and secondary validation through JFSA insurtech sandbox filings, METI digital transformation guideline documents, vehicle registration databases, and carrier annual disclosures. Bottom-up policy volume estimates triangulated against top-down premium generation benchmarks across the analysis window.
Forecast inputs considered policy type segmentation, coverage level tiers, customer category distinctions, and distribution channel evolution as core modeling dimensions. CAGRs were derived from regression analysis against vehicle density projections, logistics corridor freight volume forecasts, and smartphone penetration curves. Industry-specific inputs included telematics adoption rates and autonomous vehicle regulatory timeline assumptions.
Stress conditions across METI guideline implementation delays, automaker data access restrictions, and agent network digital resistance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory sandbox expansion and telematics platform interoperability standards. Quarterly review of FSA sandbox approval velocity and Road Traffic Act amendment progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Motor Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Personal Auto Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
Russia Car Insurance Market