
 Philippines Motor Insurance Market | 2026-2036
Philippines Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Motor Insurance Market Analytics
Logistics and last-mile delivery fleets are repositioning risk management priorities, shifting from basic third-party liability toward comprehensive motor insurance packages. Malayan Insurance leverages its long-standing agency network to dominate traditional corporate fleet placements across Luzon. AXA Philippines competes through digital-first policy issuance and telematics-integrated pricing models. Standard Insurance anchors its position in heavy commercial vehicle segments where underwriting specialization creates defensible barriers.
Philippines motor insurance constitutes a contractual risk-transfer mechanism where insurers indemnify policyholders against financial losses arising from vehicle damage, bodily injury, or third-party liability incidents, with premiums calculated through actuarial assessment of vehicle type, usage patterns, driver history, and geographic exposure zones. The product serves both statutory compliance functions and asset protection for individual owners, corporate fleets, and government vehicle pools across the archipelago's heterogeneous road infrastructure. Comprehensive coverage leads premium volume due to broader protection scope, while third-party liability retains mandatory status under national transportation codes. Online platforms represent the fastest-growing sales channel as smartphone penetration and e-commerce familiarity reshape consumer purchasing behavior among younger vehicle owners.
The Insurance Commission regulates capital adequacy, policy form approvals, and claims settlement timelines for all domestic underwriters, while the Land Transportation Office enforces compulsory third-party liability verification during vehicle registration renewals. The Anti-Money Laundering Council extends compliance obligations to premium collection channels, particularly agent-mediated transactions. Stakeholders must monitor pending amendments to motor tariff structures and the Insurance Commission's phased implementation of risk-based capital requirements that will reshape competitive positioning among mid-tier carriers.
Market Dynamics
Digital policy issuance mandates from the Insurance Commission are compressing traditional agency networks while ride-hailing fleet operators demand bundled coverage structures, forcing underwriters to rebuild distribution infrastructure around smartphone-native purchasing pathways.
Growth Catalysts
- Compulsory Third-Party Liability Enforcement:The Land Transportation Office's verification requirements during vehicle registration renewals create guaranteed premium inflows across all vehicle classes.
- Telematics Integration:Usage-based pricing models calibrated through GPS-enabled driver behavior monitoring attract commercial fleet operators seeking premium optimization.
- Metro Manila Commercial Corridors:Concentrated logistics activity along EDSA and C-5 routes generates sustained demand for comprehensive coverage among last-mile delivery operators.
Market Restraints
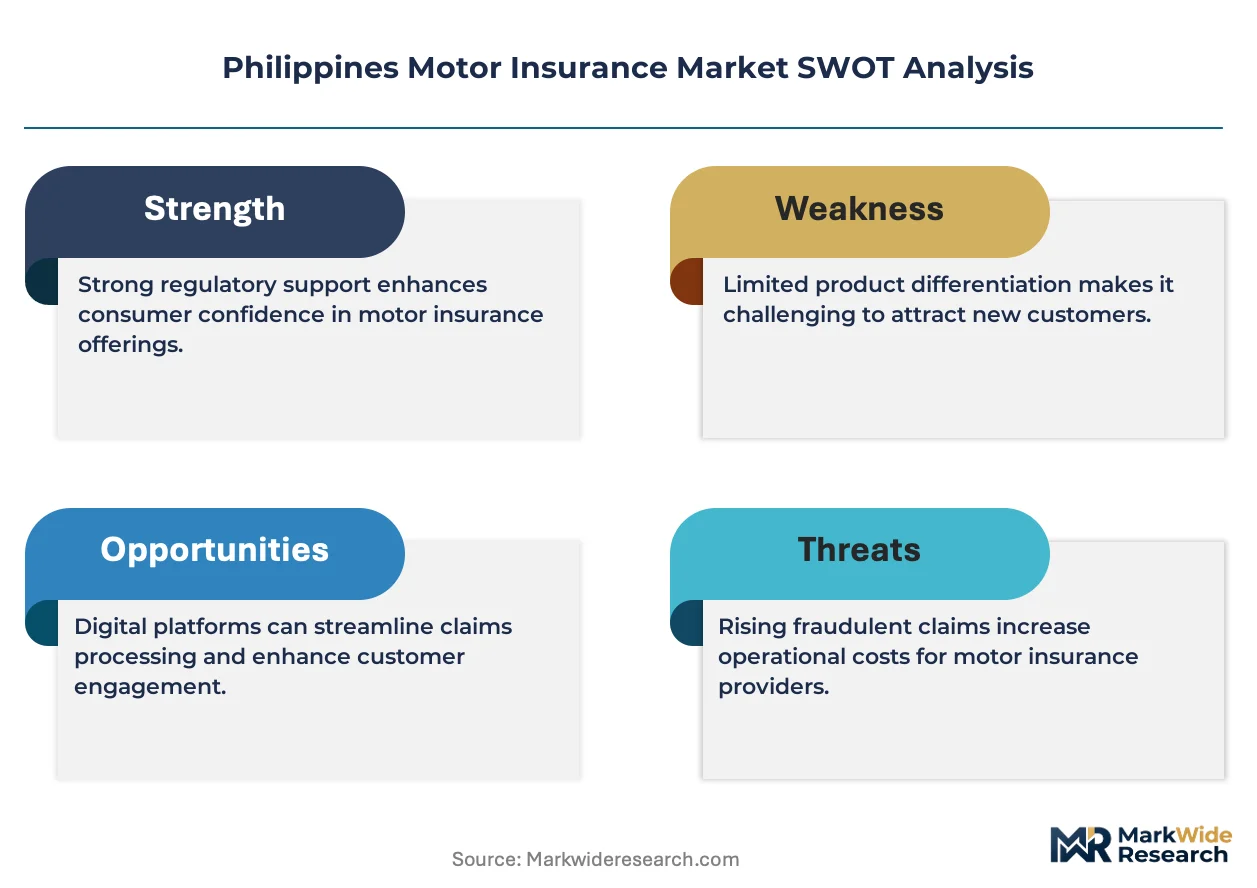
- Actuarial Data Scarcity:Sparse historical claims databases for electric vehicle fleets limit accurate risk pricing for emerging powertrain categories.
- Agent Network Concentration:Traditional distribution channels in Luzon provinces create dependency on commission-driven intermediaries resistant to digital migration.
- Fraudulent Claims Proliferation:Staged accident syndicates operating in Cebu City and Davao del Sur inflate loss ratios and compress underwriting margins.
Strategic Opportunities
- Mindanao Logistics Expansion:Underpenetrated agricultural transport corridors in Bukidnon and South Cotabato present whitespace for specialized commercial vehicle products.
- Anti-Money Laundering Council Compliance Integration:Automated premium collection systems that embed AML verification protocols attract institutional fleet accounts with complex ownership structures.
- Blockchain-Enabled Smart Contracts:Converging distributed ledger technology with parametric triggers enables instant claims settlement for minor collision events.
Industry Challenges
- Actuarial Talent Shortage:Limited domestic supply of professionals trained in telematics data interpretation constrains product innovation cycles.
- Legacy System Integration:Core policy administration platforms from the 1990s resist API connectivity with modern mobile distribution interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Motor Insurance Market |
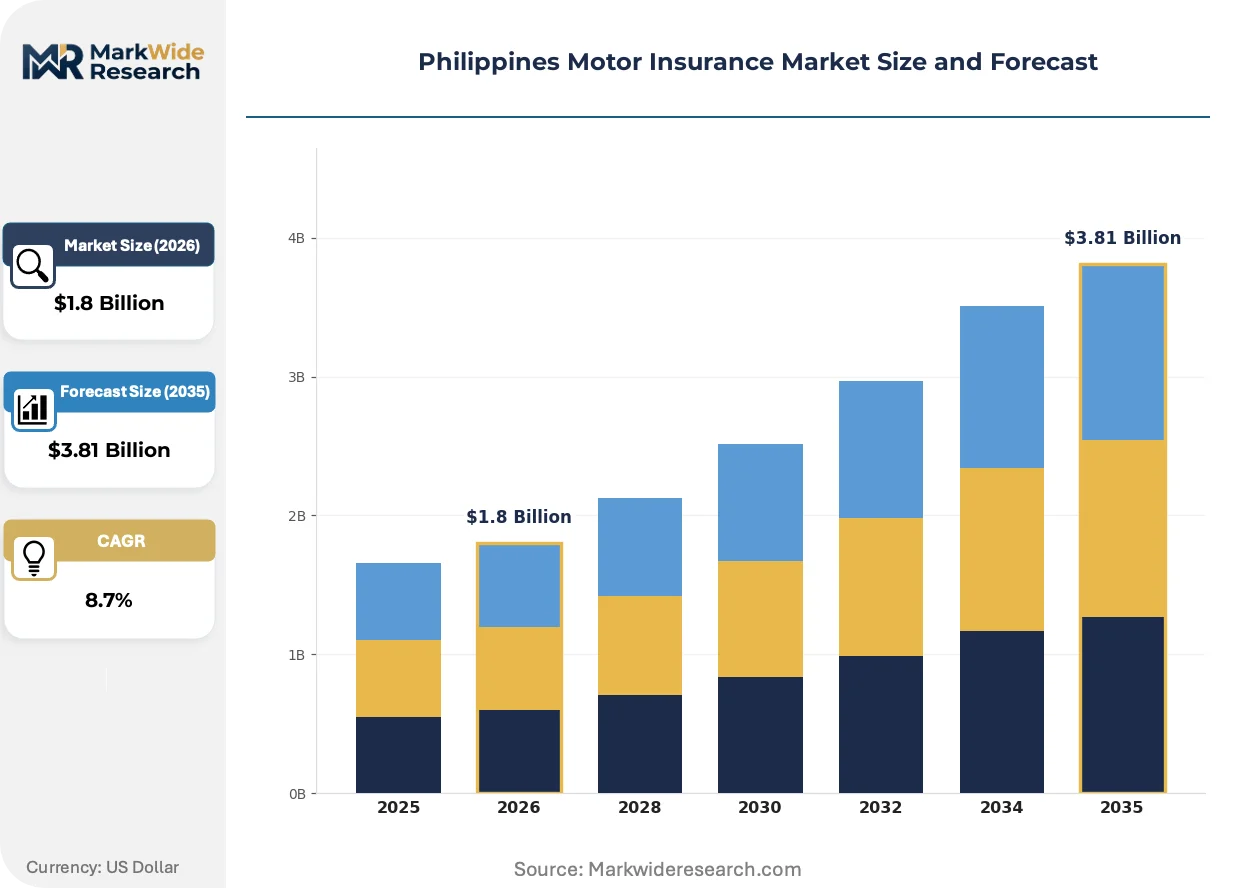
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Comprehensive, Third Party Liability, Fire & Theft, Acts of God Customer Type: Individual, Corporate, Fleet, Government Coverage Type: Personal Injury, Property Damage, Medical Expenses, Legal Liability Sales Channel: Direct Sales, Brokers, Online Platforms, Agents |
| Companies Covered | Standard Insurance, FPG Insurance, AXA Philippines, Pioneer Insurance, Cocogen Insurance, Malayan Insurance, BPI MS Insurance, OONA Insular Insurance, Prudential Guarantee and Assurance, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Motor Insurance Market Evolving Landscape
Telematics-enabled pricing models are absorbing traditional risk assessment functions while regulatory digitization mandates compress paper-based policy workflows, reshaping how underwriters compete for commercial fleet accounts.
Embedded telematics hardware is absorbing the role of manual driver history verification in premium calculation. Logistics operators with fleets exceeding fifty units are adopting black-box devices at accelerating pace. This technology is absorbing intermediary steps in risk assessment, compressing quote-to-bind timelines from days to hours.
The Insurance Commission's phased risk-based capital requirements are recalibrating reserve adequacy thresholds for mid-tier carriers. Domestic underwriters must restructure balance sheets to meet tiered solvency benchmarks. Heavy commercial vehicle specialists face the steepest compliance burden due to concentrated exposure profiles.
Fleet procurement teams are consolidating vendor relationships around integrated risk management platforms rather than standalone policy purchases. Traditional agency-mediated placements are losing share to direct digital channels among corporate buyers. This behavioral shift concentrates in Metro Manila and Cebu City where fleet management software penetration runs deepest.
Philippines Motor Insurance Market Segmentation
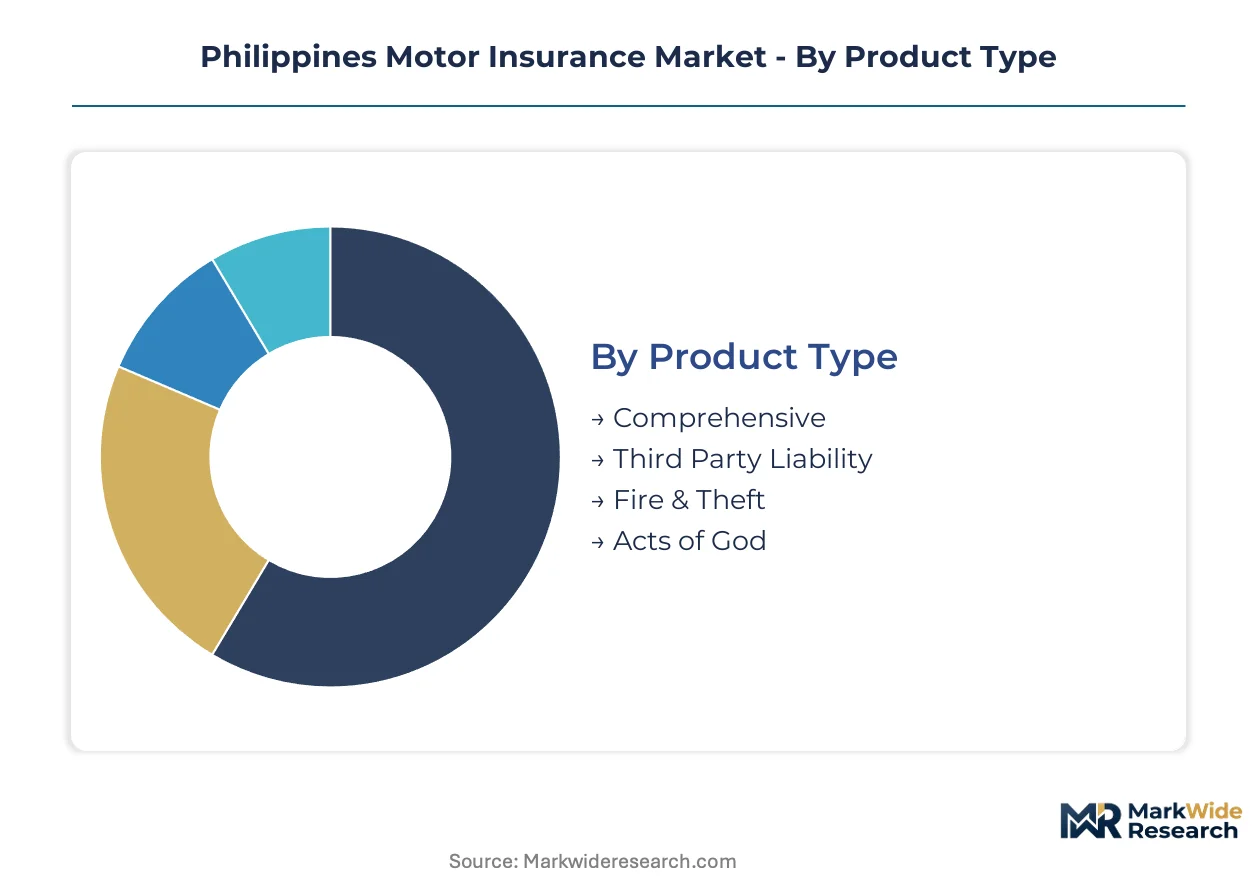
Product architecture in the Philippines motor insurance market reflects divergent compliance burdens and risk transfer mechanisms across vehicle ownership structures. Coverage design responds to Insurance Commission mandates, Land Transportation Office enforcement protocols, and fleet operator consolidation patterns.
Product Type:
Regulatory certification intensity varies sharply across product categories, with compulsory coverage carrying uniform approval requirements while voluntary extensions demand specialized actuarial sign-offs.
- Comprehensive:Bundles own-damage, theft, and third-party protection into single contracts with tiered deductibles calibrated to vehicle age and declared value. Metro Manila logistics corridors generate concentrated demand from last-mile delivery operators managing mixed fleets of motorcycles and light commercial vehicles under unified coverage structures.
- Third Party Liability:Statutorily mandated coverage verified during Land Transportation Office registration renewals, with fixed premium bands set by the Insurance Commission across passenger cars, commercial vehicles, and motorcycles. The compulsory nature guarantees baseline premium inflows but compresses underwriting margins through price regulation.
- Fire & Theft:Standalone peril coverage typically attached to older vehicles where comprehensive premiums exceed asset replacement economics. Agricultural transport operators in provincial Luzon favor this stripped-back protection for second-hand trucks.
- Acts of God:Named-peril extension covering flood, typhoon, and earthquake damage—critical for vehicles in Cebu City and Davao del Sur exposure zones where natural catastrophe frequency elevates loss ratios.
Comprehensive sits at the top of the volume ranking, with Acts of God climbing the fastest as climate exposure awareness spreads among fleet procurement teams.
Customer Type:
Premium economics and policy administration complexity diverge across ownership structures, with institutional accounts demanding API-integrated fleet management interfaces absent from retail workflows.
- Individual:Single-vehicle owners purchasing through agent networks or direct digital channels, with pricing sensitive to no-claims history and vehicle security features. Smartphone-native purchasing behavior concentrates among Metro Manila and Cebu City policyholders under age forty.
- Corporate:Multi-vehicle enterprises with dedicated risk management functions negotiating master policies covering director and employee vehicles. These accounts drive adoption of telematics-integrated pricing models and consolidated billing structures.
- Fleet:Logistics operators, ride-hailing platforms, and delivery services managing fifty-plus units under unified risk transfer arrangements. Fleet procurement teams now mandate embedded telematics hardware and parametric claims triggers as standard contract terms.
- Government:National agencies and local government units operating vehicle pools subject to public procurement regulations and Commission on Audit compliance protocols. Policy placement runs through centralized bidding processes with extended placement timelines.
Fleet commands the largest premium pool, with Corporate expanding most quickly as mid-sized enterprises professionalize risk management functions.
Coverage Type:
Claims settlement mechanics and reserve requirements differ materially across coverage categories, with bodily injury exposures carrying longer tail liabilities than property damage.
- Personal Injury:Indemnification for driver and passenger bodily harm with medical expense sub-limits and disability benefit schedules. Fraudulent claims syndicates in Cebu City and Davao del Sur specifically target this coverage category.
- Property Damage:Repair or replacement cost coverage for collision-related vehicle damage, with settlement accelerated through accredited repair shop networks. Metro Manila concentration of certified facilities compresses claim cycle times.
- Medical Expenses:Reimbursement-based coverage for hospital and rehabilitation costs distinct from personal injury lump-sum settlements. Demand concentrates in corporate fleet accounts with wellness program integration.
- Legal Liability:Defense cost and judgment coverage for civil suits arising from at-fault accidents, with policy limits structuring critical for commercial vehicle operators facing elevated third-party exposure.
Property Damage generates the highest claim frequency, with Legal Liability gaining share fastest as litigation risk awareness spreads among commercial operators.
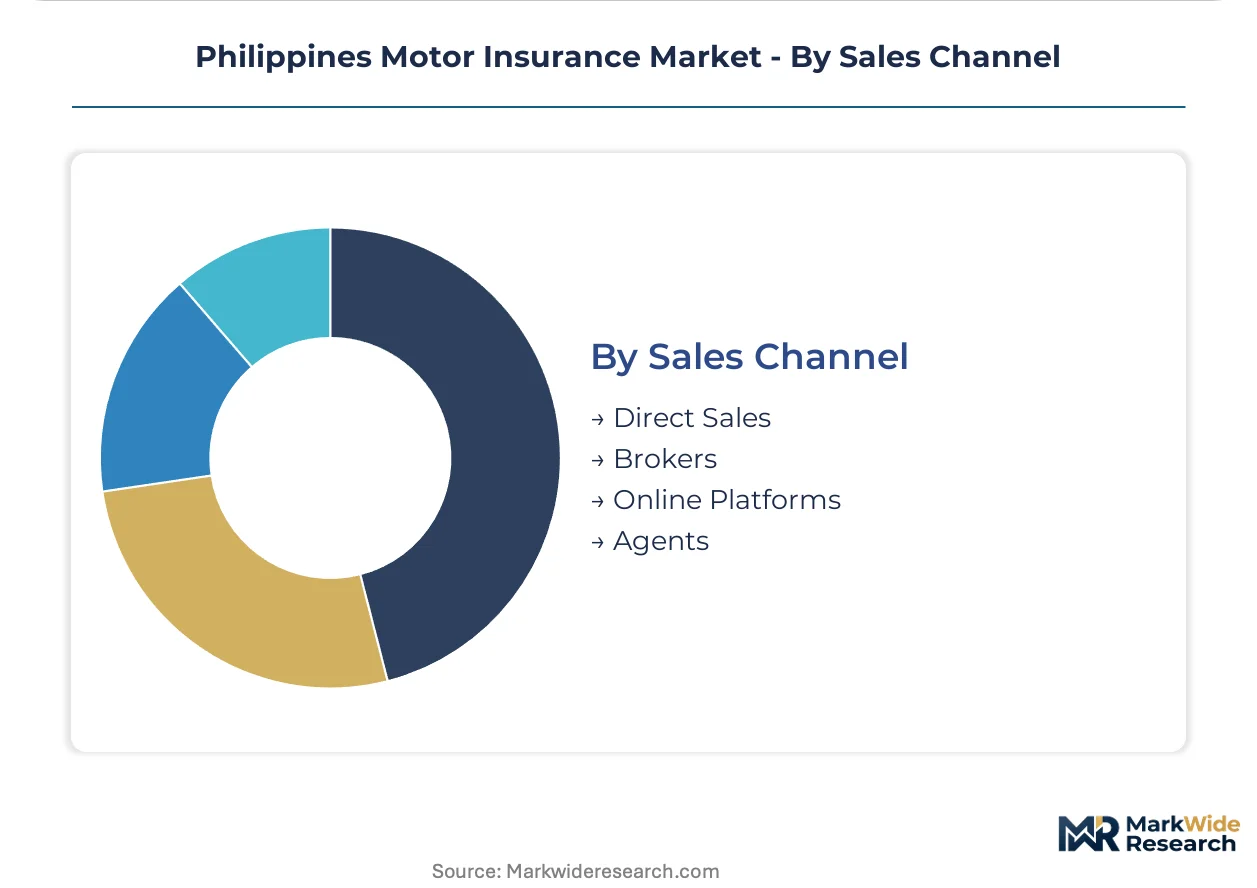
Sales Channel:
Distribution economics and Anti-Money Laundering Council compliance obligations vary across channel structures, with digital platforms embedding automated verification protocols that agent-mediated transactions lack.
- Direct Sales:Insurer-employed teams targeting large fleet accounts and government tenders through relationship-based placement. This channel captures the highest average premium per policy but carries elevated acquisition cost ratios.
- Brokers:Independent intermediaries serving corporate accounts with multi-carrier comparison and coverage design advisory. Broker consolidation in Metro Manila is reducing fragmentation among mid-market commercial placements.
- Online Platforms:Smartphone-native purchasing pathways with instant quote-to-bind functionality and digital policy issuance compliant with Insurance Commission mandates. This channel is displacing traditional agency networks among individual and small fleet accounts.
- Agents:Commission-driven intermediaries with provincial Luzon concentration resistant to digital migration. Agent networks retain dominance in rural personal auto placements where smartphone penetration lags urban centers.
Agents still dominate policy count, with Online Platforms accelerating most sharply as Insurance Commission digitization mandates compress paper-based workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila's commercial vehicle corridors concentrate the Philippines motor insurance market's premium volume, with EDSA and C-5 logistics routes generating sustained demand from last-mile delivery operators managing mixed fleets.
Metro Manila
Last-mile delivery operators and ride-hailing fleets drive comprehensive coverage demand along EDSA and C-5 corridors. The Insurance Commission's digital policy issuance mandates compress traditional agency workflows in Quezon City and Makati. Pasig City's logistics hubs anchor telematics-integrated fleet procurement.
Central Luzon
Agricultural transport operators favor stripped-back fire and theft coverage for second-hand trucks serving provincial supply chains. The Land Transportation Office enforces compulsory third-party liability verification during vehicle registration renewals across Bulacan and Pampanga. Malolos functions as a distribution node for agent-mediated rural placements.
Cebu City
Natural catastrophe exposure elevates Acts of God coverage adoption among commercial vehicle operators. Fraudulent claims syndicates inflate loss ratios and compress underwriting margins. Mandaue City's manufacturing zones concentrate heavy commercial vehicle fleets requiring specialized risk transfer.
Davao del Sur
Staged accident syndicates target personal injury coverage categories in urban collision corridors. The Insurance Commission's risk-based capital requirements recalibrate reserve adequacy for mid-tier carriers operating in Mindanao. Davao City's port logistics generate demand for legal liability protection among third-party transport contractors.
Bukidnon and South Cotabato
Underpenetrated agricultural transport corridors present whitespace for specialized commercial vehicle products. Sparse historical claims databases limit accurate risk pricing for emerging fleet categories. General Santos City's agro-industrial zones anchor logistics expansion into Mindanao's interior.
Philippines Motor Insurance Market Competitive Landscape
Strategic partnerships dominate the current landscape as underwriters rebuild distribution infrastructure around smartphone-native purchasing pathways. The market exhibits tiered concentration with dominant national carriers, mid-tier specialists, and emerging digital-first entrants competing across distinct segments. Three archetypes anchor positioning: legacy agency-network operators, telematics-integrated digital platforms, and heavy commercial vehicle underwriting specialists. Portfolio diversification and geographic expansion represent the dominant competitive moves as carriers respond to Insurance Commission digitization mandates.
Within the legacy agency-network tier, Malayan Insurance and Standard Insurance exemplify divergent specialization strategies. Malayan leverages its long-standing provincial presence to dominate traditional corporate fleet placements across Luzon. Standard anchors its position in heavy commercial vehicle segments where underwriting specialization creates defensible barriers. AXA Philippines occupies a distinct position among digital-first platforms competing through telematics-integrated pricing models and instant policy issuance.
| Leading Market Players |
|---|
| Standard Insurance |
| FPG Insurance |
| AXA Philippines |
| Pioneer Insurance |
| Cocogen Insurance |
| Malayan Insurance |
| BPI MS Insurance |
| OONA Insular Insurance |
| Prudential Guarantee and Assurance, Inc. |
| Others |
Value Network & Pricing Analysis
Automotive repair parts price indices and collision severity cost benchmarks cascade through actuarial reserving models into premium tier structures, with comprehensive coverage bands widening as supply chain concentration in Metro Manila repair networks concentrates cost negotiation leverage among accredited facility operators.
Pricing Analysis
Input-cost pass-through from automotive glass and body panel suppliers compresses margins on comprehensive policies while expanding price spreads between premium and economy tiers. Pricing stratifies across premium, standard, and economy levels based on claims history granularity and telematics data depth. Cost compression in the economy tier is intensifying because fraudulent claims syndicates in Cebu City and Davao del Sur inflate loss ratios. Fleet operators with fifty-plus units exhibit lowest price sensitivity due to risk-transfer efficiency gains, while individual motorcycle owners in provincial Luzon show highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for claims settlement services mandate accreditation of at least two repair facility networks per metropolitan zone, with Malayan Insurance and Standard Insurance maintaining parallel vendor relationships across Luzon and Visayas. Geographic supply concentration centers on Metro Manila, Cebu City, and Davao City for certified collision repair capacity. Raw material dependencies span automotive paint systems, OEM replacement parts, and diagnostic equipment. Single-source vulnerability concentrates in specialized heavy commercial vehicle repair bays serving mining and logistics fleets. Distribution runs through accredited facility networks with direct billing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Philippines motor insurance rests on telematics-enabled risk selection driving premium adequacy improvements and automated claims processing compressing administrative cost ratios.
For Market Incumbents: Hedge exposure to fraudulent claims syndicates by embedding blockchain verification protocols in personal injury settlements. Consolidate agency network control in provincial Luzon where digital migration lags. Reinforce telematics data infrastructure as the priority defensive lever against AXA Philippines' digital-first pricing models. For New Entrants and Emerging Players: Telematics-integrated micro-policies for motorcycle delivery fleets in Mindanao present the most penetrable white-space target. Agricultural transport corridors in Bukidnon and South Cotabato lack specialized commercial vehicle products. Embedded insurance partnerships with ride-hailing platforms offer the strongest go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier carriers possessing heavy commercial vehicle underwriting specialization and compliant risk-based capital structures. Long-term viability favors carriers with telematics data assets and API-integrated fleet management interfaces. Watch Insurance Commission enforcement intensity on digital policy issuance mandates as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables usage-based pricing models that attract commercial fleet operators seeking premium optimization. |
| Blockchain Claims Verification | Reduces fraudulent personal injury exposure in Cebu City and Davao del Sur corridors. |
| Mindanao Distribution Expansion | Captures underpenetrated agricultural transport demand in Bukidnon and South Cotabato. |
| Risk-Based Capital Restructuring | Positions mid-tier carriers for Insurance Commission solvency compliance ahead of phased implementation. |
| API Fleet Management Partnership | Consolidates vendor relationships around embedded risk platforms rather than standalone policies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Insurance Commission regulators, actuarial directors at domestic carriers, fleet procurement managers, and accredited repair facility operators with secondary validation. Secondary sources included Insurance Commission policy issuance databases, Land Transportation Office registration records, Anti-Money Laundering Council compliance filings, and carrier financial statements. Bottom-up premium volume estimates triangulated against top-down regulatory aggregate data.
Comparable-period anchoring aligned the projection horizon against historical regulatory filing cycles and enforcement phase-in schedules. Segmentation modeling spanned product type, customer ownership structure, coverage category, and sales channel dimensions across the analysis window. CAGRs derived from actuarial reserving trend analysis and telematics adoption curve projections. Forecast inputs incorporated Insurance Commission digitization mandate timelines and ride-hailing fleet expansion trajectories.
The model holds under stable regulatory enforcement intensity and gradual telematics penetration curves; deviation in Insurance Commission risk-based capital acceleration or catastrophic typhoon frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
China Motor Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
Japan Car Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
South Korea Motor Insurance Market