
 Germany Motor Insurance Market | 2026-2036
Germany Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Motor Insurance Market Analysis
German motor underwriters is pivoting toward usage-based models as connected vehicle penetration deepens. Allianz SE leverages telematics data to refine risk scoring across passenger car portfolios. HUK-COBURG Versicherungsgruppe anchors its position through dominant agency distribution in southern Germany. ERGO Group AG differentiates via integrated mobility services bundled with comprehensive coverage.
Germany motor insurance constitutes risk-transfer contracts indemnifying policyholders against vehicle damage, third-party liability, and theft loss, with premiums calibrated via actuarial models incorporating driver behavior telemetry and repair cost indices. Its primary purpose spans financial protection for private motorists and legal compliance with mandatory liability statutes. Comprehensive coverage leads premium pools among coverage types, while electric vehicle segments command specialized actuarial treatment due to battery replacement cost structures. Commercial fleet policy holders generate recurring revenue streams distinct from volatile individual owner churn.
BaFin supervises solvency requirements and consumer protection standards, while the EU Green Deal and national e-mobility incentives reshape vehicle replacement cycles and corresponding coverage needs. KBA registration data directly informs regional risk assessments and premium zone mapping. Stakeholders must monitor embedded insurance integrations by automotive OEMs and evolving data privacy interpretations under GDPR for telematics deployment.
Market Dynamics
Embedded telematics platforms are compressing traditional actuarial cycles, forcing German underwriters to rebuild pricing engines around real-time driver telemetry rather than static demographic proxies.
Growth Catalysts
- EU Green Deal compliance mandates:Fleet operators accelerate coverage procurement as emissions regulations tighten, expanding commercial policy volumes beyond historical replacement rates.
- Electric vehicle battery replacement costs:Specialized actuarial treatment for EV segments creates premium rate advantages for early movers in underwriting model redesign.
- Bavaria and North Rhine-Westphalia manufacturing density:Automotive production clusters sustain elevated policy issuance in these federal states compared to national averages.
Market Restraints
- GDPR interpretation uncertainty:Evolving data privacy rulings create friction for telematics deployment, delaying full-scale rollout of usage-based pricing models.
- Repair cost index volatility:Semiconductor shortages and labor inflation in German automotive workshops compress loss ratio predictability.
- OEM embedded insurance integration:Volkswagen, BMW, and Mercedes-Benz captive finance arms threaten traditional distribution by bundling coverage at point of sale.
Strategic Opportunities
- Commercial fleet telematics penetration:Medium-sized logistics operators in Saxony and Baden-Württemberg remain underpenetrated relative to large fleet benchmarks.
- Mobility-as-a-service bundling:Integrated coverage for car-sharing, ride-hailing, and subscription fleets opens recurring revenue streams distinct from individual owner churn.
- BaFin sandbox provisions:Regulatory test environments allow pilot programs for AI-driven claims automation without full licensing requirements.
Industry Challenges
- Actuarial talent scarcity:Competition for data scientists with automotive telemetry expertise outpaces German university pipeline output.
- Legacy policy administration migration:Core system modernization demands capital allocation that conflicts with Solvency II ratio maintenance targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Motor Insurance Market |
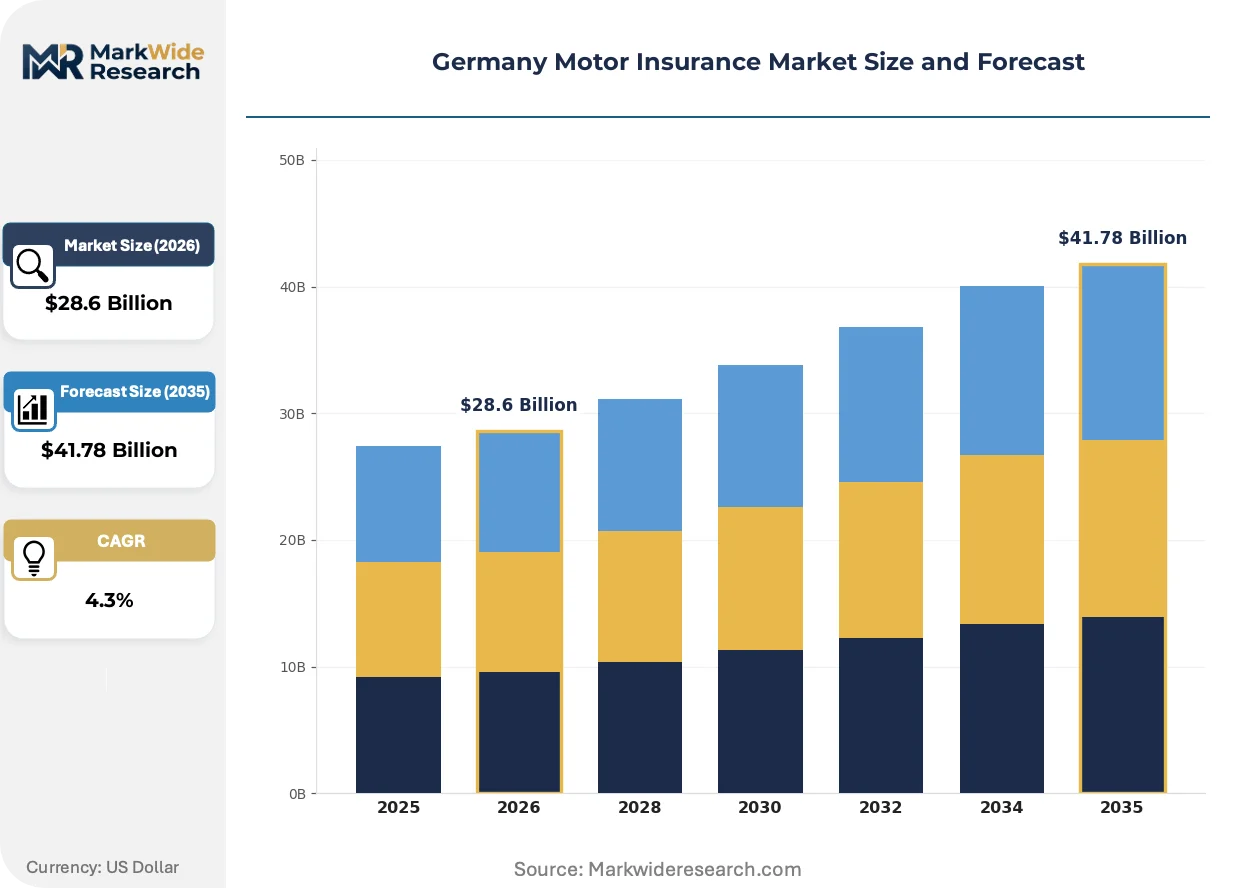
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $41.78 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Third Party, Third Party Fire & Theft, Comprehensive, Gap Insurance Policy Holder Type: Individual Owners, Commercial Fleet, Ride-Sharing Services, Corporate Clients Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles Distribution Channel: Agency, Direct, Online, Bank |
| Companies Covered | DEVK Versicherungen, ERGO Group AG, Allianz SE, Gothaer Allgemeine Versicherung AG, Zurich Gruppe Deutschland, HUK-COBURG Versicherungsgruppe, R+V Versicherung AG, Generali Deutschland AG, AXA Konzern AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Motor Insurance Market Emerging Trajectories
Telematics-enabled underwriting is collapsing the distinction between risk assessment and risk modification, transforming insurers from passive indemnifiers into active driving behavior coaches.
Embedded connected vehicle platforms is overtaking aftermarket dongle installations as the dominant data collection architecture. Passenger car OEMs now factory-install telemetry modules standard, eliminating installation friction that slowed first-generation usage-based insurance adoption. This shift compresses time-to-policy-activation from weeks to hours and enables continuous rather than episodic risk recalculation.
BaFin's strengthened consumer protection standards for algorithmic pricing demand explainable AI documentation for premium adjustments derived from telematics scores. The regulation forces underwriters to maintain human-readable audit trails alongside machine learning models. Mid-sized regional carriers lacking compliance infrastructure face disproportionate adaptation costs compared to integrated groups.
Fleet procurement teams now demand outcome-based contracts where premiums adjust against verified safety metrics rather than fixed annual rates. This purchasing pattern displaces traditional experience-rated policies in commercial segments. The shift concentrates among logistics operators in the Ruhr industrial corridor, where fuel efficiency and collision reduction carry measurable balance sheet impact.
Germany Motor Insurance Market Segmentation
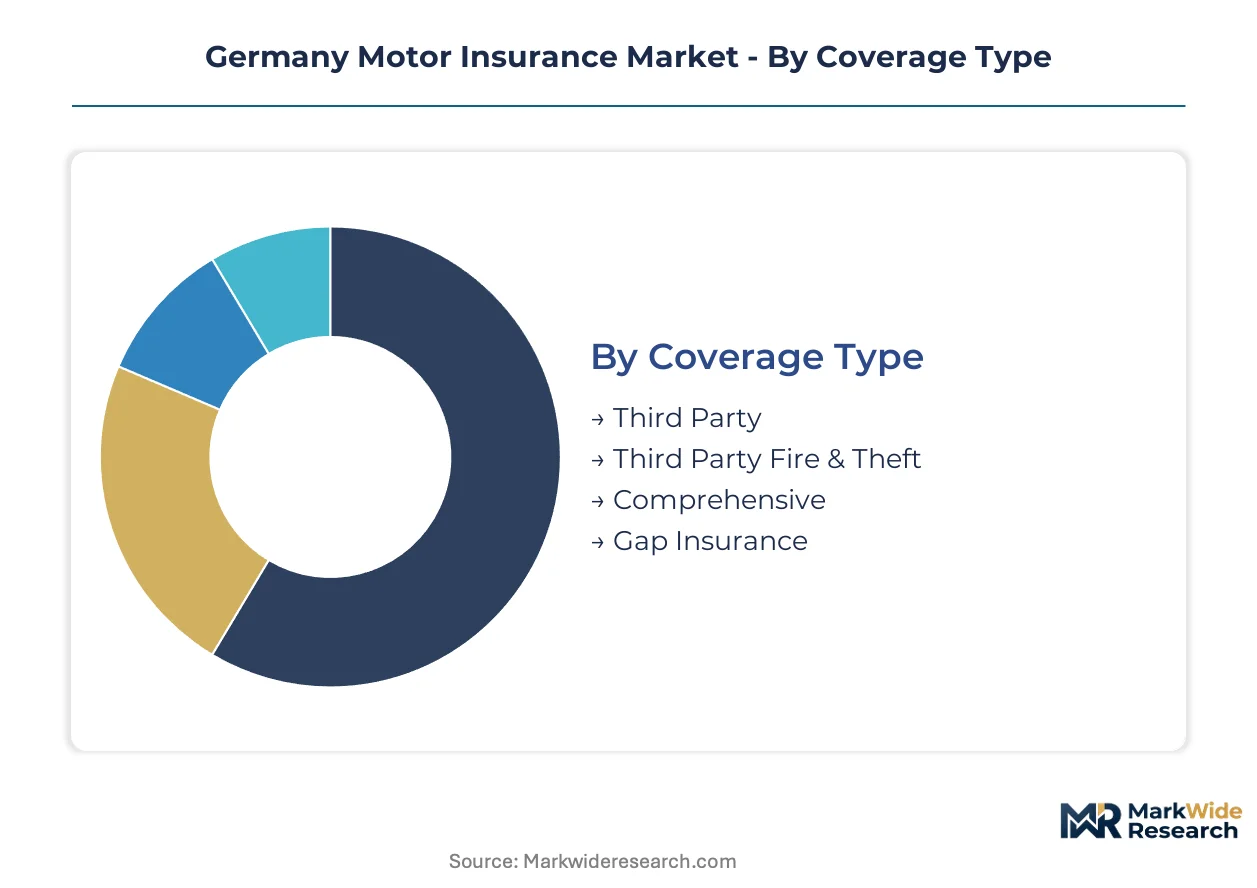
German motor insurers calibrate product architecture across four intersecting dimensions. Coverage depth, policyholder risk profiles, vehicle technology, and distribution economics each demand distinct actuarial treatment and capital allocation.
Coverage Type:
Comprehensive coverage commands premium volume leadership while mandatory liability anchors policy count. The split reflects German regulatory minimums against voluntary asset protection preferences.
- Third Party:Statutory liability coverage satisfying StVG requirements for all registered vehicles. Bavarian and North Rhine-Westphalia manufacturing clusters sustain elevated issuance volumes through fleet replacement cycles.
- Third Party Fire & Theft:Mid-tier protection adding named perils to base liability. Demand concentrates among used vehicle owners in eastern federal states where asset values justify incremental premium outlays.
- Comprehensive:Full damage indemnity including collision, vandalism, and weather loss. Telematics-enabled pricing models from Allianz SE and HUK-COBURG Versicherungsgruppe dominate this segment through refined risk scoring.
- Gap Insurance:Depreciation protection for financed and leased vehicles. New car financing penetration through captive OEM arms drives attachment rates at point-of-sale.
Mature deployment sits with Comprehensive. Newer deployment is concentrated in Gap Insurance.
Policy Holder Type:
Customer economics diverge sharply between volatile individual retention and sticky commercial fleet contracts. Fleet procurement teams now negotiate outcome-based premium adjustments against verified safety metrics.
- Individual Owners:Private motorists purchasing annual policies with high price elasticity and switching frequency. Agency distribution in southern Germany retains loyalty through localized service relationships.
- Commercial Fleet:Logistics operators and delivery services with centralized procurement and telematics integration. Ruhr corridor industrial density sustains the deepest penetration of usage-based contracts.
- Ride-Sharing Services:Platform drivers requiring hybrid personal-commercial coverage for gig economy mobility. Regulatory ambiguity around employment classification complicates standard policy structuring.
- Corporate Clients:Multi-vehicle enterprises with bundled coverage and dedicated account management. Saxony and Baden-Württemberg mid-sized operators remain underpenetrated relative to large fleet benchmarks.
Commercial Fleet exhibits the steepest expansion trajectory as emissions compliance tightens. Individual Owners face margin compression from price comparison aggregator dominance.
Vehicle Type:
Powertrain technology and vehicle mass create divergent loss cost structures. Battery replacement economics for electric fleets demand specialized actuarial treatment distinct from internal combustion risk pools.
- Passenger Cars:Private automobiles comprising the core risk pool for telematics-enabled underwriting. Embedded OEM connectivity modules now factory-standard across Volkswagen, BMW, and Mercedes-Benz lineups.
- Commercial Vehicles:Heavy trucks and vans with specialized liability exposure and regulated driver certification requirements. Long-haul operators in Baden-Württemberg generate the highest per-vehicle premium yields.
- Motorcycles:Two-wheelers with elevated injury severity and seasonal usage patterns. Southern Alpine regions sustain disproportionate policy counts relative to national vehicle stock.
- Electric Vehicles:Battery electric and plug-in hybrid platforms requiring bespoke coverage for high-voltage systems and cell replacement. KBA registration data tracks accelerating fleet penetration in urban centers.
Passenger Cars retain volume concentration. Electric Vehicles are climbing the fastest as EU Green Deal incentives reshape replacement cycles.
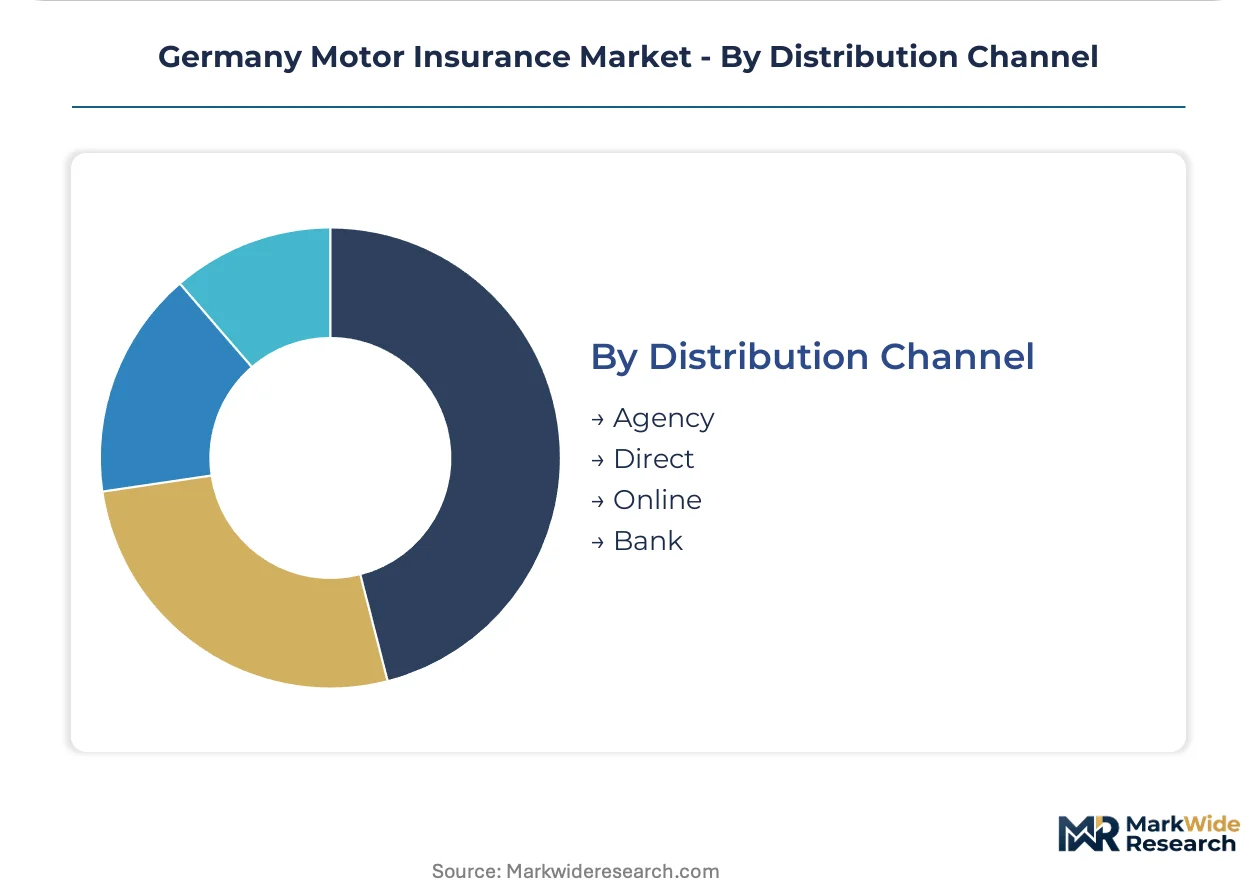
Distribution Channel:
Channel economics determine customer acquisition cost and lifetime value trajectories. Embedded insurance at vehicle point-of-sale threatens traditional intermediary structures.
- Agency:Tied and independent intermediaries with localized relationship networks. HUK-COBURG Versicherungsgruppe anchors market position through dominant southern Germany agency density.
- Direct:Insurer-owned sales forces bypassing commission structures. Price-sensitive customer segments in northern federal states show highest direct channel affinity.
- Online:Digital platforms and comparison aggregators with frictionless quote-to-bind workflows. GDPR compliance costs for telematics data handling disadvantage smaller digital entrants.
- Bank:Bancassurance partnerships leveraging credit relationships for cross-sell attachment. Auto loan bundling at point of finance sustains channel relevance despite digital displacement elsewhere.
Agency networks retain premium volume leadership. Online channels are gaining share fastest among digitally-native customer cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturing density across German federal states anchors regional premium generation. Bavarian and North Rhine-Westphalian production clusters sustain elevated policy issuance through fleet replacement cycles and supplier network coverage procurement.
Bavaria
BMW and Audi headquarters concentration drives corporate fleet coverage demand. KBA registration data tracks premium vehicle volumes exceeding national per-capita averages. Munich and Ingolstadt manufacturing zones generate the highest comprehensive coverage attachment rates among German federal states.
North Rhine-Westphalia
Ford and Volkswagen commercial vehicle plants sustain heavy truck insurance procurement. The Ruhr industrial corridor logistics operators negotiate outcome-based premium contracts against verified safety metrics. Düsseldorf and Cologne metropolitan zones concentrate agency distribution networks for mid-market passenger coverage.
Baden-Württemberg
Mercedes-Benz and Porsche engineering centers anchor high-value vehicle underwriting. Mid-sized logistics operators in Stuttgart and Mannheim remain underpenetrated relative to large fleet telematics benchmarks. EU Green Deal e-mobility incentives accelerate electric vehicle registration volumes in urban centers.
Lower Saxony
Volkswagen Wolfsburg headquarters and supplier parks generate concentrated commercial fleet demand. Hanover logistics hubs sustain long-haul operator coverage procurement with specialized liability exposure. Semiconductor supply chain volatility from regional electronics manufacturers compresses repair cost predictability.
Hesse
Frankfurt financial services sector drives executive vehicle coverage with premium risk profiles. Frankfurt Airport cargo operations sustain commercial aviation-ground fleet insurance demand. BaFin regulatory proximity concentrates compliance-focused underwriter regional offices.
Germany Motor Insurance Market Vendor Landscape
Global majors compete with regional champions across distribution channel density and telematics integration depth. The market structure consolidates around integrated financial groups with captive agency networks, while direct digital entrants fragment price-sensitive segments. Strategic archetypes include scale-driven integrated insurers, regionally anchored mutual cooperatives, and OEM-captive finance arms. Dominant competitive moves encompass embedded insurance partnerships at vehicle point-of-sale and AI-driven claims automation pilot programs.
Among integrated multinational groups, Allianz SE and Zurich Gruppe Deutschland occupy positions exemplifying telematics-enabled underwriting scale. HUK-COBURG Versicherungsgruppe anchors the mutual cooperative archetype through dominant southern Germany agency density. ERGO Group AG sits within the mobility services bundling tier, integrating coverage with integrated mobility platforms.
| Leading Market Players |
|---|
| DEVK Versicherungen |
| ERGO Group AG |
| Allianz SE |
| Gothaer Allgemeine Versicherung AG |
| Zurich Gruppe Deutschland |
| HUK-COBURG Versicherungsgruppe |
| R+V Versicherung AG |
| Generali Deutschland AG |
| AXA Konzern AG |
| Others |
Supply Flow & Price Mechanics
Captive insurance integration by automotive OEMs anchors both supply positioning and pricing power in German motor coverage. Volkswagen Financial Services, BMW Financial Services, and Mercedes-Benz Mobility bundle policies at vehicle point-of-sale, compressing independent intermediary margins while securing proprietary customer data streams for risk calibration.
Pricing Analysis
Warranty and roadside assistance bundling separates comprehensive policies from stripped liability-only coverage in German motor insurance. Three-tier pricing structure across premium, standard, and economy levels stratifies by telematics participation and no-claims history. Pricing pressure stems from comparison aggregator dominance in individual owner segments, where switching costs approach zero. Commercial fleet procurement teams exhibit lowest price sensitivity due to outcome-based contract structures tying premiums to verified safety metrics.
Supply Chain Analysis
Telematics hardware supply rests on semiconductor foundries in Taiwan, South Korea, and Germany. Embedded connectivity modules, GPS sensors, and cellular modems constitute critical component dependencies. Single-source vulnerability concentrates in automotive-grade chip supply, where foundry capacity allocation favors electric vehicle powertrain orders. Distribution runs through OEM captive finance arms, agency networks, and direct digital platforms in roughly equal premium volume shares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German motor insurance occupies a technology-transition phase where embedded telematics platforms displace static demographic underwriting. Real-time driver telemetry supplants historical claims proxies as the primary risk assessment input.
For Market Incumbents: Deepen agency network digitization to match OEM embedded insurance convenience. HUK-COBURG Versicherungsgruppe's southern Germany density provides template for localized service relationships resisting point-of-sale bundling. Invest in explainable AI documentation infrastructure ahead of BaFin algorithmic pricing enforcement.
For New Entrants and Emerging Players: The mid-market price-point gap between Allianz SE premium telematics offerings and economy direct writers presents white-space opportunity. Target underpenetrated mid-sized logistics operators in Saxony and Baden-Württemberg with outcome-based fleet contracts. Deploy mobility-as-a-service bundling for car-sharing and subscription fleet operators.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated financial groups seeking telematics capabilities. Long-term viability favors carriers with embedded OEM data partnerships or dominant regional agency density. Watch KBA electric vehicle registration velocity as inflection indicator for specialized battery coverage demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Embedded OEM connectivity modules from BMW and Volkswagen compress policy activation timelines from weeks to hours. |
| Outcome-Based Contract Expansion | Ruhr corridor logistics operators now negotiate premiums against verified collision reduction and fuel efficiency metrics. |
| AI-Driven Claims Automation | BaFin sandbox provisions enable pilot programs reducing loss adjustment expense without full licensing requirements. |
| Electric Vehicle Coverage Specialization | Battery replacement cost structures demand actuarial treatment distinct from internal combustion risk pools. |
| Agency Network Digitization | HUK-COBURG Versicherungsgruppe's southern Germany density demonstrates localized service relationships resisting OEM bundling. |
Methodological Framework
Multi-period observation of KBA registration data, BaFin solvency filings, and EU Green Deal implementation milestones anchored the trend analysis, supplemented by interviews with underwriting executives, actuarial directors, fleet procurement managers, and telematics platform engineers. Secondary validation drew from EU regulatory databases, automotive OEM financial disclosures, and German insurance association statistical yearbooks. Bottom-up policy count modeling and top-down premium pool estimation provided triangulation checks.
Segment-weighting across coverage type, policyholder category, vehicle technology, and distribution channel shaped the analytical framework. Passenger car telematics penetration curves, commercial fleet replacement cycles, and electric vehicle battery replacement cost indices informed growth trajectory modeling. CAGRs were derived from fitted trend lines rather than single-point extrapolation.
Inputs from KBA and BaFin were available through the study window; gaps in real-time telematics claims experience data introduce uncertainty bands around usage-based pricing adoption forecasts. Regulatory interpretation shifts under GDPR and EU AI Act implementation could revise embedded insurance integration timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Thailand Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
China Motor Insurance Market
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
Marine Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
Philippines Motor Insurance Market