
 Singapore Motor Insurance Market | 2026-2036
Singapore Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Motor Insurance Market Analytics
Comprehensive policy tier upgrades is bifurcating the Singapore motor insurance landscape as motorists shift from minimum third-party coverage toward broader protection packages. AXA Insurance Pte Ltd leverages its digital claims infrastructure to reduce settlement cycles and retain high-value policyholders. NTUC Income Insurance Co-operative Ltd anchors the mass-market segment through affinity distribution tied to union and cooperative memberships. Tokio Marine Insurance Singapore Ltd differentiates via specialized commercial vehicle expertise serving logistics and construction fleets.
Singapore motor insurance constitutes a risk-transfer contract indemnifying vehicle owners against collision damage, third-party liability, and theft losses, with premiums calibrated through actuarial models incorporating vehicle age, driver history, and mileage parameters. The product serves both individual wealth protection and commercial fleet risk management functions across the city-state's dense road network. Comprehensive policies command the deepest margin pools as add-on features such as roadside assistance and replacement car coverage expand average revenue per policy. Fleet operators represent the fastest-growing customer type as logistics platforms and ride-hailing services scale insurable vehicle counts under centralized procurement arrangements.
The Monetary Authority of Singapore enforces risk-based capital standards that determine minimum reserve thresholds and product pricing floors across licensed insurers. The country's Personal Data Protection Commission shapes telematics deployment and usage-based insurance models through consent and data governance requirements. Stakeholders must monitor how autonomous vehicle trials on public roads will force coverage redesigns and liability reallocation between manufacturers, operators, and insurers.
Market Dynamics
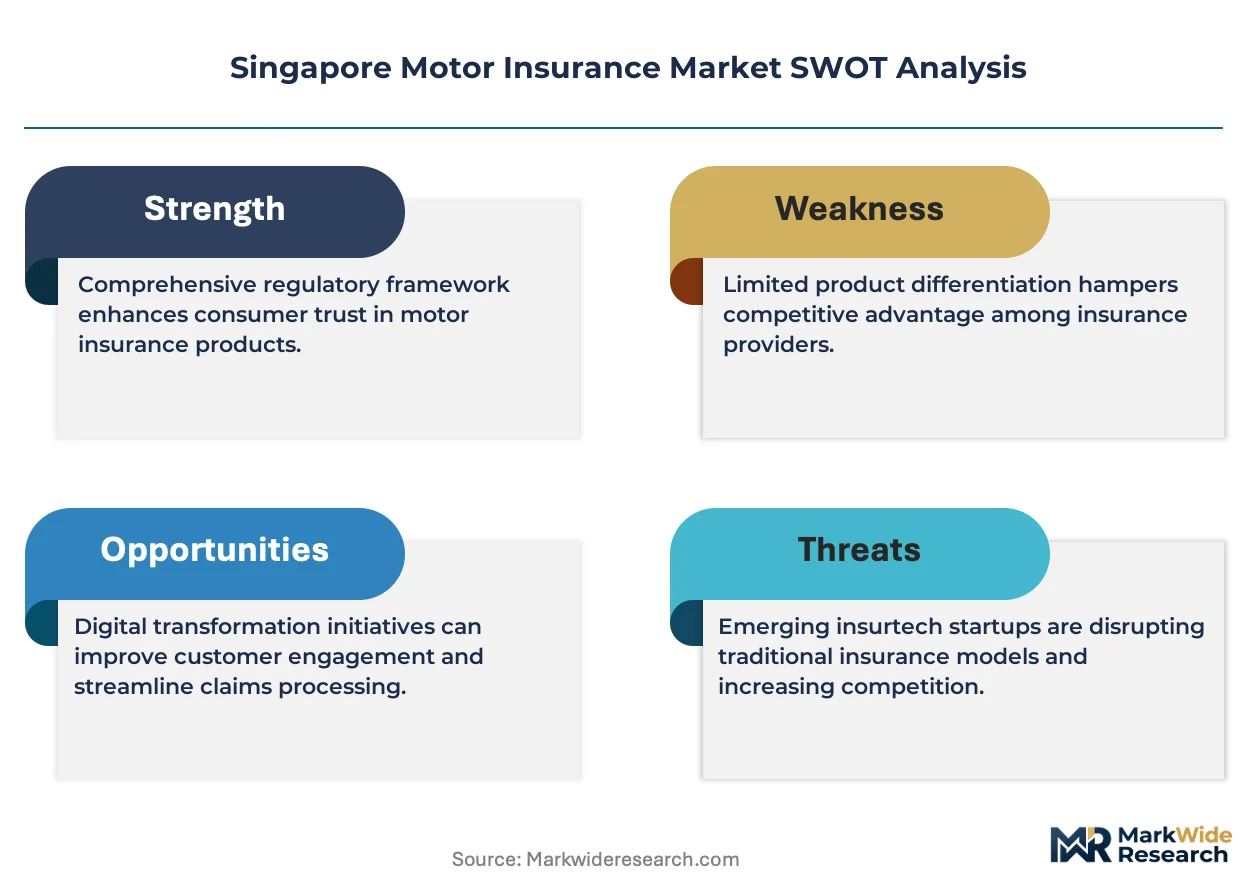
The Monetary Authority of Singapore's risk-based capital framework is compressing pricing flexibility and forcing product redesign across licensed insurers, while ride-hailing fleet expansion creates concentrated demand pools that reshape underwriting economics.
Growth Catalysts
- Telematics Integration:Usage-based insurance models leveraging real-time driving data are penetrating the Singapore market as the Personal Data Protection Commission clarifies consent frameworks for vehicle data collection.
- Fleet Operator Procurement:Centralized insurance purchasing by logistics platforms and ride-hailing services is aggregating vehicle counts under single master policies with negotiated rate structures.
- MAS Capital Standards:The Monetary Authority of Singapore's solvency requirements are accelerating product tier differentiation as insurers seek higher-margin comprehensive coverage to meet reserve thresholds.
Market Restraints
- Input Cost Volatility:Vehicle repair costs in Singapore fluctuate with imported parts availability and labor rates at authorized service centers, compressing loss ratio predictability.
- Supply Concentration Risk:Reinsurance capacity for catastrophic motor liability concentrates with a limited pool of Singapore-licensed treaty underwriters, creating capacity constraints during hard market cycles.
- Technical Limitation:Fraud detection systems struggle with staged accident schemes involving medical provider collusion, elevating claims leakage in bodily injury segments.
Strategic Opportunities
- Autonomous Vehicle Trials:Public road testing of self-driving vehicles by the Land Transport Authority is forcing coverage redesigns that reallocate liability between manufacturers, fleet operators, and insurers.
- Embedded Distribution:Digital insurance APIs integrated into vehicle financing platforms and dealership management systems are capturing policyholders at point-of-sale with reduced acquisition costs.
- Micro-Mobility Expansion:Electric scooter and motorcycle fleets serving last-mile delivery are creating new commercial vehicle segments with specialized risk profiles and pricing elasticity.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of professionals skilled in telematics data modeling and machine learning applications is delaying usage-based product launches at smaller insurers.
- Legacy System Integration:Core policy administration platforms at established insurers require costly middleware development to connect with real-time vehicle data feeds and digital claims workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Motor Insurance Market |
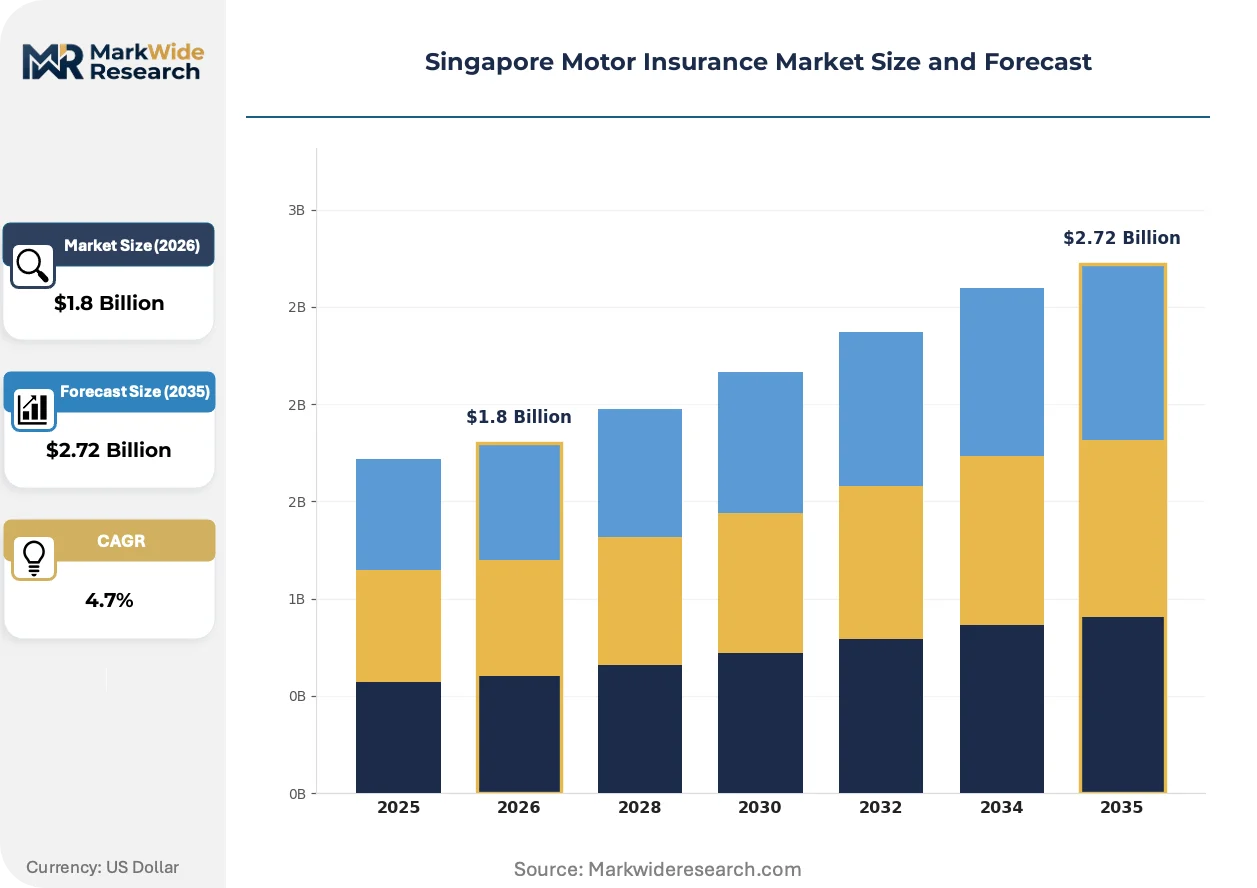
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third-Party, Limited, Fire & Theft Customer Type: Individual Motorists, Fleet Operators, Commercial Vehicles, Ride-Hailing Services Insurance Provider: Insurtechs, Traditional Insurers, Multi-Line Insurers, Direct Sellers Coverage Features: Roadside Assistance, No-Claim Bonus, Personal Accident Cover, Replacement Car |
| Companies Covered | AXA Insurance Pte Ltd, Allianz Insurance Singapore Pte Ltd, NTUC Income Insurance Co-operative Ltd, Liberty Insurance Pte Ltd, AIG Asia Pacific Insurance Pte. Ltd., Great Eastern General Insurance Limited, Tokio Marine Insurance Singapore Ltd, FWD Singapore Pte. Ltd., MSIG Insurance (Singapore) Pte. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Motor Insurance Market Evolving Landscape
Digital claims infrastructure and connected vehicle data streams are compressing settlement cycles and enabling dynamic pricing models that respond to actual driving behavior rather than static risk proxies.
Telematics-enabled usage-based insurance is bifurcating the Singapore motor insurance market between data-rich fleet operators receiving granular per-mile pricing and individual motorists on traditional annual premium structures. Logistics companies with centralized fleet management systems are adopting real-time driver scoring to negotiate rate adjustments quarterly. This technology is bifurcating underwriting approaches as insurers deploy separate pricing engines for connected versus non-connected vehicle portfolios.
The Personal Data Protection Commission's consent and data governance requirements are shaping how insurers deploy driving behavior analytics and roadside assistance location tracking. Industrial consequence includes mandatory opt-in protocols that increase customer acquisition friction but reduce regulatory enforcement exposure. Individual motorist segments in the central business district are most affected, with insurers responding through simplified consent flows and transparent data usage disclosures.
Affinity distribution through union and cooperative memberships is displacing traditional agent channels for mass-market motor coverage in Singapore. NTUC Income's cooperative model demonstrates how member-based organizations capture policyholders through payroll deduction and group negotiation leverage. This channel shift concentrates most visibly among public sector employees and manufacturing workers in Jurong and Tuas industrial corridors.
Singapore Motor Insurance Market Segmentation
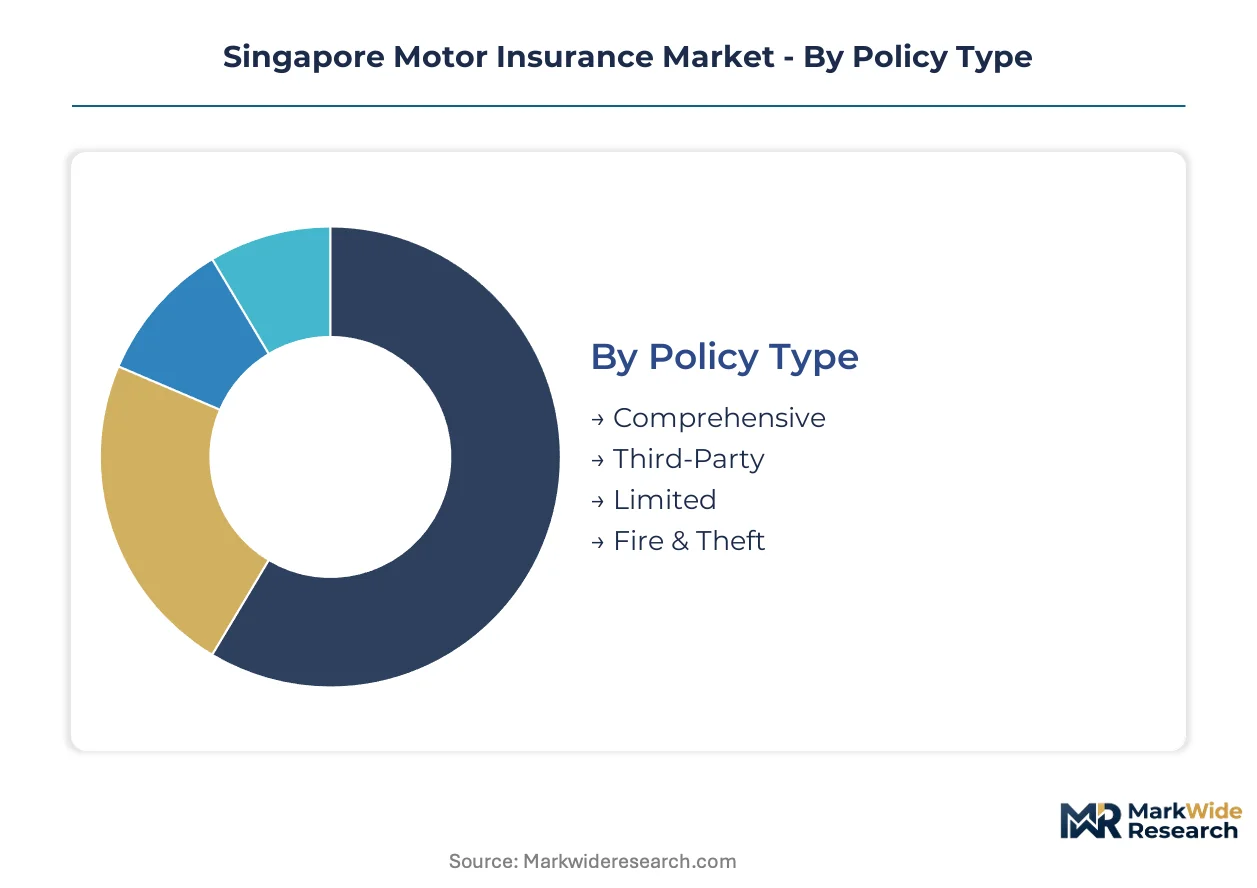
Singapore's motor insurance market segments along four distinct axes that determine pricing mechanics, distribution channels, and customer acquisition costs. Policy type and customer type classifications exert the strongest influence on underwriting economics and capital reserve requirements under MAS regulations.
Policy Type:
Distribution channels bifurcate sharply between comprehensive policies sold through digital platforms and third-party coverage retained through traditional agent networks.
- Comprehensive:Full collision, third-party liability, and theft protection bundled with optional add-ons. Demand concentrates among individual motorists in the central business district where vehicle values and repair costs justify premium outlays. MAS capital standards are pushing insurers toward this higher-margin tier to meet solvency thresholds.
- Third-Party:Minimum legal coverage for bodily injury and property damage to others. Fleet operators in logistics and ride-hailing services negotiate master policies with negotiated rate structures, compressing per-unit acquisition costs through centralized procurement.
- Limited:Intermediate protection covering third-party liability plus fire and theft for own vehicle. NTUC Income's cooperative distribution channel captures price-sensitive motorists in Jurong and Tuas industrial corridors through payroll deduction schemes.
- Fire & Theft:Named-peril coverage excluding collision damage. Tokio Marine's specialized commercial vehicle expertise serves construction fleets with asset-protection-focused structures.
Third-party policies dominate installed base. Comprehensive coverage is where expansion concentrates.
Customer Type:
Margin profiles diverge between fragmented individual accounts and concentrated fleet portfolios with quarterly rate renegotiation leverage.
- Individual Motorists:Personal vehicle owners purchasing single policies through digital comparison platforms or affinity channels. AXA's claims infrastructure investments target this segment's retention through reduced settlement cycles.
- Fleet Operators:Logistics companies and delivery platforms with centralized vehicle management systems. Telematics integration enables real-time driver scoring and dynamic pricing adjustments, representing the steepest expansion trajectory in the market.
- Commercial Vehicles:Trucks, vans, and specialized equipment serving construction and industrial sectors. Underwriting requires specialized expertise in vehicle utilization patterns and cargo liability exposure.
- Ride-Hailing Services:Platform-mediated passenger transport fleets with high mileage intensity and passenger liability exposure. Coverage redesigns are emerging as Land Transport Authority autonomous vehicle trials force liability reallocation discussions.
Individual motorists dominate installed base. Fleet operators are gaining share fastest.
Insurance Provider:
Technology intensity separates digital-native distributors from legacy carriers burdened by core system integration costs.
- Insurtechs:Digital-first platforms leveraging API distribution and real-time data analytics. Embedded insurance partnerships with vehicle financing platforms capture policyholders at point-of-sale.
- Traditional Insurers:Established carriers with branch networks and agent relationships. Legacy policy administration systems require middleware development to connect with telematics feeds.
- Multi-Line Insurers:Diversified carriers cross-selling motor coverage from property and casualty bases. Capital reserves benefit from portfolio diversification effects under MAS risk-based capital frameworks.
- Direct Sellers:Phone and online channels bypassing intermediary commissions. Cost structures enable competitive pricing for standard coverage tiers.
Traditional insurers dominate installed base. Insurtechs are where expansion concentrates.
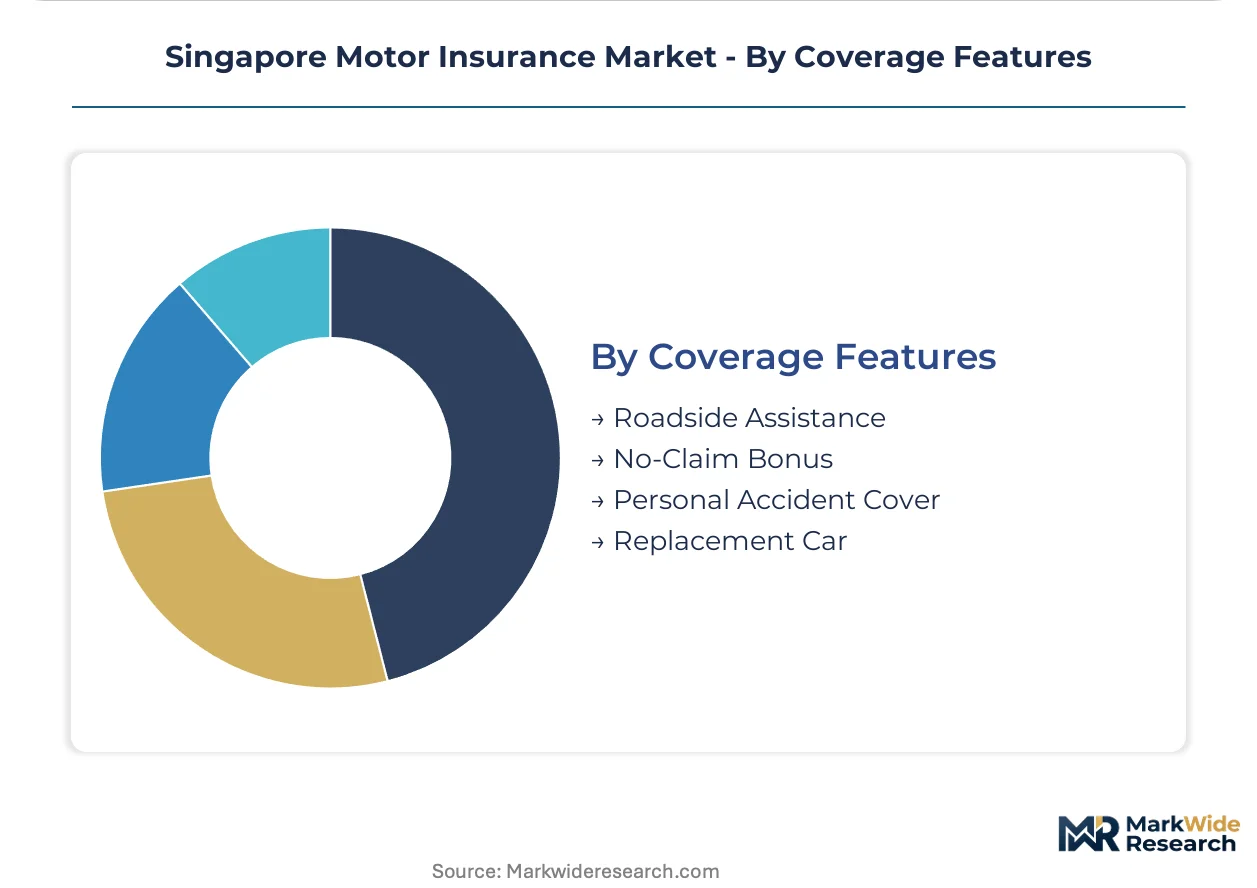
Coverage Features:
Add-on penetration rates determine average revenue per policy and retention elasticity.
- Roadside Assistance:24-hour breakdown and towing services. Personal Data Protection Commission consent requirements shape location tracking deployment.
- No-Claim Bonus:Premium discounts rewarding claim-free histories. Actuarial modeling links bonus structures to driver risk scoring accuracy.
- Personal Accident Cover:Medical and disability protection for drivers and passengers. Fraud detection systems target staged accident schemes involving medical provider collusion.
- Replacement Car:Temporary vehicle provision during repair periods. Demand concentrates among commercial vehicle operators with continuity requirements.
No-claim bonus features dominate installed base. Roadside assistance is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore motor insurance operates as a net importer of reinsurance capacity, with treaty coverage sourced primarily from London, Bermuda, and regional Asian markets to backstop catastrophic liability exposure. The city-state's regulatory framework and fleet operator demand create distinct sub-regional concentrations across its urban geography.
Central Business District
Individual motorists in the CBD generate the highest comprehensive policy penetration rates due to elevated vehicle values and parking density. The Land Transport Authority's congestion pricing schemes influence mileage patterns that feed into usage-based insurance models. Raffles Place and Marina Bay financial clusters concentrate white-collar professionals purchasing high-tier coverage with roadside assistance add-ons.
Jurong Industrial Corridor
Logistics platforms and manufacturing workers in Jurong and Tuas drive affinity-based motor insurance procurement through cooperative membership channels. NTUC Income's payroll deduction schemes capture this price-sensitive segment with limited and third-party coverage tiers. The Jurong Port container traffic sustains commercial vehicle fleets requiring specialized cargo liability riders.
Northeast Residential Belt
Mass-market family vehicles in Ang Mo Kio, Serangoon, and Hougang anchor third-party policy volumes with lower average revenue per policy. Housing Development Board estate parking configurations reduce theft risk and compress fire-and-theft coverage demand. Digital comparison platforms have displaced traditional agent channels fastest in this suburban segment.
Changi-Airport Logistics Zone
Ride-hailing fleet operators and air freight ground transport services cluster around Changi and the adjacent industrial parks. High-mileage intensity vehicles here drive telematics adoption for quarterly rate renegotiation with insurers. The Civil Aviation Authority of Singapore's ground handling regulations impose additional liability coverage requirements on commercial operators.
Singapore Motor Insurance Market Competitive Landscape
Listed leaders compete with private specialists across capital adequacy and distribution reach in Singapore's motor insurance sector. The market structure consolidates around three to four dominant multi-line carriers with sufficient risk-based capital reserves under MAS requirements, while cooperative and foreign specialist insurers occupy niche positions. Strategic archetypes separate digital-native distributors leveraging API partnerships, cooperative affinity channels with embedded payroll deduction, and traditional carriers with legacy branch infrastructure. Competitive moves concentrate on telematics integration partnerships and embedded distribution deals with vehicle financing platforms.
Within the cooperative tier, NTUC Income Insurance Co-operative Ltd anchors mass-market penetration through union-linked distribution. AXA Insurance Pte Ltd and Tokio Marine Insurance Singapore Ltd represent contrasting archetypes: the former exemplifies digital claims infrastructure investment for retention, while the latter occupies specialized commercial vehicle expertise serving logistics and construction verticals. These three named entities illustrate how capital structure and distribution DNA determine competitive positioning under tightening solvency standards.
| Leading Market Players |
|---|
| AXA Insurance Pte Ltd |
| Allianz Insurance Singapore Pte Ltd |
| NTUC Income Insurance Co-operative Ltd |
| Liberty Insurance Pte Ltd |
| AIG Asia Pacific Insurance Pte. Ltd. |
| Great Eastern General Insurance Limited |
| Tokio Marine Insurance Singapore Ltd |
| FWD Singapore Pte. Ltd. |
| MSIG Insurance (Singapore) Pte. Ltd. |
| Others |
Value Network & Pricing Analysis
Telematics-enabled usage-based models replacing traditional annual premium structures simultaneously redistribute pricing power toward data-rich fleet operators and compress margins for insurers serving non-connected vehicle portfolios. This substitution dynamic concentrates underwriting economics around real-time driver scoring capabilities while fragmenting supply chain influence across reinsurance treaty markets.
Pricing Analysis
Fleet operators with centralized procurement functions anchor Singapore motor insurance pricing through quarterly rate renegotiation leverage tied to telematics data feeds. Three-tier pricing structure across comprehensive, limited, and third-party coverage levels differentiates by vehicle value, driver history granularity, and add-on penetration. Cost compression in third-party tiers is intensifying because ride-hailing platforms negotiate master policies at volume scale. Individual motorists in the central business district exhibit lowest price sensitivity due to high vehicle replacement values, while Jurong industrial corridor workers show highest sensitivity to premium outlays.
Supply Chain Analysis
Just-in-time reinsurance capacity sourcing from London, Bermuda, and regional Asian treaty markets leaves Singapore insurers exposed to hard market cycle disruptions without strategic stockpiles of catastrophic liability backing. Primary capacity draws from domestic licensed carriers, with risk transfer resting on international reinsurance relationships for peak exposure layers. Single-source vulnerability concentrates in bodily injury reinsurance towers where capacity tightens during loss-intensive periods. Distribution runs through broker-mediated treaty placements rather than direct insurer-to-reinsurer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore motor insurance operates as a substitution defense market where embedded insurance APIs and telematics-native insurtechs threaten traditional agent-channel incumbents with disintermediation at point-of-sale. Incumbents must navigate this substitute threat while rebuilding core systems for real-time data integration.
For Market Incumbents: Shield comprehensive policyholder relationships through accelerated claims infrastructure investments that reduce settlement cycles below digital-native competitor benchmarks. Prioritize backward integration into telematics data partnerships with vehicle manufacturers to secure exclusive driver behavior feeds. Channel control through embedded distribution deals with financing platforms represents the critical defensive lever against API-based entrants.
For New Entrants and Emerging Players: Anchor in the micro-mobility commercial vehicle segment where electric scooter and motorcycle fleets serving last-mile delivery lack specialized coverage solutions from established carriers. The Changi-Airport logistics zone presents the most penetrable geography given high-mileage intensity and quarterly rate renegotiation openness. A usage-based insurance go-to-market angle leveraging simplified consent flows under Personal Data Protection Commission guidelines captures fleet operators frustrated with legacy insurer data governance friction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with traditional insurers burdened by legacy policy administration platforms requiring costly middleware development for telematics connectivity. Long-term viability across the analysis window hinges on successful digital transformation execution rather than brand heritage. The signal to watch is quarterly disclosure of telematics-enabled policy share expansion as an inflection indicator for underwriting margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Partnership | Exclusive access to vehicle manufacturer driving behavior feeds locks in fleet operator pricing power. |
| Embedded Distribution API | Integration with vehicle financing platforms captures policyholders at point-of-sale with reduced acquisition costs. |
| Claims Infrastructure Modernization | Compressed settlement cycles through digital workflows improve retention among high-value comprehensive policyholders. |
| Micro-Mobility Coverage Development | Specialized risk products for electric scooter fleets address underserved last-mile delivery segments. |
| Reinsurance Treaty Diversification | Expanded London and Bermuda relationships reduce single-source vulnerability during catastrophic liability hard markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with underwriting executives, claims operations directors, and fleet procurement managers at logistics platforms, alongside secondary validation through Monetary Authority of Singapore regulatory filings, Land Transport Authority vehicle registration databases, and reinsurance treaty market capacity reports. Bottom-up policy volume estimates triangulated against top-down market value assessments derived from premium rate benchmarks across comprehensive, third-party, and limited coverage tiers.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning policy type, customer archetype, distribution channel, and coverage feature penetration. CAGRs were derived from trend extrapolation of fleet operator growth trajectories and individual motorist policy upgrade rates, with inputs including autonomous vehicle trial progression timelines and Personal Data Protection Commission consent framework evolution.
Underlying assumptions cover stable Monetary Authority of Singapore risk-based capital requirements and continued ride-hailing fleet expansion, with deviation risk concentrated in reinsurance capacity availability during catastrophic loss events and telematics adoption velocity among individual motorists. Revision becomes warranted when embedded insurance API penetration crosses thresholds that materially displace traditional agent channel volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Japan Car Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
United Kingdom Motor Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
India Car Insurance Market