
 Crop Agricultural Insurance Market | 2026-2036
Crop Agricultural Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Agricultural Insurance Market Insights
Claims-processing automation is rewriting where margin pools accumulate across the crop insurance value chain. PICC Property and Casualty Company Limited leverages its state-backed distribution network to dominate China's provincial pilot programs. Chubb Limited anchors its competitive position through specialized underwriting expertise in North American row-crop and specialty-crop segments. QBE Insurance Group competes across Australian broadacre and emerging Asian markets with weather-indexed products.
Crop agricultural insurance constitutes risk-transfer instruments that indemnify agricultural producers against yield shortfalls, revenue declines, or weather-driven losses through parametric triggers or actual-loss verification, with policies typically calibrated to growing-degree days, rainfall thresholds, or historical average yields. The primary purpose centers on stabilizing farm income volatility and securing credit access for planting-season input financing. Yield-based and revenue-based products command the largest premium volumes in mature markets, while weather-based index insurance captures the fastest expansion in regions with sparse ground-adjustment infrastructure. Distribution through agricultural cooperatives and bancassurance channels concentrates in developing markets where lender-mandated coverage drives origination.
The USDA's Risk Management Agency shapes product design and premium subsidy structures across federally backed programs in the United States, while India's PMFBY operational guidelines administered by the Ministry of Agriculture mandate uniform premium rates and technology-based crop-cutting experiments for claims settlement. China's NMPA and provincial agricultural commissions supervise pilot expansions of policy-type innovations tied to grain-security targets. Stakeholders must monitor how regulator-mandated technology adoption in claims verification reshapes operating cost structures and competitive differentiation between public and private program administrators.
Market Dynamics
Parametric triggers anchored to satellite-derived vegetation indices are compressing claims settlement cycles from months to weeks, redistributing value capture toward data infrastructure providers and away from traditional loss-adjusters.
Growth Catalysts
- India's PMFBY subsidy framework:Uniform premium rates and technology-based crop-cutting experiments expand coverage among smallholders previously excluded from commercial underwriting.
- Soy and corn operations in Brazil:Commercial growers scale multi-peril coverage as lender-mandated insurance becomes standard for input financing.
- Sentinel-2 and Landsat imagery:Free-access satellite data reduces basis risk in index products, enabling program expansion in regions lacking ground-based weather stations.
Market Restraints
- Basis risk in rainfall-indexed products:Mismatch between measured precipitation and actual field-level moisture stress limits uptake among risk-averse smallholders.
- Actuarial data scarcity in Sub-Saharan Africa:Sparse historical yield records inflate premium loading factors and constrain private market entry.
- Subsidy dependency in mature programs:Farmer willingness-to-pay collapses when government premium support phases out, as observed in pilot withdrawals.
Strategic Opportunities
- Livestock mortality index products in Kenya and Ethiopia:Pastoralist communities remain underserved by conventional indemnity-based coverage.
- Integration of soil moisture probes with drone imagery:Converging ground-truth sensors and aerial platforms enable granular risk stratification at sub-field resolution.
- China's provincial pilot expansions:NMPA-supervised grain-security targets create procurement pathways for revenue-protection products tied to commodity price floors.
Industry Challenges
- Remote sensing interpretation expertise:Underwriters lack personnel trained in agronomic modeling and satellite data analytics.
- Legacy core system integration:Established carriers struggle to embed parametric triggers into policy administration platforms designed for indemnity workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Agricultural Insurance Market |
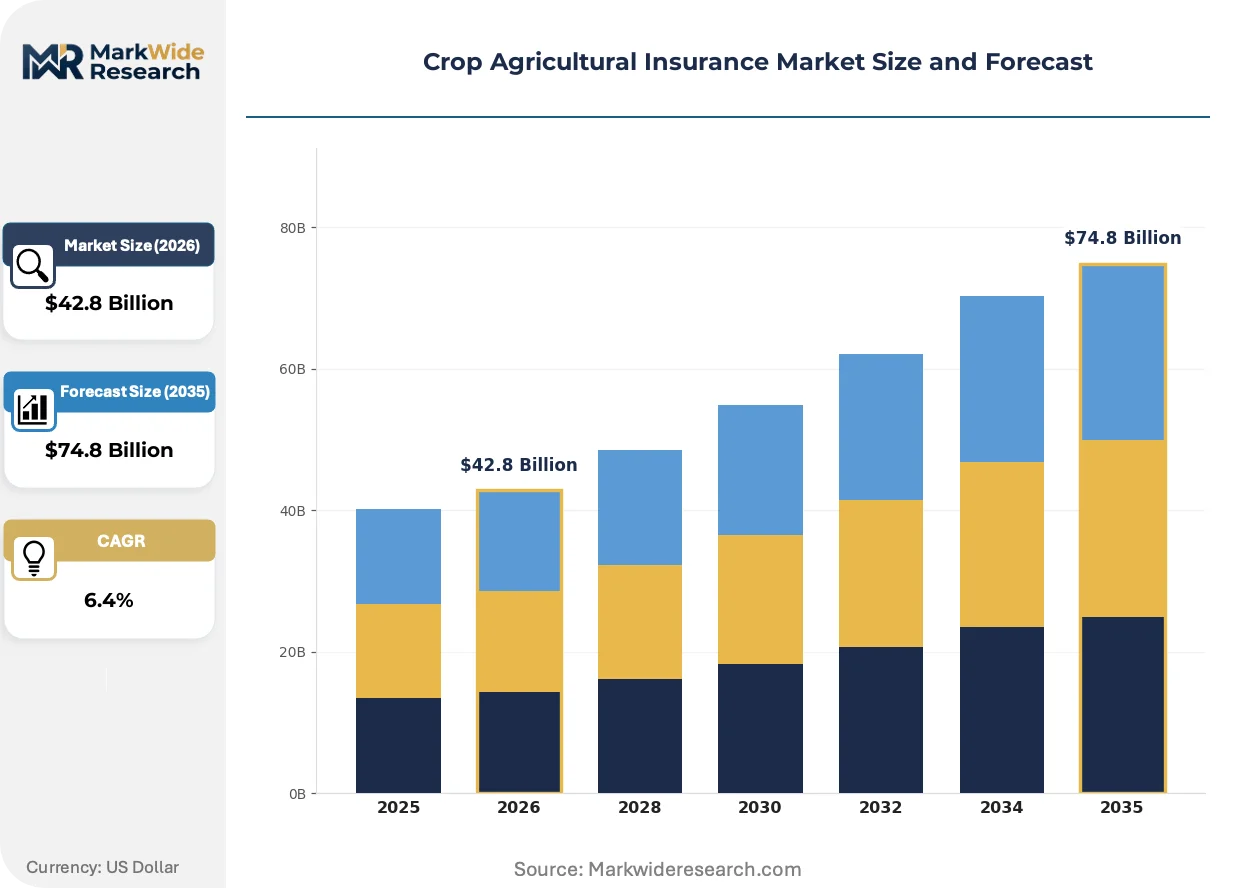
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Yield-Based, Weather-Based, Revenue-Based, Multi-Peril, Area-Based Coverage Scope: Single Crop, Multiple Crops, Whole-Farm, Dollar, Group Distribution Channel: Direct Sales, Insurance Brokers, Bancassurance, Online Platforms, Agricultural Cooperatives End User: Smallholder Farmers, Commercial Growers, Agribusiness Firms, Contract Farmers |
| Companies Covered | PICC Property and Casualty Company Limited, Chubb Limited, QBE Insurance Group, Tokio Marine HCC, Zurich Insurance Group, Agriculture Insurance Company of India, Great American Insurance Company, ICICI Lombard General Insurance Company Limited, Sompo Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Agricultural Insurance Market Trends and Innovations
Claims verification infrastructure is pivoting from human-adjusted field visits to automated detection pipelines, compressing operating cost structures and redefining competitive moats around data acquisition rather than adjuster networks.
Satellite-based index triggers is migrating from experimental pilots to core product architecture across emerging-market programs. Agriculture Insurance Company of India and private underwriters in Brazil now embed normalized difference vegetation index thresholds directly into policy terms. This compression of the verification layer eliminates loss-adjustor field deployments and shifts margin pools toward imagery providers and agronomic modelers.
USDA's Risk Management Agency is tightening data quality standards for approved insurance providers participating in federally backed programs. The agency now mandates standardized reporting formats for acreage and production data. North American row-crop carriers are responding by investing in automated planting and harvest verification systems to maintain program eligibility.
Cooperative distribution channels in developing markets face disintermediation pressure from mobile-enabled direct sales platforms. Agricultural input retailers in India now bundle insurance with seed and fertilizer purchases through unified digital interfaces. This channel consolidation concentrates origination volume among integrated agribusiness platforms and compresses commissions for standalone broker networks.
Crop Agricultural Insurance Market Segmentation
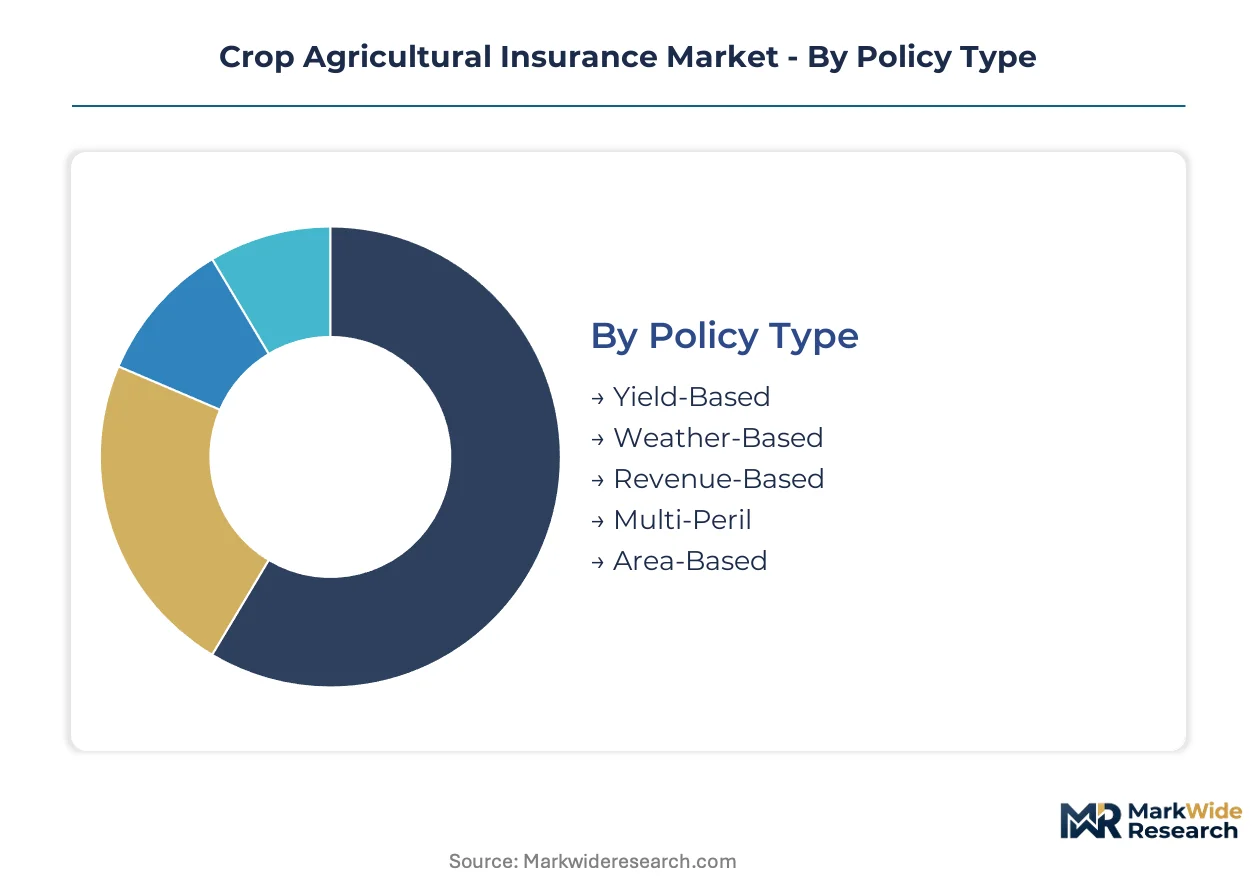
Segmentation in crop agricultural insurance determines pricing precision, distribution economics, and technology deployment priorities. Policy design choices directly influence claims verification costs and reinsurance structuring across divergent farm scales and risk profiles.
Policy Type:
Cycle times vary dramatically: weather-based parametric products settle claims within weeks of trigger events, while multi-peril indemnity policies require months of field verification and loss adjustment.
- Yield-Based:Indemnity triggers activate when realized farm yields fall below county-average or individual historical benchmarks. USDA's Risk Management Agency dominates this segment through federally subsidized programs covering corn, soybeans, and wheat in the United States.
- Weather-Based:Parametric structures linked to rainfall thresholds, growing-degree days, or satellite-derived vegetation indices eliminate loss-adjustment delays. India's PMFBY has accelerated adoption here through technology-based crop-cutting experiments that compress settlement cycles.
- Revenue-Based:Protects against combined yield and price risk through futures-market price guarantees. Commercial growers in North American row-crop regions favor this structure for lender-mandated coverage securing input financing.
- Multi-Peril:Comprehensive coverage spanning drought, flood, pest, and disease losses through named-peril bundling. Brazil's commercial soy and corn operations drive demand as lender requirements harden.
- Area-Based:Index triggers calibrated to regional average yields rather than individual farm performance, reducing adverse selection and administrative overhead. Sub-Saharan African pilot programs leverage this design where ground-truth data remains sparse.
Yield-Based policies anchor the volume base in mature subsidized markets while Weather-Based products gain share at the steepest rate in emerging economies lacking adjustment infrastructure.
Coverage Scope:
Cost tiering separates premium pricing: whole-farm and group policies achieve scale economies through pooled risk pools, while single-crop coverage commands higher per-acre administrative loading.
- Single Crop:Standalone policies covering one commodity type with tailored triggers and coverage levels. Cotton and specialty-crop growers in California and Texas prefer this precision for crops with distinct risk profiles.
- Multiple Crops:Bundled coverage across two to three commodities common in diversified operations. Midwest grain farms pairing corn and soybeans dominate this segment.
- Whole-Farm:Enterprise-level protection aggregating all agricultural production under unified revenue or yield guarantees. Large commercial operations in Australia and Canada favor this for administrative simplicity.
- Dollar:Fixed-sum coverage specifying indemnity amounts regardless of actual planted acreage or yield outcomes. Contract farmers with predetermined delivery obligations select this structure.
- Group:Community-rated products where premiums and payouts depend on aggregate regional performance rather than individual outcomes. Agricultural cooperatives in India distribute these to smallholder collectives.
Whole-Farm coverage dominates premium volumes among commercial operations while Group products expand most quickly among smallholder populations served through cooperative channels.
Distribution Channel:
Customer type dictates channel economics: agribusiness firms prefer direct underwriting relationships, while smallholders concentrate in cooperative and bancassurance networks where credit bundling drives origination.
- Direct Sales:Carrier-employed agents or captive distribution targeting large commercial accounts with complex risk profiles. Chubb Limited and QBE Insurance Group deploy specialized underwriters for this segment.
- Insurance Brokers:Independent intermediaries serving mid-scale operations requiring product comparison and placement advice. North American specialty-crop regions retain broker involvement for non-standard coverage.
- Bancassurance:Lender-mandated coverage embedded in planting-season input financing. Brazil's commercial agriculture sector has standardized this channel for soy and corn operations.
- Online Platforms:Mobile-enabled direct purchase with automated underwriting and satellite-based verification. India's input retailers now bundle insurance with seed and fertilizer through unified digital interfaces.
- Agricultural Cooperatives:Member-owned distribution leveraging collective bargaining and local trust relationships. Agriculture Insurance Company of India originates substantial volume through this channel.
Bancassurance maintains the largest premium flow while Online Platforms are climbing the fastest as mobile penetration deepens in rural markets.
End User:
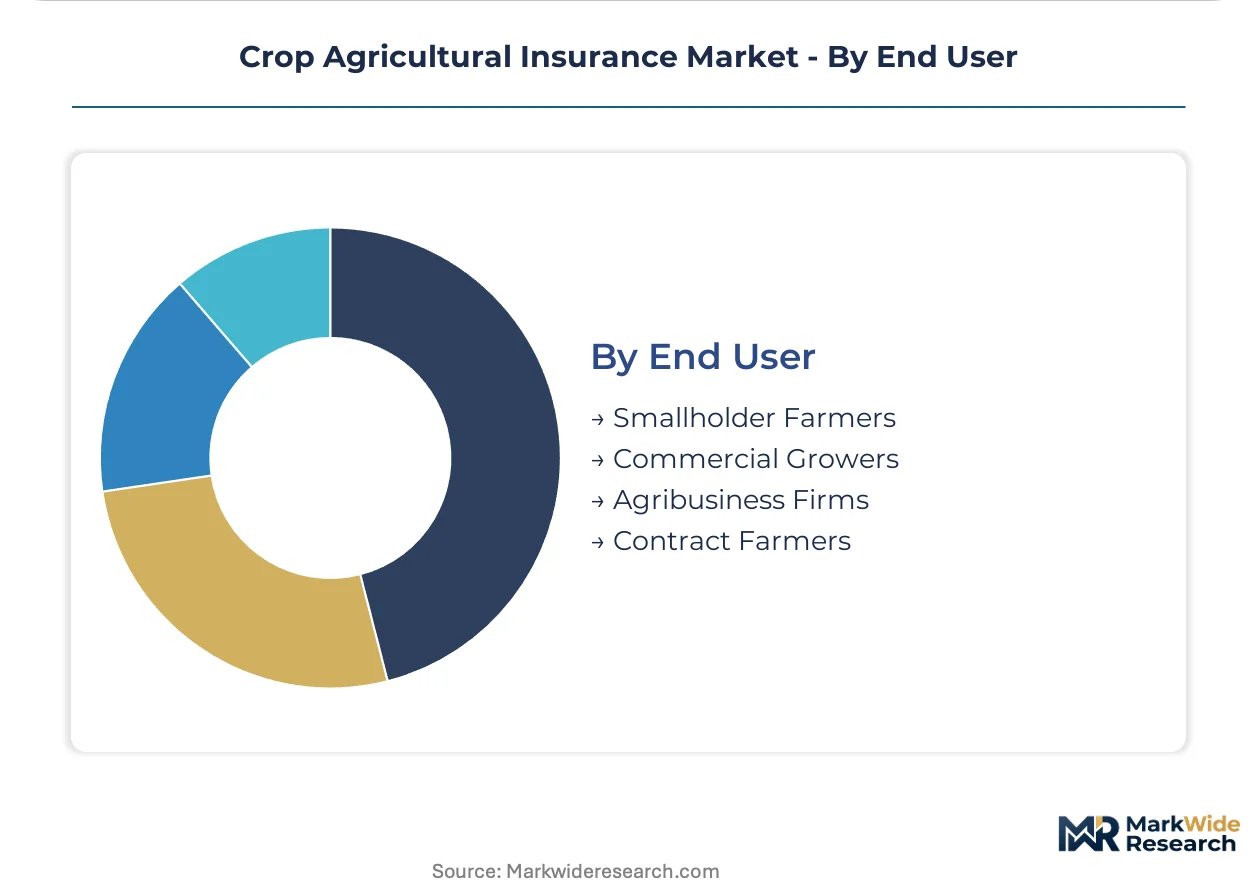
Maturity separates technology adoption: commercial growers and agribusiness firms demand satellite-verified parametric products, while smallholders remain anchored to traditional indemnity structures with government subsidy dependence.
- Smallholder Farmers:Operators cultivating under five hectares with limited risk-bearing capacity and credit access constraints. India's PMFBY subsidy framework targets this population through uniform premium rates and technology-based verification.
- Commercial Growers:Mid-to-large scale operations with lender-mandated coverage requirements and sophisticated risk management needs. Brazil's expanding soy and corn sector exemplifies this segment's growth trajectory.
- Agribusiness Firms:Vertically integrated enterprises with captive farming operations and portfolio-level risk transfer requirements. North American grain handlers and processors dominate demand here.
- Contract Farmers:Producers operating under fixed-price or fixed-volume agreements with processors or exporters. Poultry and horticulture supply chains in Southeast Asia concentrate this structure.
Commercial Growers generate the dominant premium base while Smallholder Farmers represent the steepest expansion opportunity as subsidy programs and mobile distribution penetrate previously excluded populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across geographies: smallholder-dominated markets exhibit elastic demand collapsing when subsidies withdraw, while commercial agriculture regions demonstrate inelastic willingness-to-pay for lender-mandated coverage. Brazil and India represent opposite poles of this elasticity spectrum.
United States
Commercial corn and soybean operations drive premium volumes across the Midwest Corn Belt. The USDA's Risk Management Agency mandates standardized acreage reporting and subsidizes yield-based and revenue-based products. Iowa and Illinois anchor program participation, with automated planting verification systems spreading across large-scale operations.
India
Smallholder populations exceeding 100 million operators create the world's largest addressable market for crop insurance. The Pradhan Mantri Fasal Bima Yojana framework administered by the Ministry of Agriculture mandates uniform premium rates and technology-based crop-cutting experiments. Maharashtra and Gujarat concentrate origination volume through Agriculture Insurance Company of India and private underwriter partnerships.
Brazil
Commercial soy and corn expansion in Mato Grosso and Goiás hardens lender-mandated coverage requirements for input financing. Brazil's national agricultural insurance program subsidizes premiums for family farming operations while commercial growers absorb full cost. São Paulo-based underwriters compete through multi-peril products with satellite-derived vegetation index triggers.
China
Provincial pilot expansions supervised by the NMPA tie policy innovation to grain-security targets. Heilongjiang and Henan provinces dominate premium generation through state-backed distribution networks. PICC Property and Casualty leverages its provincial branch infrastructure to capture volume in centrally directed programs.
Australia
Broadacre wheat and barley operations across Western Australia and New South Wales favor whole-farm revenue protection. QBE Insurance Group and domestic underwriters compete through weather-indexed products calibrated to rainfall anomalies. The Bureau of Meteorology data feeds parametric trigger mechanisms displacing traditional loss adjustment.
Crop Agricultural Insurance Market Competitive Landscape
State-backed domestic champions and global commercial underwriters split the market into distinct competitive spheres. Public-sector insurers leverage subsidy channel capture and regulatory preference in emerging markets, while international specialists deploy technical underwriting capacity in commercial agriculture segments. Three archetypes dominate: government-linked domestic carriers, global multi-line insurers with agricultural divisions, and regional specialists in parametric index products. Consolidation pressure intensifies through technology partnerships with satellite imagery providers and agronomic modeling platforms.
Within the state-linked tier, PICC Property and Casualty Company Limited and Agriculture Insurance Company of India exemplify channel dominance through government mandate and cooperative distribution. Chubb Limited occupies a position among global commercial underwriters specializing in North American row-crop and specialty-crop technical underwriting. QBE Insurance Group represents the regional specialist archetype with indexed product expertise across Australian broadacre and Asian emerging markets.
| Leading Market Players |
|---|
| PICC Property and Casualty Company Limited |
| Chubb Limited |
| QBE Insurance Group |
| Tokio Marine HCC |
| Zurich Insurance Group |
| Agriculture Insurance Company of India |
| Great American Insurance Company |
| ICICI Lombard General Insurance Company Limited |
| Sompo Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
Subsidy withdrawal risk in India's PMFBY framework determines both the compression of premium spreads between government-backed and commercial tiers and the geographic concentration of underwriting capacity around state-mandated distribution channels. This structural dependency creates pricing inflexibility that ripples through reinsurance layering and technology vendor selection across emerging-market programs.
Pricing Analysis
Reinsurance recovery rate drives lifetime value across multi-peril and parametric product lines. Three-tier pricing structure across premium, standard, and economy levels separates lender-mandated commercial coverage from subsidized smallholder programs and bare-bones area-index products. Cost compression in satellite-verified parametric tiers is intensifying because free-access Sentinel-2 imagery eliminates proprietary data licensing premiums. Agribusiness firms demonstrate the least price sensitivity due to portfolio-level risk transfer requirements, while smallholder collectives served through cooperative channels exhibit acute elasticity when government support phases out.
Supply Chain Analysis
Supply-chain finance facilities extended by satellite imagery providers and agronomic modeling platforms are compressing cash conversion cycles for program administrators. Underwriting capacity concentrates in India, Brazil, and the United States as regulatory frameworks and subsidy structures anchor carrier infrastructure. Proprietary vegetation-index algorithms, ground-truth sensor networks, and reinsurance treaty capacity constitute critical input dependencies. Single-source vulnerability in earth-observation data feeds from the European Space Agency's Sentinel constellation threatens program continuity. Distribution runs through agricultural cooperatives and bancassurance channels in developing markets, while direct underwriting relationships dominate commercial agriculture segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across policy-type architectures creates specialized niches as parametric triggers displace traditional indemnity workflows. Satellite-enabled verification infrastructure demands distinct capabilities from legacy loss-adjustment operations, spawning carve-out opportunities for data-native entrants.
For Market Incumbents: Entrench position through captive control over agronomic modeling talent and exclusive imagery partnerships that lock in vegetation-index calibration expertise. Defensive consolidation around automated claims pipelines counters emerging data-analytics specialists. Investment in USDA Risk Management Agency compliance infrastructure preserves eligibility in federally subsidized programs as data quality standards tighten. For New Entrants and Emerging Players: Establish a beachhead in livestock mortality index products across Kenyan and Ethiopian pastoralist communities where conventional indemnity coverage remains absent. White-space concentration in soil-moisture probe integration with drone imagery enables sub-field risk stratification at resolution levels legacy carriers cannot match. Go-to-market execution through mobile-enabled direct sales platforms bypasses cooperative channel disintermediation pressures. For Investors and Strategic Acquirers: China's NMPA provincial pilot expansions reshape the acquisition landscape by creating procurement pathways for revenue-protection products tied to grain-security targets. Long-term viability favors carriers with demonstrated parametric product architecture and satellite-data integration capabilities. Acquisition target archetype: regional specialists with indexed product expertise and established Bureau of Meteorology or equivalent meteorological agency data partnerships. Watch for inflection when regulator-mandated technology adoption thresholds trigger carrier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Architecture Migration | Shifts margin pools toward imagery providers and agronomic modelers away from field adjusters. |
| Satellite Data Partnership Exclusivity | Locks in vegetation-index calibration expertise that determines claims trigger accuracy. |
| Regulatory Compliance Infrastructure Investment | Maintains USDA Risk Management Agency program eligibility as data quality standards tighten. |
| Mobile Platform Distribution Buildout | Captures smallholder origination volume as cooperative channels face disintermediation pressure. |
| Soil Moisture Sensor Network Deployment | Enables sub-field resolution risk stratification that differentiates pricing precision. |
Research Methodology
A standing panel of crop insurance program administrators, reinsurance treaty underwriters, satellite imagery specialists, and agricultural cooperative distribution managers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from USDA Risk Management Agency program bulletins, India's PMFBY operational guidelines, China's NMPA provincial pilot directives, and European Space Agency Sentinel data access documentation. Bottom-up policy volume aggregation and top-down premium pool estimation were triangulated against reinsurance market capacity reports.
Scenario-bracketing across subsidy continuation, satellite data access cost trajectories, and parametric trigger adoption curves bounded the projection range. Segmentation dimensions modeled include policy type, coverage scope, distribution channel, and farm-scale archetype across the analysis window. CAGRs were derived from elasticity-adjusted penetration curves and reinsurance pricing cycle assumptions. Forecast inputs incorporated growing-degree day volatility indices and commodity price correlation matrices specific to row-crop and specialty-crop exposures.
Stress conditions across monsoon failure frequency, government premium support withdrawal timing, and earth-observation data feed interruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology adoption thresholds and regulatory mandate enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
US Motor Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
Private Passenger Auto Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Russia Car Insurance Market
Motor Insurance
Malaysia Motor Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Canada Motor Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
China Car Insurance Market