
 India Motor Insurance Market | 2026-2036
India Motor Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Motor Insurance Market Outlook
Multi-channel distribution is expanding across the India motor insurance landscape as insurers reduce sole reliance on traditional agent networks. ICICI Lombard General Insurance leverages its digital infrastructure to capture direct-to-consumer premiums, while Bajaj Allianz General Insurance anchors its position through extensive rural agency penetration. HDFC ERGO General Insurance competes by specializing in commercial fleet solutions with tailored underwriting capabilities.
India motor insurance constitutes risk-transfer contracts covering financial liability arising from vehicle ownership, operation, or damage, with policies structured around actuarial pricing models incorporating vehicle age, engine displacement cubic capacity, and insured declared value calculations. Third-party coverage dominates policy volumes due to statutory mandate under the Motor Vehicles Act, while pay-as-you-drive products represent the fastest-growing structural segment as telematics-enabled usage-based pricing gains regulatory traction. Comprehensive coverage retains the deepest margin pools despite higher acquisition costs, particularly among premium vehicle owners in metropolitan clusters.
The Insurance Regulatory and Development Authority of India mandates minimum third-party coverage and governs premium rate filings, while the Insurance Information Bureau maintains centralized claims and vehicle data repositories that standardize risk assessment protocols. The Ministry of Road Transport and Highways enforces vehicle fitness and registration linkages that directly determine policy validity and renewal cycles. Stakeholders must monitor how embedded telematics and real-time driving data reshape product design, pricing granularity, and fraud detection architectures.
Market Dynamics
Telematics-enabled usage-based insurance is compressing traditional actuarial pricing models across India's motor insurance sector, forcing insurers to rebuild risk assessment around real-time driving behavior rather than static vehicle attributes.
Growth Catalysts
- Long-term third-party mandate:The Insurance Regulatory and Development Authority of India's mandatory multi-year third-party policy framework locks in premium volumes and reduces policy lapse rates for commercial fleets.
- Fleet digitization:Commercial vehicle operators in Maharashtra and Gujarat are adopting GPS-linked fleet management systems that integrate directly with insurer telematics platforms for dynamic premium adjustments.
- Rural agency expansion:Tier-2 and Tier-3 cities across Madhya Pradesh and Rajasthan are driving new policy origination through localized agent networks penetrating previously uninsured vehicle populations.
Market Restraints
- Claims fraud concentration:Staged accidents and inflated repair billing in Delhi-NCR and Mumbai metropolitan clusters erode combined ratios for comprehensive coverage products.
- Reinsurance capacity constraints:Global reinsurers are tightening capacity for Indian motor catastrophe exposure following consecutive monsoon-related flood loss events.
- Legacy IT fragmentation:Mid-tier insurers operate on policy administration systems that cannot ingest real-time telematics data streams, delaying usage-based product rollout.
Strategic Opportunities
- Embedded insurance integration:OEMs and ride-hailing platforms in Bengaluru and Hyderabad are white-labeling motor coverage at point-of-sale, bypassing traditional distribution friction.
- Pay-as-you-drive regulatory sandbox:The Insurance Regulatory and Development Authority of India's experimental framework for mileage-linked premiums opens product design flexibility for low-utilization vehicle owners.
- Two-wheeler underpenetration:Uttar Pradesh and Bihar present substantial addressable markets where third-party compliance remains below statutory thresholds despite enforcement tightening.
Industry Challenges
- Telematics data standardization:Insurers lack uniform protocols for ingesting driving behavior feeds from heterogeneous OEM and aftermarket device manufacturers, complicating actuarial model calibration.
- Claims workforce scaling:Surge demand for field assessors in high-growth states outpaces trained talent pipeline development, extending claim settlement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Motor Insurance Market |
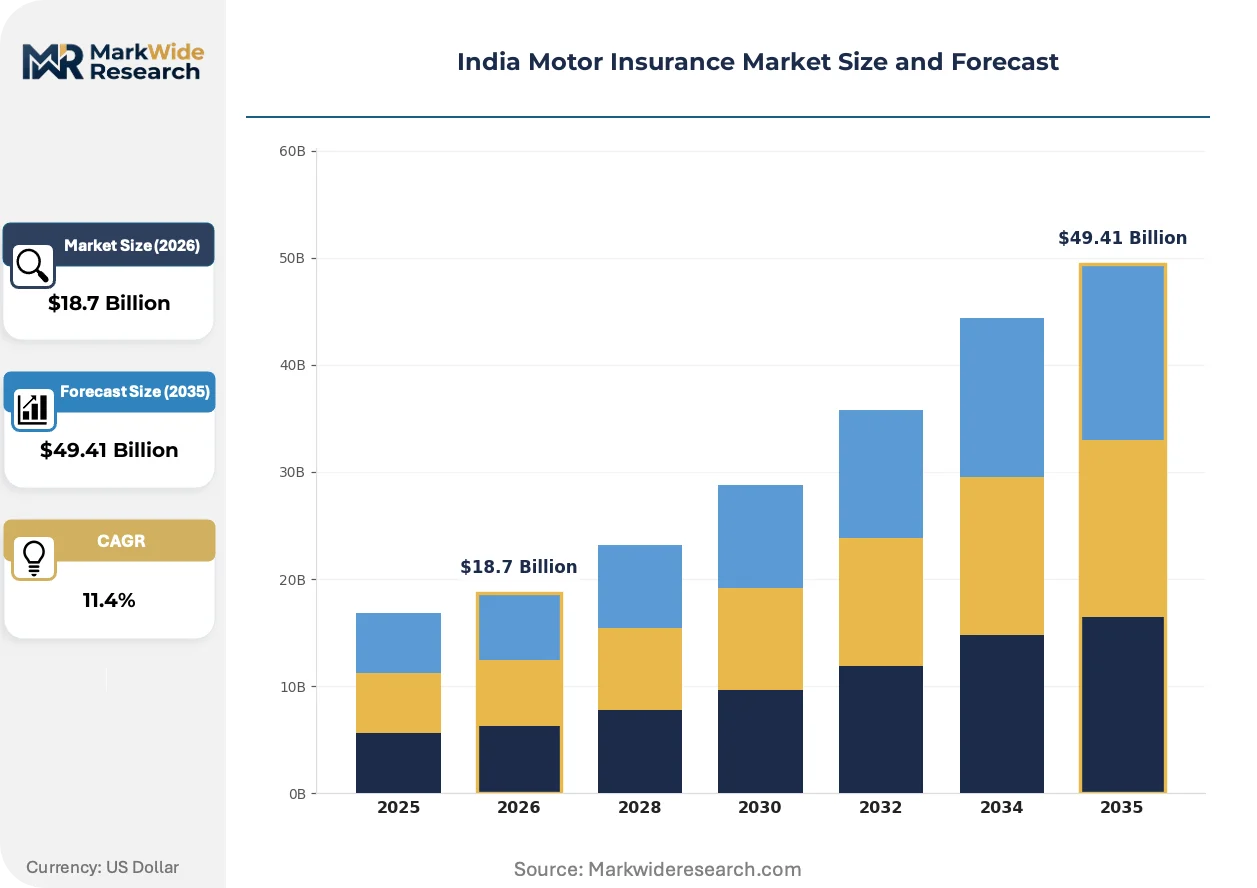
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Comprehensive, Third-Party, Standalone Own Damage, Pay-As-You-Drive Customer Type: Individual Owners, Fleet Owners, Commercial Vehicles, Ride-Sharing Services Distribution Channel: Online, Agents, Brokers, Direct Sales Coverage Type: Liability, Collision, Theft, Personal Injury Protection |
| Companies Covered | SBI General Insurance, IFFCO Tokio General Insurance, HDFC ERGO General Insurance, Tata AIG General Insurance, Universal Sompo General Insurance, ICICI Lombard General Insurance, Future Generali India Insurance, New India Assurance, Bajaj Allianz General Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Motor Insurance Market Strategic Shifts
Real-time data infrastructure is displacing retrospective underwriting across India's motor insurance value chain, compressing the gap between risk exposure and price adjustment from annual cycles to instantaneous recalibration.
Artificial intelligence-driven claims assessment is unifying damage evaluation and fraud detection into single-pass workflows. Insurers in Tamil Nadu and Karnataka are deploying computer vision models trained on regional vehicle damage patterns. This convergence is eliminating separate physical inspection and document verification stages, reducing claim settlement timelines from weeks to hours.
The Insurance Regulatory and Development Authority of India's sandbox framework for usage-based motor products is enabling premium calculation tied to actual kilometers driven. Commercial fleet operators in Ahmedabad and Pune are piloting policies where monthly premiums adjust based on telematics-reported mileage brackets. This regulatory flexibility is attracting technology partnerships between insurers and automotive OEMs seeking embedded coverage differentiation.
Digital-first distribution is capturing younger vehicle owners who bypass agent-mediated purchase journeys. Direct-to-consumer platforms in Mumbai and Delhi are converting two-wheeler buyers through mobile-optimized quote-to-bind experiences under ten minutes. This channel shift is forcing traditional agency networks to reposition toward complex commercial fleet advisory rather than transactional retail policy sales.
India Motor Insurance Market Segmentation
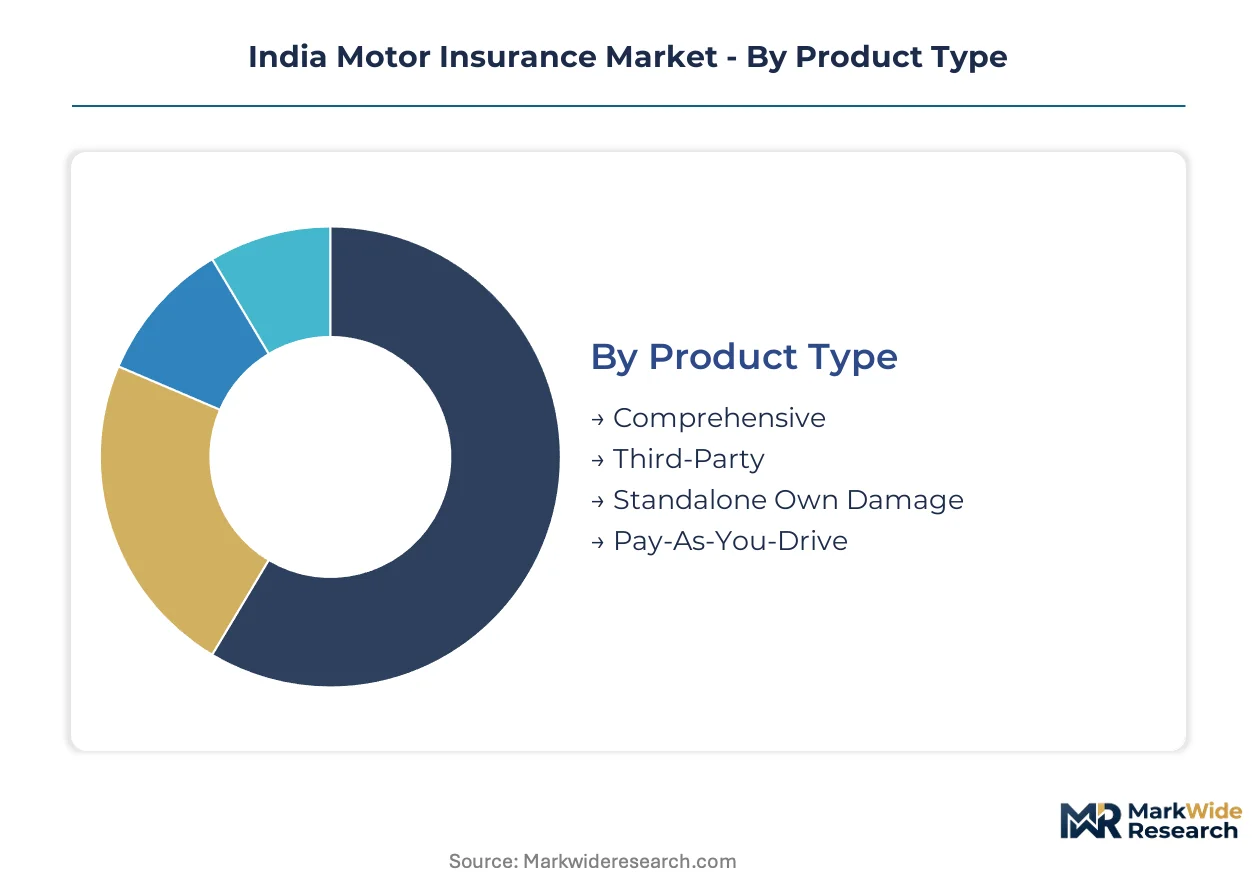
Segmentation in India's motor insurance sector reveals divergent profitability profiles across product structures and customer archetypes. Insurers calibrate capital allocation, distribution investment, and technology deployment differently for each segment based on claims frequency, renewal stickiness, and data availability for pricing refinement.
Product Type:
Third-party coverage dominates policy volumes while comprehensive products concentrate margin pools, creating a volume-versus-value tension that shapes insurer portfolio strategy.
- Comprehensive:Bundles own-damage protection with third-party liability under single policy contracts. Demand clusters among premium vehicle owners in Mumbai and Delhi where repair costs justify higher premiums despite elevated acquisition expenses.
- Third-Party:Statutorily mandated coverage under the Motor Vehicles Act limiting insurer liability to external damages and bodily injury. Maharashtra and Gujarat generate the densest policy concentrations due to commercial vehicle registration intensity and enforcement rigor.
- Standalone Own Damage:Decoupled coverage for vehicle self-damage purchased alongside mandatory third-party policies. Uptake accelerates among used vehicle owners seeking flexible protection without full comprehensive premiums.
- Pay-As-You-Drive:Telematics-linked mileage brackets determine premium obligations dynamically. The Insurance Regulatory and Development Authority of India's sandbox framework enables pilots in Bengaluru and Pune where low-utilization vehicle owners cluster.
Mature deployment sits with Third-Party coverage. Newer deployment is concentrated in Pay-As-You-Drive products.
Customer Type:
Commercial vehicle exposure demands specialized underwriting capabilities that retail personal lines cannot replicate, segmenting the market by operational complexity and loss severity potential.
- Individual Owners:Personal vehicle policyholders purchasing through agent networks or direct digital channels. Tamil Nadu and Karnataka exhibit dense concentrations of two-wheeler owners migrating from uninsured to compliant status.
- Fleet Owners:Multi-vehicle operators requiring centralized policy administration and loss control programs. GPS-linked fleet management integration in Ahmedabad and Pune enables dynamic premium adjustments based on real-time utilization data.
- Commercial Vehicles:Trucks, buses, and cargo carriers operating under goods carriage permits with elevated third-party exposure. Uttar Pradesh and Bihar present substantial addressable markets where enforcement tightening drives compliance conversion.
- Ride-Sharing Services:Platform-mediated drivers requiring hybrid personal-commercial coverage structures. Hyderabad and Chennai host concentrated demand from aggregator-affiliated vehicle operators seeking seamless coverage transitions between private and commercial use.
Individual Owners generate the deepest premium pools. Ride-Sharing Services are climbing the fastest as platform economics normalize insurance costs into per-trip pricing.
Distribution Channel:
Channel selection directly determines customer acquisition cost structures and data capture depth for subsequent pricing refinement and cross-selling.
- Online:Direct-to-consumer platforms converting quotes through mobile-optimized interfaces. Younger vehicle owners in metropolitan clusters complete purchase journeys under ten minutes, bypassing traditional agent mediation entirely.
- Agents:Localized representative networks penetrating Tier-2 and Tier-3 cities across Madhya Pradesh and Rajasthan. Personal relationships sustain renewal retention where digital literacy remains limited.
- Brokers:Intermediaries aggregating multiple insurer offerings for commercial clients with complex risk profiles. Corporate fleet procurement in Delhi-NCR and Mumbai leverages broker negotiation for coverage customization.
- Direct Sales:Insurer-employed field force targeting high-value commercial accounts. Bancassurance partnerships and OEM point-of-sale integration in Bengaluru and Hyderabad expand reach without intermediary commission burdens.
Agent networks retain the widest geographic footprint. Online channels are gaining share fastest as smartphone penetration deepens in semi-urban markets.
Coverage Type:
Risk transfer scope varies by peril specificity, with liability coverage mandated universally and optional protections calibrated to asset value and driver exposure.
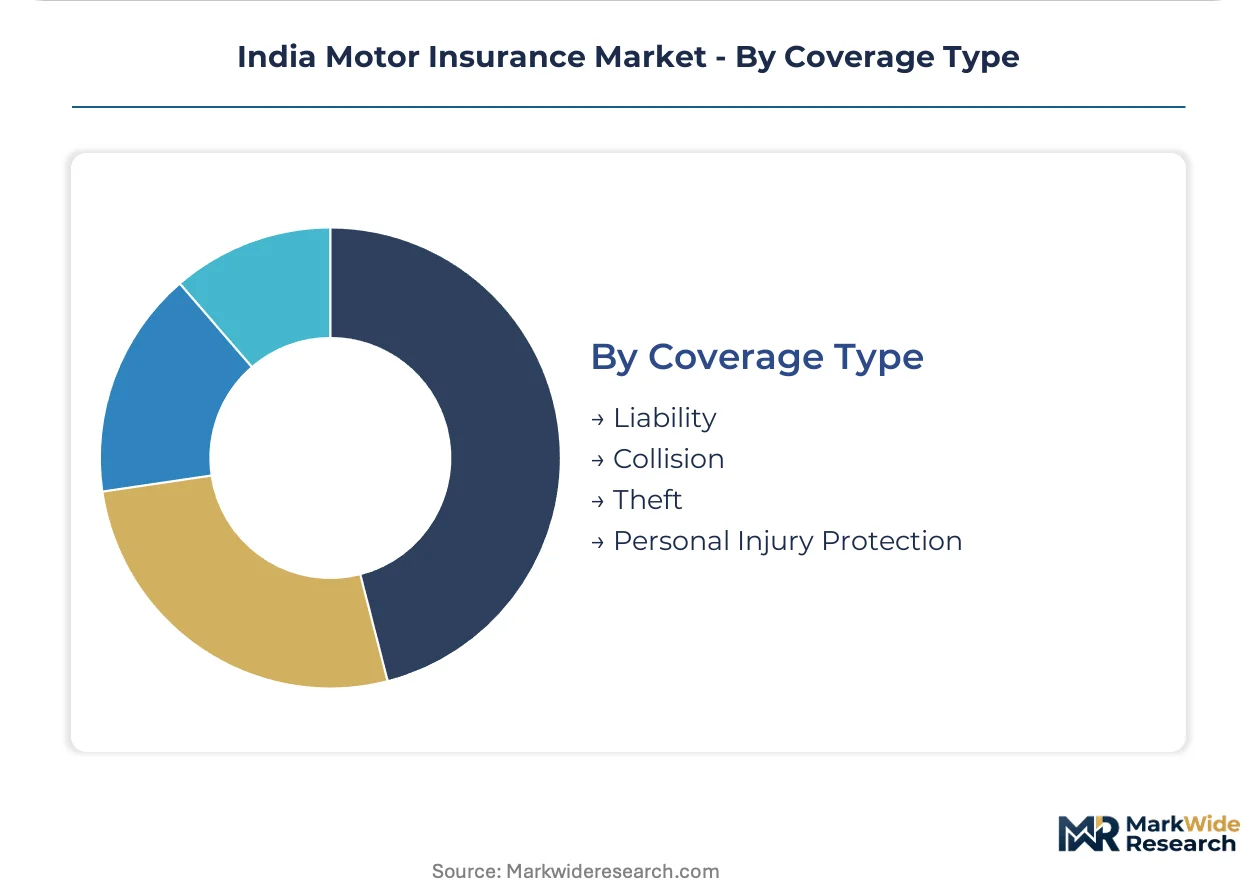
- Liability:Legally compulsory protection against third-party bodily injury and property damage. The Insurance Regulatory and Development Authority of India governs premium rate filings through standardized tariff structures.
- Collision:Own-damage protection for accident-induced vehicle impairment. Premium vehicle owners in metropolitan clusters prioritize this coverage where repair costs exceed depreciation-adjusted vehicle values.
- Theft:Protection against total loss from vehicle stealing or hijacking. Demand concentrates in urban agglomerations with elevated crime incidence and organized vehicle theft networks.
- Personal Injury Protection:Medical expense and disability coverage for occupants regardless of fault attribution. Limited penetration in India compared to mature markets due to overlapping health insurance coverage and regulatory non-mandate.
Liability coverage anchors statutory compliance. Collision protection is expanding most quickly as comprehensive policy uptake rises among asset-conscious vehicle owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's dense commercial vehicle corridors and Gujarat's logistics hubs anchor motor insurance demand across India's western seaboard. The Insurance Regulatory and Development Authority of India's state-level enforcement variations create divergent compliance environments that reshape premium collection patterns.
Maharashtra
Mumbai and Pune metropolitan clusters concentrate comprehensive policy demand among premium vehicle owners. The state's Motor Vehicles Department enforces third-party coverage verification through automated checkpoint integration. Nashik and Nagpur logistics corridors drive commercial fleet policy origination as interstate cargo movement intensifies.
Gujarat
Ahmedabad and Surat industrial belts generate dense commercial vehicle registration activity requiring specialized underwriting. The state's e-Vahan platform links registration data directly with insurer policy administration systems. Mundra and Hazira port zones anchor marine-cargo fleet coverage purchases as container throughput expands.
Karnataka
Bengaluru's technology workforce accelerates digital-first policy purchase adoption through mobile platforms. The state's transport department mandates GPS installation for commercial permits, enabling telematics-linked premium structures. Mysuru and Hubli-Dharwad corridors witness rising two-wheeler compliance conversion as enforcement tightens.
Tamil Nadu
Chennai's automotive manufacturing ecosystem creates captive demand for fleet coverage among component suppliers. The state's Regional Transport Office digitization reduces policy renewal friction for commercial operators. Coimbatore and Madurai industrial zones drive heavy commercial vehicle insurance purchases as manufacturing output climbs.
Delhi-NCR
The National Capital Region's vehicle density compresses claim settlement timelines through AI-driven assessment deployment. The Supreme Court-mandated insurance verification at pollution checkpoints enforces compliance among uninsured vehicle owners. Gurugram and Noida corporate fleet operators demand usage-based products as hybrid work patterns reduce utilization.
India Motor Insurance Market Competitive Environment
Global reinsurance capacity competes with domestic capital reserves across India's motor insurance sector, creating tiered competitive dynamics. The market structure fragments between public sector incumbents with legacy agency networks and private insurers deploying digital infrastructure. Three archetypes dominate: scale-driven multi-line insurers, technology-native digital specialists, and public sector carriers with branch penetration. Consolidation pressure is accelerating through bancassurance partnerships and embedded distribution tie-ups.
Within the scale-driven tier, ICICI Lombard General Insurance and HDFC ERGO General Insurance exemplify digital-first underwriting capabilities, while Bajaj Allianz General Insurance anchors extensive rural agency penetration. These private insurers occupy positions that leverage telematics integration and direct-to-consumer platforms against public sector distribution depth. SBI General Insurance represents the public sector archetype with branch-network reach into Tier-3 markets where digital literacy remains constrained.
| Leading Market Players |
|---|
| SBI General Insurance |
| IFFCO Tokio General Insurance |
| HDFC ERGO General Insurance |
| Tata AIG General Insurance |
| Universal Sompo General Insurance |
| ICICI Lombard General Insurance |
| Future Generali India Insurance |
| New India Assurance |
| Bajaj Allianz General Insurance |
| Others |
Value Chain & Pricing Dynamics
The Insurance Regulatory and Development Authority of India's mandatory long-term third-party policy framework gates both qualified supply and premium-tier pricing access, as only insurers with sufficient solvency reserves and approved rate filings can participate in the mandated multi-year coverage segment. This regulatory filter compresses pricing power among compliant incumbents while excluding undercapitalized regional players from the highest-volume product tier.
Pricing Analysis
Warranty and service bundling separates comprehensive coverage from bare third-party policies, with premium vehicle owners in Mumbai and Delhi paying elevated rates for packaged own-damage protection and concierge claim handling. Price differentiation rests on vehicle insured declared value brackets and geographic risk zones, with metropolitan clusters commanding higher premiums due to elevated theft and accident frequency. Pricing pressure stems from telematics-enabled usage-based products undercutting traditional annual premium structures. Individual two-wheeler owners in Tier-3 cities exhibit highest price sensitivity, while commercial fleet operators in Gujarat prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Domestic-content mandates under the Insurance Regulatory and Development Authority of India's data localization requirements reshape sourcing, forcing insurers to maintain India-based policy administration servers and claims processing infrastructure. Geographic supply concentration draws from domestic IT services providers in Bengaluru and Hyderabad, reinsurance capacity from London and Singapore markets, and telematics hardware from Chinese and Taiwanese component manufacturers. Raw material dependencies include cloud computing infrastructure, GPS tracking devices, and actuarial software licenses. Single-source vulnerability sits with concentrated reinsurance capacity for catastrophic motor exposure. Distribution runs through hybrid agent-digital networks with bancassurance partnerships penetrating semi-urban markets.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India motor insurance market functions as a cost-of-compliance story where the Insurance Regulatory and Development Authority of India's mandatory long-term third-party framework erects a barrier-to-entry moat that protects established players with approved rate filings and solvency reserves.
For Market Incumbents: Extend telematics integration depth to defend against digital-native entrants capturing usage-based segments. ICICI Lombard and HDFC ERGO should deepen backward integration into proprietary driving data analytics rather than relying on third-party device feeds. Capacity addition in Gujarat and Maharashtra commercial corridors anchors fleet market share against broker-mediated competition. Certification investment in IRDAI sandbox participation preserves first-mover positioning as regulatory frameworks evolve. For New Entrants and Emerging Players: Embedded insurance partnerships with automotive OEMs and ride-hailing platforms bypass traditional agency network barriers. White-label distribution at point-of-sale in Bengaluru and Hyderabad captures digitally native vehicle owners without legacy commission structures. Two-wheeler third-party compliance gaps in Uttar Pradesh and Bihar represent the most penetrable geography. Direct-to-consumer mobile platforms with sub-ten-minute quote-to-bind journeys attack the individual owner segment where agent relationships remain weakest. For Investors and Strategic Acquirers: IRDAI approval of pay-as-you-drive sandbox expansions beyond Bengaluru and Pune is the leading indicator that telematics-based pricing will achieve regulatory normalization and scale viability. Long-term viability favors insurers with captive data infrastructure and OEM integration pipelines rather than pure distribution plays. Acquisition targets should display embedded distribution agreements or proprietary fleet management system integrations. Watch for reinsurance capacity tightening signals as the marker for sector consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Insurers partnering with automotive OEMs in Chennai and Pune gain real-time driving data feeds for dynamic pricing. |
| Embedded Insurance Partnership | Ride-hailing platforms in Hyderabad white-label coverage at driver onboarding, reducing acquisition friction. |
| Long-term Policy Capacity Buildout | Solvency reserve enhancement enables participation in IRDAI-mandated multi-year third-party coverage segments. |
| Geographic Agency Expansion | Tier-2 and Tier-3 city penetration in Madhya Pradesh captures uninsured vehicle populations through localized networks. |
| AI Claims Assessment Deployment | Computer vision models trained on Tamil Nadu damage patterns compress settlement cycles from weeks to hours. |
Study Parameters
Document review covered Insurance Regulatory and Development Authority of India circulars, Insurance Information Bureau claims databases, and Motor Vehicles Department enforcement records, complemented by interviews with underwriting heads at private insurers, actuarial consultants, fleet operations managers in Maharashtra and Gujarat, and regional transport office administrators. Secondary validation drew from regulatory filings, industry association motor insurance bulletins, and telematics provider technical specifications. Bottom-up policy volume estimates triangulated against top-down premium collection data from regulatory disclosures.
Cross-referencing historical premium growth patterns against panel input from insurer strategy teams anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, customer archetype, distribution channel, and geographic risk zone. CAGRs derived from fitted trend lines adjusted for regulatory intervention timing and enforcement intensity variation by state. Industry-specific forecast inputs incorporated vehicle registration projections from transport department data and telematics adoption curves from pilot program disclosures.
Caveats apply where IRDAI regulatory amendments, monsoon severity affecting catastrophic loss ratios, or reinsurance capacity withdrawals could materially shift the outlook. Forecasts reflect documented assumptions about enforcement tightening pace and digital adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Bangladesh Motor Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
Global Commercial Auto Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
US Motor Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
New Energy Car Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
France Motor Insurance Market
Motor Insurance
Russia Car Insurance Market