
 Two-Wheeler Brake Pads Market | 2026-2036
Two-Wheeler Brake Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeler Brake Pads Market Analysis
Indian friction material producers is broadening export capacity for motorcycle brake pads to serve Southeast Asian OEM programs. Brembo S.p.A leverages its Italian motorsport heritage to dominate premium performance upgrade channels. Robert Bosch sustains aftermarket coverage through dense distribution networks spanning European and Asian repair shops. Endurance Technologies Limited anchors South Asian supply with integrated foundry-to-assembly operations serving domestic motorcycle manufacturers.
Two-wheeler brake pads are composite friction elements bonded to steel backing plates, engineered to deliver consistent coefficient of friction across wet and thermal cycles while limiting rotor wear. These components convert kinetic energy into heat through controlled surface abrasion, with sintered metallic formulations tolerating sustained temperatures above 350°C in high-performance motorcycle applications. Semi-metallic and ceramic formulations lead volume production due to their balance of thermal stability and cost efficiency, while carbon segments command premium positioning in racing and superbike categories where weight reduction and fade resistance justify elevated pricing. The aftermarket retailer channel captures the largest margin pool as rider-driven replacement cycles outpace OEM fitment volumes in mature two-wheeler markets.
India's BIS brake lining standards, Europe's REACH chemical restrictions on copper and heavy metals in friction materials, and the EPA's broader particulate emissions oversight collectively constrain formulation choices and supplier market access. These regulatory frameworks push manufacturers toward copper-free ceramic alternatives and extended testing protocols that extend product development timelines. Stakeholders must monitor evolving material bans and homologation requirements to align R&D pipelines with jurisdiction-specific compliance deadlines.
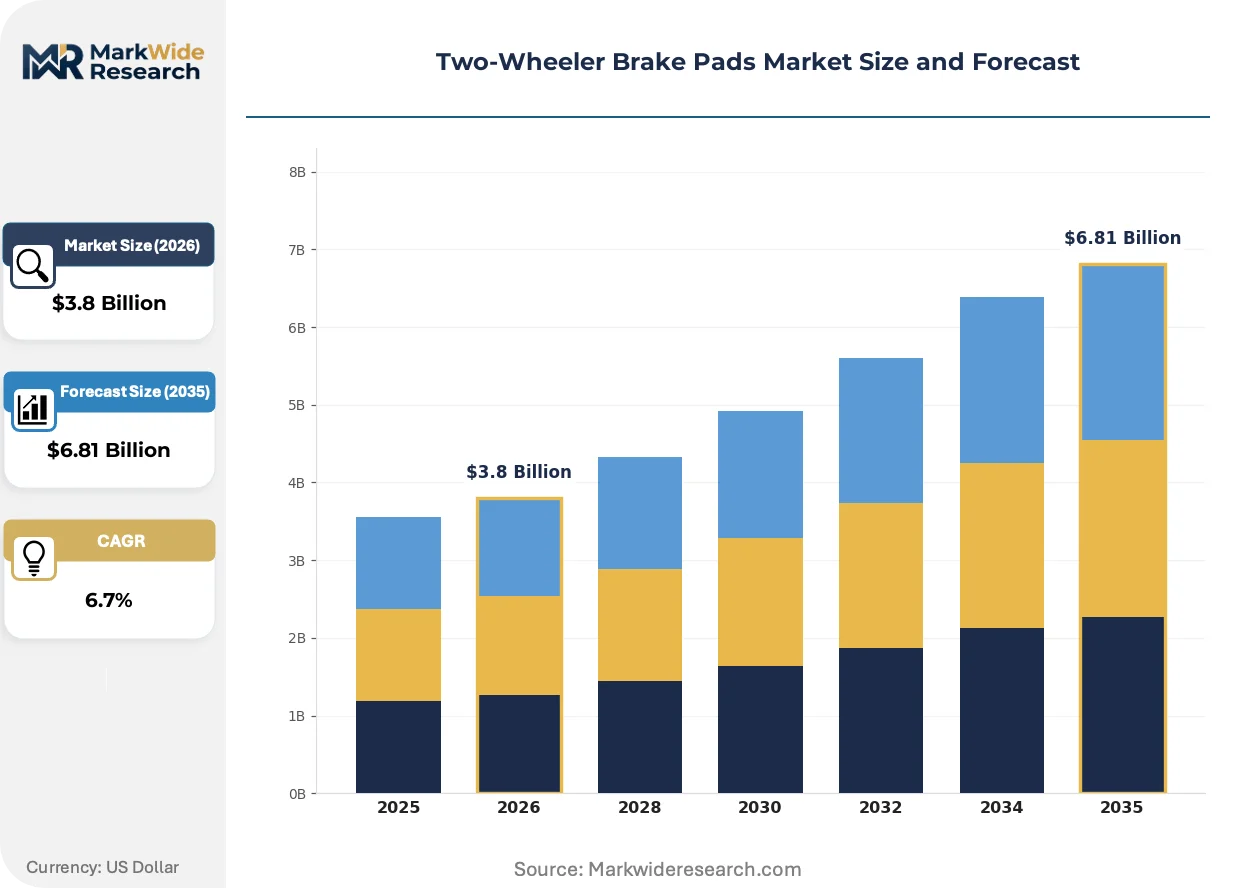
Market Dynamics
Replacement cycles in mature two-wheeler markets now outpace OEM fitment volumes, compressing supplier margins while amplifying aftermarket channel power across Southeast Asian urban corridors and Latin American secondary cities.
Growth Catalysts
- Indonesia's dense urban corridors:Two-wheeler ownership rates exceeding four-wheeler penetration by multiples create sustained friction component demand from fleet expansion and wear-based replacement.
- BIS certification mandates:India's tightening material specifications for automotive brake linings are disqualifying substandard suppliers and consolidating qualified vendor pools.
- Sintered metallic formulations:High-performance motorcycle applications requiring sustained temperature tolerance above 350°C are pulling premium material adoption into mid-tier segments.
Market Restraints
- Copper and heavy metal bans:Europe's REACH chemical restrictions are forcing complete reformulation of legacy friction materials, extending R&D timelines and raising qualification costs.
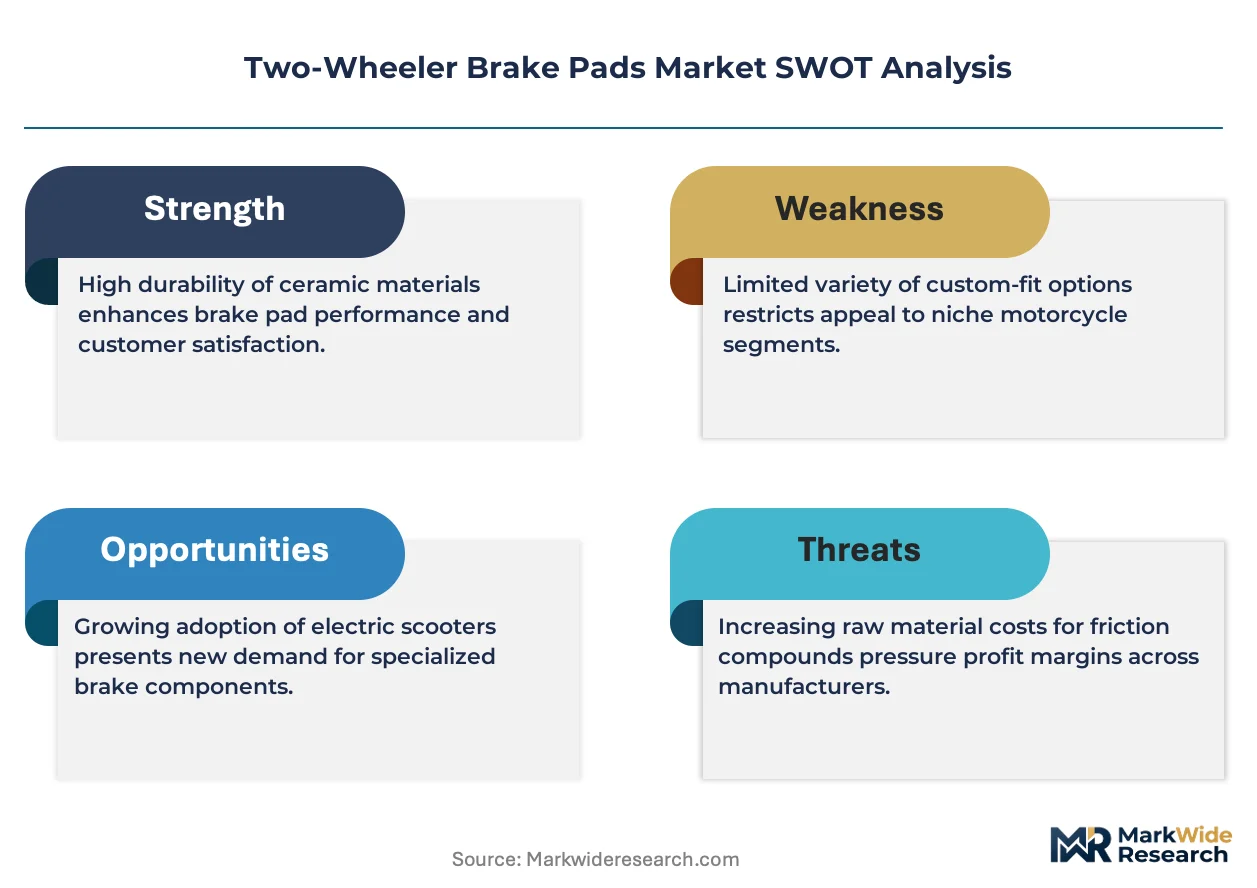
- Raw material concentration:Synthetic fiber and ceramic powder supply chains cluster in specific East Asian production zones, exposing formulators to single-source vulnerability.
- Homologation complexity:Jurisdiction-specific testing protocols for brake lining certification create fragmented approval requirements that block rapid geographic expansion.
Strategic Opportunities
- Copper-free ceramic alternatives:Regulatory pressure from EPA particulate emissions oversight and European material bans is opening premium positioning for compliant formulations.
- Integrated foundry-to-assembly operations:Captive steel backing plate production and friction material bonding under one roof compresses cost structures and accelerates OEM program responsiveness.
- Racing and superbike categories:Carbon segment brake pads commanding elevated pricing through weight reduction and fade resistance benefits justify dedicated premium product lines.
Industry Challenges
- Formulation chemistry expertise:Scarcity of tribology specialists capable of balancing coefficient of friction consistency across wet and thermal cycles constrains product development velocity.
- Multi-jurisdiction compliance:Simultaneous tracking of India's BIS updates, Europe's REACH amendments, and EPA enforcement patterns demands dedicated regulatory intelligence functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeler Brake Pads Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Semi-Metallic, Ceramic, Carbon End User: OEMs, Aftermarket Retailers, Repair Shops, Distributors Application: Motorcycles, Scooters, E-Bikes, Off-Road Bikes Upgrade Type: Standard, Performance, Racing, Eco-friendly |
| Companies Covered | EBC Brakes, Nisshinbo Holdings Inc., Brembo S.p.A, SBS Friction A/S, Akebono Brake Industry, Robert Bosch, Tenneco Inc., Endurance Technologies Limited, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeler Brake Pads Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning, with formulation choices now determining market access rather than merely product performance.
Ceramic matrix composites incorporating non-asbestos organic binders are electrifying brake pad performance benchmarks by delivering thermal stability without copper content. Premium motorcycle OEMs in Italy and Japan are adopting these formulations for 2027 model year platforms. This technology is electrifying supplier qualification requirements as foundries without ceramic pressing capabilities face exclusion from tier-one supply programs.
Europe's REACH chemical restrictions on copper and heavy metals in friction materials are eliminating legacy semi-metallic formulations from EU market access. Manufacturers must now complete extended emissions testing protocols before commercialization. The aftermarket channel across Germany, France, and Benelux is responding by accelerating inventory turnover toward pre-certified copper-free alternatives.
Direct-to-rider digital platforms are compressing traditional distributor layers in replacement brake pad procurement. Independent repair shops in São Paulo, Bangkok, and Mexico City now source friction components through mobile-enabled B2B marketplaces rather than regional wholesalers. This channel shift is most visible in Southeast Asian secondary cities where two-wheeler density supports same-day delivery economics.
Two-Wheeler Brake Pads Market Segmentation
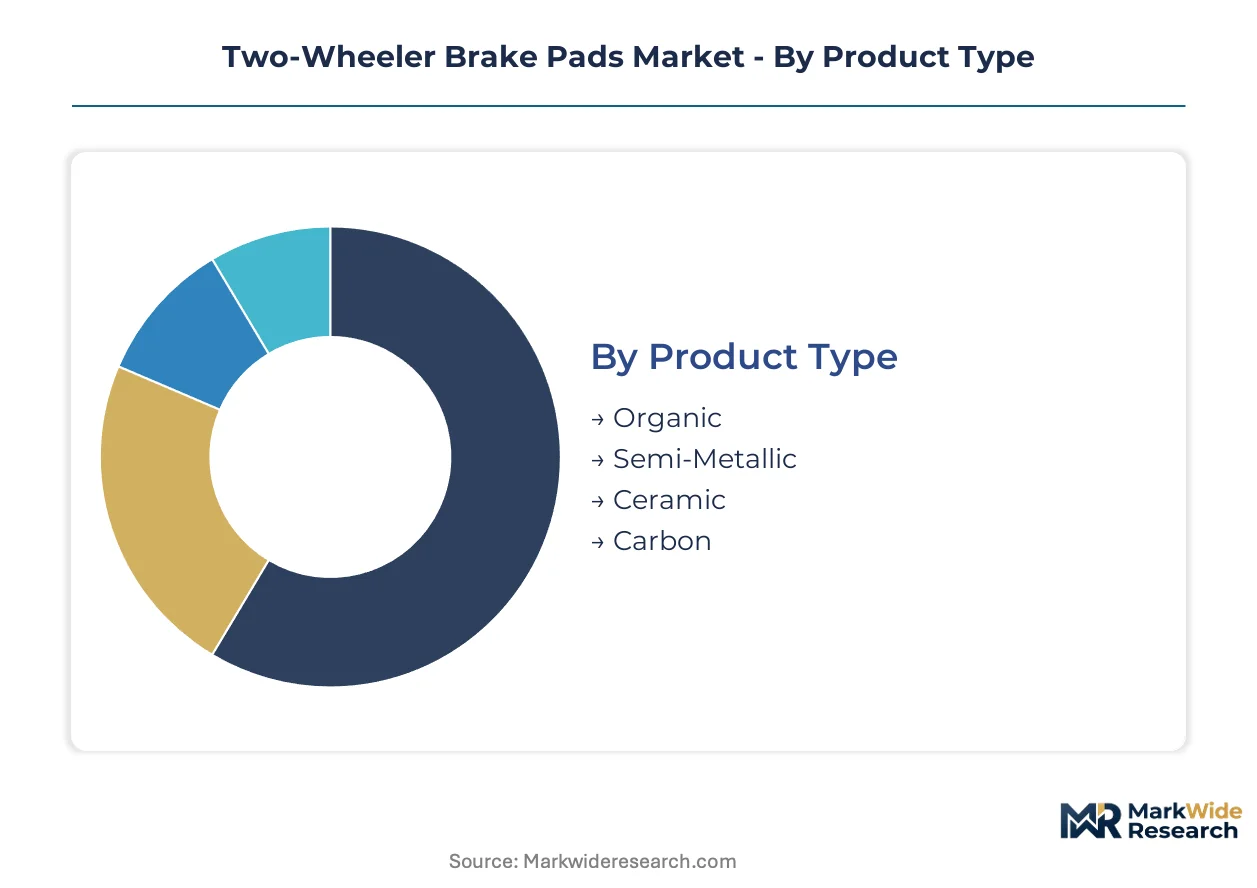
Brake pad segmentation in the two-wheeler market determines which suppliers qualify for specific OEM programs versus aftermarket channels. Material chemistry and thermal specifications create distinct regulatory compliance burdens across each category, directly shaping supplier market access and R&D investment priorities.
Product Type:
Certification requirements vary sharply by formulation: India's BIS mandates apply to all automotive brake linings, while Europe's REACH copper bans specifically target semi-metallic and older organic formulations, exempting compliant ceramics and carbons from reformulation timelines.
- Organic:Non-asbestos organic binders blended with glass, rubber, and Kevlar fibers deliver quiet operation and low rotor wear for urban commuting applications. Demand concentrates in Southeast Asian scooter fleets where cost sensitivity dominates procurement decisions and BIS compliance remains the primary qualification hurdle.
- Semi-Metallic:Steel wool, copper, and brass fibers embedded in phenolic resin matrices provide superior heat dissipation for mid-performance motorcycles. Europe's REACH restrictions on copper content are forcing complete reformulation of legacy semi-metallic pads, disqualifying non-compliant suppliers from EU aftermarket access and compressing margins through extended testing protocols.
- Ceramic:Copper-free ceramic powders bonded with advanced non-metallic matrices achieve thermal stability above 400°C without heavy metal content, satisfying both EPA particulate emissions oversight and European chemical restrictions.
- Carbon:Carbon-carbon composites and carbon-ceramic hybrids deliver extreme fade resistance and weight reduction for superbike and racing applications where performance justifies premium positioning.
Leading the category by volume: Semi-Metallic. Growing fastest: Ceramic.
End User:
Channel economics diverge sharply: OEM fitment demands full homologation and long-term supply contracts, while repair shops and distributors prioritize inventory velocity and same-day availability over certification depth.
- OEMs:Motorcycle manufacturers in India, Indonesia, and Vietnam require suppliers to complete BIS certification, ISO/TS 16949 quality systems, and model-specific durability testing before program award, locking in multi-year supply relationships.
- Aftermarket Retailers:Rider-driven replacement cycles in São Paulo, Bangkok, and Mexico City create sustained demand for pre-certified friction components stocked for immediate availability, with margin pools exceeding OEM fitment through brand premium capture.
- Repair Shops:Independent mechanics in dense urban corridors source brake pads through mobile-enabled B2B platforms that compress traditional distributor layers and accelerate procurement velocity.
- Distributors:Regional wholesalers in Latin American secondary cities and Southeast Asian provincial markets maintain inventory buffers that bridge manufacturer production cycles and repair shop consumption patterns.
OEMs dominate absolute volume. Aftermarket Retailers expand most quickly through digital channel migration.
Application:
Vehicle architecture dictates thermal load profiles and replacement frequency, with motorcycles and off-road bikes demanding sintered metallic tolerance while scooters and e-bikes prioritize low-dust ceramic formulations for urban duty cycles.
- Motorcycles:Internal combustion engines and higher curb weights generate sustained braking energy requiring friction materials rated above 350°C, with premium segments in Italy and Japan adopting ceramic matrix composites for upcoming model year platforms.
- Scooters:Stop-and-go urban duty cycles in Indonesian and Indian dense corridors favor low-metallic and ceramic formulations that minimize brake dust accumulation and extend service intervals.
- E-Bikes:Regenerative braking systems reduce mechanical brake dependency, yet residual friction pad demand concentrates in European and North American markets where e-bike penetration rates climb fastest.
- Off-Road Bikes:Mud, water, and abrasive terrain exposure demands sintered metallic pads with open porosity structures that maintain friction consistency across contaminated surfaces.
Motorcycles anchor category volume. E-Bikes gain share fastest through electrification tailwinds.
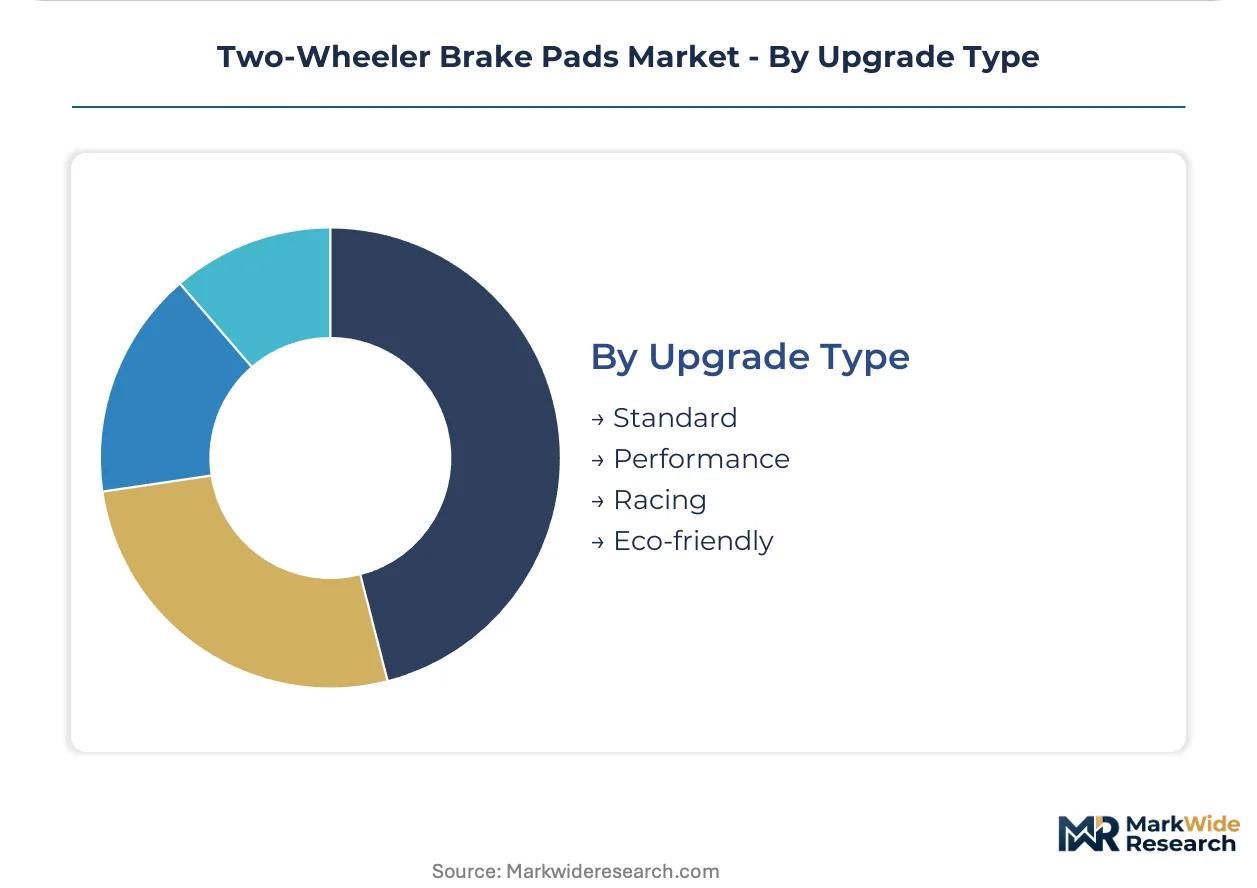
Upgrade Type:
Performance tier selection correlates with rider demographics and regulatory environment, where racing and performance segments bypass copper restrictions through limited-volume exemptions while eco-friendly formulations capture compliance-driven substitution.
- Standard:Baseline friction materials meeting minimum safety certifications dominate fleet replacement in emerging markets where cost minimization overrides performance differentiation.
- Performance:Enhanced thermal capacity and coefficient of friction consistency target enthusiast riders in European and Japanese markets seeking measurable braking improvement without full racing specification.
- Racing:Carbon and advanced ceramic formulations command elevated pricing through weight reduction and fade resistance benefits, with dedicated supply chains operating outside mass-market regulatory timelines.
- Eco-friendly:Copper-free and low-emission formulations align with EPA particulate oversight and European REACH amendments, opening premium positioning for compliant suppliers in regulated jurisdictions.
Standard upgrades lead by volume. Eco-friendly formulations climb fastest on regulatory substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic fiber and ceramic powder supply chains cluster in East Asian production zones, yet demand dispersion across emerging and mature motorcycle markets creates distinct regional competitive dynamics shaped by local fleet composition and regulatory intensity.
India
Motorcycle fleet expansion in Maharashtra and Gujarat generates sustained replacement demand for friction components. BIS certification mandates for automotive brake linings tighten material specifications and consolidate qualified supplier pools. Tamil Nadu's integrated foundry-to-assembly corridors anchor domestic production serving Hero MotoCorp and Bajaj Auto programs.
Indonesia
Dense urban corridors in Jakarta and Surabaya sustain two-wheeler ownership rates exceeding four-wheeler penetration by multiples. The national standardization agency enforces quality benchmarks for brake components that parallel evolving BIS frameworks. Jababeka Industrial Estate hosts friction material bonding operations supplying regional OEM fitment.
Germany
Performance upgrade channels in Bavaria and Baden-Württemberg pull premium ceramic formulations into enthusiast segments. REACH chemical restrictions on copper and heavy metals eliminate legacy semi-metallic formulations from EU market access. KBA homologation protocols extend testing timelines for aftermarket suppliers seeking German distribution.
United States
EPA particulate emissions oversight constrains formulation choices for copper-containing friction materials across California and Texas motorcycle populations. State-level environmental regulations in the Pacific Northwest accelerate inventory turnover toward pre-certified copper-free alternatives. Midwest distributor networks bridge manufacturer production cycles and repair shop consumption patterns.
Brazil
São Paulo's independent repair shops source brake pads through mobile-enabled B2B platforms that compress traditional wholesale layers. ANVISA alignment with international friction material standards shapes import qualification requirements. Minas Gerais industrial zones concentrate steel backing plate production feeding regional assembly operations.
Two-Wheeler Brake Pads Market Vendor Landscape
Global majors compete with regional champions across formulation expertise and distribution density, producing a tiered structure where integrated manufacturers hold cost advantages while specialists capture premium positioning. The vendor base stratifies between captive OEM suppliers, broad-line aftermarket distributors, and performance-focused upgrade specialists. Two dominant competitive moves define current rivalry: backward integration into steel backing plate production, and geographic expansion through jurisdiction-specific homologation investments.
Within the premium performance tier, Brembo S.p.A exemplifies motorsport heritage positioning, while Robert Bosch represents scale-driven aftermarket coverage through dense repair shop networks. Endurance Technologies Limited anchors South Asian supply with integrated manufacturing operations. These three occupy distinct competitive spaces—Italian premium positioning, German distribution breadth, and Indian captive OEM integration—rather than direct confrontation across identical customer segments.
| Leading Market Players |
|---|
| EBC Brakes |
| Nisshinbo Holdings Inc. |
| Brembo S.p.A |
| SBS Friction A/S |
| Akebono Brake Industry |
| Robert Bosch |
| Tenneco Inc. |
| Endurance Technologies Limited |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Ceramic matrix composite adoption for 2027 motorcycle platforms is simultaneously elevating R&D cost thresholds and concentrating qualified supplier pools around East Asian pressing capabilities. This technology transition tightens margin structures for legacy semi-metallic producers while rewarding integrated manufacturers with captive ceramic powder sourcing.
Pricing Analysis
Warranty and service bundling separates OEM supply contracts from aftermarket transactions, with motorcycle manufacturers in India and Indonesia demanding multi-year durability guarantees that inflate upfront pricing. Three-tier pricing structure across premium ceramic, standard semi-metallic, and economy organic levels reflects certification grade and thermal performance specifications. Cost compression in mid-tier segments is intensifying because REACH-driven reformulation extends qualification timelines. Fleet operators in Southeast Asian urban corridors exhibit highest price sensitivity, while racing enthusiasts in Italy and Japan absorb premium positioning for carbon-ceramic formulations.
Supply Chain Analysis
Regional distribution centers in Thailand, Vietnam, and southern China anchor hub-and-spoke patterns serving Southeast Asian repair shop networks. Synthetic fiber and ceramic powder supply chains cluster in East Asian production zones, exposing formulators to single-source vulnerability from concentrated phenolic resin and copper-free ceramic feedstock sources. Distribution runs through mobile-enabled B2B platforms that displace traditional wholesale layers in São Paulo, Bangkok, and Mexico City procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around qualified suppliers capable of navigating multi-jurisdiction homologation, with India's BIS mandates and Europe's REACH amendments disqualifying substandard formulators.
For Market Incumbents: Lock in OEM program continuity through accelerated BIS certification completion and captive steel backing plate production in Tamil Nadu and Maharashtra corridors. Defend against copper-free ceramic specialists by securing long-term supply agreements with Indonesian motorcycle manufacturers ahead of 2027 model year transitions. Prioritize regulatory intelligence functions tracking simultaneous EPA, REACH, and BIS amendment timelines. For New Entrants and Emerging Players: Enter via eco-friendly formulation positioning in European aftermarket channels where REACH compliance creates premium substitution demand. Target German and Benelux performance upgrade segments with pre-certified copper-free ceramics that bypass legacy supplier reformulation delays. Deploy direct-to-rider digital platforms compressing distributor margins in Southeast Asian secondary cities. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to automotive friction conglomerates seeking Southeast Asian manufacturing footprints. Five-to-ten year viability favors integrated foundry-to-assembly operators with established OEM relationships and ceramic pressing capabilities. Monitor BIS certification queue lengths as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Backing Plate Production | Captive foundry operations in Tamil Nadu compress cost structures serving Hero MotoCorp and Bajaj Auto programs. |
| Ceramic Matrix Composite Formulation Investment | Non-asbestos organic binder expertise qualifies suppliers for 2027 Japanese and Italian premium motorcycle platforms. |
| Multi-Jurisdiction Homologation Acceleration | Simultaneous BIS, REACH, and EPA compliance unlocks OEM fitment across Indian, European, and North American markets. |
| Direct-to-Rider Digital Platform Launch | Mobile-enabled B2B procurement in São Paulo and Bangkok displaces traditional wholesale layers and captures margin. |
| Copper-Free Ceramic Alternative Development | Heavy-metal-free formulations satisfy European chemical restrictions and command premium positioning in regulated jurisdictions. |
Methodological Framework
Independent corroboration across friction material R&D directors, OEM procurement managers at Indian and Indonesian motorcycle manufacturers, aftermarket distributors in São Paulo and Bangkok, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with tribology specialists and brake system engineers combined with secondary validation from BIS certification databases, REACH amendment filings, EPA emissions test protocols, and vehicle production registries. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Rate-of-change decomposition across motorcycle fleet expansion, replacement cycle acceleration, and regulatory compliance cost inflation structured the analytical framework. Segmentation dimensions modeled include material formulation chemistry, end-user channel architecture, vehicle application type, and performance upgrade tier throughout the forecast period. CAGRs derived from fitted growth curves applied to base year estimates, with industry-specific inputs incorporating sintered metallic thermal tolerance requirements and ceramic powder supply constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH amendment acceleration or BIS certification timeline extensions. Outputs reflect documented assumptions regarding regulatory enforcement patterns and OEM platform transition schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Saudi Arabia Motorcycle ADAS Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market
Bikes and Motorcycles
Asia-Pacific Motorcycle Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Kids Bicycle Market
Bikes and Motorcycles
Bike Hub Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market