
 Global Hybrid Bicycles Market | 2026-2036
Global Hybrid Bicycles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hybrid Bicycles Market Outlook
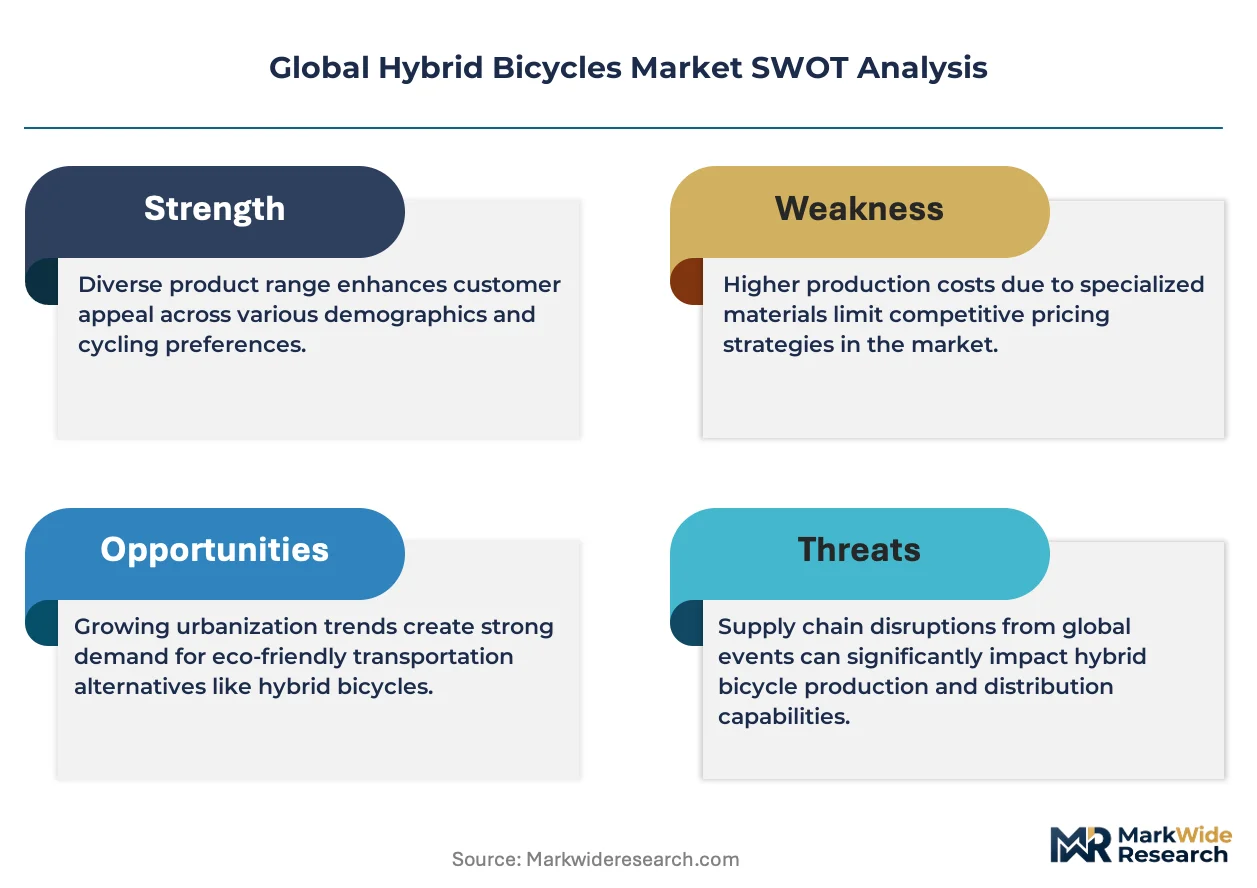
Skilled e-bike motor calibration technicians is rotating from scarce to strategic across European and Asian assembly plants. Trek Bicycle Corporation leverages its vertically integrated frame manufacturing to sustain margin control across premium city hybrid lines. Giant Manufacturing Co. Ltd. anchors volume production through captive carbon fiber forging facilities in Taiwan. Specialized Bicycle Components differentiates via proprietary Future Shock suspension integration on commuter-focused platforms.
Hybrid bicycles combine road-bike geometry with flat handlebars and medium-width tires, typically running 700c wheels with 32-42mm tire clearance for mixed-surface versatility; manufacturers optimize aluminum or carbon frames with relaxed head tube angles to balance efficiency and comfort across paved and light gravel terrain. City Hybrid and Commuter Hybrid categories lead unit volume as employers expand cycle-to-work benefit schemes across OECD markets. Electric technology within the technology segment captures expanding margin pools as mid-drive motor systems displace hub-motor configurations in premium tiers. Fitness Hybrid remains a mature category with replacement-cycle demand rather than net-new rider acquisition.
The EU Green Deal directs member-state cycling infrastructure subsidies, while the F-Gas Regulation governs refrigerants in battery thermal management systems for electric variants. Japan's METI enforces JIS standards for frame fatigue testing that constrain market entry for uncertified Asian producers. China's GB standards for lithium-ion battery safety create additional compliance layers for electric hybrid imports. Stakeholders must monitor subsidy phase-out schedules and battery chemistry certification timelines to calibrate regional inventory and R&D commitments.
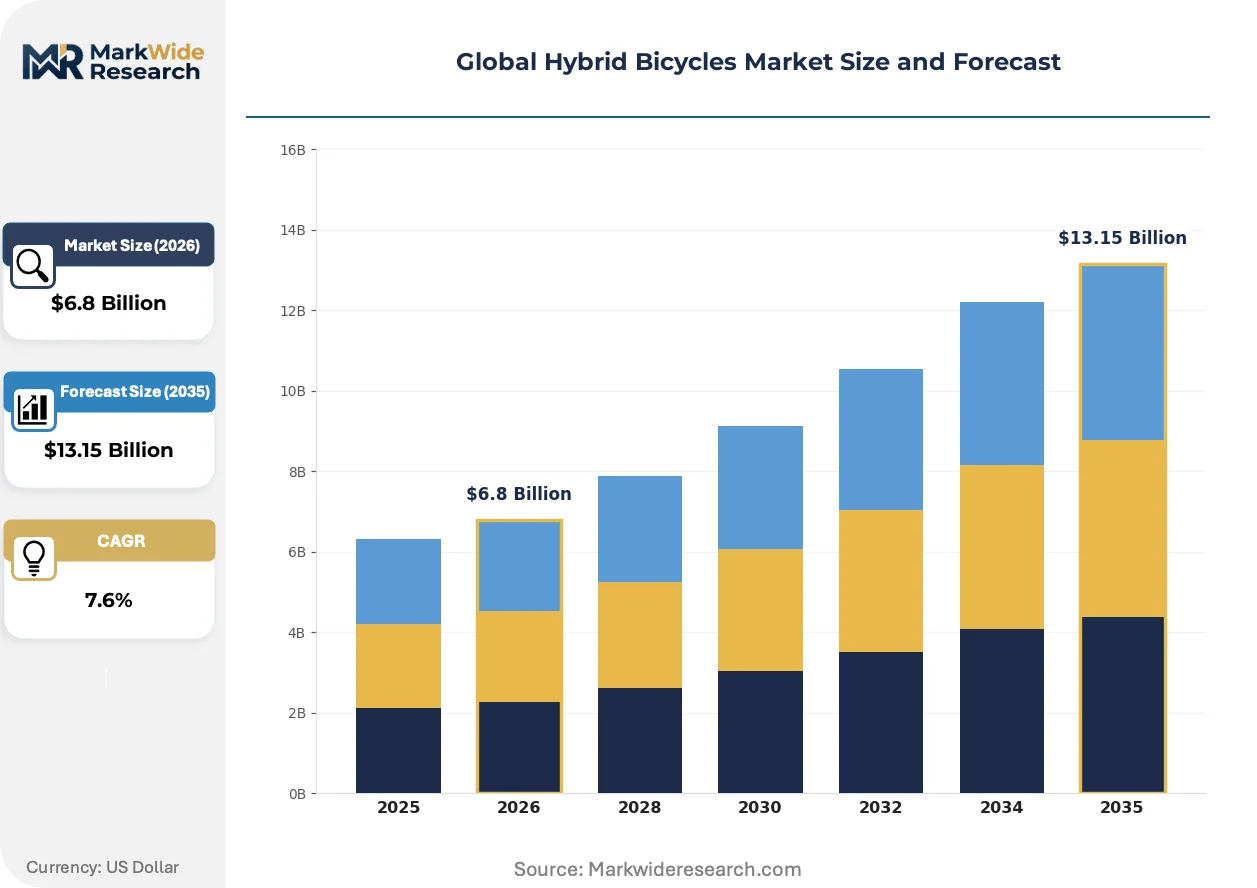
Market Dynamics
Mid-drive motor architecture is displacing hub-motor configurations across premium hybrid tiers, compressing supplier margins while rewarding brands with captive motor calibration expertise and firmware development capabilities.
Growth Catalysts
- EU Green Deal cycling infrastructure subsidies:Member-state funding for protected bike lanes and cycle highways accelerates commuter adoption in Germany, the Netherlands, and Denmark.
- Employer bike-leasing schemes:German cycle-to-work benefit programs create concentrated purchase pull through salary-sacrifice arrangements.
- Lithium-ion battery energy density gains:Improved cell chemistry extends electric hybrid range thresholds, converting skeptical urban commuters.
Market Restraints
- Carbon fiber supply concentration:Taiwan and mainland China host over 80% of global carbon fiber forging capacity for bicycle frames, creating single-source vulnerability.
- Mid-drive motor technical complexity:Torque sensor calibration and firmware integration require specialized technician labor that remains scarce across European assembly plants.
- F-Gas Regulation refrigerant constraints:The EU's phasedown of hydrofluorocarbons complicates battery thermal management system design for electric variants.
Strategic Opportunities
- India's urban micromobility gap:Low bicycle penetration in tier-1 cities offers white space for affordable electric hybrid entry.
- Digital direct-to-consumer channels:Online configurators and virtual fit tools bypass traditional dealer networks, capturing margin and customer data.
- Japan's METI e-mobility incentives:Subsidies for electric bicycle purchases in aging municipalities create targeted demand pockets.
Industry Challenges
- E-bike motor calibration technician scarcity:European and Asian assembly plants compete for skilled labor capable of torque sensor tuning and firmware flashing.
- Multi-standard battery certification complexity:China's GB standards, Japan's JIS requirements, and EU battery passports demand parallel testing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hybrid Bicycles Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain Hybrid, City Hybrid, Commuter Hybrid, Fitness Hybrid End User: Casual Riders, Fitness Enthusiasts, Commuters, Tourists Technology: Electric, Non-Electric, Smart Features, Lightweight Materials Distribution Channel: Online Retail, Brick-and-Mortar, Specialty Shops, Outdoor Retailers |
| Companies Covered | Trek Bicycle Corporation, Giant Manufacturing Co. Ltd., Specialized Bicycle Components, Cannondale Bicycle Corporation, Scott Sports SA, Merida Industry Co. Ltd., Bianchi, Kona Bicycle Company, Raleigh Bicycle Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hybrid Bicycles Market Strategic Shifts
Product architecture is fragmenting along electrification lines, with motor placement and battery integration becoming the primary axis of competitive differentiation rather than frame material or component tier.
Mid-drive motor systems is bifurcating the electric hybrid category into performance-oriented torque-sensor configurations and cost-optimized cadence-sensor alternatives. Premium commuter segments in Germany and the Netherlands adopt torque-sensor units for natural pedaling feel. This technical split is compressing hub-motor suppliers into entry-tier contracts while elevating mid-drive specialists.
REACH substance restrictions and the EU's F-Gas Regulation are forcing material substitutions in battery enclosures and thermal management systems. Manufacturers must reformulate polymer compounds and redesign cooling loops. Electric hybrid variants targeting EU member states face the steepest compliance cost escalations.
Subscription-based mobility packages are displacing outright bicycle ownership among urban professionals in Copenhagen, Amsterdam, and Berlin. Employers bundle fleet access with maintenance and insurance. This shift compresses replacement cycles while transferring residual value risk to fleet operators.
Global Hybrid Bicycles Market Segmentation
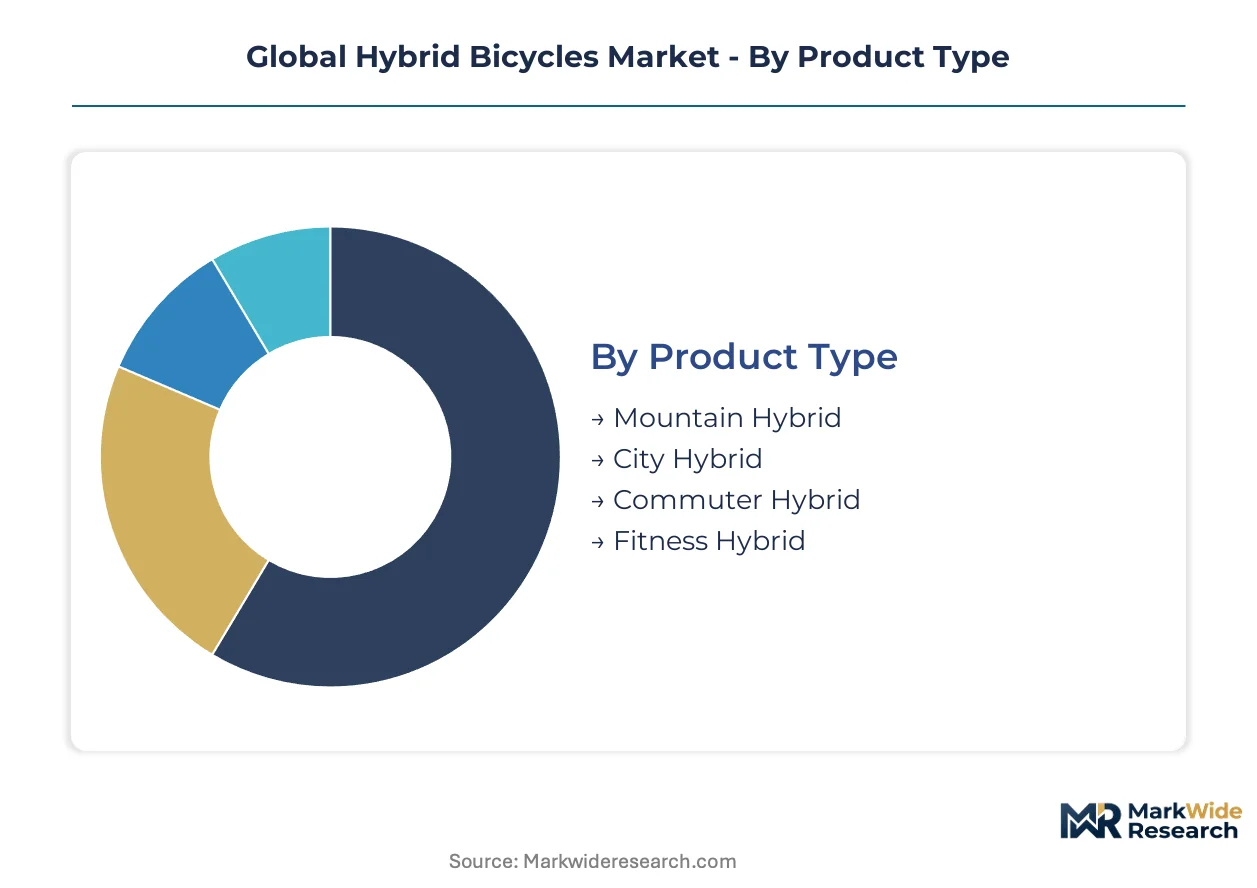
Hybrid bicycle demand fragments across distinct use cases and buyer profiles, with channel strategy determining which segments manufacturers prioritize. Electrification and smart connectivity are reshaping product architecture faster than frame material evolution.
Product Type:
City Hybrid and Commuter Hybrid lines dominate dealer floor space in Germany and the Netherlands, while Mountain Hybrid and Fitness Hybrid serve discrete recreational channels with different margin profiles.
- City Hybrid:Relaxed geometry with 700c wheels and 35-40mm tire clearance optimizes paved urban navigation. German employer bike-leasing schemes concentrate purchase volume in this segment, with salary-sacrifice arrangements converting skeptical car commuters.
- Commuter Hybrid:Integrated rack and fender mounts plus generator hub compatibility define the specification. Dutch cycling infrastructure subsidies and Copenhagen employer fleet programs accelerate replacement cycles for this category.
- Mountain Hybrid:Suspension fork and wider tire clearance accommodate light trail use. Demand concentrates in recreational retail channels across North American and Australian markets.
- Fitness Hybrid:Aggressive geometry mimics road bikes with flat handlebar control. Replacement-driven demand from aging recreational cyclists sustains volume without net-new rider acquisition.
By volume, City Hybrid leads. By growth pace, Commuter Hybrid is expanding most quickly.
End User:
Cost tier alignment separates casual price-sensitive buyers from premium-seeking enthusiasts, with commuter subsidies creating an artificial middle tier in Northern European markets.
- Commuters:Employer benefit programs and municipal infrastructure investment in Germany, Denmark, and the Netherlands convert this segment fastest. Range anxiety and weather protection rank as primary purchase barriers.
- Fitness Enthusiasts:Performance metrics and Strava integration drive specification demands. This segment accepts premium pricing for carbon frames and electronic shifting.
- Casual Riders:Weekend recreational use and neighborhood errand-running define the use case. Price elasticity remains highest in this segment.
- Tourists:Rental fleet demand and destination cycling experiences concentrate volume in Amsterdam, Copenhagen, and Portland rental networks.
Commuters generate the highest per-unit revenue through electrification upsells. Casual Riders constitute the largest addressable population.
Technology:
Margin pools concentrate in electric powertrains and smart connectivity modules, with lightweight materials becoming table stakes rather than differentiators.
- Electric:Mid-drive motor architecture with torque sensor calibration commands premium positioning. EU F-Gas Regulation compliance costs for battery thermal management compress entry-tier margins.
- Smart Features:GPS tracking, theft alerts, and ride-data integration attract urban professionals. Subscription revenue potential draws venture-backed entrants.
- Non-Electric:Mechanical simplicity and lower total cost of ownership sustain demand in price-sensitive Southern European and Southeast Asian markets.
- Lightweight Materials:Aluminum dominates volume production; carbon fiber concentrates in premium tiers with Taiwan and China controlling forging capacity.
Electric variants claim the steepest value growth trajectory. Non-Electric retains the widest geographic penetration.
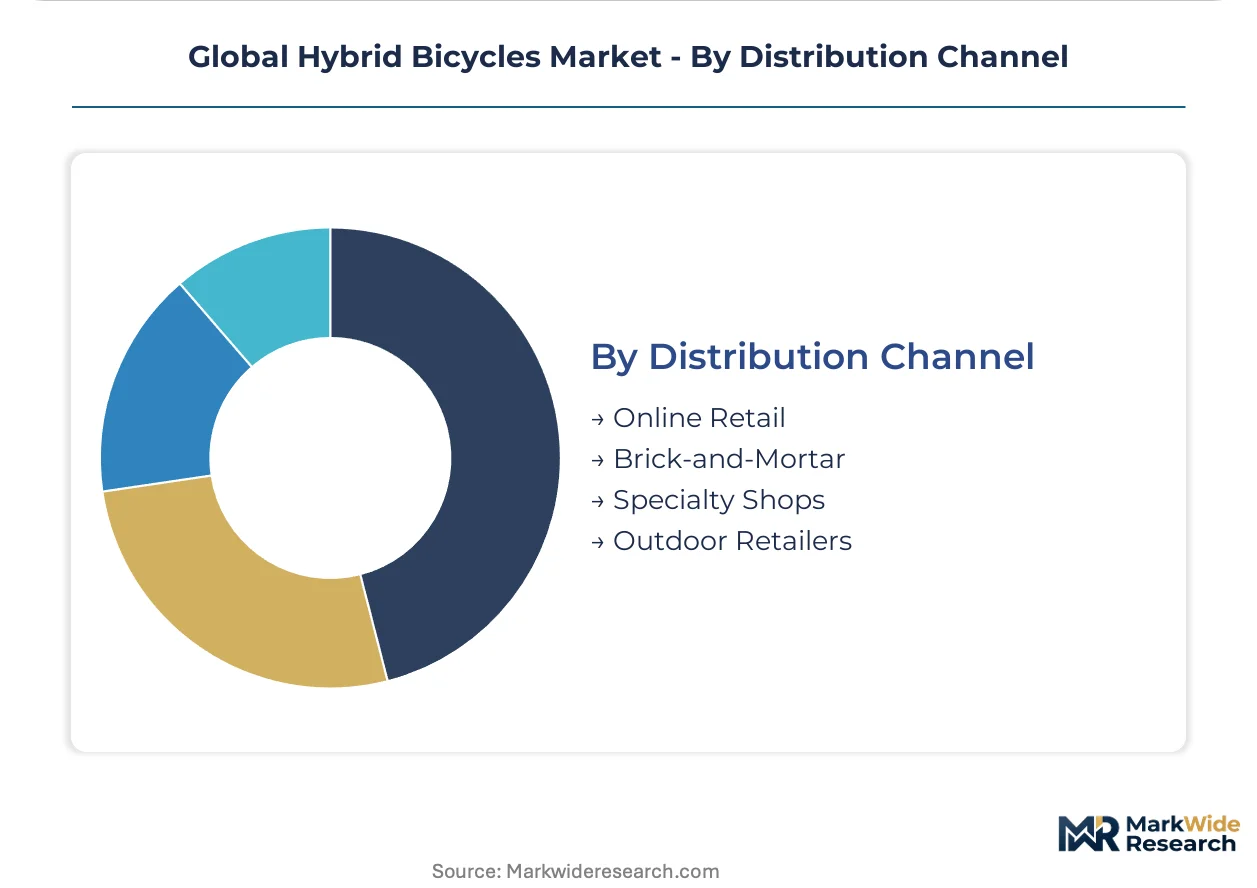
Distribution Channel:
Geographic concentration of cycling culture determines channel viability, with specialty retail commanding service-intensive electric variants and direct channels capturing data-rich customer relationships.
- Specialty Shops:Technical service capability for mid-drive motor calibration and warranty support justifies premium positioning. German and Dutch independent dealers anchor this channel.
- Online Retail:Virtual fit tools and direct-to-consumer configurators bypass dealer markups. Data capture enables subscription service attachment.
- Brick-and-Mortar:Mass-market sporting goods chains serve casual riders with limited technical support. Inventory turns faster but margins compress.
- Outdoor Retailers:Mountain Hybrid and adventure-oriented variants align with camping and hiking customer bases. Seasonal demand patterns create inventory risk.
Specialty Shops command the highest service attach rates. Online Retail is climbing the fastest in customer acquisition efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors demand concentration in Germany, where cycling infrastructure subsidies and employer bike-leasing programs generate the steepest purchase pull. Municipal investment patterns across Northern Europe, East Asia, and North America are fragmenting along subsidy durability and regulatory compliance timelines.
Germany
Employer salary-sacrifice arrangements and KBA-registered fleet programs convert car commuters to electric hybrids at scale. The EU F-Gas Regulation imposes refrigerant phase-down schedules on battery thermal management systems. Stuttgart and Munich anchor manufacturing clusters where mid-drive motor calibration technicians rotate between assembly plants.
Netherlands
Copenhagen-style cycle highways and employer fleet subsidies accelerate Commuter Hybrid replacement cycles. REACH substance restrictions force polymer reformulation in battery enclosures. Amsterdam and Utrecht concentrate subscription-based mobility operators transferring residual value risk from consumers to fleet managers.
United States
Fitness Hybrid replacement demand from aging recreational cyclists sustains non-electric volume without net-new rider acquisition. NHTSA safety standards and state-level e-bike classification laws fragment electric variant eligibility. Portland and Minneapolis anchor municipal bike-share expansions integrating smart-connected fleet management.
Japan
METI e-mobility subsidies target aging municipalities with electric bicycle purchase incentives. JIS frame fatigue testing standards constrain market entry for uncertified Asian producers. Osaka and Nagoya host carbon fiber forging facilities supplying premium-tier frame manufacturers.
China
GB standards for lithium-ion battery safety create compliance layers for electric hybrid exports. MIIT dual carbon goals redirect domestic production toward electrified micromobility. Tianjin and Shenzhen anchor aluminum frame volume production serving cost-optimized global supply chains.
Global Hybrid Bicycles Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive carbon fiber forging and in-house motor calibration capabilities separating margin sustainability from commodity pressure. The vendor base fragments across four strategic archetypes: vertically integrated frame-forging specialists, mid-drive motor system integrators, subscription-based mobility operators, and direct-to-consumer configurators. Consolidation pressure concentrates in electric powertrain sourcing, while geographic expansion and technology licensing dominate competitive moves among second-tier assemblers.
Among Taiwan-based manufacturing specialists, Giant Manufacturing Co. Ltd. and Merida Industry Co. Ltd. occupy positions anchoring volume production through captive forging infrastructure. Trek Bicycle Corporation exemplifies the integrated leader archetype, with backward control over frame manufacturing sustaining margin defense across premium city hybrid lines. Specialized Bicycle Components sits within the technology-differentiation tier, representing brands that compete via proprietary suspension integration and firmware development capabilities rather than scale economies.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Giant Manufacturing Co. Ltd. |
| Specialized Bicycle Components |
| Cannondale Bicycle Corporation |
| Scott Sports SA |
| Merida Industry Co. Ltd. |
| Bianchi |
| Kona Bicycle Company |
| Raleigh Bicycle Company |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation refrigerant phase-down schedules gate battery thermal management system qualification while simultaneously stratifying electric hybrid pricing tiers, forcing manufacturers to absorb compliance costs in entry segments or pass them through in premium torque-sensor configurations.
Pricing Analysis
German employer bike-leasing schemes sustain 40-60% price premiums over Southern European markets for identically specced City Hybrids. Three-tier pricing structure across premium, standard, and economy levels separates torque-sensor mid-drive units from cadence-sensor alternatives from hub-motor entry models. Cost compression in hub-motor tiers is intensifying because Chinese OEMs are flooding European direct-to-consumer channels. Casual Riders in Southeast Asia exhibit highest price elasticity, while German commuters show lowest sensitivity due to salary-sacrifice tax advantages.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for carbon fiber frame shipments from Taiwan. Taiwan, China, and Japan anchor global supply, with carbon fiber forging concentrated in Taichung and Shenzhen while mid-drive motors source from Osaka and Nagoya. Raw material dependencies span lithium-ion cells, rare-earth magnets for motors, and high-modulus carbon fiber pre-preg. Single-source vulnerability concentrates in Taiwanese carbon forging capacity. Distribution runs through German and Dutch specialty dealers for electric variants, with direct-to-consumer channels capturing non-electric volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric scooter and moped sharing networks pose immediate substitution threats to urban hybrid adoption, compelling incumbents to defend commuter use-case lock-in through integrated mobility partnerships.
For Market Incumbents: Fortify mid-drive motor calibration capabilities through technician apprenticeship programs in Stuttgart and Munich manufacturing clusters. Deepen backward integration into battery thermal management system design to offset F-Gas Regulation compliance cost pressure from European climate mandates. For New Entrants and Emerging Players: Differentiate on subscription-based fleet management software for employer bike-leasing schemes in Copenhagen, Amsterdam, and Berlin. India's tier-1 urban micromobility gap offers the most penetrable white space, with affordable torque-sensor electric hybrids addressing range-anxious car commuters. Digital direct-to-consumer configurators bypass entrenched dealer networks while capturing customer data for service attachment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mid-drive motor system integration as firmware development and torque sensor calibration expertise concentrate margin pools. Long-term viability favors acquirers targeting vertically integrated frame-forging specialists with captive carbon fiber capacity. Watch battery chemistry certification timelines across China's GB standards, Japan's JIS requirements, and EU battery passport implementation as the critical inflection signal for regional inventory repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Mid-Drive Motor Calibration Center Establishment | Captive technician training in Stuttgart and Munich addresses scarce labor pools constraining European assembly. |
| Battery Thermal Management System Redesign | F-Gas Regulation compliance enables continued EU market access for electric hybrid variants. |
| Subscription Fleet Platform Launch | Employer benefit scheme integration in Copenhagen and Amsterdam transfers residual value risk from consumers. |
| Direct-to-Consumer Configurator Deployment | Virtual fit tools bypass dealer markups while capturing customer data for service revenue attachment. |
| India Market Entry Partnership | Tier-1 city micromobility gap offers white space for affordable electric hybrid penetration. |
Study Parameters
A standing panel of frame manufacturing plant managers, mid-drive motor system engineers, German employer benefit scheme administrators, and Dutch cycling infrastructure planners provided ongoing calibration across the study. Primary interviews with these stakeholders combined with secondary validation from EU F-Gas Regulation implementation filings, METI e-mobility subsidy disclosures, China MIIT production statistics, and KBA fleet registration databases. Bottom-up unit shipment modeling triangulated against top-down value estimates derived from import customs data and specialty dealer point-of-sale systems.
Consistency checks validated volume and value outputs against external benchmarks including IHS Markit bicycle production databases, European Cyclists' Federation infrastructure investment trackers, and Japan Bicycle Promotion Institute shipment statistics. The analytical framework segmented demand across product type, end user archetype, technology tier, and distribution channel throughout the forecast period. CAGRs were derived from logistic diffusion curves fitted to electric powertrain adoption patterns, with sensitivity testing around battery energy density improvement trajectories and employer subsidy durability assumptions.
Decision-makers should treat outputs as directional under sustained EU Green Deal cycling infrastructure commitment and stable lithium-ion cell cost curves; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation enforcement intensity and China GB battery certification reciprocity agreements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Cruiser Bikes Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
China E-Bike Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Austria E-Bike Market
Bikes and Motorcycles
Motorcycle Suspension System Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
Italy E-Bike Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Bicycle Saddles Market
Bikes and Motorcycles
Global Motorcycle Handlebar Control Switch Market