
 Bike Hub Market | 2026-2036
Bike Hub Market Size, Share, and Industry Trends Forecast 2026-2036
Bike Hub Market Insights
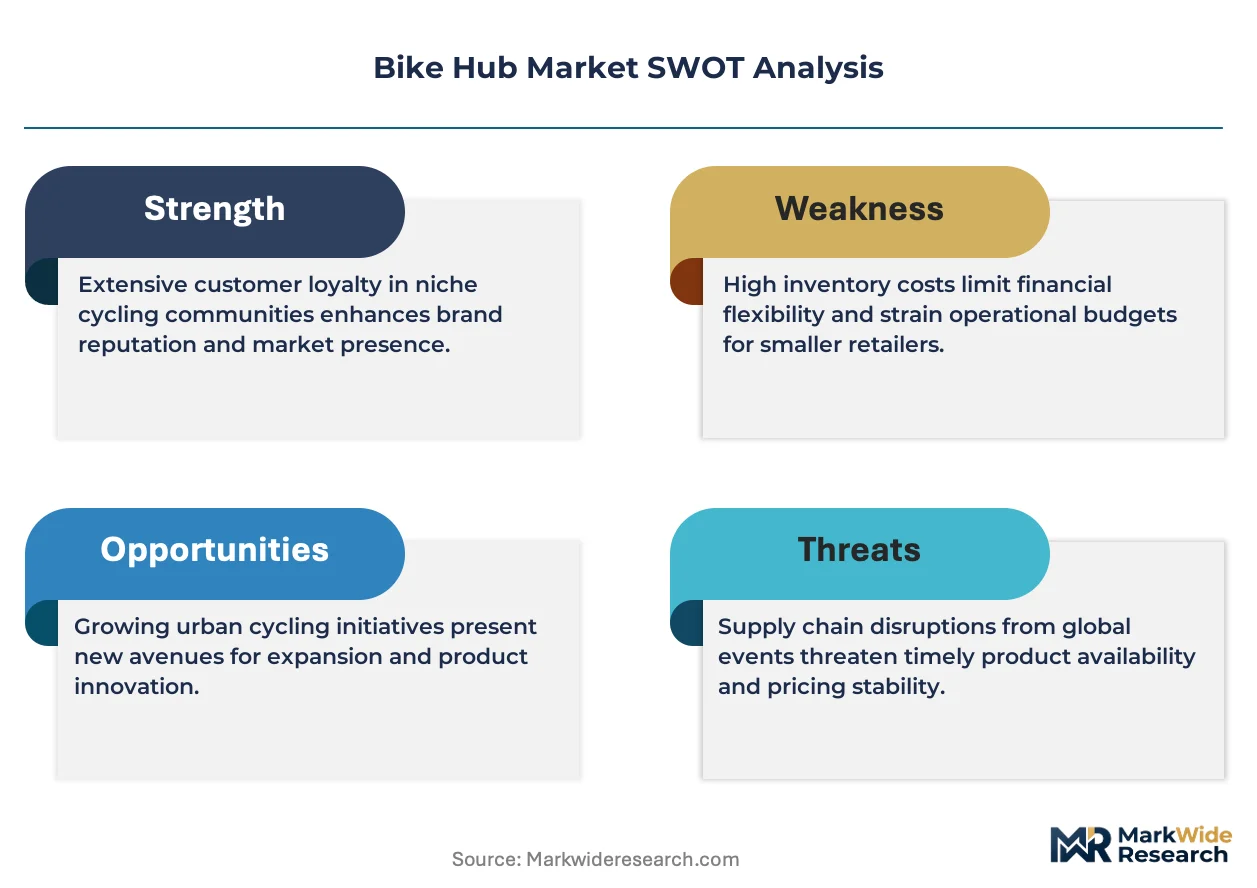
Carbon fiber is expanding its share in premium hub shells as manufacturers chase gram reductions without sacrificing spoke tension integrity. DT Swiss leverages in-house carbon layup expertise to command the ultralight performance tier. Shimano anchors mass-market supply through captive forging facilities in Japan and Malaysia. Hope Tech specializes in small-batch CNC machining for the custom wheelbuild segment in the United Kingdom.
A bike hub is the central component of a bicycle wheel that houses the axle, bearings, and freehub mechanism, typically manufactured from 7075-T6 aluminum billet or forged magnesium alloy with sealed cartridge bearings rated to IP65 ingress protection. Its primary function transmits pedaling torque to the rim while enabling coasting through a ratchet or pawl engagement system. Smart Hubs represent the fastest-growing product type as integrated torque sensors and Bluetooth connectivity expand the addressable base beyond mechanical purists. Aluminum remains the dominant material by volume, though carbon fiber commands disproportionate margin pools in the enthusiast and professional tiers. Aftermarket installation channels compete directly with OEM supply as direct-to-consumer wheel brands erode traditional bike shop service revenue.
The EU Green Deal and REACH substance restrictions shape material choices and end-of-life recycling obligations for European hub manufacturers. The EPA regulates industrial forging emissions in the United States, while China's GB standards mandate fatigue testing protocols for export-grade hubs. Japan's METI promotes lightweight component R&D through targeted manufacturing subsidies. Stakeholders must monitor how evolving e-bike motor integration standards redefine hub flange geometry and bearing load specifications.
Market Dynamics
E-bike motor integration standards are redefining hub flange geometry and bearing load specifications, forcing manufacturers to retool forging dies and recalibrate fatigue testing protocols. This structural shift ripples through material selection, supply chain configuration, and aftermarket service requirements.
Growth Catalysts
- EU Green Deal emission targets:Fleet operators in Germany accelerate e-bike procurement to meet tightening decarbonization mandates, driving hub demand for commercial-grade durability ratings.
- Smart Hub technology convergence:Integrated torque sensors and Bluetooth connectivity expand the addressable base beyond mechanical purists into data-driven training and fleet management applications.
- China GB standards export compliance:Fatigue testing protocols mandated for export-grade hubs elevate quality baselines, reducing warranty claims and opening premium tier access for compliant manufacturers.
Market Restraints
- 7075-T6 aluminum billet price volatility:Aerospace and automotive competition for aerospace-grade aluminum creates input cost instability for precision-machined hub shells.
- Production concentration in China:Hub shell forging and CNC machining capacity clusters in Guangdong and Zhejiang provinces, exposing supply chains to regional logistics disruptions.
- REACH substance restrictions:End-of-life recycling obligations and restricted substance lists complicate coating and anodizing processes for European market access.
Strategic Opportunities
- Aftermarket direct-to-consumer channels:Wheel brands selling complete builds online erode traditional bike shop service revenue, creating white space for hub manufacturers to capture margin through branded replacement programs.
- Carbon fiber layup expertise transfer:Composite manufacturing capabilities from adjacent industries enable gram reduction in premium hub shells without sacrificing spoke tension integrity.
- Japan METI lightweight component subsidies:Targeted R&D funding supports magnesium alloy forging development, accelerating material diversification beyond aluminum dominance.
Industry Challenges
- CNC programming talent scarcity:Small-batch custom wheelbuild segments require skilled machinists capable of tight-tolerance spoke hole drilling, with training pipelines failing to match demand.
- E-bike motor standard fragmentation:Competing axle interfaces and flange spacing specifications force hub manufacturers to maintain excessive SKU variety, compressing production runs.
- IP licensing complexity in ratchet mechanisms:Proprietary engagement system patents create barriers to entry for new entrants seeking to compete in the high-engagement-point performance tier.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bike Hub Market |
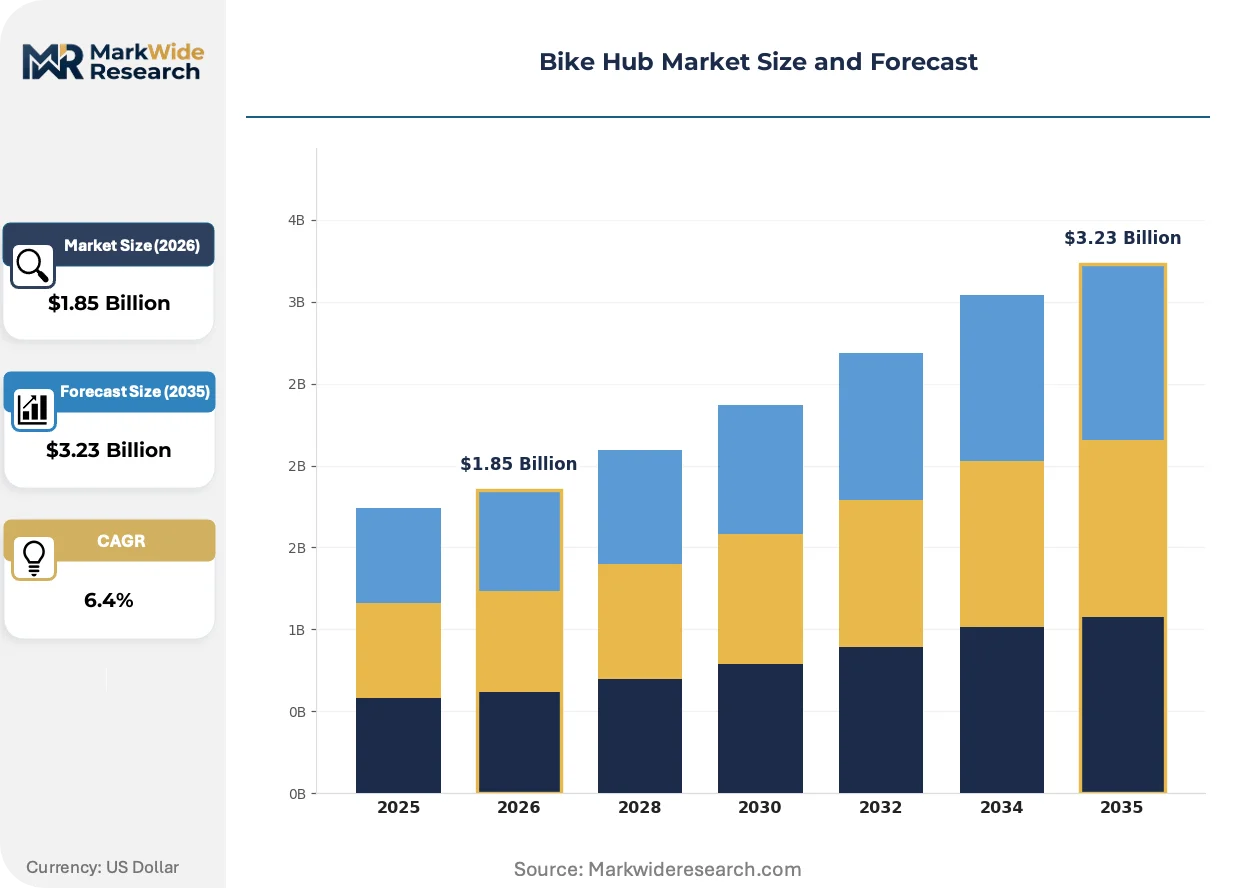
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Hubs, Conventional Hubs, Disc Hubs, V-Brake Hubs End User: Commuters, Enthusiasts, Rental Services, Professionals Material: Aluminum, Steel, Carbon Fiber, Plastic Installation Type: Built-in, Retrofit, Aftermarket, OEM |
| Companies Covered | Chris King, Fulcrum, Shimano, Project321, Novatec, DT Swiss, Hope Tech, Formula, Campagnolo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bike Hub Market Trends and Innovations
Active torque sensing and wireless connectivity are migrating from high-end road cycling into gravel and commuter segments, collapsing the traditional technology tiering that separated professional from enthusiast equipment. Material science advances and regulatory pressure are simultaneously reshaping how hubs are specified, sourced, and serviced.
Smart Hubs with integrated power measurement and smartphone pairing are expanding into mid-tier gravel and commuter wheelsets as riders demand training data previously reserved for dedicated power meters. Component brands are licensing sensor modules rather than developing proprietary electronics, accelerating feature democratization. This convergence is compressing the premium tier's technology exclusivity window and forcing traditional mechanical hub specialists to partner or exit.
REACH substance restrictions and EU Green Deal circular economy mandates are forcing European hub manufacturers to eliminate hexavalent chromium coatings and establish closed-loop aluminum recycling partnerships. The industrial consequence is elevated processing costs for anodizing and surface finishing operations. Manufacturers serving the EU market are responding by consolidating coating operations in certified facilities and redesigning for disassembly to meet extended producer responsibility requirements.
Direct-to-consumer wheel brands are unbundling the traditional bike shop service model by shipping pre-tensioned complete wheelsets with online fitment guides, capturing service revenue that previously flowed to local mechanics. This channel disruption is most visible in North American and Northern European markets where cycling infrastructure investment has expanded the addressable rider base beyond shop-dependent enthusiasts. Hub manufacturers are adapting by developing tool-free bearing replacement systems and video-based maintenance protocols to support remote ownership experiences.
Bike Hub Market Segmentation
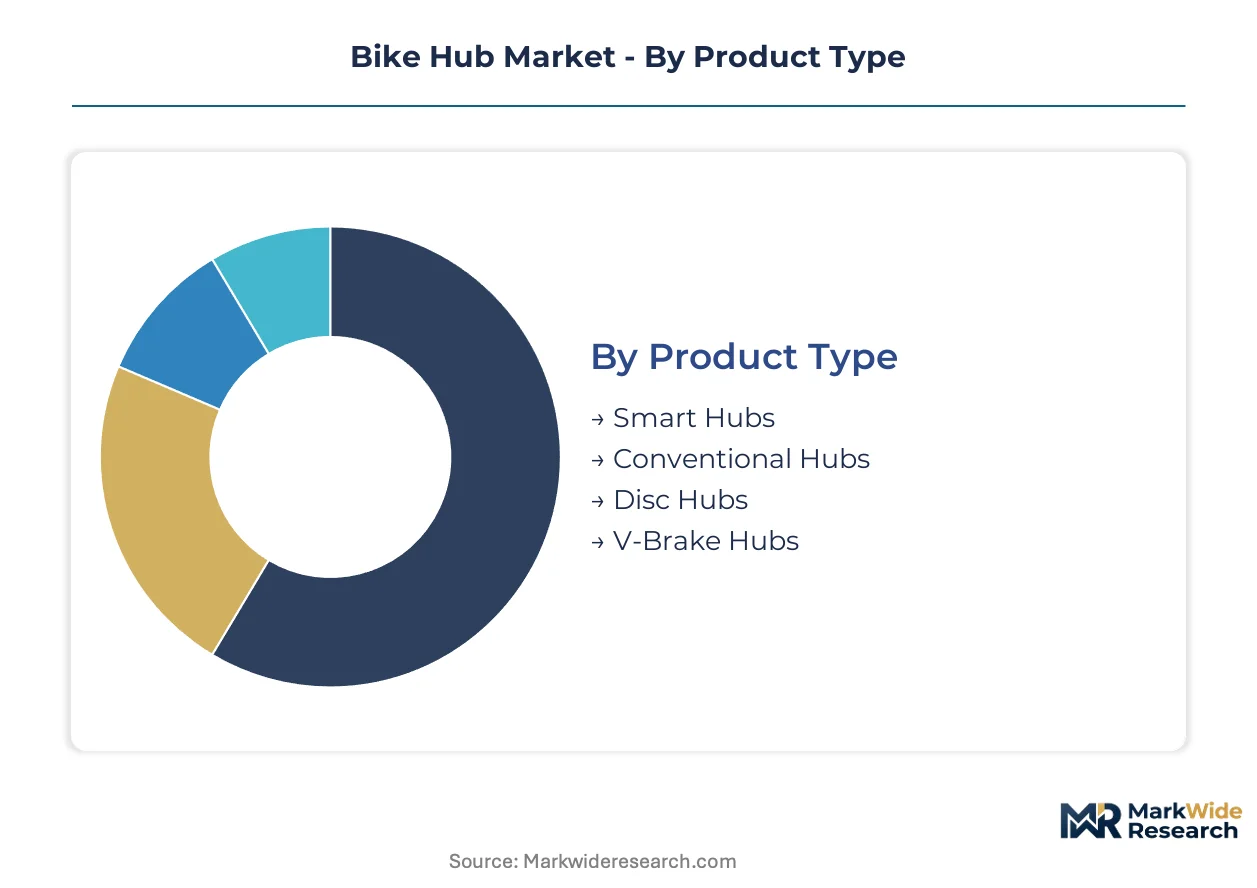
Hub specification diverges sharply across rider use cases and integration requirements. Each segmentation axis reveals distinct procurement patterns, durability expectations, and margin structures that shape manufacturer positioning.
Product Type:
Buyers differentiate primarily by connectivity requirements and braking interface compatibility, not price alone.
- Smart Hubs:Embedded torque sensors and Bluetooth Low Energy modules enable power meter functionality without external sensors. Fleet operators in Germany specify these for e-bike asset tracking and predictive maintenance scheduling under EU Green Deal compliance mandates.
- Conventional Hubs:Mechanical pawl or ratchet engagement systems without electronic integration dominate replacement part demand. Hope Tech and similar specialists in the United Kingdom serve custom wheelbuilders requiring small-batch CNC precision for spoke tension integrity.
- Disc Hubs:Oversized flanges accommodate six-bolt or center-lock rotor mounting with reinforced bearing shells.
- V-Brake Hubs:Narrower flange spacing suits rim-brake road and commuter frames with legacy dropout widths.
Volume sits with Conventional Hubs; growth tilts toward Smart Hubs.
End User:
Service intensity and specification sophistication separate these buyer groups more than unit economics.
- Commuters:Weather-sealed cartridge bearings rated to IP65 ingress protection reduce maintenance frequency for daily riders. Municipal procurement in Copenhagen and Amsterdam specifies sealed units with five-year service intervals.
- Enthusiasts:Engagement point count and freehub sound tuning drive purchase decisions alongside weight reduction targets. DT Swiss commands this tier through in-house carbon layup expertise for gram-critical builds.
- Rental Services:Commercial durability ratings prioritize bearing longevity over rotational mass.
- Professionals:UCI team mechanics demand rapid freehub body interchangeability for multi-discipline race weekends.
Enthusiasts generate the highest margin per unit; Rental Services are expanding most quickly as micromobility fleets scale.
Material:
Processing cost and fatigue performance determine sourcing geography and tier placement.
- Aluminum:7075-T6 billet and forged 6061 variants dominate volume production with excellent strength-to-weight ratios. China's GB standards mandate fatigue testing protocols that elevate quality baselines for export-grade shells from Guangdong and Zhejiang forging clusters.
- Carbon Fiber:Unidirectional layups around aluminum spoke beds achieve gram reductions without sacrificing flange stiffness. Premium tier positioning depends on in-house composite expertise transfer from adjacent motorsport and aerospace industries.
- Steel:Chromoly variants persist in cargo bike and tandem applications requiring ultimate load capacity.
- Plastic:Glass-reinforced nylon hubs serve children's bicycle price points with molded bearing seats.
Aluminum commands unit volume; Carbon Fiber gains share fastest in the enthusiast and professional tiers.
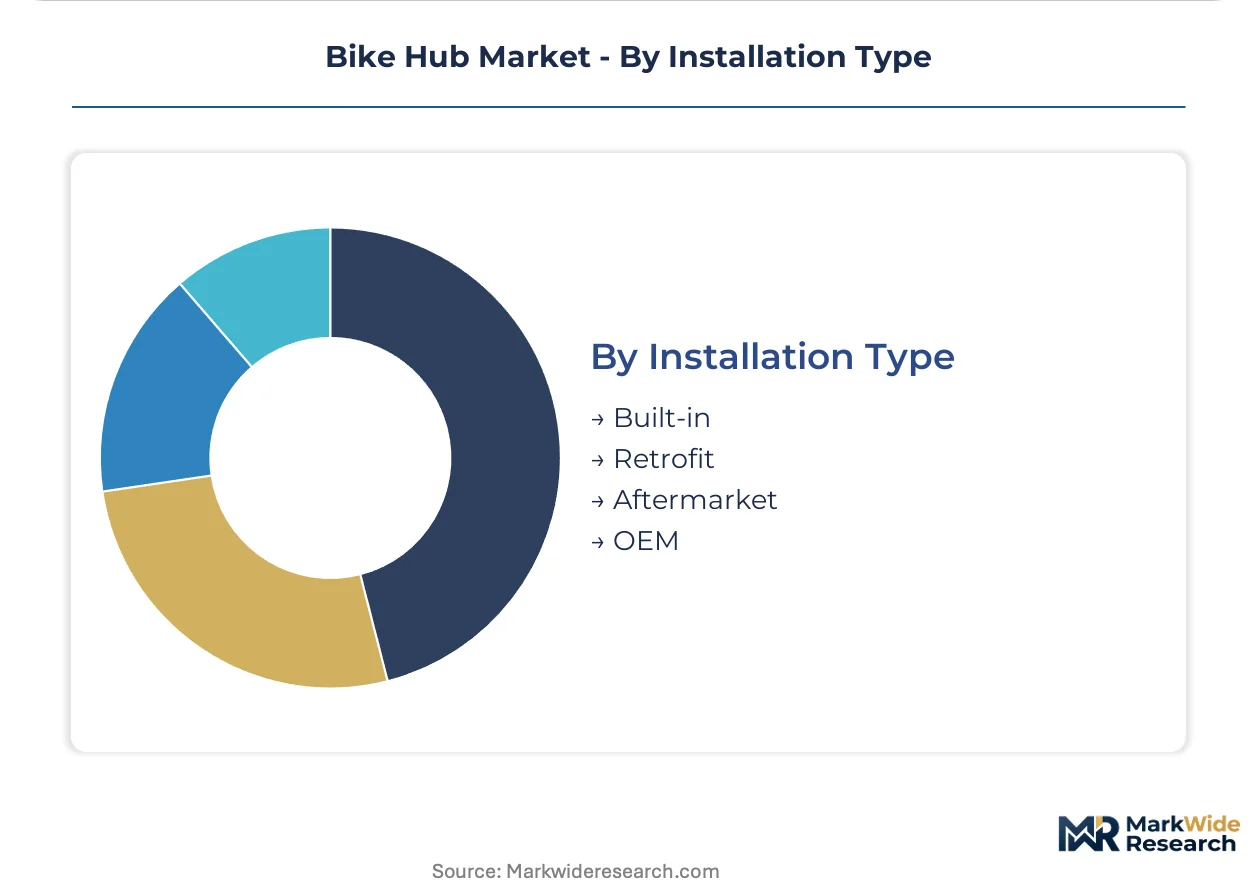
Installation Type:
Channel control and service revenue allocation define competitive dynamics in this category.
- Aftermarket:Direct-to-consumer wheel brands ship pre-tensioned complete builds with video-based maintenance protocols, capturing service revenue previously flowing to local mechanics. Tool-free bearing replacement systems support remote ownership experiences.
- OEM:Captive supply agreements with frame manufacturers require volume commitments and standardized axle interfaces. Shimano leverages forging facilities in Japan and Malaysia to anchor mass-market supply through long-term contracts.
- Built-in:Motor-integrated hub designs for e-bikes require proprietary flange geometry matching specific drive units.
- Retrofit:Axle adapter kits enable older frame compatibility with modern thru-axle standards.
OEM locks in volume commitments; Aftermarket channels are climbing the fastest as direct-to-consumer brands erode traditional bike shop service revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany where fleet operators scale e-bike procurement to meet EU Green Deal emission targets, while production gravity rests in China's Guangdong and Zhejiang forging clusters.
Germany
Fleet operators in Berlin and Hamburg accelerate e-bike procurement to meet tightening EU Green Deal decarbonization mandates. The KBA regulates commercial vehicle safety standards that extend to fleet-grade hub durability ratings. Manufacturing concentrates in Baden-Württemberg where precision machining suppliers serve the custom wheelbuild segment.
China
Export-grade hub production dominates global volume as GB standards mandate fatigue testing protocols for international market access. The MIIT oversees industrial forging emissions and lightweight component R&D subsidies. Guangdong and Zhejiang provinces host concentrated CNC machining capacity for 7075-T6 aluminum billet processing.
United States
Direct-to-consumer wheel brands in California and Colorado capture service revenue through pre-tensioned complete builds and video-based maintenance protocols. The EPA regulates industrial forging emissions from captive production facilities. The Pacific Northwest anchors enthusiast demand for gram-critical carbon fiber hub configurations.
Japan
METI promotes lightweight component R&D through targeted manufacturing subsidies supporting magnesium alloy forging development. JIS standards define bearing load specifications for domestic and export markets. The Chubu region around Nagoya maintains captive forging facilities for mass-market supply anchoring.
United Kingdom
Custom wheelbuilders in Manchester and Bristol drive small-batch CNC precision demand for spoke tension integrity. REACH substance restrictions complicate coating and anodizing processes for EU market access. The West Midlands cluster specializes in ratchet mechanism prototyping for the performance tier.
Bike Hub Market Competitive Landscape
Technology licensing dominates the current landscape as component brands partner for sensor module integration rather than developing proprietary electronics. The vendor base organizes around three strategic archetypes: mass-market forging specialists with captive facilities, precision CNC machinists serving custom segments, and composite material innovators transferring expertise from adjacent industries. M&A activity targets sensor technology capabilities, while geographic expansion focuses on EU-compliant coating and recycling infrastructure.
Among premium-tier specialists, Chris King and DT Swiss exemplify the precision-forging archetype with in-house material expertise, while Hope Tech represents the small-batch CNC machining segment serving custom wheelbuilders. These three companies anchor distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Chris King |
| Fulcrum |
| Shimano |
| Project321 |
| Novatec |
| DT Swiss |
| Hope Tech |
| Formula |
| Campagnolo |
| Others |
Pricing and Supply Chain Analysis
Performance tier bifurcation between carbon fiber enthusiast hubs and commodity aluminum units manifests in divergent margin structures and sourcing geographies. Premium positioning draws from in-house composite expertise and small-batch CNC capacity, while volume production anchors in captive forging facilities serving OEM contracts.
Pricing Analysis
Volume-mass split separates aluminum commodity hubs from carbon fiber premium tiers. Three-tier pricing structure across premium, standard, and economy levels tracks material grade and bearing specification, with IP65 sealing and engagement point count as key differentiation drivers. Cost compression in standard aluminum tiers intensifies because aerospace-grade 7075-T6 billet competes with automotive and aviation procurement. Fleet operators in Germany exhibit lowest price sensitivity due to EU Green Deal compliance mandates; children's bicycle OEMs face acute margin pressure.
Supply Chain Analysis
7075-T6 aluminum billet supply rests on Chinese smelter capacity and Malaysian forging operations, with Japanese magnesium alloy development emerging as an alternative feedstock. Precision-machined hub shells draw from Guangdong and Zhejiang CNC clusters, while carbon fiber layup expertise sources from adjacent motorsport and aerospace industries. Single-source vulnerability concentrates in Chinese forging die production and coating chemical supply. Distribution runs through direct-to-consumer wheel brands and traditional bike shop channels, with aftermarket service revenue shifting toward remote ownership models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into sensor module capabilities and captive forging capacity defines competitive positioning as e-bike motor standards fragment and smart hub demand accelerates.
For Market Incumbents: Hedge against SKU proliferation by consolidating axle interface families and securing long-term billet offtake agreements with Guangdong forging clusters. Carbon fiber expertise acquisition from adjacent industries defends margin position against composite specialists entering from motorsport supply chains. REACH compliance investment in closed-loop anodizing partnerships protects EU market access as substance restrictions tighten. For New Entrants and Emerging Players: Enter via aftermarket direct-to-consumer channels where traditional bike shop service revenue erosion creates white space for branded replacement programs. Small-batch CNC machining for custom wheelbuilders in the United Kingdom offers the most penetrable segment given Hope Tech's capacity constraints and DT Swiss's premium tier focus. Tool-free bearing replacement systems paired with video-based maintenance protocols enable remote ownership support without physical service infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with sensor technology specialists given smart hub convergence and fleet management data monetization catalysts. Long-term viability favors manufacturers with dual aluminum-carbon material capabilities and EU-compliant coating infrastructure. Watch e-bike motor standard consolidation as the inflection indicator for hub flange geometry stability and SKU rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Captive 7075-T6 billet processing insulates margin against aerospace competition and Guangdong logistics disruptions. |
| Sensor Module Licensing Partnership | Bluetooth Low Energy integration accelerates smart hub feature democratization without proprietary electronics development. |
| EU-Compliant Coating Facility Certification | REACH-conforming anodizing operations secure market access as hexavalent chromium restrictions expand. |
| Direct-to-Consumer Wheel Brand Launch | Pre-tensioned complete builds capture service revenue from eroding bike shop channels in North America. |
| Magnesium Alloy R&D Collaboration | METI-subsidized lightweight component development diversifies material dependence beyond aluminum dominance. |
Research Methodology
Multi-period observation of hub specification trends, e-bike fleet procurement patterns, and forging capacity utilization anchored the trend analysis, supplemented by interviews with component brand product managers, custom wheelbuilders, OEM procurement leads, and fleet operations directors. Secondary validation drew from MIIT industrial policy filings, EPA forging emission disclosures, KBA commercial vehicle safety standards, and EU Green Deal implementation progress reports. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Segment-weighting across product type, material grade, installation channel, and end-user archetype informed value distribution estimates throughout the forecast period. CAGRs were derived from trend extrapolation moderated by regulatory inflection points and technology adoption curves. E-bike motor standard fragmentation and smart hub sensor cost curves served as industry-specific forecast inputs alongside aluminum billet price volatility assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under supply chain disruption scenarios and accelerated EU circular economy mandate implementation. E-bike subsidy policy shifts, REACH substance list expansion, and GB standards fatigue testing protocol revisions warrant ongoing watch as forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
China E-Bike Market
Bikes and Motorcycles
Global Motorcycle Supercharger Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
Child Bike Seats Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
Motorcycles Fuel Tank Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market