
 ASEAN E-Bike Market | 2026-2036
ASEAN E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN E-Bike Market Outlook
Pay-as-you-ride leasing and battery-swapping subscriptions is reconfiguring capital requirements for new entrants across Southeast Asia. Yadea Technology Group Co. Ltd leverages its integrated motor and controller manufacturing to protect margins in price-sensitive Indonesian cities. Giant Manufacturing Co. Ltd anchors premium positioning through dealer networks in Bangkok and Ho Chi Minh City. VinFast competes with vertically integrated battery cell production at its Haiphong complex.
An ASEAN e-bike combines a pedal-assisted bicycle frame with an electric drivetrain typically rated between 250W and 750W, powered by a rechargeable battery pack mounted on the downtube or rear rack, designed for urban mobility and commercial logistics across tropical climates with high humidity tolerance. City E-Bikes dominate unit volume in Jakarta, Manila, and Hanoi where short-distance commuting defines the core use case, while Cargo E-Bikes capture expanding margin pools as Grab, Gojek, and ShopeeXpress operators electrify parcel and food delivery fleets. Lithium-ion battery configurations now lead technology positioning as lead-acid replacements accelerate in Vietnam and Indonesia due to weight and cycle-life advantages.
Thailand's Board of Investment EV incentives, Indonesia's Ministry of Industry local content requirements, and Vietnam's Ministry of Transport helmet and registration standards collectively shape product homologation and market access timelines across the region. Cambodia, Laos, and Myanmar present regulatory ambiguity that constrains formal channel development but creates informal import corridors through Thai and Vietnamese border traders. Stakeholders must monitor which ASEAN member state next harmonizes its motor power limits and road-use classifications with either the EU L1e-A framework or China's GB standards, as that alignment will determine which supply chain configurations achieve cross-border scale.
Market Dynamics
Last-mile delivery electrification is compressing replacement cycles across Southeast Asian urban corridors, as fleet operators in Jakarta, Bangkok, and Ho Chi Minh City phase out two-stroke motorcycles faster than retail consumers upgrade personal vehicles.
Growth Catalysts
- Thailand Board of Investment EV incentives:Tax holidays and import duty exemptions for battery and motor manufacturing are pulling assembly capacity into the Eastern Economic Corridor.
- Urban congestion penalties:Jakarta's odd-even license plate restrictions and Bangkok's congestion charging zones are elevating e-bike operating cost advantages over internal combustion alternatives.
- Lithium-ion chemistry maturation:Cell energy density improvements and pack cost declines are accelerating lead-acid replacement in Vietnam and Indonesia.
Market Restraints
- Import tariff volatility:Indonesia's Ministry of Industry local content requirements create homologation delays for non-ASEAN sourced battery management systems and motor controllers.
- Charging infrastructure gaps:Residential electricity access limitations in Philippine informal settlements and Indonesian peri-urban kampungs constrain overnight charging for personal ownership models.
- Technical workforce scarcity:Certified lithium-ion battery technicians and power electronics repair specialists remain concentrated in Bangkok and Ho Chi Minh City.
Strategic Opportunities
- Cambodia, Laos, and Myanmar informal corridors:Regulatory ambiguity in these frontier markets creates first-mover positioning through Thai and Vietnamese border trader networks before formal channel establishment.
- Battery-swapping subscription models:Pay-as-you-ride leasing is reconfiguring capital requirements for delivery fleet operators in Indonesian cities.
- EU L1e-A framework alignment:The first ASEAN member state to harmonize motor power limits and road-use classifications with this standard will unlock cross-border supply chain scale for exporters.
Industry Challenges
- Vietnam Ministry of Transport helmet and registration compliance:Homologation timelines for new powertrain configurations create launch delays and inventory risk for manufacturers.
- Cross-border battery logistics:UN 38.3 lithium-ion shipping certification and thermal runaway containment requirements add freight cost and documentation complexity for regional distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN E-Bike Market |
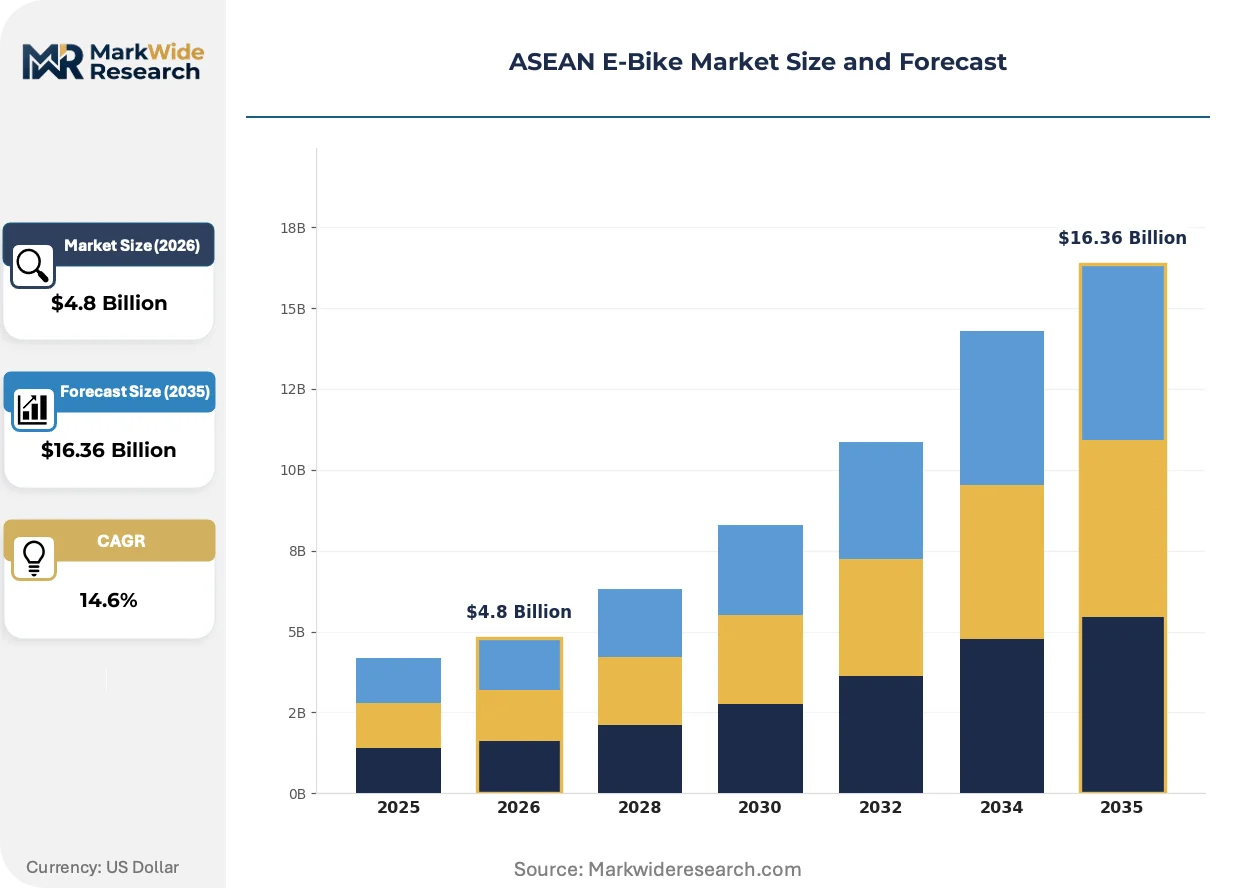
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Folding E-Bikes, Mountain E-Bikes, Cargo E-Bikes Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Lithium Polymer End User: Commuters, Delivery Services, Leisure Riders, Tourists Distribution Channel: Online Retail, Direct Sales, Dealers, Supermarkets |
| Companies Covered | Yadea Technology Group Co. Ltd, Giant Manufacturing Co. Ltd, Yamaha Motor Co. Ltd, Trek Bicycle Corporation, Merida Industry Co. Ltd, Accell Group N.V, AIMA Technology Group Co. Ltd, VinFast, Polygon Bikes, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN E-Bike Market Strategic Shifts
Digital platform integration is rewiring how fleet operators acquire, maintain, and retire electric two-wheelers across Southeast Asian logistics networks.
Telematics-enabled predictive maintenance is virtualizing traditional dealer service relationships. Grab, Gojek, and ShopeeXpress delivery operators in Jakarta and Bangkok now receive battery health alerts and motor diagnostics through smartphone applications rather than physical inspection intervals. This compression of maintenance cycles is reducing unplanned downtime while shifting service revenue from parts replacement to software subscriptions.
Thailand's Board of Investment EV incentive structure is accelerating localized motor and controller production. Manufacturers establishing assembly in the Eastern Economic Corridor receive eight-year corporate income tax exemptions and machinery import duty relief. Vietnamese and Indonesian competitors are responding by lobbying their respective Ministries of Industry for equivalent production-linked incentive schemes.
Subscription-based asset-light procurement is displacing outright purchase among urban delivery fleets. Operators in Ho Chi Minh City and Manila now prefer per-kilometer battery-swapping contracts that bundle vehicle, energy, and maintenance into single operational expenditures. This shift transfers residual value risk to lessors while locking fleet customers into multi-year platform relationships.
ASEAN E-Bike Market Segmentation
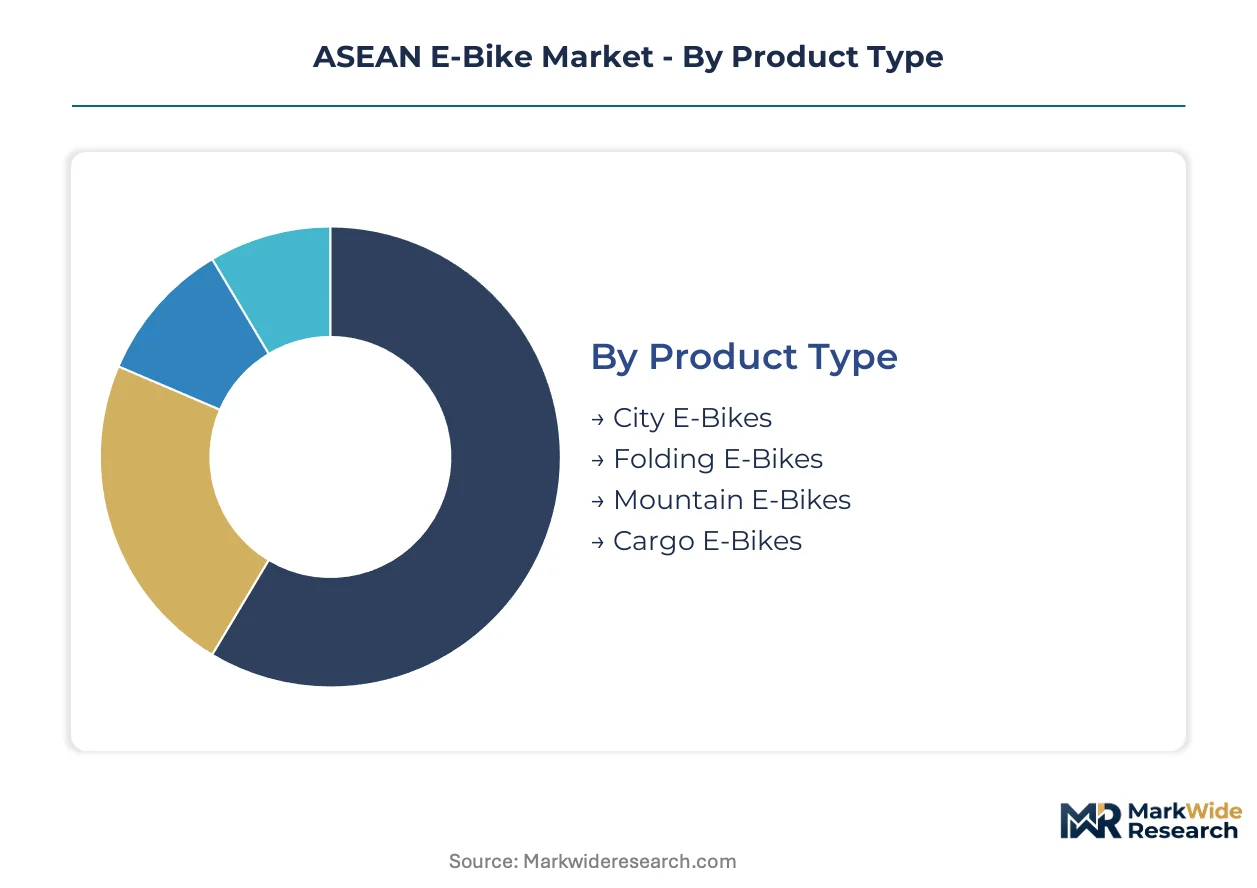
ASEAN e-bike procurement patterns diverge sharply between fleet operators seeking standardized utility and individual buyers prioritizing versatility. Segment-level profitability varies threefold depending on battery chemistry, channel configuration, and service attach rates. Understanding these fault lines enables targeted positioning across Jakarta's delivery corridors and Bangkok's retail showrooms.
Product Type:
Replacement cycles stretch from eighteen months for commercial cargo units to seven years for leisure-oriented mountain frames. Fleet operators in Ho Chi Minh City and Manila drive the fastest inventory turnover, while personal ownership models in Hanoi and Bangkok extend depreciation schedules.
- City E-Bikes:Step-through frames with 250W hub motors and integrated lighting dominate Jakarta, Manila, and Hanoi commuting corridors. Grab and Gojek fleet procurement concentrates demand in the 36V/10Ah configuration band, with battery-swapping compatibility now a mandatory specification for new tenders.
- Cargo E-Bikes:Extended wheelbase frames with 500W+ mid-drive motors and reinforced rear racks carry 150kg payloads across ShopeeXpress and Lazada last-mile networks. Thai assembly plants in the Eastern Economic Corridor now prioritize this segment for export qualification under Board of Investment incentive rules.
- Folding E-Bikes:Collapsible 20-inch wheel formats with quick-release battery packs serve multi-modal commuters in Singapore and Kuala Lumpur rail corridors.
- Mountain E-Bikes:Full-suspension 750W systems with hydraulic disc brakes target leisure riders in northern Thai hill stations and Vietnamese highland tourism zones.
City E-Bikes anchors the volume base while Cargo E-Bikes gains share at the steepest rate.
Battery Type:
Cost tiers separate segments by three-to-one capital intensity ratios, from lead-acid entry points to lithium-polymer premium positioning. Chemistry selection directly determines vehicle weight, thermal tolerance in tropical humidity, and residual financing value.
- Lithium-ion:NMC and LFP cell formats now power 70% of new ASEAN registrations, with 48V/20Ah packs becoming the fleet standard. Vietnamese manufacturers leverage Haiphong cell production to undercut imported alternatives on total cost of ownership calculations.
- Lead-acid:Remaining Indonesian and Philippine informal market share depends on 12V/20Ah sealed units for sub-$400 retail price points, though cycle life limitations drive rapid replacement demand.
- Nickel-metal Hydride:Legacy chemistry persists in refurbished Japanese import channels through Cambodian and Laotian border traders.
- Lithium Polymer:Pouch cell configurations enable frame-integrated battery designs for premium folding and mountain categories in Bangkok and Singapore.
Lithium-ion commands the installed base while Lithium Polymer climbs fastest in unit value terms.
End User:
Application requirements split the market between route-optimization software integration for logistics operators and aesthetic customization for individual purchasers. Usage intensity varies tenfold between daily commercial mileage and weekend recreational patterns.
- Delivery Services:Grab, Gojek, ShopeeXpress, and Lazada operators in Jakarta, Bangkok, and Ho Chi Minh City specify telematics-ready controllers and swappable battery architectures. Subscription procurement models now outnumber outright purchases in this segment.
- Commuters:Office workers in Manila, Kuala Lumpur, and Hanoi prioritize 25km range adequacy with theft-resistant locking systems and smartphone mount integration.
- Leisure Riders:Weekend cyclists in Thai resort towns and Vietnamese coastal provinces seek pedal-assist modes for extended trail access without full motor dependency.
- Tourists:Rental fleet operators in Bali, Phuket, and Siem Reap favor standardized 250W city formats with simplified controls and multilingual interface options.
Delivery Services generates the highest throughput velocity while Commuters delivers the broadest geographic coverage.
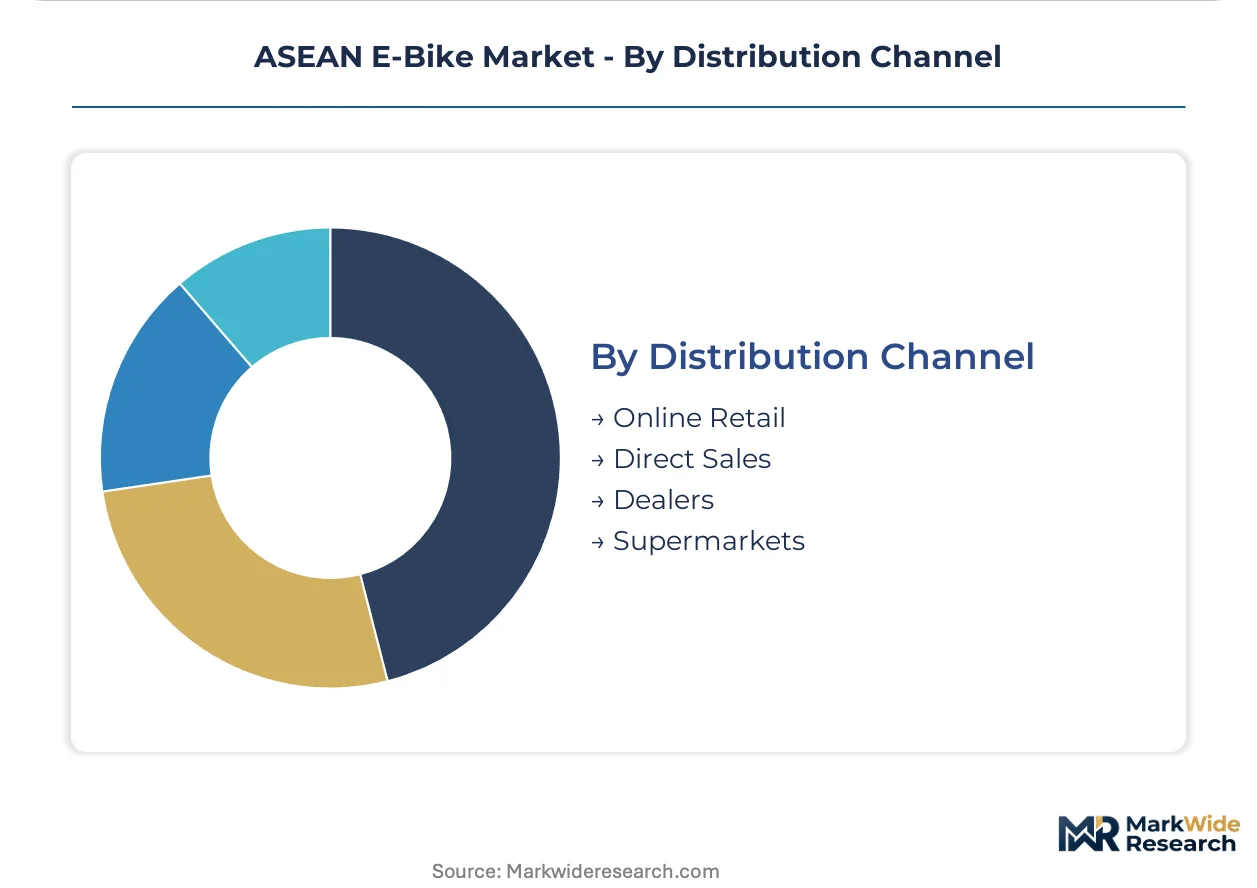
Distribution Channel:
Customer type determines channel profitability, with fleet direct sales yielding service attach rates five times higher than supermarket transactions. Channel selection constrains warranty fulfillment speed and spare parts availability.
- Direct Sales:VinFast and Yadea field teams negotiate enterprise contracts with Grab and Gojek regional subsidiaries, bundling vehicle supply with predictive maintenance software and battery-swapping network access.
- Dealers:Giant Manufacturing and regional distributors maintain service-capable showrooms in Bangkok, Ho Chi Minh City, and Jakarta, capturing premium positioning through test-ride experiences and financing arrangements.
- Online Retail:Shopee and Lazada marketplace listings dominate Indonesian and Philippine consumer entry points, with cash-on-delivery terms overcoming credit access barriers.
- Supermarkets:Big C and Lotus's hypermarkets in Thailand and Vietnam stock entry-level lead-acid models for impulse purchases with minimal service support.
Dealers retain the margin leadership position while Direct Sales expands most quickly in absolute unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Board of Investment EV incentives are redrawing manufacturing geography across Southeast Asia, pulling assembly capacity into the Eastern Economic Corridor while neighboring states craft competitive policy responses.
Thailand
Fleet electrification mandates from Bangkok's congestion charging zones and Grab's procurement specifications drive commercial demand. The Board of Investment grants eight-year corporate income tax exemptions for battery and motor manufacturing. The Eastern Economic Corridor hosts expanding assembly plants serving export markets and domestic last-mile operators.
Indonesia
Jakarta's odd-even license plate restrictions and Gojek's fleet conversion programs accelerate two-stroke replacement. The Ministry of Industry imposes local content requirements on battery management systems and motor controllers. Jababeka Industrial Estate outside Jakarta concentrates inbound component processing for domestic assembly.
Vietnam
Red River Delta and Mekong Delta urban corridors exhibit the highest e-bike penetration rates in ASEAN. The Ministry of Transport enforces helmet and registration standards that shape homologation timelines. VinFast's Haiphong complex anchors vertically integrated battery cell production for regional supply.
Philippines
ShopeeXpress and Lazada logistics networks in Metro Manila drive commercial adoption despite residential charging constraints. The Department of Trade and Industry oversees import documentation for lithium-ion packs. Cebu City's emerging assembly operations target Visayas archipelago distribution.
Singapore
Multi-modal rail integration and last-mile connectivity requirements shape folding e-bike specifications for commuters. The Land Transport Authority regulates motor power limits and pathway access classifications. Jurong Innovation District hosts testing facilities for tropical climate durability validation.
ASEAN E-Bike Market Competitive Environment
On the supply side, the industry is bifurcating between integrated manufacturers with captive battery production and assembly specialists dependent on imported cell supplies. Three strategic archetypes now dominate: vertically integrated conglomerates controlling upstream chemistry, component-integrated assemblers protecting margins through motor and controller manufacturing, and brand-positioned distributors relying on OEM supply arrangements. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure cell supply commitments and swapping network access.
Among integrated manufacturers, Yadea Technology Group Co. Ltd and VinFast exemplify the upstream-control archetype through in-house production of critical powertrain components. Giant Manufacturing Co. Ltd occupies a position representing brand-differentiated positioning through dealer network density. These three anchors illustrate how geographic origin and corporate structure shape strategic optionality across ASEAN's incentive-differentiated markets.
| Leading Market Players |
|---|
| Yadea Technology Group Co. Ltd |
| Giant Manufacturing Co. Ltd |
| Yamaha Motor Co. Ltd |
| Trek Bicycle Corporation |
| Merida Industry Co. Ltd |
| Accell Group N.V |
| AIMA Technology Group Co. Ltd |
| VinFast |
| Polygon Bikes |
| Others |
Value Chain & Pricing Dynamics
Import tariff volatility on battery management systems and motor controllers from non-ASEAN sources compresses pricing tier spreads while forcing assembly localization decisions across Indonesian and Thai production corridors. This regulatory chokepoint simultaneously widens the gap between domestically sourced lithium-ion configurations and imported lead-acid alternatives while reshaping supplier geography toward Eastern Economic Corridor and Jababeka Industrial Estate clusters.
Pricing Analysis
Certification level against Vietnam's Ministry of Transport helmet and registration standards creates the primary spread between premium homologated fleet units and informal-market alternatives. Three-tier pricing structure across premium telematics-enabled cargo bikes, standard city commuter formats, and economy lead-acid entry points captures this differentiation. Pricing pressure stems from VinFast's vertically integrated Haiphong cell production undercutting imported battery pack costs. Delivery fleet operators exhibit lowest price sensitivity due to total cost of ownership calculations, while individual commuters in Philippine informal settlements face acute affordability constraints.
Supply Chain Analysis
Contract manufacturing capacity concentrates in Thailand's Eastern Economic Corridor assembly plants, Vietnamese Haiphong-area facilities, and Indonesian Jababeka Industrial Estate operations. Cell production draws from China's NMC and LFP chemistry suppliers, South Korean electrolyte specialists, and Japanese separator manufacturers. Single-source vulnerability persists in semiconductor-based motor controllers subject to Indonesia's local content requirements. Distribution runs through direct enterprise sales for Grab and Gojek fleets, dealer networks in Bangkok and Ho Chi Minh City, and Shopee marketplace channels for individual purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN e-bike penetration remains in early-cycle expansion, with last-mile delivery fleet electrification providing sustained adoption tailwinds across Jakarta, Bangkok, and Ho Chi Minh City logistics corridors.
For Market Incumbents: Insulate margin positions through backward integration into motor and controller manufacturing as Yadea Technology Group has demonstrated, while securing multi-year battery cell supply commitments from Vietnamese or Thai production bases. Defensive patent filings around tropical humidity-tolerant battery thermal management systems will raise barriers against emerging Chinese entrants seeking ASEAN market access.
For New Entrants and Emerging Players: Establish a beachhead in Cambodia, Laos, and Myanmar border trader corridors where regulatory ambiguity delays incumbent formal channel establishment. The cargo e-bike segment serving ShopeeXpress and Lazada operators offers the most penetrable entry point given subscription procurement models that transfer residual value risk to fleet lessors. Lead with battery-swapping network partnerships rather than vehicle-only sales.
For Investors and Strategic Acquirers: The market sits at an infrastructure-buildout phase that favors component-integrated assemblers with captive motor production over brand-dependent distributors. Long-term viability over the next decade hinges on securing localized production qualifications under Thailand Board of Investment or equivalent Vietnamese incentive schemes. Monitor which ASEAN member state first harmonizes motor power limits with EU L1e-A framework as the signal for cross-border supply chain scale inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Cell Supply Agreement | Locks in lithium-ion cost advantage against lead-acid alternatives for Indonesian fleet tenders. |
| Localized Assembly Qualification | Unlocks Thailand Board of Investment tax exemptions and import duty relief for Eastern Economic Corridor facilities. |
| Battery-Swapping Network Partnership | Captures recurring revenue streams from Grab and Gojek operators shifting to subscription procurement. |
| Telematics Platform Integration | Enables predictive maintenance subscriptions that displace traditional dealer service relationships. |
| Regulatory Harmonization Lobbying | Positions supply chains for EU L1e-A or China GB standards alignment across ASEAN borders. |
Study Parameters
Desk research of ASEAN customs trade databases, Thailand Board of Investment incentive filings, and Vietnam Ministry of Transport regulatory precedents preceded structured interviews with fleet procurement managers at Grab and Gojek, powertrain engineers at Thai and Vietnamese assembly plants, and battery cell sourcing specialists. Primary fieldwork with delivery operators in Jakarta, Bangkok, and Ho Chi Minh City validated replacement cycle assumptions and charging infrastructure constraints. Secondary sources included Indonesia Ministry of Industry local content directives, Philippine Department of Trade and Technology import documentation, and Singapore Land Transport Authority pathway access classifications. Bottom-up unit shipment estimates triangulated against top-down market value projections.
Assumptions held fixed across the modeling period include Thailand's eight-year corporate income tax exemption continuity, Vietnam's helmet and registration enforcement intensity, and Indonesia's local content requirement thresholds. Variable assumptions encompass lithium-ion cell cost decline trajectories, fleet electrification mandates from congestion charging zones, and harmonization timelines with EU L1e-A or China GB standards. The analytical framework modeled volume and value across product type, battery chemistry, end-user application, and distribution channel dimensions. CAGRs derived from logistic curve penetration modeling calibrated to two-stroke motorcycle replacement rates and commercial fleet turnover patterns.
Macroeconomic conditions sit as an overlay; deviation in regional currency stability, electricity tariff structures, or EV incentive fiscal sustainability would shift the trajectory. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement intensity. Quarterly review of Thailand Board of Investment policy adjustments, Vietnam Ministry of Transport homologation queue lengths, and Indonesian Ministry of Industry local content rule modifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Utility Vehicle Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
United Kingdom E-Bike Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Latin America Electric Bus Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
South America Electric Vehicles Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
RV SLI Battery Market