
 Kids Bicycle Market | 2026-2036
Kids Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Bicycle Market Intelligence
Aluminum is restructuring frame economics across the kids bicycle category, displacing legacy steel construction through weight reduction and corrosion resistance without proportional cost escalation. Islabikes leverages its UK-based engineering focus to sustain premium positioning in lightweight aluminum designs. Trek Bicycle Corp. dominates North American retail channels through broad distribution and brand recognition. Guardian Bikes differentiates through proprietary braking technology and direct-to-consumer channel control.
A kids bicycle constitutes a human-powered, single-rider vehicle engineered with proportional frame geometry, reduced crank lengths, and restricted gear ranges to accommodate riders between 18 months and 14 years, typically manufactured with wheel diameters from 12 to 24 inches and frame materials selected for strength-to-weight ratio. Balance bikes lead entry-level demand as parents prioritize early motor-skill development before pedal transition. Mountain bikes capture margin concentration in the preteen segment where trail-accessibility features command price premiums. Aluminum frames represent the fastest-growing material category as manufacturing scale narrows the cost gap with steel.
The US Consumer Product Safety Commission mandates mechanical and labeling standards that shape product design and testing protocols for domestic market access. The EU's REACH regulation and CE marking requirements govern chemical composition and safety certification for European distribution, effectively filtering non-compliant imports. China's GB standards and SAMR oversight establish baseline quality thresholds for both domestic consumption and export manufacturing. Stakeholders must monitor evolving chemical restrictions and regional certification reciprocity to optimize compliance investment against market expansion timing.
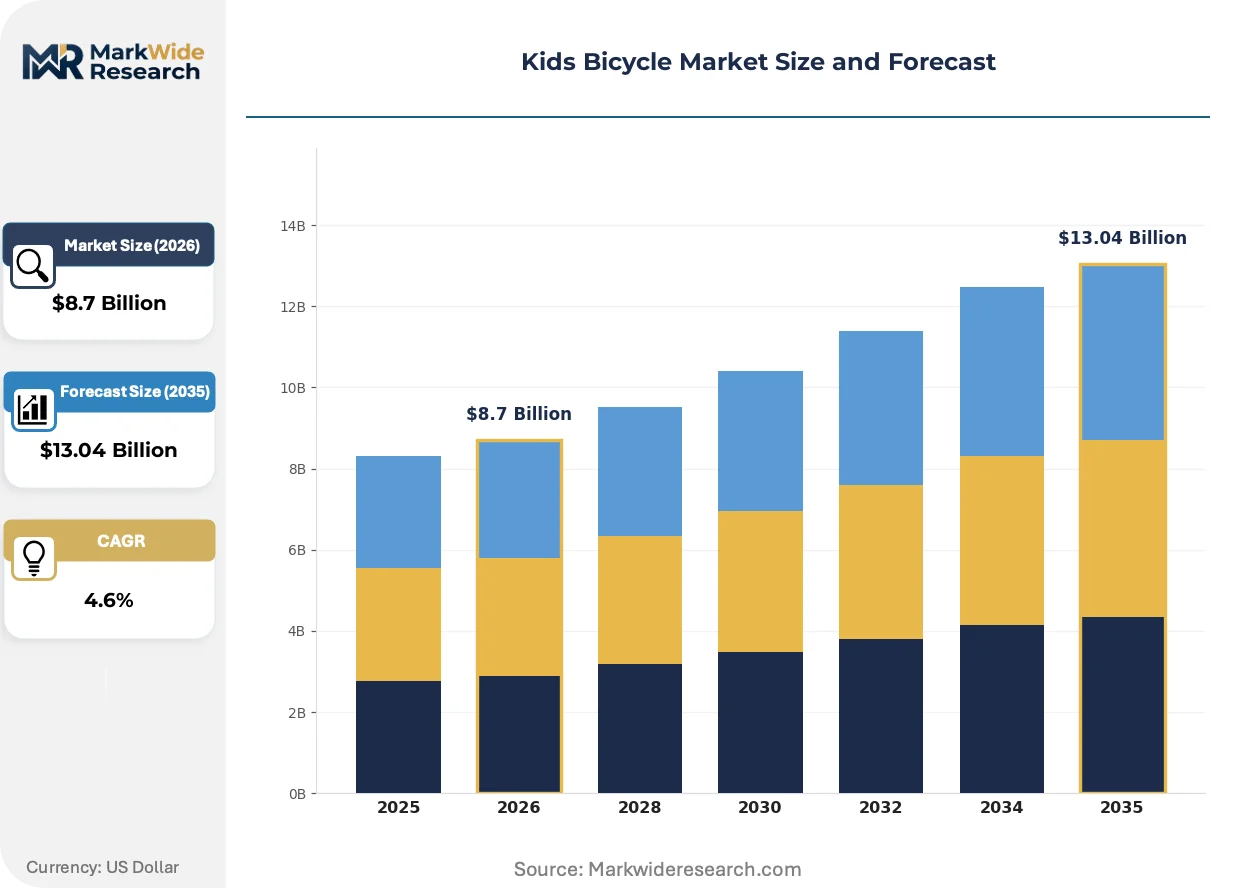
Market Dynamics
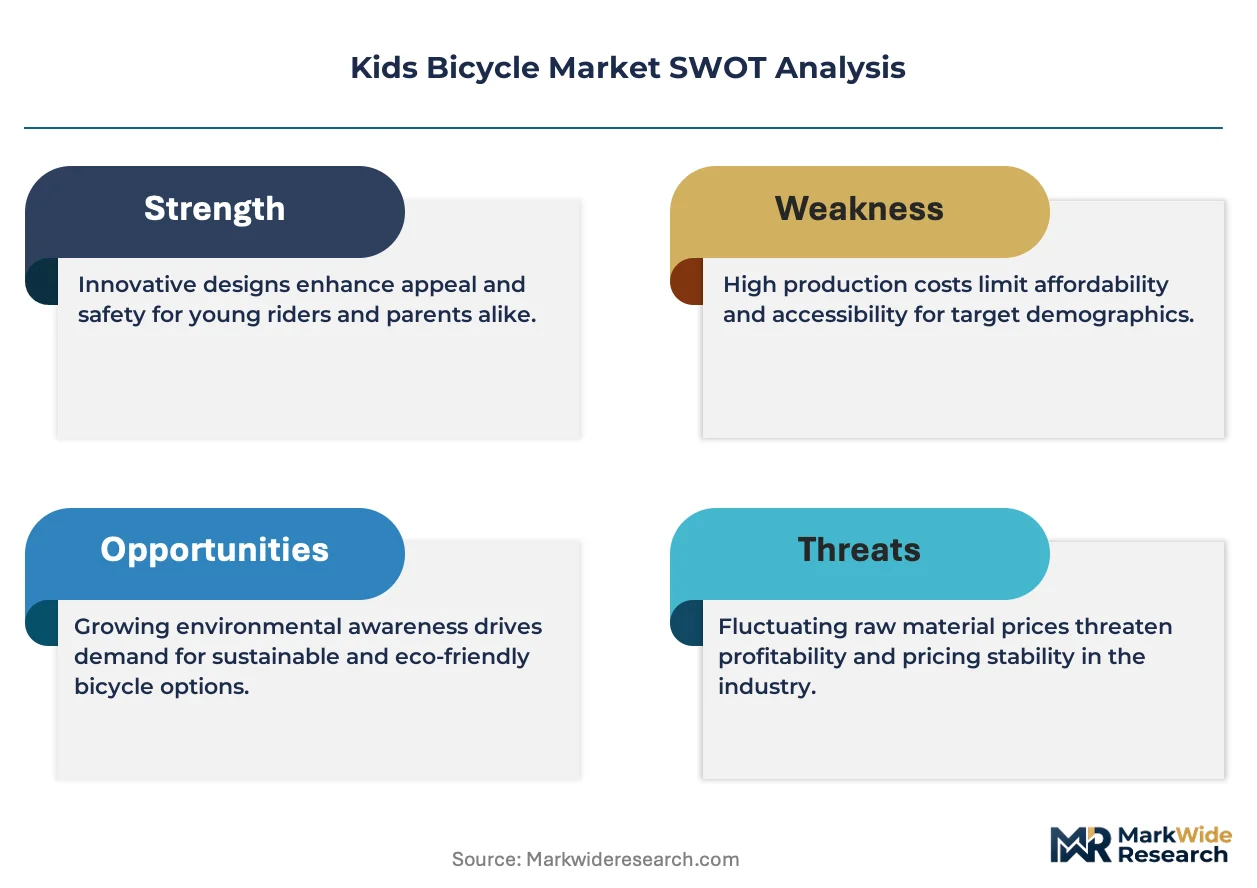
Aluminum frame adoption is compressing cost structures across the kids bicycle supply chain, forcing incumbent steel-dependent manufacturers to retool production lines or cede volume to lightweight specialists. This material transition interacts with REACH chemical compliance costs to reshape which suppliers can operate profitably in European distribution channels.
Growth Catalysts
- EU REACH chemical standards:Tightening restrictions on phthalates and heavy metals in coatings are filtering out low-cost competitors, creating compliance-driven market share consolidation for certified manufacturers.
- Preschool motor-skill development focus:Parental demand for balance bikes as early childhood physical education tools is expanding the addressable age range downward from traditional pedal-entry points.
- China domestic production scale:Concentrated manufacturing clusters in Tianjin and Zhejiang are driving aluminum forging cost curves below steel equivalent at equivalent strength-to-weight ratios.
Market Restraints
- Aluminum ingot price volatility:Input cost swings for 6061 and 7005 series alloys compress margin predictability for frame fabricators locked into annual retail pricing contracts.
- Single-source component dependency:Hydraulic disc brake systems and sealed bearing hubs concentrate in Taiwanese and Japanese supplier networks, creating geographic supply risk.
- Steel legacy infrastructure:Existing brazing equipment and chromoly tube inventories at established manufacturers create stranded asset friction against aluminum TIG welding retooling requirements.
Strategic Opportunities
- India urban middle-class expansion:Underpenetrated organized retail for premium children's cycling products in tier-two cities offers first-mover positioning before local manufacturing scales.
- Subscription and lease models:Rapid growth-stage sizing requirements create structural demand for access-over-ownership services that reduce parental purchase hesitation.
- E-bike motor miniaturization:Convergence of 250W pedal-assist systems with 20-inch wheel formats opens trail-accessibility segments previously restricted by terrain difficulty.
Industry Challenges
- Welding technician certification timelines:Aluminum TIG qualification requirements extend production workforce onboarding by four to six months versus steel brazing certification paths.
- Multi-jurisdiction labeling compliance:Simultaneous CPSC, CE, and GB standard adherence forces SKU proliferation or lowest-common-denominator specification compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Bicycle Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain Bikes, BMX Bikes, Road Bikes, Balance Bikes Frame Material: Steel, Aluminum, Carbon Fiber, Plastic Wheel Size: 12 Inch, 16 Inch, 20 Inch, 24 Inch Age Group: Toddlers, Preschoolers, Early School Age, Preteens |
| Companies Covered | Specialized Bicycle Components Inc., Islabikes, Accell Group NV, Guardian Bikes, Frog Bikes, woom Bikes, Trek Bicycle Corp., Strider Bikes, Prevelo Bikes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Bicycle Market Strategic Shifts & Innovations
Manufacturing process evolution and distribution channel restructuring are simultaneously altering how kids bicycles reach end consumers and what technical specifications define competitive viability. These shifts favor suppliers with in-house engineering capabilities over pure assembly operations.
Carbon fiber reinforced polymer is converging with thermoplastic forming processes to enable complex tube shapes previously machined from aluminum billets. High-performance preteen racing segments in Germany and the Netherlands are adopting these frames despite 40% cost premiums. This convergence is compressing the traditional aluminum-steel material hierarchy into a three-tier structure where weight-minimization commands disproportionate price realization.
REACH Annex XVII restrictions on nickel release rates are forcing component suppliers to migrate from electroplated finishes toward PVD and ceramic coating alternatives. The industrial consequence is elevated testing documentation burdens and extended product development cycles for European market entry. Brake lever and pedal manufacturers serving the 6-10 year age bracket face the most acute reformulation pressure given prolonged skin contact exposure risks.
Direct-to-consumer assembly models are displacing traditional bike shop intermediaries for entry-level and mid-tier price points. Parents in suburban US markets increasingly purchase online with home delivery, shifting pre-purchase fitting consultation toward digital sizing tools and post-purchase assembly service partnerships. This channel rotation is most visible in California and Texas metropolitan corridors where two-day delivery expectations have normalized across durable goods categories.
Kids Bicycle Market Segmentation
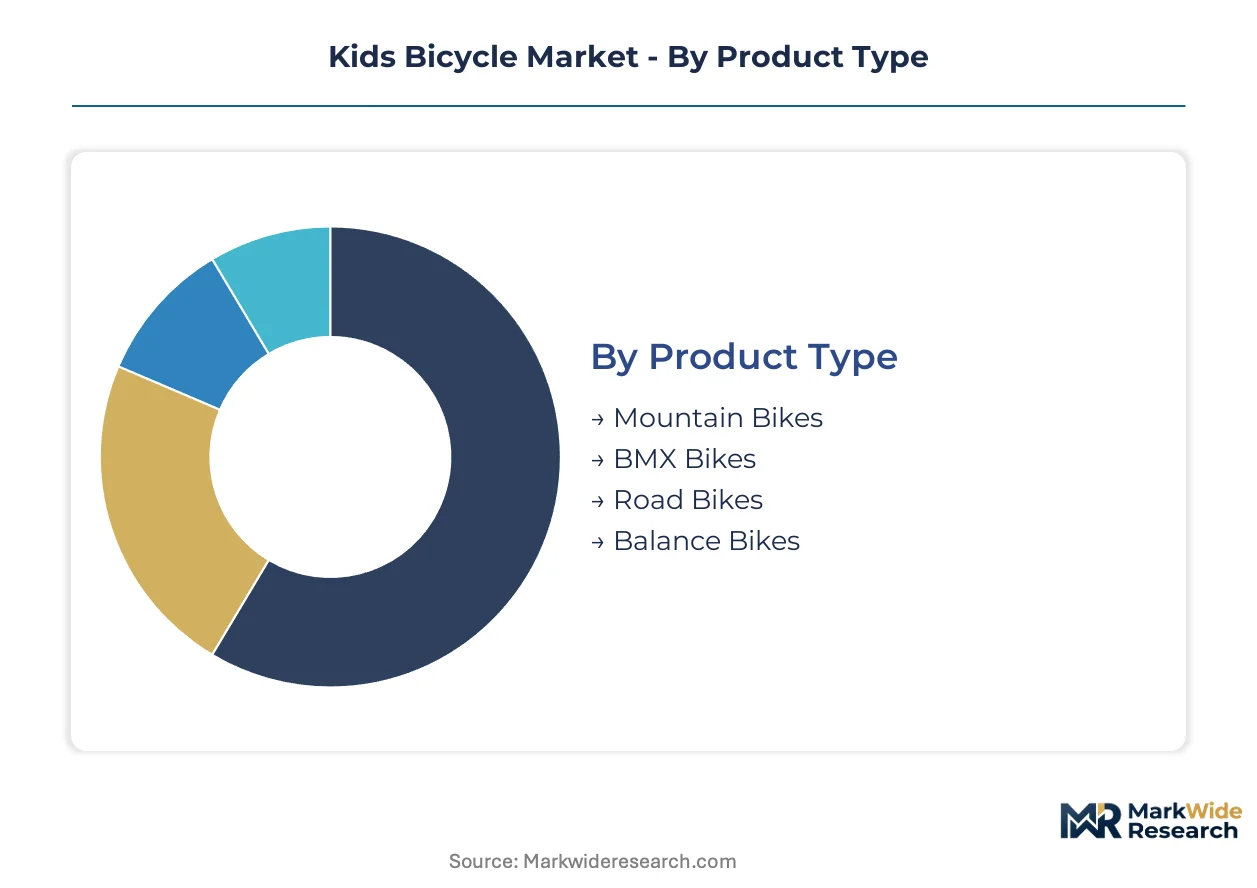
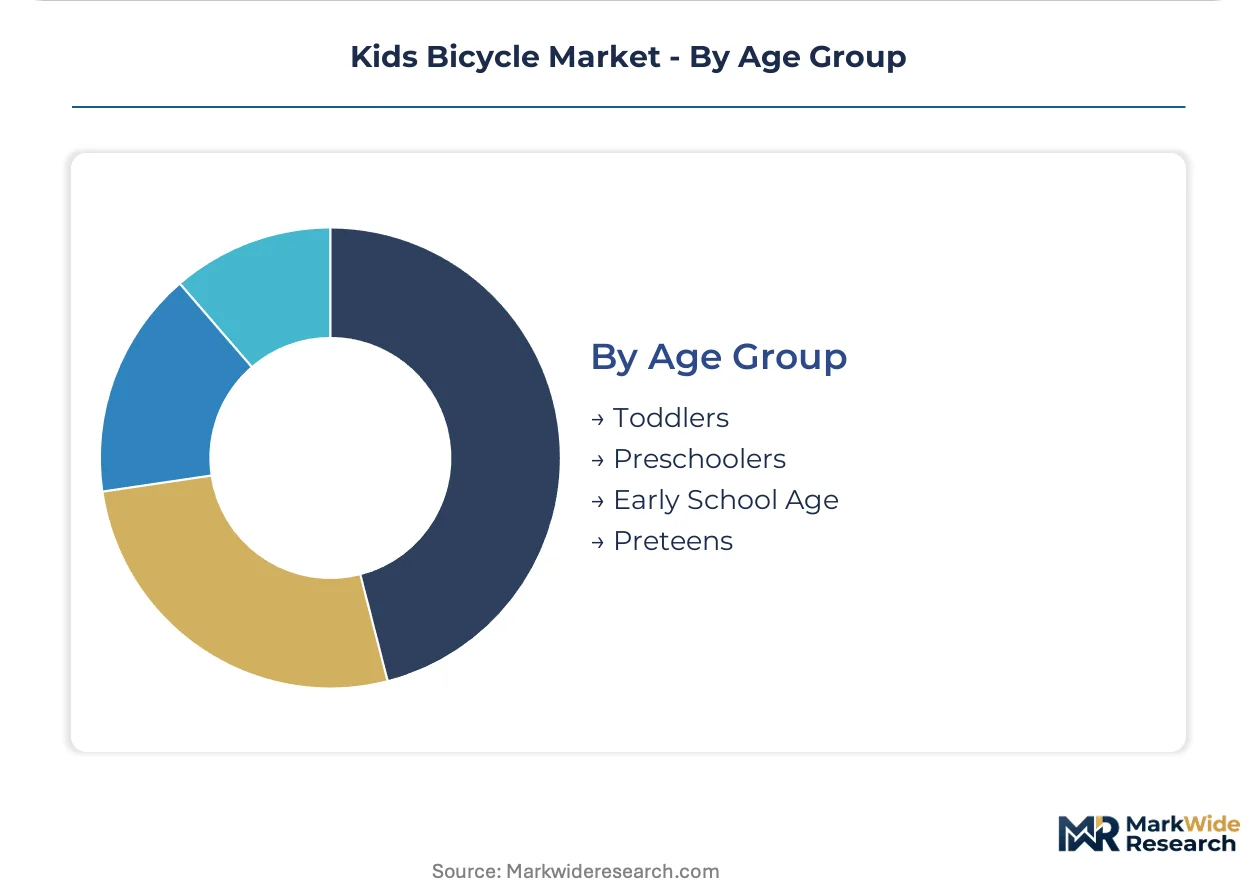
Material transitions and age-specific sizing requirements fragment the kids bicycle market into distinct technical tiers. Manufacturers must align frame geometry, wheel diameter, and component specifications with developmental stages and regional regulatory standards to capture parental purchase decisions.
Product Type:
Volume concentrates in entry-level categories where parental hesitation is lowest, while premium capture depends on trail-accessibility features and competitive positioning.
- Mountain Bikes:Suspension forks and knobby tire configurations accommodate off-trail riding for ages 8-14. Preteen demand in Germany and Colorado clusters around hydraulic disc brake specifications that exceed CPSC baseline requirements.
- BMX Bikes:Reinforced frames and 20-inch wheel formats support skatepark and pump-track disciplines. California and Florida municipal recreation investments are expanding dedicated riding infrastructure that sustains replacement purchase cycles.
- Road Bikes:Drop-bar configurations with narrow tire profiles target junior racing programs in the Netherlands and Belgium.
- Balance Bikes:Pedal-free designs with low standover height train equilibrium for riders aged 18 months to 4 years.
Today's leader: Mountain Bikes. Tomorrow's challenger: Balance Bikes.
Frame Material:
Cost-to-weight ratios determine material selection hierarchy, with manufacturing scale and chemical compliance filtering viable suppliers.
- Aluminum:6061 and 7005 series alloys deliver corrosion resistance and 30-40% weight reduction versus steel at narrowing cost premiums. Tianjin and Zhejiang forging clusters are compressing price differentials through production scale.
- Steel:Chromoly and hi-tensile constructions retain dominance in sub-$150 retail tiers where parental price sensitivity is acute. Legacy brazing infrastructure at established manufacturers creates stranded asset friction against aluminum retooling.
- Carbon Fiber:Thermoplastic forming processes enable complex tube shapes for German and Dutch junior racing segments.
- Plastic:Injection-molded frames serve disposable-tier balance bikes and rental fleet applications.
Aluminum is climbing the fastest as REACH-compliant coating costs erode steel's residual price advantage.
Wheel Size:
Proportional scaling requirements create discrete product lifecycles that drive replacement frequency.
- 12 Inch:Entry balance bike format for 18-36 month riders with inseam measurements below 35 centimeters.
- 16 Inch:First pedal bike specification for ages 4-6 with coaster brake dominance and training wheel compatibility.
- 20 Inch:Mid-childhood standard for ages 6-9 spanning BMX, mountain, and hybrid configurations. Texas and California suburban markets show highest per-capita penetration.
- 24 Inch:Preteen transition format bridging to adult 26-inch and 27.5-inch standards.
Twenty-inch formats command the steepest expansion trajectory as multi-discipline versatility extends product lifespan.
Age Group:
Purchase authority and developmental priorities shift across parental decision-making stages.
- Toddlers:Balance bike introduction at 18-36 months with safety certification visibility driving brand selection.
- Preschoolers:Pedal transition at ages 3-5 represents peak purchase frequency as families acquire multiple sizes for siblings.
- Early School Age:Ages 6-9 segment commands highest absolute unit volume through school commuting and recreational trail use.
- Preteens:Ages 10-14 category captures margin concentration where terrain capability and social visibility justify price premiums.
Preschoolers generate the highest transaction velocity. Preteens deliver the strongest margin realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tianjin and Zhejiang manufacturing clusters anchor global kids bicycle production capacity, with regional demand patterns diverging sharply between developed safety-regulated markets and emerging volume-driven economies. Parental purchasing authority concentrates differently across geographies, shaping channel strategies and product specification requirements.
United States
Suburban family formations in Texas and California metropolitan corridors drive replacement purchase cycles for 20-inch wheel formats. The US Consumer Product Safety Commission mandates mechanical and labeling standards that filter non-compliant imports through testing protocol requirements. Guardian Bikes and Trek Bicycle Corp. anchor direct-to-consumer channel control alongside traditional retail partnerships.
Germany
Junior racing programs and trail-accessibility culture sustain premium positioning for hydraulic disc brake specifications in the 8-14 age bracket. The EU REACH regulation and CE marking requirements govern chemical composition and safety certification, elevating compliance documentation burdens for coating suppliers. Bavaria and Baden-Württemberg host specialized retailers serving competitive youth cycling segments.
China
Domestic youth sports investment and organized retail expansion concentrate demand in tier-one and tier-two cities. SAMR oversight and GB standards establish baseline quality thresholds for both domestic consumption and export manufacturing. Tianjin forging clusters compress aluminum frame cost curves below steel equivalents through production scale advantages.
Netherlands
Cycling infrastructure integration and early childhood physical education priorities expand balance bike penetration into the 18-36 month demographic. ECHA chemical restrictions filter electroplated component finishes toward PVD and ceramic coating alternatives. Randstad urban corridors concentrate specialty retail and junior racing program distribution.
India
Urban middle-class expansion in Maharashtra and Karnataka creates first-mover positioning opportunities before local manufacturing scales. BIS quality certification and import duty structures shape competitive entry barriers for premium children's cycling products. Organized retail penetration remains underdeveloped in tier-two cities relative to population density.
Kids Bicycle Market Key Industry Players
Global majors compete with regional champions across distribution channel control and material specialization dimensions. The vendor base separates into three functional tiers: aluminum-focused lightweight specialists, steel-dependent volume producers, and premium carbon fiber racing fabricators. Strategic archetypes include direct-to-consumer disruptors, engineering-centric niche players, and broad-channel mass-market incumbents. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers retool production lines for REACH-compliant aluminum fabrication.
Within the engineering-centric tier, Islabikes and Frog Bikes exemplify UK-based lightweight aluminum positioning through proportional frame geometry specialization. Trek Bicycle Corp. anchors North American retail channel dominance through broad distribution infrastructure and brand recognition. Guardian Bikes occupies the direct-to-consumer vector with proprietary braking technology and channel control architecture. These three companies represent distinct strategic archetypes rather than overlapping competitive positioning.
| Leading Market Players |
|---|
| Specialized Bicycle Components Inc. |
| Islabikes |
| Accell Group NV |
| Guardian Bikes |
| Frog Bikes |
| woom Bikes |
| Trek Bicycle Corp. |
| Strider Bikes |
| Prevelo Bikes |
| Others |
Cost & Logistics Intelligence
Captive aluminum forging operations in Tianjin and Zhejiang manufacturing clusters anchor both supply security and pricing power for frame fabricators serving REACH-regulated European markets. This backward integration into 6061 and 7005 alloy processing insulates certified producers from commodity spot volatility while compressing cost curves below steel-dependent competitors.
Pricing Analysis
Aluminum ingot cost pass-through mechanisms dominate frame pricing dynamics, with 6061 and 7005 series alloy volatility compressing margin predictability for fabricators locked into annual retail contracts. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified lightweight designs from chromoly steel entry points and carbon fiber racing tiers. Cost compression in sub-$150 steel segments is intensifying because legacy brazing infrastructure creates stranded asset friction against aluminum retooling requirements. Preschool parents exhibit acute price sensitivity in first-pedal purchases, while preteen trail-accessibility specifications command the lowest elasticity.
Supply Chain Analysis
EU REACH Annex XVII nickel release restrictions are reshaping component sourcing toward PVD and ceramic coating alternatives for brake lever and pedal suppliers. Geographic supply concentration centers on China for aluminum forging, Taiwan for hydraulic disc brake systems, and Japan for sealed bearing hubs. Raw material dependencies rest on 6061 alloy billets, thermoplastic resins for carbon fiber forming, and REACH-compliant coating chemistries. Single-source vulnerability concentrates in Taiwanese brake system suppliers, creating geographic concentration risk. Distribution runs through direct-to-consumer channels displacing traditional bike shop intermediaries in suburban US corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU REACH chemical standards tighten material compliance thresholds and filter non-certified competitors from European distribution channels.
For Market Incumbents: Anchor aluminum TIG welding certification programs to defend technician workforce pipelines against four-to-six month qualification timelines that constrain production scaling. Defend channel position by deepening backward integration into REACH-compliant coating processes before electroplated finish suppliers exit the market. Consolidation pressure from stranded steel brazing infrastructure at legacy manufacturers creates acquisition opportunities for aluminum-focused fabricators with certified European distribution. For New Entrants and Emerging Players: REACH Annex XVII restrictions in Europe open a window for PVD and ceramic coating specialists to capture component supply share from electroplated finish incumbents facing reformulation pressure. Target subscription and lease models in US suburban markets where rapid growth-stage sizing requirements create structural demand for access-over-ownership services. Pursue direct-to-consumer assembly partnerships with last-mile logistics providers to bypass traditional bike shop intermediaries in California and Texas metropolitan corridors. For Investors and Strategic Acquirers: Roll-up economics work for aluminum-focused lightweight specialists because REACH compliance costs and certification documentation burdens create scale advantages that fragment steel-dependent legacy producers. Platform consolidation targets should emphasize in-house forging capabilities and established European distribution relationships rather than pure assembly operations. Watch aluminum ingot price volatility as the inflection signal determining margin compression severity for non-integrated frame fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Investment | PVD and ceramic alternatives capture share from electroplated suppliers facing nickel release restrictions. |
| Direct-to-Consumer Channel Expansion | Home delivery partnerships with digital sizing tools bypass bike shop intermediaries in Texas and California. |
| Aluminum Forging Capacity Addition | Tianjin cluster expansion compresses cost curves below steel equivalents through production scale. |
| Subscription Model Launch | Access-over-ownership services reduce parental purchase hesitation for rapid growth-stage sizing requirements. |
| Technician Certification Program | TIG welding qualification pipelines defend against four-to-six month onboarding timelines constraining output. |
Research Approach
Bottom-up age-group and wheel-size modeling reconciled against top-down material-category production tracking forms the analytical core of this study. Primary interviews with frame design engineers, REACH compliance officers at coating suppliers, procurement leads at retail distributors, and after-sales service managers combined with secondary validation from customs records, CPSC recall databases, ECHA restriction updates, and SAMR quality disclosure filings. Triangulation between demand-side parental purchase pattern analysis and supply-side forging capacity assessments ensures dimensional consistency across projections.
Input-output matrices map aluminum alloy consumption to frame output volumes across 12-inch through 24-inch wheel formats, with segmentation dimensions spanning product type, frame material, age group, and regional regulatory cluster. CAGRs derive from slope-intercept modeling of historical volume trajectories adjusted for REACH compliance cost pass-through and aluminum-steel substitution elasticities. Forecast inputs incorporate youth sports investment flows in China, suburban family formation rates in US metropolitan corridors, and junior racing program expansion in Germany and the Netherlands.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price spike conditions or accelerated REACH chemical restriction timelines. Projections reflect assumptions regarding certification reciprocity stability and technician training pipeline throughput. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Adventure Motorcycle Market
Bikes and Motorcycles
Motorcycle Hub Motor Market
Bikes and Motorcycles
Europe E-Cargo Bike Market
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Austria E-Bike Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Global Motorcycle Handlebar Control Switch Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Motorsports Motorcycle Market