
 Electric Motorsport Market | 2026-2036
Electric Motorsport Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Motorsport Market Foresight
Silicon carbide is rebalancing powertrain economics by replacing traditional silicon IGBTs in inverter modules, cutting switching losses and thermal mass. Porsche leverages in-house semiconductor sourcing to protect margin on its 99X Electric platform. Rimac sustains technology leadership through proprietary 800-volt architecture development. McLaren Racing anchors its Formula E program with extensive simulator-based powertrain calibration.
Electric motorsport encompasses competitive racing disciplines utilizing battery-electric or hydrogen-electric propulsion systems, typically operating at 400–800 volts DC with peak power outputs exceeding 250 kW in premier categories. These vehicles serve as R&D accelerators for road-relevant electrification technologies under extreme thermal and duty-cycle conditions. Formula E commands the largest revenue pool among vehicle types due to manufacturer-backed championship budgets and media rights value. Solid-state battery research attracts disproportionate investment within battery technology segments as teams pursue energy density breakthroughs. Professional teams represent the most concentrated end-user segment, absorbing the bulk of factory development spending and technical personnel.
FIA technical regulations govern powertrain homologation and battery safety standards across championship formats. EPA tailpipe-equivalent frameworks and EU Green Deal mobility targets shape manufacturer participation incentives in electric racing series. Stakeholders must monitor regulatory divergence between FIA safety mandates and national type-approval standards as series expand into new territories.
Market Dynamics
OEM-backed factory teams are consolidating technical control as battery energy density regulations tighten across FIA jurisdictions, compressing development cycles and concentrating R&D spending among vertically integrated manufacturers.
Growth Catalysts
- EU Green Deal mobility targets:Manufacturer participation incentives in electric racing series strengthen as the framework mandates fleet electrification timelines, channeling engineering talent toward motorsport R&D platforms.
- Silicon carbide inverter modules:Semiconductor substitution cuts switching losses and thermal mass, enabling powertrain packaging density gains that translate directly to lap time advantages.
- Formula E championship budgets:Factory-backed entries absorb concentrated technical personnel and capital deployment, creating sustainable revenue pools for series organizers and suppliers.
Market Restraints
- Lithium supply concentration:Raw material processing dominance in specific geographies creates input cost volatility and geopolitical exposure for battery pack procurement.
- FIA homologation timelines:Extended certification cycles for new powertrain architectures delay competitive deployment and freeze development spending across multiple seasons.
- Solid-state battery immaturity:Energy density breakthroughs remain laboratory-constrained, limiting on-track validation opportunities for next-generation cell chemistries.
Strategic Opportunities
- India motorsport infrastructure:Underpenetrated market conditions and rising manufacturer interest create entry pathways for championship expansion and local team formation.
- Hydrogen-electric convergence:FIA regulatory frameworks for fuel cell categories enable technology diversification beyond pure battery architectures.
- Simulator-based powertrain calibration:Digital twin adoption reduces track testing costs and accelerates iterative development cycles for professional teams.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent pools for high-voltage inverter design remain shallow relative to demand from multiple racing categories.
- 800-volt platform integration:Legacy charging infrastructure and service equipment requires capital-intensive reconfiguration to support next-generation vehicle architectures.
- Cross-series IP licensing:Proprietary battery management algorithms and thermal control systems generate disputes between factory teams and independent entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Motorsport Market |
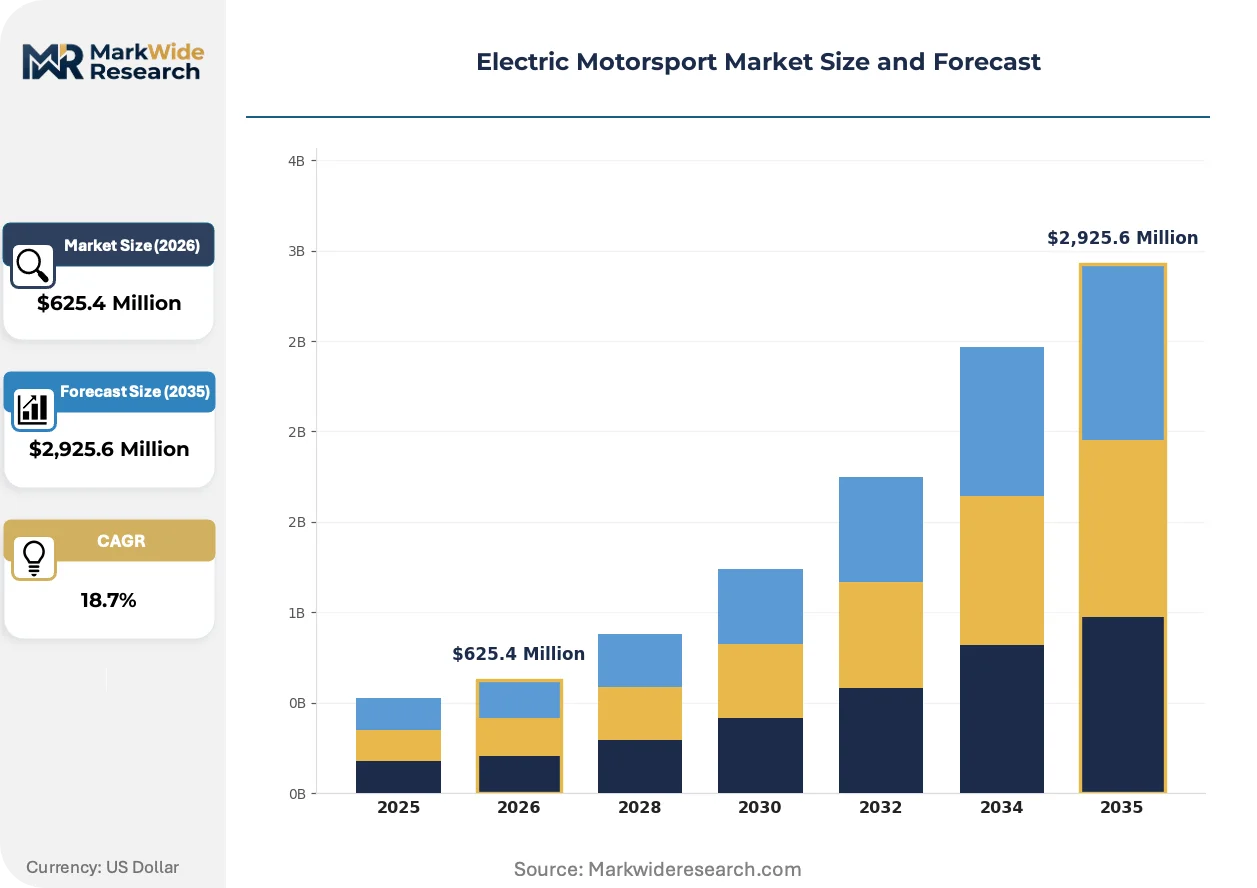
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $2,925.6 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Formula E, Electric Bikes, E-Karts, Electric SUVs Battery Technology: Lithium-Ion, Solid-State, Flow Batteries, Nickel-Metal Hydride Event Type: Championships, Exhibitions, Demonstration Races, Test Events End User: Professional Teams, Private Owners, Manufacturers, Spectators |
| Companies Covered | McLaren Racing, DS Automobiles, Porsche, Rimac, Yamaha Motor Company, Nissan, Mahindra Racing, Pininfarina, Stellantis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Motorsport Market Shifts & Advancements
Technology maturation is compressing the gap between racing validation and road car deployment, with powertrain architectures migrating faster from track to production vehicle programs than in previous motorsport eras.
Silicon carbide semiconductors are replacing traditional silicon IGBTs in inverter modules. Factory teams are adopting these components at pace as regulations tighten thermal efficiency requirements. This substitution is converging with battery packaging constraints to enable higher sustained power outputs within fixed weight limits.
FIA technical regulations governing powertrain homologation are expanding scope to cover battery safety standards and crash structure integration. These mandates force earlier design freeze dates and concentrate validation spending among manufacturers with captive testing facilities. Professional teams in Western Europe face the most compressed compliance timelines as championship headquarters proximity accelerates regulatory implementation.
After-sales technical service unbundling is separating powertrain maintenance from chassis preparation. Independent race preparation specialists are capturing service contracts as factory teams focus R&D resources on competitive development. This pattern is most visible in the United Kingdom and Germany where established motorsport engineering clusters support fragmented team structures.
Electric Motorsport Market Segmentation
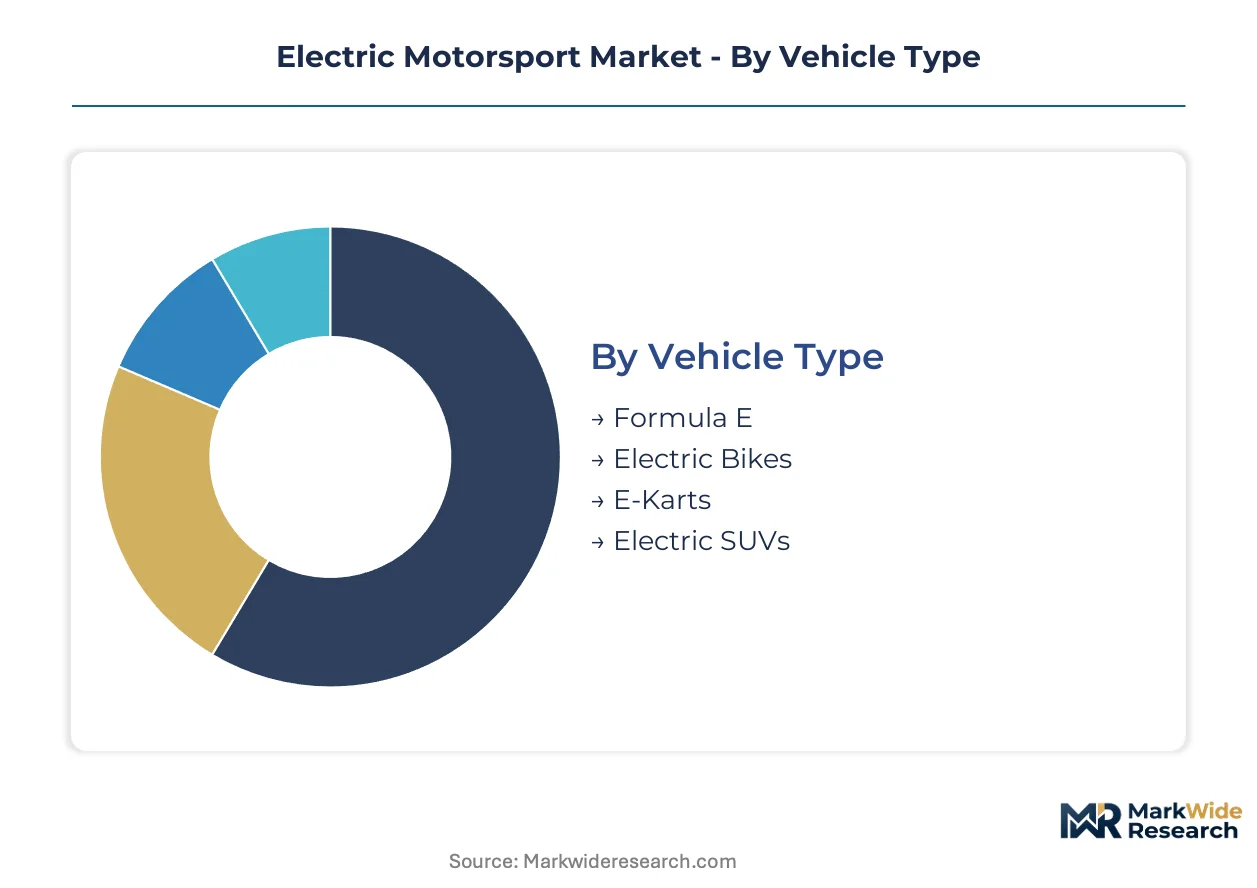
Electric motorsport segmentation reflects divergent R&D priorities across manufacturer-backed series and emerging grassroots formats. Championship budgets and homologation timelines concentrate investment in specific vehicle architectures while battery chemistry roadmaps split between proven lithium-ion deployments and laboratory-bound solid-state development.
Vehicle Type:
Buyer decisions here track manufacturer championship commitment and media rights value rather than unit economics alone.
- Formula E:Premier open-wheel category operating at 800 volts DC with peak outputs exceeding 250 kW. Factory-backed entries from Porsche, Jaguar, and Nissan concentrate engineering talent in Western Europe where FIA homologation cycles run shortest and championship budgets absorb the bulk of professional team spending.
- Electric SUVs:Off-road electric racing formats including Extreme E and emerging rally-cross derivatives. Series organizers target sustainability-conscious sponsors while manufacturers leverage the platform for SUV road car technology transfer under extreme thermal and duty-cycle validation.
- Electric Bikes:Two-wheeled electric racing categories spanning MotoE and regional championships.
- E-Karts:Entry-level electric karting formats serving driver development pipelines and grassroots participation.
Volume sits with Formula E; growth tilts toward Electric SUVs.
Battery Technology:
Procurement patterns here split between immediate competitive deployment and long-dated energy density roadmaps.
- Lithium-Ion:Mature cell chemistry dominating current Formula E and production-based series. NMC and LFP variants balance power delivery against thermal stability under sustained high-load conditions where FIA safety mandates govern crash structure integration and thermal runaway containment.
- Solid-State:Next-generation architecture promising energy density breakthroughs for future homologation cycles. Laboratory-constrained validation timelines delay on-track deployment despite disproportionate R&D investment from manufacturers targeting road car technology transfer.
- Flow Batteries:Redox flow architectures enabling rapid refueling through electrolyte exchange.
- Nickel-Metal Hydride:Legacy chemistry retained in cost-constrained entry-level categories.
Commercial traction clusters on Lithium-Ion; patent filing velocity favors Solid-State.
Event Type:
Revenue concentration follows broadcast rights value and manufacturer activation budgets rather than participant volume.
- Championships:Multi-round series with FIA sanctioning and factory team participation. Formula E and Extreme E command sustainable revenue pools through media rights, title sponsorship, and manufacturer technical partnership fees concentrated in Western European headquarters markets.
- Demonstration Races:Single-event showcases at established motorsport venues. These formats attract manufacturer marketing spend for technology visibility without full-season budget commitment, particularly at legacy circuits seeking electrification relevance.
- Exhibitions:Static or low-speed showcases at automotive trade events and city festivals.
- Test Events:Private manufacturer sessions and FIA homologation validation runs.
Spending concentrates in Championships; sponsor experimentation expands fastest through Demonstration Races.
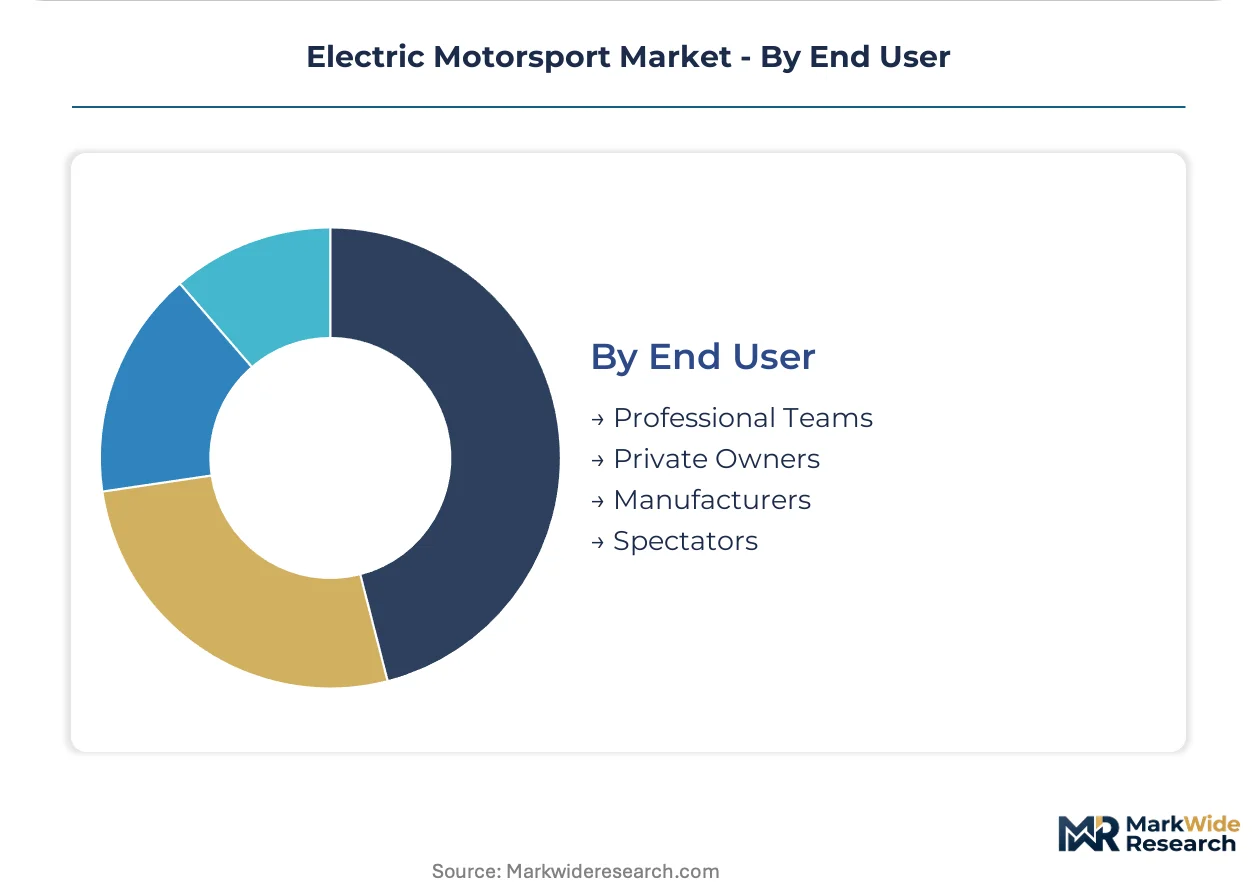
End User:
Customer economics diverge sharply between factory-funded R&D platforms and individual asset ownership.
- Professional Teams:Factory-backed and independent race operations absorbing concentrated technical personnel and capital deployment. These entities drive powertrain development cycles and validate semiconductor and battery innovations under FIA technical regulations before road car migration.
- Manufacturers:OEMs funding championship entries as R&D accelerators and marketing platforms. EU Green Deal mobility targets channel engineering talent toward motorsport programs as fleet electrification timelines compress internal development roadmaps.
- Private Owners:Individual competitors in club-level electric racing and time attack formats.
- Spectators:Event attendees and broadcast consumers generating media rights and ticket revenue.
Development investment pools with Professional Teams; manufacturer commitment expansion outpaces other segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formula E championship budgets concentrate engineering talent in Western Europe, where FIA homologation cycles run shortest and manufacturer factory teams absorb the bulk of professional development spending.
United Kingdom
McLaren Racing anchors its Formula E program with extensive simulator-based powertrain calibration from its Woking headquarters. The FIA technical regulations governing battery safety standards receive rapid implementation through proximity to championship administration. Silverstone-based engineering clusters support fragmented team structures as after-sales technical service unbundles from chassis preparation.
Germany
Porsche leverages in-house semiconductor sourcing to protect margin on its 99X Electric platform while Stuttgart engineering centers drive silicon carbide inverter adoption. The EU Green Deal mobility targets channel manufacturer participation incentives toward motorsport R&D platforms. Baden-Württemberg manufacturing clusters concentrate captive testing facilities for compressed compliance timelines.
France
DS Automobiles maintains factory-backed entries through Paris-region engineering centers as battery energy density regulations tighten across FIA jurisdictions. The country's national automotive regulator enforces type-approval standards that shape powertrain homologation requirements. Île-de-France technical partnerships sustain championship revenue pools through media rights and manufacturer activation budgets.
United States
EPA tailpipe-equivalent frameworks shape manufacturer participation incentives for electric racing series expansion into North American territories. California-based technology clusters attract disproportionate solid-state battery research investment despite laboratory-constrained validation timelines. Los Angeles and San Francisco metropolitan areas host demonstration races that attract sustainability-conscious sponsors without full-season budget commitment.
China
Raw material processing dominance for lithium supply creates input cost volatility exposure for battery pack procurement across factory team supply chains. The Ministry of Industry and Information Technology governs GB standards for high-voltage electrical systems that influence FIA safety mandate alignment. Shenzhen and Shanghai engineering centers concentrate power electronics engineering talent for inverter module development.
Electric Motorsport Market Competitive Landscape
Strategic partnerships dominate the current landscape as OEM-backed factory teams consolidate technical control and concentrate R&D spending among vertically integrated manufacturers. The vendor base structures across three tiers: captive semiconductor sourcing operations, independent race preparation specialists, and championship-organizing rights holders. Two archetypes prevail—automotive OEMs with in-house motorsport divisions and dedicated racing constructors with proprietary powertrain architectures. Technology licensing and geographic expansion represent the dominant competitive moves as series expand into underpenetrated territories.
Among manufacturer-backed entrants, Porsche, McLaren Racing, and Rimac occupy positions that exemplify divergent strategic archetypes within the competitive set. Porsche represents the vertically integrated automotive OEM with captive semiconductor supply chains. McLaren Racing anchors the specialist racing constructor model with heavy reliance on digital twin development infrastructure. Rimac sits within the emerging technology pure-play category, characterized by proprietary high-voltage architecture development and third-party supply relationships to external OEM programs.
| Leading Market Players |
|---|
| McLaren Racing |
| DS Automobiles |
| Porsche |
| Rimac |
| Yamaha Motor Company |
| Nissan |
| Mahindra Racing |
| Pininfarina |
| Stellantis |
| Others |
Supply & Pricing Matrix
Lithium carbonate spot indices cascading through battery pack procurement contracts stratify pricing tiers across factory-backed and independent team archetypes, with raw material volatility compressing margins most acutely for entrants lacking captive semiconductor sourcing or long-dated supplier agreements.
Pricing Analysis
High-volume chassis procurement from established constructors runs on thin margins, while low-volume powertrain development commands substantial premiums reflecting embedded R&D recovery and FIA homologation compliance costs. Pricing stratifies across factory-backed championship entries, independent professional teams, and grassroots demonstration formats, with differentiation anchored in battery energy density certification tiers and after-sales technical service bundling. Cost compression in independent team segments is intensifying as lithium supply concentration feeds input volatility. Private owner categories exhibit highest price sensitivity; OEM-backed factory teams demonstrate least sensitivity due to captive R&D budget absorption.
Supply Chain Analysis
FIA battery safety certification and semiconductor automotive-grade qualification gates concentrate supplier approvals among incumbents with established motorsport validation histories. Cell manufacturing clusters in China, South Korea, and Japan feed the tier-one battery pack assembly operations anchoring Formula E supply. Silicon carbide wafer fabrication draws from Taiwan and Germany, with inverter module integration resting on specialized power electronics engineering pools in the United Kingdom and Germany. Single-source vulnerability for lithium hydroxide refining creates geopolitical exposure. Distribution runs through factory team captive procurement arms and independent race preparation specialists with unbundled service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics engineering scarcity and extended FIA homologation timelines constrain capacity expansion, propping pricing power for qualified suppliers and vertically integrated manufacturers with captive validation facilities.
For Market Incumbents: Cement technology leadership through proprietary 800-volt architecture development and in-house semiconductor sourcing that insulates margins from raw material volatility. Deepen backward integration into battery cell supply through strategic partnerships with Asian manufacturers. Prioritize simulator-based powertrain calibration infrastructure to compress development cycles against emerging technology pure-plays. For New Entrants and Emerging Players: The mid-tier pricing gap between factory-backed Formula E entries and grassroots electric karting formats offers white-space opportunity for regional championship organizers and independent race preparation specialists. Target India motorsport infrastructure expansion where underpenetrated conditions and rising manufacturer interest reduce competitive density. Pursue hydrogen-electric convergence categories as regulatory frameworks mature, enabling technology diversification without direct confrontation with established battery-electric incumbents. For Investors and Strategic Acquirers: The window for entry favors technology pure-plays with proprietary high-voltage architectures and third-party OEM supply relationships over capital-intensive factory team operations with fixed cost structures. Long-term viability hinges on road-relevant technology transfer capabilities spanning the 5-10 year electrification transition. Monitor solid-state battery validation milestones as the critical inflection signal for next-generation competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Adoption | Porsche's in-house semiconductor sourcing protects margin on 99X Electric platform development. |
| Simulator-Based Powertrain Calibration | McLaren Racing's Woking infrastructure accelerates iterative development without track testing cost inflation. |
| 800-Volt Platform Standardization | Rimac's proprietary architecture development sustains technology leadership across third-party OEM programs. |
| India Motorsport Infrastructure Entry | Underpenetrated market conditions and rising manufacturer interest create expansion pathways for championship organizers. |
| Hydrogen-Electric Category Development | FIA regulatory frameworks for fuel cell racing enable technology diversification beyond pure battery architectures. |
Research Methodology
Independent corroboration across FIA technical delegates, Tier 1 supplier procurement leads, and championship organizing rights holders underwrites the qualitative findings, with secondary validation drawing from FIA homologation filings, EU Green Deal mobility target documentation, and EPA tailpipe-equivalent framework publications. Primary interviews with powertrain engineering directors, battery pack procurement managers, and motorsport regulatory affairs specialists combined with customs data for lithium carbonate trade flows and semiconductor import records. Bottom-up segmentation modeling and top-down championship budget aggregation triangulate market sizing.
Rate-of-change decomposition across vehicle type, battery technology, event format, and end-user segments structures the analytical framework over the projection horizon. CAGRs derive from segment-level growth factor analysis incorporating manufacturer participation incentives, regulatory timeline compression, and technology maturation curves. Modeled inputs include FIA homologation cycle durations, battery energy density roadmap milestones, and silicon carbide adoption curves across inverter module deployments.
Inputs from FIA technical working groups and championship financial disclosures were available through the study window; gaps in solid-state battery laboratory-to-track validation timelines introduce uncertainty bands for long-dated technology migration assumptions. Forecasts reflect documented assumptions regarding regulatory convergence between FIA safety mandates and national type-approval standards. A model refresh is warranted upon material change in EU Green Deal fleet electrification timeline acceleration or lithium supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Bike Fenders Market
Bikes and Motorcycles
Germany E-Bike Market
Bikes and Motorcycles
Motorcycle Hub Motor Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Two-Wheeler Fuel Injection Systems Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Cruiser Bikes Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
Two Wheeler Seats Market