
 Saudi Arabia Motorcycle ADAS Market | 2026-2036
Saudi Arabia Motorcycle ADAS Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Motorcycle ADAS Market Insights
Fleet operator demand in Saudi Arabia is hardening as commercial delivery and logistics companies standardize on motorcycle ADAS for liability reduction. Continental AG leverages its radar-based portfolio to anchor OEM partnerships with premium motorcycle brands. Robert Bosch GmbH competes through Bosch Mobility Solutions with integrated sensor fusion platforms. TVS Motor Co. differentiates by embedding factory-installed ADAS at accessible price points for the regional mid-market.
Motorcycle Advanced Driver Assistance Systems integrate radar, camera, and ultrasonic sensors to deliver collision avoidance, adaptive cruise control, and lane departure warning functions specifically calibrated for two-wheeler dynamics and lean-angle compensation. Camera-based technology leads installation volume due to lower unit cost and mature supply chains, while radar-based systems capture premium margin pools in factory-installed configurations. Aftermarket channels serve the largest addressable base of existing motorcycles, though OEM solutions command higher per-unit pricing and tighter calibration standards.
SASO mandates increasingly reference motorcycle safety equipment, while the Saudi Traffic Department enforces commercial fleet inspection protocols that incentivize ADAS retrofitting. The General Authority for Transport coordinates with insurers to link premium discounts to verified blind spot detection and collision warning installations. Stakeholders must monitor regulatory harmonization timelines between SASO technical regulations and United Nations ECE framework adoptions to time product certification investments.
Market Dynamics
SASO's tightening vehicle safety mandates are compressing certification timelines and forcing OEMs to pre-integrate radar and camera systems at the factory level, fundamentally restructuring how motorcycle ADAS reaches Saudi riders.
Growth Catalysts
- Commercial fleet liability reduction:Delivery and logistics operators in Riyadh and Jeddah are standardizing on blind spot detection and collision warning systems to lower insurance premiums and accident-related litigation exposure.
- SASO technical regulations:The Saudi Standards, Metrology and Quality Organization is expanding mandatory safety equipment lists to include motorcycle-specific ADAS, creating compliance-driven replacement cycles.
- Lean-angle compensation algorithms:Advanced sensor fusion calibrated for two-wheeler dynamics is enabling functional parity with passenger car systems, expanding addressable use cases beyond straight-line highway riding.
Market Restraints
- Semiconductor supply concentration:Radar sensor chip fabrication concentrates in East Asian foundries, exposing Saudi distributors to lead time volatility and minimum order quantity constraints.
- Technical calibration limitations:Aftermarket installations lack factory-grade dynamometer validation, producing performance variance that undermines insurer recognition programs.
- Substitution by telematics-only solutions:Basic GPS tracking and accelerometer-based crash detection offer lower upfront costs for cost-sensitive fleet operators, delaying ADAS adoption in price-driven segments.
Strategic Opportunities
- Eastern Province fleet expansion:Dammam and Khobar logistics corridors remain underpenetrated relative to Riyadh and Jeddah, offering first-mover positioning for regional service networks.
- Insurance-linked incentive structures:The General Authority for Transport is coordinating premium discount frameworks that reward verified ADAS installations, creating direct economic pull for compliant systems.
- Camera-radar convergence:Integrated sensor platforms combining computer vision with millimeter-wave detection are reducing unit costs while expanding functional coverage to low-visibility conditions.
Industry Challenges
- Certification timeline compression:SASO's accelerated harmonization with United Nations ECE frameworks is forcing manufacturers to parallel-track multiple approval processes without guaranteed timeline alignment.
- Specialized technician scarcity:Radar calibration and sensor fusion debugging require competencies distinct from traditional automotive electrical work, constraining aftermarket service capacity expansion.
- Legacy fleet integration friction:Retrofitting ADAS onto existing motorcycles without CAN bus architecture demands workaround wiring harnesses that complicate warranty and liability positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Motorcycle ADAS Market |
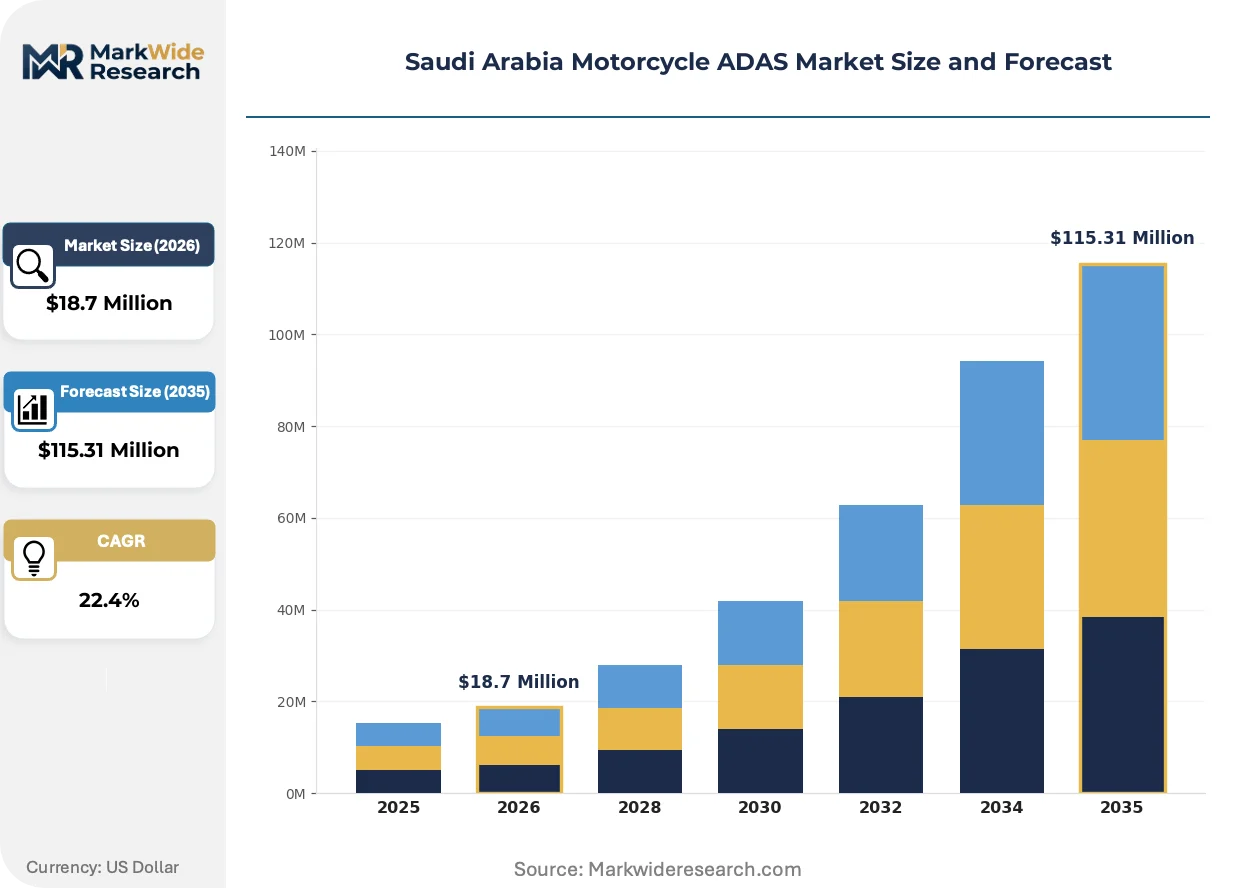
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $115.31 Million |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Cruise Control, Collision Avoidance System, Lane Departure Warning, Blind Spot Detection Technology: Radar-Based, Camera-Based, Lidar Systems, Ultrasonic Sensors End User: Private Riders, Fleet Operators, Law Enforcement, Emergency Services Installation: Factory Installed, Aftermarket, Retrofitted, OEM Solutions |
| Companies Covered | Honda Motor Co. Ltd., BMW Motorrad, Continental AG, TVS Motor Co., Garmin Ltd., Robert Bosch GmbH, Bosch Mobility Solutions, Ducati Motor Holding S.P.A, ZF Friedrichshafen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Motorcycle ADAS Market Trends and Innovations
Sensor fusion architectures and regulatory pressure are converging to push motorcycle ADAS from aftermarket add-ons to factory-integrated standard equipment, compressing the value chain and redefining competitive differentiation.
Edge-based processing is decentralizing computational load from centralized ECUs to distributed sensor modules. Premium motorcycle OEMs are adopting this architecture to reduce wiring complexity and enable over-the-air calibration updates. The shift is compressing aftermarket margins by locking functionality behind proprietary diagnostic tools.
SASO's adoption of United Nations ECE framework provisions is mandating specific test protocols for motorcycle blind spot detection and lane support systems. Manufacturers must now submit lean-angle performance data under standardized conditions. The requirement is accelerating investment in Saudi-based homologation facilities and technical partnerships with European certification bodies.
Fleet procurement is consolidating around outcome-based safety metrics rather than equipment specifications. Large delivery operators in Riyadh are contracting for accident-rate reductions and insurance premium guarantees, transferring performance risk to ADAS suppliers and system integrators. This shift is most visible in last-mile logistics verticals where liability exposure concentrates.
Saudi Arabia Motorcycle ADAS Market Segmentation
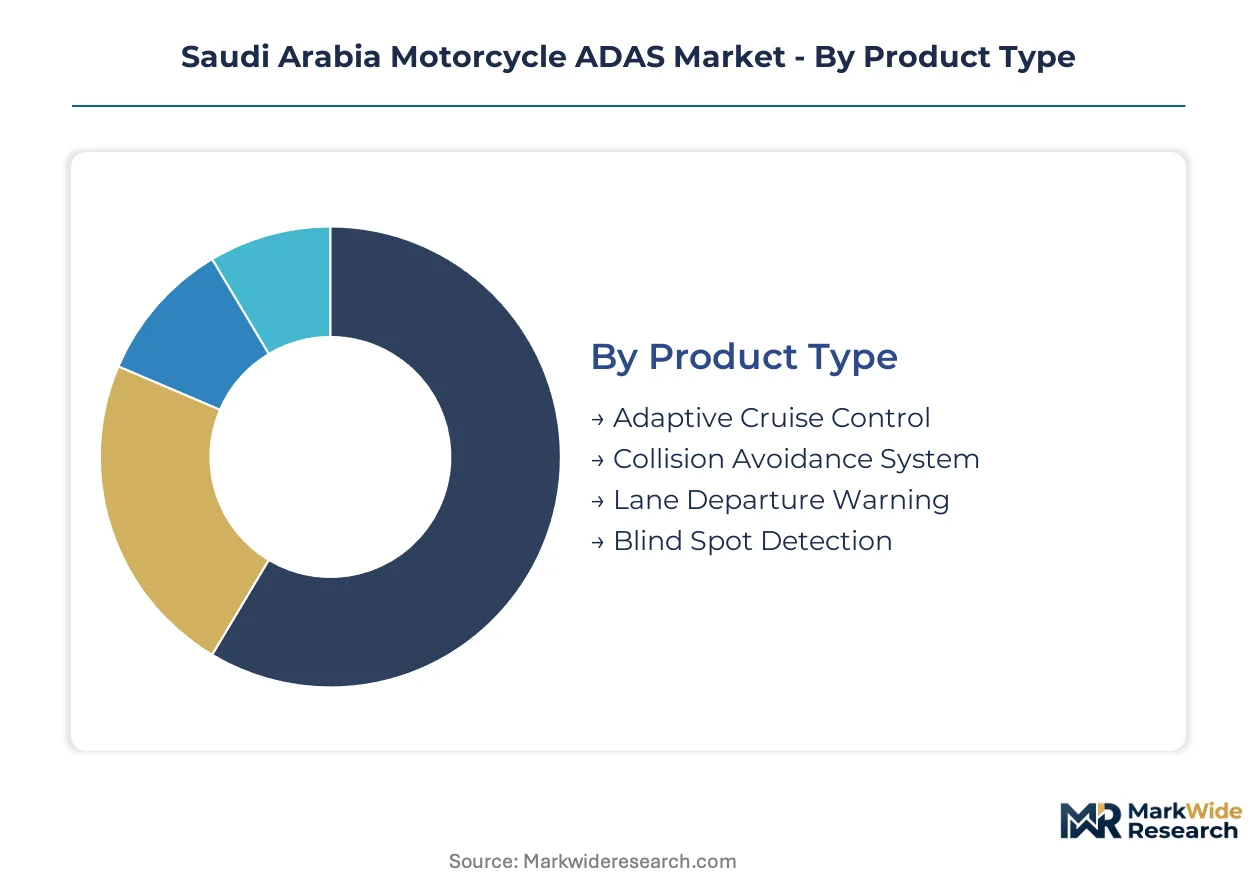
Motorcycle ADAS segmentation in Saudi Arabia reflects a bifurcation between compliance-driven fleet procurement and premium private rider expectations. Technology choices cascade through installation channels, end-user risk profiles, and SASO certification pathways.
Product Type:
Volume concentrates in entry-level warning systems while premium margins accrue to integrated control functions.
- Adaptive Cruise Control:Radar-enabled speed modulation maintains safe following distances during highway transit between Riyadh and Dammam logistics corridors. Fleet operators in long-haul commercial segments specify this function for driver fatigue reduction and fuel efficiency gains.
- Collision Avoidance System:Sensor fusion platforms combining millimeter-wave radar with camera vision execute emergency braking interventions calibrated for motorcycle lean angles. Demand clusters with premium OEM factory installations where dynamometer validation ensures insurer recognition.
- Lane Departure Warning:Camera-based edge detection alerts riders to unintended drift during high-speed highway segments.
- Blind Spot Detection:Ultrasonic and radar rear-quarter monitoring addresses the most common collision scenario in urban Jeddah traffic.
Mature deployment sits with Blind Spot Detection. Newer deployment is concentrated in Adaptive Cruise Control.
Technology:
Cost tiers separate proven sensing modalities from emerging platforms still seeking volume scale.
- Camera-Based:Computer vision processors analyze lane markings, traffic signs, and surrounding vehicle positions using single or stereo camera arrays. The technology dominates aftermarket channels serving Riyadh and Jeddah private riders due to lower unit costs and simplified calibration requirements.
- Radar-Based:Millimeter-wave sensors penetrate dust, rain, and glare conditions common to Eastern Province desert highways. Factory-installed configurations command premium positioning through OEM partnerships with European and Japanese motorcycle brands.
- Lidar Systems:Solid-state laser scanning delivers centimeter-range precision for advanced rider assistance prototyping.
- Ultrasonic Sensors:Short-range acoustic detection fills near-field coverage gaps in parking and low-speed maneuvering scenarios.
Camera-Based systems anchor current volume. Radar-Based platforms are climbing the fastest as SASO mandates tighten.
End User:
Application context dictates performance requirements and procurement authority structures.
- Fleet Operators:Commercial delivery and logistics companies in Riyadh and Jeddah standardize on blind spot detection and collision warning bundles to satisfy General Authority for Transport inspection protocols and secure insurance premium discounts. Procurement decisions centralize through fleet management departments with outcome-based safety contracts.
- Private Riders:Individual owners of premium motorcycles in urban centers seek factory-integrated ADAS for technology differentiation and resale value protection. Purchase decisions emphasize brand prestige and over-the-air update capability.
- Law Enforcement:Traffic police motorcycle units require ruggedized systems with pursuit-grade reliability.
- Emergency Services:Medical response and fire department two-wheeler fleets prioritize collision avoidance during high-speed urban navigation.
Fleet Operators drive standardization. Private Riders concentrate feature innovation pull.
Installation:
Channel structure determines calibration fidelity, warranty coverage, and regulatory recognition eligibility.
- Factory Installed:OEM-integrated systems undergo dynamometer validation and lean-angle compensation tuning during production. SASO certification attaches to the complete vehicle, streamlining registration and inspection processes for Riyadh-based premium motorcycle distributors.
- Aftermarket:Dealer-fitted solutions serve the largest addressable base of existing motorcycles without factory ADAS capability. Technical calibration limitations produce performance variance that undermines insurer incentive program eligibility.
- Retrofitted:Standalone sensor packages adapt to legacy motorcycles lacking CAN bus architecture through workaround wiring harnesses.
- OEM Solutions:Tier-1 supplier direct partnerships with motorcycle manufacturers enable proprietary sensor fusion platforms.
Aftermarket channels address volume. Factory Installed configurations capture margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet procurement concentrates in Riyadh and Jeddah, where logistics operators and premium motorcycle distributors cluster around major transport corridors. SASO regulatory harmonization is accelerating certification investments across sub-regional markets.
Riyadh
Central Region logistics hubs generate the strongest fleet operator demand for blind spot detection and collision warning bundles. SASO technical regulations mandate factory-grade calibration standards for commercial vehicle registrations. Dammam-Riyadh highway corridors anchor long-haul adaptive cruise control deployments for fatigue reduction.
Eastern Province
Dammam and Khobar logistics corridors remain underpenetrated relative to Riyadh, offering expansion opportunities for regional service networks. The General Authority for Transport coordinates with insurers to link premium discounts to verified ADAS installations. Petrochemical industry fleet operators in Jubail Industrial City are standardizing on radar-based systems for desert highway transit.
Western Region
Jeddah's dense urban traffic patterns drive aftermarket camera-based system adoption among private riders. The Saudi Traffic Department enforces commercial fleet inspection protocols that incentivize retrofitting. Mecca-Taif mountain routes concentrate premium motorcycle sales where lean-angle compensation algorithms prove critical.
NEOM Northwest
Smart city infrastructure investments are embedding connected vehicle standards that favor integrated sensor fusion platforms. NEOM regulatory frameworks reference United Nations ECE provisions for autonomous vehicle readiness. Testbed corridors between Oxagon and THE LINE are validating motorcycle-specific ADAS performance under extreme climate conditions.
Saudi Arabia Motorcycle ADAS Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aftermarket retrofit opportunities through simplified calibration protocols. Market structure bifurcates between OEM-integrated factory systems and dealer-fitted aftermarket solutions. Tier-1 automotive suppliers anchor premium positioning through radar-based portfolios, while motorcycle specialists compete on lean-angle algorithm differentiation. Dominant competitive moves include strategic partnerships with European certification bodies and geographic expansion into Eastern Province service networks.
Among Germany-based fabricators, Continental AG and Robert Bosch GmbH exemplify the tier-1 automotive supplier archetype, anchoring OEM partnerships through integrated sensor fusion platforms. TVS Motor Co. occupies a position within the motorcycle-native specialist tier, representing factory-installed ADAS accessibility for regional mid-market segments. Bosch Mobility Solutions sits within the same corporate structure as Robert Bosch GmbH, illustrating how established automotive players are carving dedicated mobility units to address two-wheeler dynamics.
| Leading Market Players |
|---|
| Honda Motor Co. Ltd. |
| BMW Motorrad |
| Continental AG |
| TVS Motor Co. |
| Garmin Ltd. |
| Robert Bosch GmbH |
| Bosch Mobility Solutions |
| Ducati Motor Holding S.P.A |
| ZF Friedrichshafen AG |
| Others |
Pricing and Supply Chain Analysis
Specialized radar calibration technician scarcity in Riyadh and Jeddah compresses aftermarket service capacity, widening labor-cost differentials between factory-integrated and dealer-fitted installations across premium, standard, and economy pricing tiers.
Pricing Analysis
Volume concentrates in aftermarket camera-based systems while margins accrue to factory-installed radar configurations. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated bundles with SASO certification from dealer-fitted solutions with calibration limitations. Price differentiation rests on certification grade and dynamometer validation status. Cost compression in the aftermarket tier is intensifying because telematics-only substitutes delay ADAS adoption among price-driven fleet operators. Fleet procurement departments exhibit highest price sensitivity; premium private riders in Jeddah and Riyadh show least.
Supply Chain Analysis
Single-source vulnerability sits with millimeter-wave radar sensor chip fabrication concentrating in Taiwan, South Korea, and Japan. The supply chain draws from East Asian foundries for radar chipsets, European tier-1 suppliers for sensor fusion software, and domestic Saudi distributors for final-mile logistics. Raw material dependencies center on silicon wafers, automotive-grade radar substrates, and CAN bus wiring harnesses. Tariff exposure on semiconductor imports constrains distributor margin flexibility. Distribution runs through OEM direct channels for factory installations and authorized dealer networks for aftermarket fitment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: specialized technician scarcity props pricing power for certified installation providers while constraining aftermarket expansion velocity.
For Market Incumbents: Anticipate SASO's accelerated ECE harmonization compressing certification timelines by pre-integrating sensor fusion platforms at the factory level. Anchor OEM partnerships with European and Japanese motorcycle brands to lock in proprietary diagnostic tool ecosystems. Defend against emerging camera-only retrofit specialists by deepening backward integration into radar calibration training programs within Saudi technical institutes. For New Entrants and Emerging Players: Eastern Province commercial fleet operators represent the most penetrable buyer archetype currently underserved by Riyadh-centric service networks. Target Dammam and Khobar logistics corridors with mobile calibration units addressing petrochemical industry fleet procurement. Pursue insurance-linked incentive program eligibility as the primary go-to-market credential. For Investors and Strategic Acquirers: The window for entry favors regional aftermarket service networks with SASO certification pathways already initiated. Long-term viability hinges on technician training infrastructure capable of scaling across the Kingdom's dispersed fleet operator base. Monitor General Authority for Transport premium discount framework expansion as the signal indicating regulatory pull timing for compliant system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Homologation Facility Investment | SASO's ECE adoption accelerates demand for Saudi-based lean-angle validation testing capacity. |
| Radar Calibration Training Program | Specialized technician pipelines address the binding constraint on aftermarket service network expansion. |
| Insurance Partnership Structuring | General Authority for Transport coordination creates direct economic pull for verified installations. |
| Eastern Province Service Network | Dammam and Khobar logistics corridors offer first-mover positioning with lower competitive density. |
| Sensor Fusion Platform Integration | Camera-radar convergence reduces unit costs while expanding functional coverage to desert highway conditions. |
Research Methodology
Regulatory filing databases, automotive production statistics, and commercial fleet procurement records formed the secondary backbone. Primary interviews with SASO certification officers, Tier 1 supplier platform engineers, aftermarket distributor operations heads, and fleet procurement managers at Riyadh logistics operators supplied demand-side validation. Bottom-up and top-down triangulation cross-checked volume estimates against insurance-linked incentive program enrollment data and vehicle registration flows through the Saudi Traffic Department.
Bottom-up modeling built from individual product type adoption curves, technology cost trajectories, and end-user segment procurement patterns across the projection horizon. Segmentation dimensions included installation channel, technology modality, and fleet operator versus private rider application context. CAGRs were derived from logistic diffusion curves fitted to regulatory mandate implementation timelines and insurance discount program expansion rates. Forecast inputs incorporated SASO technical regulation adoption schedules and lean-angle algorithm performance benchmarking data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply normalization and technician training program scale-up velocity. Forecasts reflect assumptions around regulatory harmonization pace and fleet operator liability cost trajectories without guaranteed timeline alignment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle ADAS Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Mountain Bike Suspension Market
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
Asia-Pacific Ride on Bikes Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Bicycle Crank Motor Market