
 China Motorcycle ADAS Market | 2026-2036
China Motorcycle ADAS Market Size, Share, and Industry Trends Forecast 2026-2036
China Motorcycle ADAS Market Insights
Embedded software engineering talent is rotating from consumer electronics into automotive-tier suppliers, easing firmware bottlenecks that had constrained motorcycle ADAS rollout. Robert Bosch GmbH leverages its ABS-to-ADAS module pipeline to dominate safety system integration for domestic OEMs. Continental AG anchors high-volume radar sensor production through its Shanghai engineering center. Beijing West Industries (BWI) Group competes on cost-optimized camera systems tailored to electric motorcycle platforms.
China Motorcycle ADAS comprises sensor fusion, electronic control units, and algorithmic decision layers engineered to detect road hazards, monitor rider behavior, and execute automated interventions at speeds below 120 km/h. Camera systems lead technology adoption due to lower unit costs and mature supply chains, while radar sensors represent the fastest-expanding segment as all-weather reliability becomes mandatory for premium sport motorcycles. Collision avoidance commands the largest application share among fleet operators, whereas adaptive cruise control generates higher margins in the touring bike product category.
MIIT mandates connected-vehicle data security compliance for all ADAS-equipped motorcycles sold in China, while SAMR enforces GB standard conformity assessment on sensor hardware. NMPA registration requirements for optical and radar devices create entry barriers for unqualified aftermarket providers. Stakeholders must monitor how China's dual carbon goals reshape electrification timelines and whether GB standards will harmonize with UN ECE regulations to enable export-oriented production.
Market Dynamics
GB standards for vehicle active safety are tightening compliance thresholds faster than domestic suppliers can certify, creating a certification bottleneck that favors established tier-one integrators with existing NMPA registrations.
Growth Catalysts
- MIIT connected-vehicle mandates:Data security compliance requirements for all ADAS-equipped motorcycles are forcing OEMs to source only from registered domestic suppliers, accelerating formal market development.
- Yangtze River Delta cluster effects:Co-location of tier-one sensor suppliers with motorcycle assembly plants reduces logistics costs and enables just-in-time firmware updates.
- Electric motorcycle platforms:Native 48V electrical architectures on premium electric models eliminate power constraints that limited ADAS deployment on internal combustion engines.
Market Restraints
- Radar sensor import dependency:77GHz mmWave radar modules remain concentrated among German and Japanese suppliers, exposing domestic assemblers to currency volatility and lead time extension.
- SAMR conformity assessment backlog:Optical device certification queues at NMPA-authorized test labs now exceed eight months, delaying product launches for unregistered aftermarket entrants.
- Lidar cost floor:Solid-state lidar units remain priced above viable thresholds for sub-250cc motorcycle segments, capping addressable volume.
Strategic Opportunities
- Southwestern China manufacturing expansion:Chongqing and Chengdu motorcycle hubs lack localized ADAS engineering presence, creating first-mover advantage for technical service partnerships.
- Camera-radar fusion algorithms:Deep learning models trained on Chinese road conditions offer performance advantages over adapted European systems in low-visibility scenarios.
- Fleet operator direct procurement:Food delivery and logistics platforms are bypassing OEM channels to specify ADAS configurations at contract manufacturing partners.
Industry Challenges
- Embedded firmware engineering scarcity:Talent migration from consumer electronics has eased entry-level shortages but left deficits in automotive-grade validation and ISO 26262 functional safety expertise.
- Dual carbon timeline compression:MIIT electrification mandates are accelerating platform redesign cycles, forcing ADAS suppliers to revalidate sensor mounting and thermal management on new electric architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Motorcycle ADAS Market |
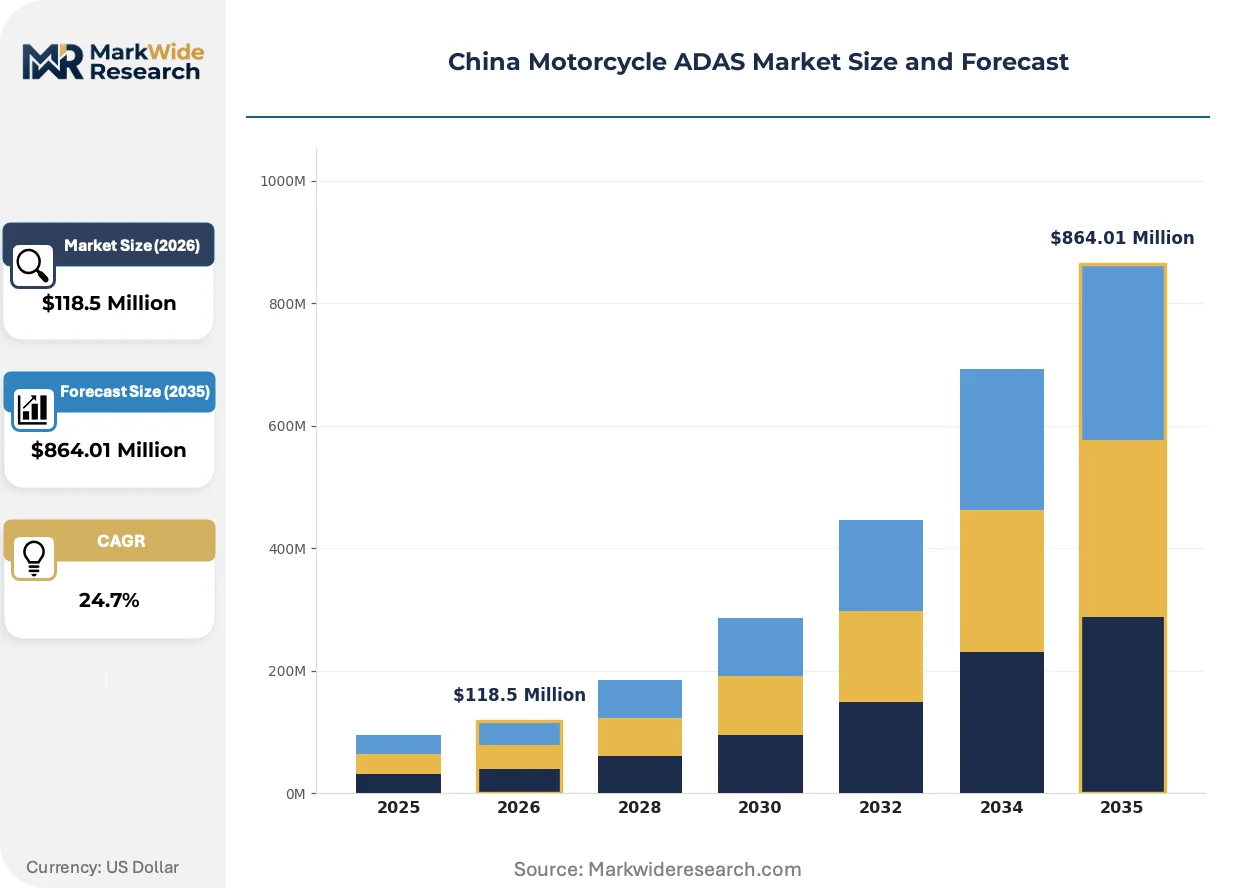
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $864.01 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Camera Systems, Radar Sensors, Lidar, Ultrasonic Sensors Application: Collision Avoidance, Lane Departure Warning, Adaptive Cruise Control, Blind Spot Detection End User: OEMs, Aftermarket Providers, Custom Builders, Fleet Operators Product Type: Standard Motorcycles, Electric Motorcycles, Touring Bikes, Sport Motorcycles |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Beijing West Industries (BWI) Group, Denso Corporation, BMW Motorrad, Ducati Motor Holding S.P.A., Garmin Ltd., Kawasaki Heavy Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Motorcycle ADAS Market Trends and Innovations
Sensor technology roadmaps are diverging sharply between cost-optimized mass-market systems and premium all-weather configurations, while regulatory data localization requirements reshape supplier qualification protocols.
Camera-based ADAS is bifurcating into single-lane departure warning systems for economy commuters and multi-camera surround-view configurations for touring motorcycles. Domestic OEMs in the 150-250cc segment are adopting the former to meet minimum GB standard compliance without margin erosion. Premium sport bike manufacturers are compressing radar dependency by deploying stereo camera arrays with neural network depth estimation.
MIIT data security regulations now require all connected ADAS systems to store telemetry within mainland China and undergo cybersecurity certification before NMPA device registration. This industrial consequence has disqualified several European telematics providers from qualified supplier lists. Domestic OEMs are responding by qualifying local cloud infrastructure partners and redesigning over-the-air update architectures.
Fleet procurement contracts now specify ADAS performance metrics tied to insurance premium reductions rather than hardware feature checklists. Delivery platform operators in Shanghai and Shenzhen are displacing traditional OEM sales channels by negotiating directly with tier-one suppliers for volume camera system integrations. This behavioral shift is most visible in the instant delivery vertical, where accident liability costs have exceeded hardware acquisition costs in total cost of ownership calculations.
China Motorcycle ADAS Market Segmentation
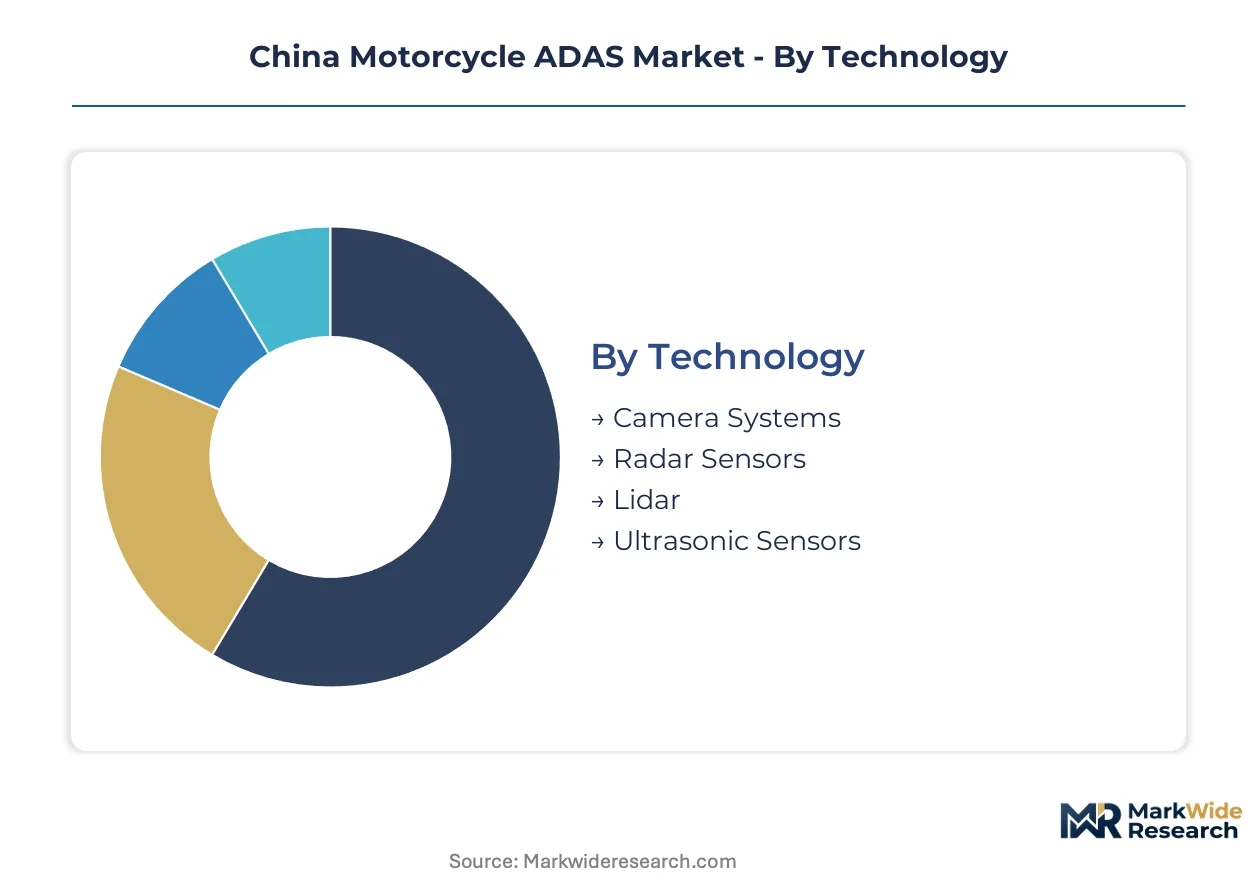
Technology and application boundaries in China's motorcycle ADAS market are blurring as sensor fusion becomes standard. Segmentation clarity determines supplier positioning against MIIT certification requirements and NMPA registration pathways.
Technology:
Camera systems face substitution pressure from radar-lidar fusion in premium tiers, while ultrasonic sensors confront displacement by solid-state alternatives in cost-optimized segments.
- Camera Systems:Mono and stereo configurations process visual data through neural network pipelines for lane marking recognition and obstacle classification. Demand concentrates in Jiangsu and Zhejiang provinces where tier-one integrators co-locate with electric motorcycle OEMs seeking GB standard compliance at minimum cost.
- Radar Sensors:77GHz mmWave modules deliver all-weather velocity and range detection independent of lighting conditions. Chongqing-based sport motorcycle manufacturers specify these for adaptive cruise control as rider expectations for premium safety features harden.
- Lidar:Solid-state units emit pulsed laser arrays for high-resolution 3D point cloud generation in urban collision avoidance scenarios.
- Ultrasonic Sensors:Short-range acoustic modules support parking assistance and low-speed maneuvering in dense traffic environments.
Camera systems anchor the volume base while radar sensors gain share at the steepest rate.
Application:
Collision avoidance commands the highest hardware expenditure per unit as fleet operators negotiate insurance-linked performance guarantees.
- Collision Avoidance:Forward-facing sensor arrays trigger automatic braking or throttle reduction when closing speeds exceed calibrated thresholds. Meituan and Ele.me delivery platforms in Shanghai mandate these systems for contract manufacturers supplying their rider fleets.
- Adaptive Cruise Control:Radar-camera fusion maintains following distances on highways without rider throttle intervention. Premium touring bike OEMs in the Yangtze River Delta bundle this capability to differentiate against Japanese imports.
- Lane Departure Warning:Camera-based edge detection alerts riders through handlebar vibration or dashboard indicators.
- Blind Spot Detection:Rear-mounted radar modules monitor adjacent traffic during lane changes on multi-lane expressways.
Collision avoidance dominates unit economics while adaptive cruise control expands most quickly in the premium touring segment.
End User:
Fleet procurement patterns are compressing traditional OEM channels as delivery platforms specify direct supplier relationships.
- OEMs:Domestic manufacturers integrate ADAS modules during platform design to satisfy MIIT connected-vehicle mandates and streamline NMPA registration.
- Fleet Operators:Logistics and food delivery platforms bypass retail channels to negotiate volume contracts with tier-one sensor suppliers.
- Aftermarket Providers:Independent installers serve existing motorcycle owners seeking retroactive GB standard compliance.
- Custom Builders:Specialty manufacturers tailor ADAS configurations for niche sport and touring applications.
OEMs retain the installed base while fleet operators are climbing the fastest as procurement channels.
Product Type:
Electric motorcycle architectures eliminate power constraints that previously limited ADAS deployment on internal combustion platforms.
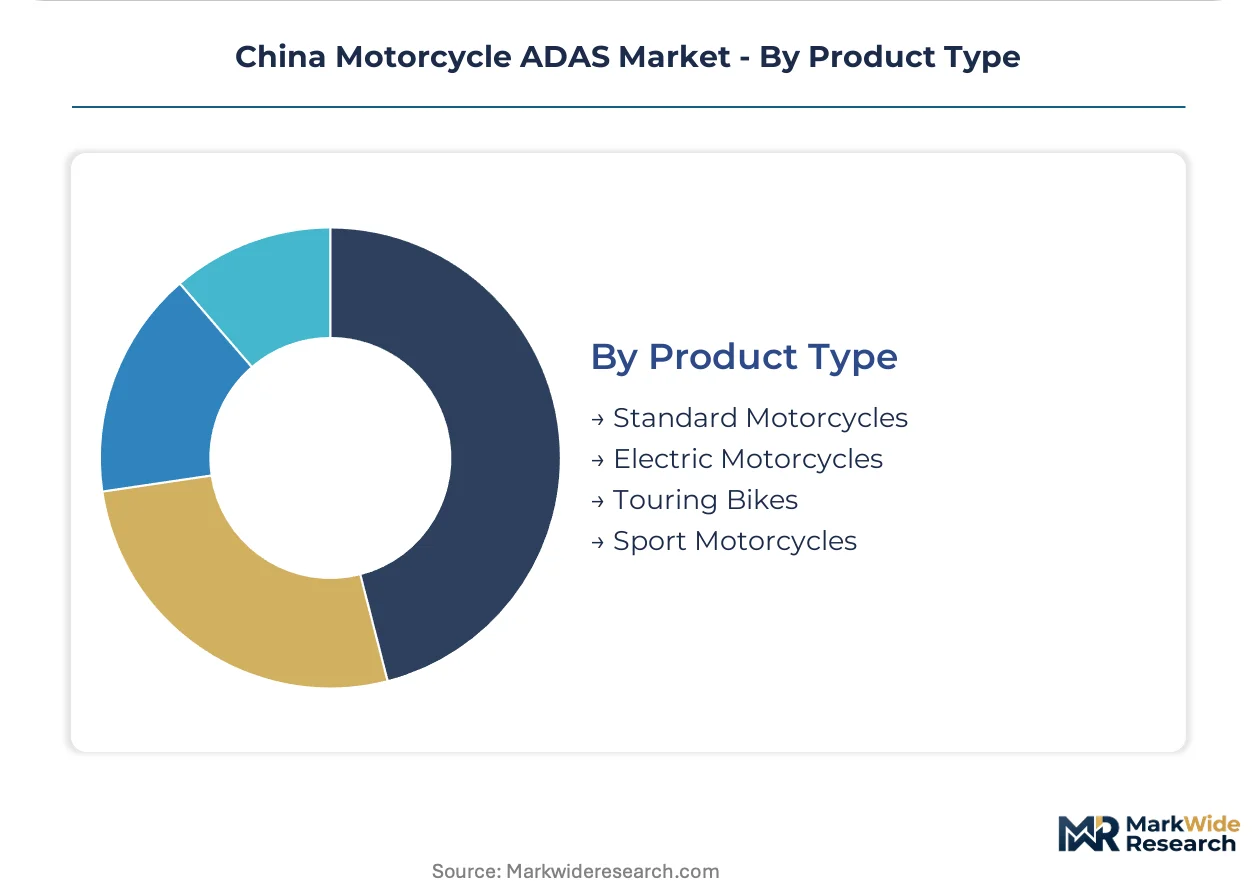
- Electric Motorcycles:Native 48V electrical systems support multi-sensor arrays without alternator capacity limitations. Manufacturers in Shenzhen and Hangzhou leverage this advantage to meet MIIT electrification timelines.
- Touring Bikes:Long-distance platforms prioritize adaptive cruise control and blind spot detection for highway safety. Premium specifications in this category generate the highest margins per ADAS unit.
- Standard Motorcycles:Economy commuter models adopt minimal camera-based lane departure warning to achieve baseline GB compliance.
- Sport Motorcycles:High-performance platforms integrate radar-dependent collision avoidance for track-day and canyon riding scenarios.
Standard motorcycles anchor the volume base while electric motorcycles gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's motorcycle ADAS consumption pattern diverges from Western markets where individual touring riders drive premium feature adoption. Chinese demand concentrates in fleet procurement channels for urban delivery platforms, with electrification timelines compressing deployment schedules beyond the pace seen in European or North American markets.
Yangtze River Delta
Shanghai and Hangzhou anchor the highest ADAS penetration rates as Meituan and Ele.me mandate collision avoidance systems for contract manufacturers. MIIT connected-vehicle data security regulations require localized cloud infrastructure, disqualifying several European telematics providers from supplier lists. Tier-one sensor integrators co-locate with electric motorcycle OEMs in Suzhou and Ningbo to enable just-in-time firmware updates.
Pearl River Delta
Shenzhen manufacturers leverage native 48V electrical architectures to support multi-sensor arrays without alternator constraints. SAMR conformity assessment backlogs at NMPA-authorized test labs now exceed eight months, delaying product launches for unregistered aftermarket entrants. Dongguan-based assembly plants specialize in camera-radar fusion modules for premium sport motorcycle exports.
Sichuan-Chongqing
Chongqing's sport motorcycle manufacturers specify 77GHz mmWave radar for adaptive cruise control as rider expectations for premium safety features harden. GB standards for vehicle active safety tighten compliance thresholds faster than domestic suppliers can certify, creating bottlenecks that favor established tier-one integrators. Chengdu lacks localized ADAS engineering presence, creating first-mover advantage for technical service partnerships.
Beijing-Tianjin-Hebei
Capital region fleet operators negotiate direct procurement contracts with tier-one suppliers, bypassing traditional OEM retail channels. NMPA registration requirements for optical and radar devices create entry barriers for unqualified aftermarket providers. Tianjin's port infrastructure handles imported 77GHz radar modules from German and Japanese suppliers, exposing domestic assemblers to currency volatility.
Shandong Peninsula
Jinan and Qingdao manufacturers focus on economy commuter models adopting minimal camera-based lane departure warning for baseline GB compliance. Dual carbon timeline compression from MIIT electrification mandates accelerates platform redesign cycles, forcing ADAS suppliers to revalidate sensor mounting on new electric architectures. Local suppliers compete on cost-optimized camera systems tailored to sub-250cc segments.
China Motorcycle ADAS Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in China's motorcycle ADAS market. The upper tier commands safety system integration contracts through existing NMPA registrations and ABS-to-ADAS module pipelines. Below them, cost-optimized camera specialists and radar-dependent premium configurators occupy distinct competitive positions. Consolidation pressure is mounting as certification bottlenecks favor incumbents with established test lab relationships and registered device portfolios.
Among German-anchored tier-one integrators, Continental AG and Robert Bosch GmbH exemplify the integrated leadership archetype through their ABS-to-ADAS module pipelines and Shanghai-based engineering centers. Beijing West Industries (BWI) Group occupies a position within the domestic cost-optimization tier, representing specialists in camera systems tailored to electric motorcycle platforms. These three companies illustrate the market's structural division between foreign-originated safety integration and locally-registered component supply.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Beijing West Industries (BWI) Group |
| Denso Corporation |
| BMW Motorrad |
| Ducati Motor Holding S.P.A. |
| Garmin Ltd. |
| Kawasaki Heavy Industries Limited |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Yangtze River Delta tier-one integrators and domestic electric motorcycle OEMs lock in multi-year sensor module commitments while insulating both parties from spot-market volatility in 77GHz radar components. These contractual structures simultaneously secure NMPA registration pathways and stabilize unit economics across electrification platform transitions mandated by MIIT dual carbon timelines.
Pricing Analysis
Project-based pricing dominates collision avoidance system procurement as Meituan and Ele.me negotiate volume guarantees with tier-one camera suppliers. Certification grade and volume scale drive price differentiation, with NMPA-registered optical devices commanding premiums over unregistered aftermarket alternatives. Cost compression in economy commuter segments is intensifying because Shandong Peninsula manufacturers compete on minimal lane departure warning configurations. Fleet operators exhibit the lowest price sensitivity due to insurance-linked total cost of ownership calculations, whereas aftermarket providers face acute margin pressure from SAMR conformity assessment backlogs.
Supply Chain Analysis
Germany and Japan anchor 77GHz mmWave radar module fabrication, while China dominates camera system assembly and ECU integration. The supply chain draws from imported radar chipsets, domestic lens optics, and Yangtze River Delta firmware engineering. Single-source vulnerability concentrates in German radar suppliers exposed to currency volatility and extended lead times. Distribution runs through tier-one integrators co-located with OEM assembly plants, bypassing traditional aftermarket channels for fleet-direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates multiple entry points as fleet procurement patterns displace traditional OEM channels and electrification mandates force platform redesign cycles. The divergence between cost-optimized mass-market systems and premium all-weather configurations generates distinct competitive arenas.
For Market Incumbents: Compound NMPA registration advantages by accelerating ABS-to-ADAS module pipeline extensions before SAMR conformity assessment backlogs ease. Deepen technical service partnerships in Chengdu and Chongqing to preempt Southwestern China manufacturing expansion by competitors. Certification bottlenecks favor established tier-one integrators with registered device portfolios and test lab relationships. For New Entrants and Emerging Players: Anchor in camera-radar fusion algorithm development trained on Chinese low-visibility road conditions, where adapted European systems underperform. Target the Sichuan-Chongqing sport motorcycle corridor for adaptive cruise control specifications as domestic manufacturers harden premium safety expectations. Pursue direct technical service partnerships with fleet operators bypassing OEM channels rather than competing for tier-one supplier status. For Investors and Strategic Acquirers: Capital is best deployed toward tier-one integrators with existing NMPA registrations and ABS module pipelines that can absorb camera-radar fusion capabilities through capability adjacencies. Long-term viability hinges on MIIT data security compliance infrastructure and electrification platform validation cycles. Monitor GB standard harmonization with UN ECE regulations as the signal indicating export-oriented production viability and valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Registration Acceleration | Early certification completion locks in qualified supplier status before SAMR backlog clearance widens competition. |
| Camera-Radar Fusion R&D | Deep learning models trained on Chinese road conditions outperform adapted European systems in low-visibility scenarios. |
| Southwestern China Technical Partnership | Chengdu and Chongqing manufacturing hubs lack localized ADAS engineering presence, creating first-mover positioning. |
| Fleet-Direct Procurement Channel | Meituan and Ele.me delivery platforms negotiate volume contracts bypassing traditional OEM retail structures. |
| 48V Architecture Sensor Validation | Native electric motorcycle electrical systems eliminate power constraints that limited ADAS on internal combustion platforms. |
Research Methodology
Initial hypotheses were tested against primary input from tier-one supplier procurement directors, OEM platform engineers, fleet operator safety managers, and NMPA regulatory affairs specialists and refined through secondary validation. Sources included MIIT connected-vehicle mandate documentation, SAMR GB standard conformity assessment records, NMPA device registration databases, and Yangtze River Delta industrial cluster trade data. Bottom-up sensor unit shipment estimates and top-down OEM platform adoption rates were triangulated to constrain variance.
Variance decomposition across technology, application, end user, and product type segments structured the analytical framework over the projection horizon. Motorcycle class, propulsion architecture, and regional manufacturing cluster density served as cross-cutting segmentation dimensions. CAGRs were derived from installed base penetration curves and replacement cycle assumptions, with electrification timeline compression and fleet procurement acceleration as industry-specific demand inputs.
Decision-makers should treat outputs as directional under assumptions of sustained MIIT electrification mandates and NMPA registration pathway stability; material deviation in GB standard harmonization progress or radar import dependency resolution would warrant model refresh. Specific risks include SAMR conformity assessment queue duration volatility and dual carbon timeline acceleration compressing platform redesign cycles. Recalibration cycles align with material shifts in fleet procurement contract structures and GB standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Italy E-Bike Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
Motorcycle Suspension System Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Motorcycle Hub Motor Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Cargo Bicycles Market