
 Americas Container Technology Market | 2026-2036
Americas Container Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Container Technology Market Analysis
The U.S. EPA emissions standards for port operations and maritime transport is consolidating demand for container technologies that optimize cargo consolidation and reduce idle vessel time. Docker Inc leverages its open-source ecosystem to sustain developer mindshare across North and South American enterprises. Red Hat Inc anchors enterprise Kubernetes adoption through its OpenShift platform, while Amazon Web Services competes with managed container services that extend cloud-native infrastructure to logistics hubs.
Americas Container Technology encompasses standardized intermodal freight units—typically constructed from corten steel with weather-resistant coatings and corner castings engineered for stacking loads exceeding 190 metric tons—designed to enable seamless transfer between ship, rail, and truck without cargo handling. Refrigerated containers command premium positioning due to pharmaceutical cold-chain requirements and perishable agricultural exports from Chile and Mexico, while tank containers serving chemical and liquid bulk transport represent the fastest-expanding product category. Steel construction dominates unit economics across shipping and intermodal transport applications, though aluminum variants gain traction in weight-sensitive air cargo and last-mile logistics segments where fuel efficiency directly impacts operator margins.
The U.S. Coast Guard and Transport Canada enforce structural integrity and hazardous materials containment standards that shape container design specifications and certification requirements for cross-border trade. Brazil's ANTT and Mexico's SCT regulate domestic intermodal operations, creating compliance layers that favor vendors with established regional certification expertise. Stakeholders must monitor divergence between U.S. OSHA workplace safety mandates and emerging Latin American digital freight platform regulations, as compliance fragmentation will determine which technology architectures achieve scalable deployment across the hemisphere's logistics corridors.
Market Dynamics
Data sovereignty mandates under Brazil's LGPD and evolving U.S. state privacy laws are forcing financial services firms to re-architect containerized workloads around jurisdictional boundaries, creating fragmented deployment patterns across São Paulo and New York metro corridors.
Growth Catalysts
- Port Emissions Compliance:The U.S. EPA standards for maritime transport operations are consolidating procurement around container technologies that optimize cargo consolidation and minimize idle vessel time in coastal logistics hubs.
- Cold-Chain Pharmaceutical Demand:Temperature-controlled container deployments are accelerating across Chile and Mexico to serve perishable agricultural export corridors and biologics distribution networks.
- São Paulo Logistics Digitization:Brazil's port modernization programs and ANTT regulatory frameworks are driving smart container tracking system adoption through state-level infrastructure investments.
Market Restraints
- Corten Steel Price Volatility:Raw material input costs for weather-resistant container construction fluctuate with global steel markets, compressing margins for manufacturers without backward integration into metallurgical supply.
- Cross-Border Certification Friction:Divergent structural integrity standards between the U.S. Coast Guard and Transport Canada create compliance layering costs for intermodal operators serving North American trade corridors.
- Aluminum Substitution Ceiling:Weight-sensitive air cargo segments face technical limitations where aluminum container variants cannot match corten steel load-bearing specifications for heavy freight categories.
Strategic Opportunities
- Mexico SCT Regulatory Tailwind:Mexico's domestic intermodal regulatory evolution creates first-mover positioning for vendors with established certification expertise in Latin American digital freight platforms.
- Tank Container White Space:Chemical and liquid bulk transport applications represent underpenetrated demand relative to dry container saturation, with specialized certification requirements limiting competitive entry.
- Edge-Cloud Convergence:Integration of container orchestration with distributed logistics node computing enables real-time cargo monitoring across Brazil's interior highway networks beyond port-centric deployments.
Industry Challenges
- Kubernetes Talent Scarcity:Enterprise container platform operations require specialized DevOps skill sets that remain concentrated in São Paulo and U.S. coastal technology corridors, limiting deployment velocity in secondary markets.
- Legacy System Integration Complexity:Mainframe-based customs and port management systems in established Latin American trade hubs create middleware friction for API-native container tracking implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Container Technology Market |
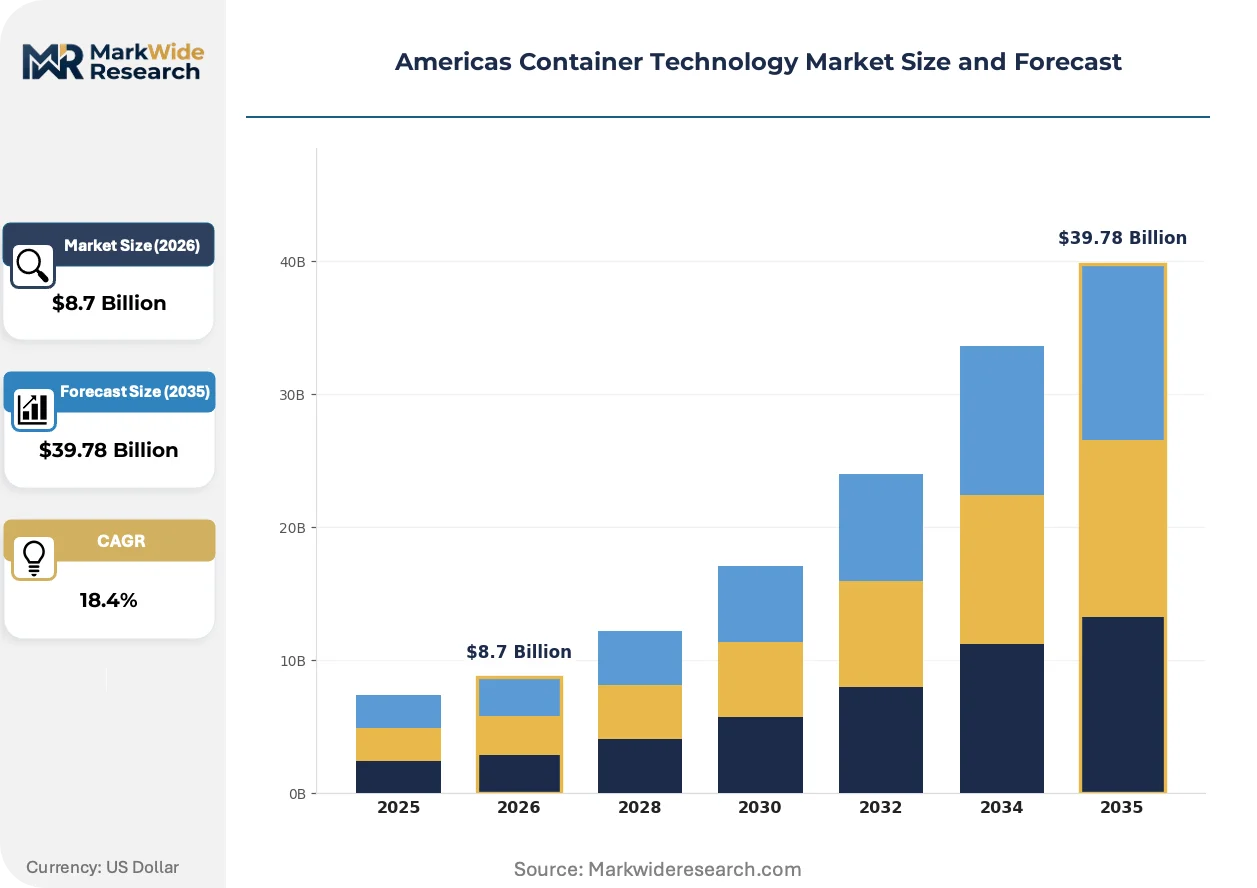
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ISO Containers, Refrigerated Containers, Tank Containers, Collapsible Containers Application: Shipping, Logistics, Storage, Intermodal Transport End User: Manufacturers, Retailers, Distributors, Freight Forwarders Material: Steel, Aluminum, Fiberglass, Composite |
| Companies Covered | Docker Inc, Red Hat Inc, VMware Inc, IBM Corporation, Microsoft Corporation, Amazon Web Services, Google LLC, Oracle Corporation, Rancher Labs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Container Technology Market Emerging Trajectories
Container technology architectures across the Americas are pivoting from static asset tracking toward dynamic workload orchestration, with regulatory pressure and edge computing capabilities jointly reshaping vendor competitive positioning.
Refrigerated container units with integrated IoT sensor arrays are absorbing pharmaceutical cold-chain validation requirements that previously demanded separate monitoring infrastructure. Biologics distributors in Chile and Mexico are adopting these consolidated platforms at accelerated procurement cycles. The technology is absorbing compliance documentation burdens that formerly required parallel quality management systems.
Brazil's ANTT and Mexico's SCT are converging domestic intermodal regulations toward digital freight platform mandates that mirror U.S. EPA emissions transparency requirements. This regulatory alignment is compressing certification timelines for cross-border operators. Tank container segments serving chemical transport are responding with preemptive IoT telemetry investments to satisfy emerging audit trail standards.
Buyers in financial services and pharmaceutical verticals are consolidating vendor relationships around managed container service contracts that bundle infrastructure with compliance attestation. Traditional equipment-leasing channels face displacement from outcome-based agreements where uptime and data sovereignty guarantees replace capital expenditure models. São Paulo state enterprises exhibit the most pronounced procurement consolidation, driven by LGPD enforcement timelines.
Americas Container Technology Market Segmentation
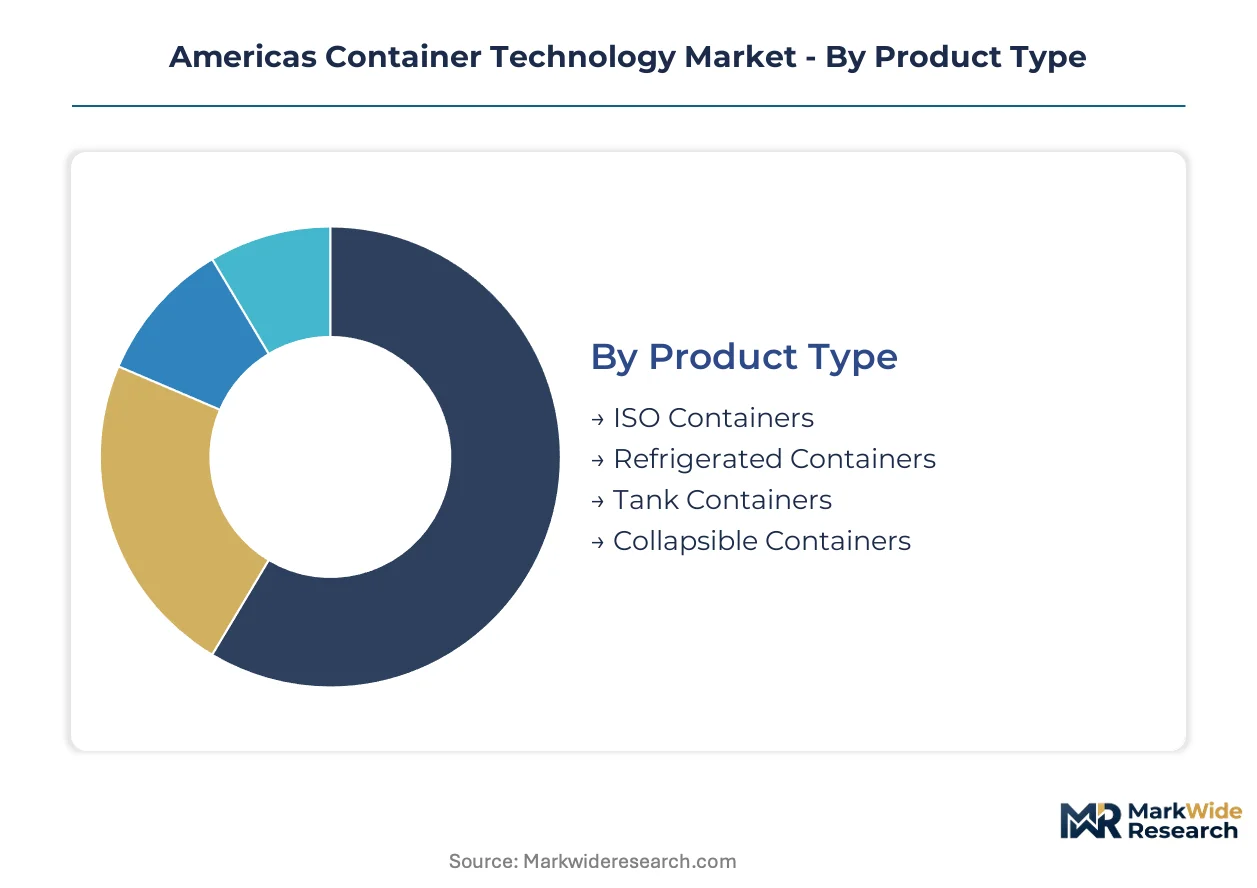
Container technology procurement patterns diverge sharply across product specifications and operational use cases. Understanding these fault lines reveals where vendor capabilities align with buyer compliance burdens and infrastructure investment cycles.
Product Type:
Supply concentration in corten steel manufacturing favors established producers with backward integration into metallurgical sourcing.
- ISO Containers:Standardized 20-foot and 40-foot units constructed from weather-resistant corten steel with corner castings rated for stacking loads exceeding 190 metric tons. Demand concentrates in São Paulo state port modernization programs where ANTT-mandated digital freight tracking requires standardized telemetry mounting points.
- Refrigerated Containers:Temperature-controlled units with integrated compressor systems and IoT sensor arrays designed for pharmaceutical cold-chain validation. Chilean biologics distributors and Mexican perishable agricultural exporters drive procurement concentration as these units absorb compliance documentation burdens formerly requiring parallel quality management systems.
- Tank Containers:Specialized pressure vessels for chemical and liquid bulk transport with hazardous materials certification frameworks.
- Collapsible Containers:Foldable steel or aluminum variants designed for empty return optimization in last-mile logistics networks.
ISO containers absorb the bulk of installed capacity; tank containers are expanding most quickly due to underpenetrated demand in chemical transport segments.
Application:
Cost tier differentiation separates capital-intensive port infrastructure from asset-light logistics orchestration platforms.
- Shipping:Deep-sea vessel loading operations requiring structural certification under U.S. Coast Guard and Transport Canada cross-border standards. New York and São Paulo financial services firms expanding containerized workload deployments for data sovereignty compliance generate indirect demand through freight forwarding consolidation.
- Logistics:Third-party coordination of multimodal cargo movements with real-time tracking integration. Brazil's interior highway networks beyond port-centric deployments drive edge-cloud convergence investments for distributed node computing.
- Storage:Static depot and warehouse container utilization for inventory staging.
- Intermodal Transport:Seamless rail-truck-ship transfer operations governed by domestic regulatory frameworks.
Shipping absorbs the bulk of installed capacity; logistics is expanding most quickly as digital freight platform mandates compress procurement cycles.
End User:
Volume concentration varies by customer type, with enterprise-scale buyers commanding outcome-based service contracts.
- Manufacturers:Industrial producers of automotive, electronics, and consumer goods requiring inbound component and outbound finished goods containerization. Mexico's SCT regulatory evolution favors vendors with established certification expertise in Latin American digital freight platforms.
- Retailers:Omnichannel distributors consolidating inventory flows through regional distribution centers. São Paulo state enterprises exhibit pronounced procurement consolidation driven by LGPD enforcement timelines and data sovereignty re-architecture requirements.
- Distributors:Intermediate wholesalers managing fragmented supplier networks.
- Freight Forwarders:Intermediary operators coordinating cross-border documentation and customs clearance.
Manufacturers absorb the bulk of installed capacity; retailers are expanding most quickly through managed container service contracts bundling infrastructure with compliance attestation.
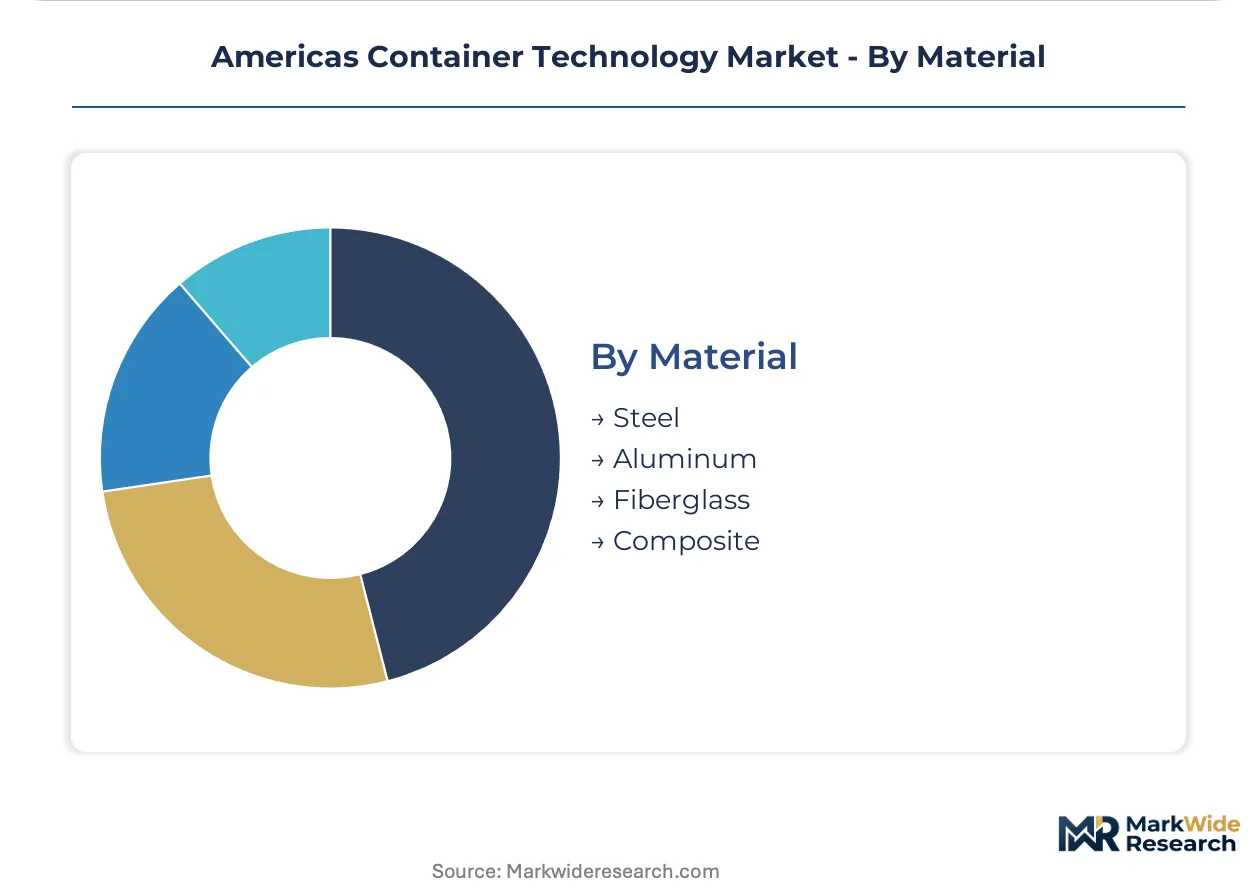
Material:
Margin structures diverge between commodity steel production and specialty lightweight alloys.
- Steel:Corten and carbon steel variants dominating unit economics across shipping and intermodal applications. Raw material input cost volatility compresses margins for manufacturers without upstream control over metallurgical supply chains.
- Aluminum:Weight-sensitive alloys gaining traction in air cargo and last-mile logistics where fuel efficiency directly impacts operator margins. Technical limitations prevent aluminum variants from matching corten steel load-bearing specifications for heavy freight categories.
- Fiberglass:Corrosion-resistant composite panels for specialized chemical and pharmaceutical containment.
- Composite:Hybrid material constructions combining structural polymers with metal reinforcement.
Steel absorbs the bulk of installed capacity; aluminum is expanding most quickly in weight-sensitive air cargo segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors container technology deployment across the Americas, with the Brazilian state's port modernization and ANTT regulatory frameworks driving smart tracking system investments that exceed activity in other regional corridors.
United States
New York metro financial services firms are re-architecting containerized workloads to satisfy evolving state privacy mandates and data sovereignty requirements. The EPA emissions standards for maritime transport operations are consolidating procurement around cargo consolidation technologies that minimize idle vessel time in coastal logistics hubs. Los Angeles-Long Beach port operators are deploying edge-cloud convergence systems for real-time cargo monitoring.
Brazil
São Paulo state enterprises exhibit pronounced procurement consolidation driven by LGPD enforcement timelines and logistics digitization investments. ANTT regulatory frameworks mandate digital freight platform integration across domestic intermodal operations. Port modernization programs in Santos and Paranaguá are accelerating smart container tracking adoption through state-level infrastructure allocations.
Mexico
SCT regulatory evolution is creating first-mover positioning for vendors with established certification expertise in Latin American digital freight platforms. Perishable agricultural exporters in Sinaloa and Jalisco are driving refrigerated container deployments with integrated IoT sensor arrays. Mexico City metro manufacturers are consolidating vendor relationships around managed container service contracts.
Chile
Biologics distributors in Santiago and Valparaíso are adopting temperature-controlled container platforms at accelerated procurement cycles. Cold-chain pharmaceutical demand is absorbing compliance documentation burdens that formerly required parallel quality management systems. Port operators in San Antonio are responding to EPA-aligned emissions transparency requirements with preemptive telemetry investments.
Canada
Transport Canada structural integrity standards are shaping container design specifications for cross-border trade with the United States. Vancouver port operators are consolidating demand around technologies that optimize cargo consolidation under federal maritime emissions guidelines. Toronto financial services firms are expanding containerized workload deployments to meet provincial privacy framework requirements.
Americas Container Technology Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the managed service and compliance-attestation dimension, with outcome-based contracts displacing traditional equipment-leasing channels. The vendor base organizes into three tiers: cloud-native infrastructure providers anchoring enterprise Kubernetes adoption, open-source ecosystem sustainers capturing developer mindshare, and specialized logistics technology vendors with regional certification expertise. Dominant competitive moves include strategic partnerships bundling infrastructure with compliance guarantees and geographic expansion into São Paulo and Mexico City corridors.
Within the cloud-native infrastructure tier, Amazon Web Services and Microsoft Corporation occupy positions as scale-driven platform providers, while Docker Inc exemplifies the open-source ecosystem archetype sustaining developer adoption across North and South American enterprises. Red Hat Inc anchors enterprise Kubernetes positioning through its OpenShift platform, representing the managed service consolidation pattern where uptime and data sovereignty guarantees replace capital expenditure models. These three players collectively illustrate how vendor capabilities align with buyer compliance burdens in financial services and pharmaceutical verticals.
| Leading Market Players |
|---|
| Docker Inc |
| Red Hat Inc |
| VMware Inc |
| IBM Corporation |
| Microsoft Corporation |
| Amazon Web Services |
| Google LLC |
| Oracle Corporation |
| Rancher Labs |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap container manufacturers across Brazil and Mexico anchor regional supply discipline through conservative balance sheet management that resists cyclical discounting. Their financing patterns tether pricing power to long-term port authority contracts rather than spot-market volatility, creating asymmetric margin protection when corten steel input costs fluctuate.
Pricing Analysis
Value-based pricing anchored to cargo throughput guarantees dominates managed container service contracts, particularly for São Paulo state enterprises facing LGPD compliance deadlines. Three-tier pricing structure across premium certification-grade, standard ISO-compliant, and economy refurbished tiers separates buyers by regulatory exposure rather than volume scale. Pricing pressure stems from aluminum substitution in air cargo segments where fuel efficiency mandates compress operator margins. Small freight forwarders exhibit acute price sensitivity, while biologics distributors prioritize uptime guarantees over per-unit costs.
Supply Chain Analysis
Warehouse-distribution layer consolidation around Santos, Paranaguá, and Veracruz ports creates hub-and-spoke patterns that concentrate finished container inventory within 48-hour truck coverage of major consumption zones. Manufacturing draws from corten steel mills in Brazil, China, and the United States, with corner casting foundries concentrated in Monterrey and São Paulo industrial corridors. Single-source vulnerability in specialized compressor systems for refrigerated units exposes logistics operators to extended lead time volatility. Distribution runs through equipment-leasing channels and direct OEM sales to port authorities, with outcome-based service contracts displacing traditional capital expenditure models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Brazil's ANTT digital freight platform mandates erect barrier-to-entry moats favoring vendors with preemptive certification investments.
For Market Incumbents: Cement regional certification expertise through ANTT and SCT pre-qualification programs before regulatory deadlines harden competitive exclusion. Deepen captive supply of corten steel through offtake agreements with Brazilian metallurgical producers to defend margin position against raw material volatility. Threat substitution from collapsible aluminum variants in last-mile logistics demands counter-positioning through integrated IoT telemetry bundling. For New Entrants and Emerging Players: Mid-sized chemical distributors in Mexico's interior states represent an underserved buyer archetype with unconsolidated procurement and limited incumbent relationships. White-space concentration in tank container segments serving hazardous materials transport offers penetrable entry with specialized certification investment. Go-to-market execution through SCT regulatory consulting partnerships accelerates credibility building faster than direct equipment sales cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor equipment-leasing platforms with contracted port authority revenue streams in Brazil's Southeast region. Long-term viability over a decade horizon hinges on regulatory alignment rather than manufacturing scale, positioning compliance-first managed service operators above commodity equipment producers. Watch LGPD enforcement intensity as the signal indicating accelerated procurement consolidation among São Paulo financial services firms.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | ANTT and SCT compliance timelines compress competitive entry windows for late movers. |
| Backward Integration into Steel Supply | Captive corten sourcing insulates margin structures from commodity price volatility cycles. |
| IoT Telemetry Platform Integration | Edge-cloud convergence enables real-time cargo monitoring beyond port-centric deployments. |
| Managed Service Contract Expansion | Outcome-based agreements with uptime guarantees displace traditional equipment-leasing channels. |
| Tank Container Specialization | Hazardous materials certification requirements limit competitive saturation in chemical transport. |
Methodological Framework
Document review covered customs and trade databases, SEC filings from publicly traded logistics technology vendors, ANTT regulatory filings, and EPA maritime emissions guidance, complemented by interviews with port operations directors, container fleet procurement managers, cold-chain logistics coordinators, and DevOps platform engineers at financial services firms. Secondary validation drew from SCT infrastructure investment disclosures, Brazilian steel industry association production data, and pharmaceutical distributor quality management system documentation. Bottom-up unit economics modeling and top-down sectoral expenditure analysis were triangulated against primary field intelligence.
Market sizing outputs reflect segmentation across product type, application, end user, and material composition dimensions, with additional disaggregation by regulatory compliance tier and deployment model. CAGRs were derived from regression analysis of historical procurement cycles against infrastructure investment pipelines and enforcement timeline acceleration. Forecast inputs incorporated port modernization budget allocations, LGPD compliance cost estimates, and edge computing hardware deployment trajectories across Brazil's interior highway networks.
Revisions become necessary when ANTT regulatory implementation timelines shift, corten steel price volatility exceeds modeled bands, or Kubernetes talent scarcity constraints slow enterprise container platform adoption beyond secondary markets. Forecasts reflect documented assumptions regarding infrastructure investment continuity and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Container Monitoring Market
Containers
Child-Resistant Containers Market
Containers
PET Hinged Containers Market
Containers
Tin Containers Market
Containers
Foam Hinged Take-Out Containers Market
Containers
In-Mold Labelled Containers Market
Containers
Aluminum Foil Containers Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
Compartment Take-Out Container Market
Containers
North America Insulated Shipping Containers Market
Containers
Grab and Go Containers Market
Containers
Container Liner Market
Containers
Laboratory Sample Container Market
Containers
EPS Container Market
Containers
Slip Lid Can Market
Containers
Vials Market