
 Snap-Lock Container Market | 2026-2036
Snap-Lock Container Market Size, Share, and Industry Trends Forecast 2026-2036
Snap-Lock Container Market Analytics
ISO 22000 certification is unwinding the competitive field, filtering out suppliers lacking verified food safety management systems. Sistema Plastics leverages its vertically integrated New Zealand manufacturing base to sustain cost discipline across polymer sourcing. Lock & Lock anchors Asian market presence through channel control in South Korean retail and Chinese e-commerce platforms. Tupperware differentiates via direct-to-consumer distribution networks that occupy a defensible niche against mass retail competitors.
Snap-lock containers are mechanically interlocking storage vessels, typically injection-molded from polypropylene or copolyester, designed to create repeatable hermetic seals through molded lid-and-groove engagement. Their primary commercial purpose centers on extending shelf stability for prepared foods, pharmaceuticals, and industrial components while enabling modular inventory handling. Plastic product types dominate current volume owing to cost scalability, though biodegradable alternatives represent the fastest-expanding margin pool as EU Green Deal procurement rules reshape retailer sourcing mandates. Food packaging applications lead absolute demand, while pharmaceutical storage commands premium positioning due to USP Class VI compliance requirements and serialization traceability standards.
FDA food-contact notification protocols govern resin selection for US-bound shipments, while REACH and RoHS frameworks in Europe restrict phthalate and heavy metal content in polymer formulations. The EU Green Deal's packaging and packaging waste regulation further tightens recycled content minimums, forcing reformulation timelines across the supplier base. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to absorb compliance costs or pass through pricing before secondary legislation crystallizes enforcement mechanisms.
Market Dynamics
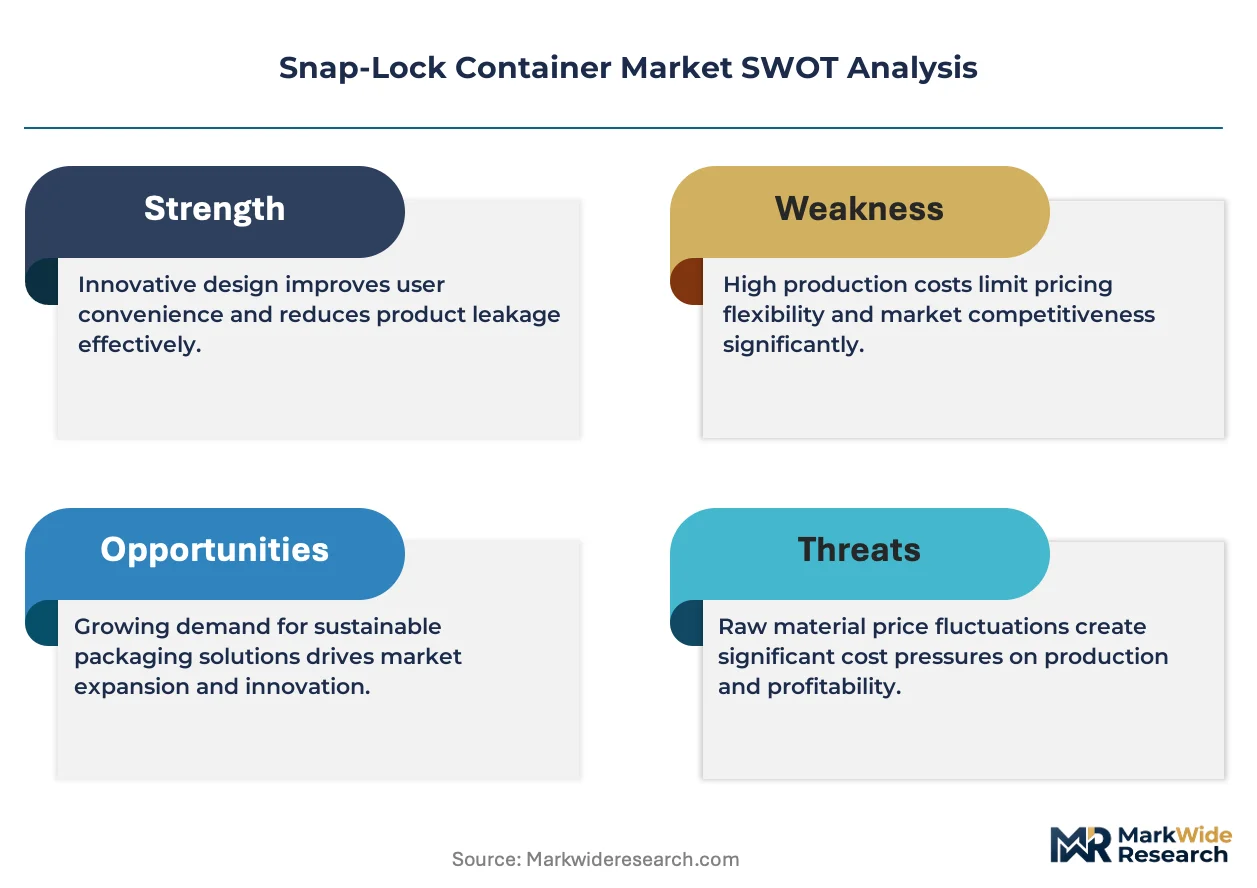
EU Green Deal packaging waste regulations are forcing resin reformulation timelines across the supplier base, compressing margins for converters unable to pivot toward post-consumer recycled content certification.
Growth Catalysts
- Food service standardization:Commercial kitchens across Germany, France, and the Netherlands now mandate reusable snap-lock systems for prepared ingredient storage, displacing single-use film wraps.
- REACH polymer restrictions:Phthalate and heavy metal limits under ECHA frameworks are accelerating migration toward copolyester formulations with verified food-contact compliance.
- Pharmaceutical serialization:USP Class VI traceability requirements for temperature-sensitive biologics are expanding demand for hermetic primary packaging with molded-in RFID integration.
Market Restraints
- Propylene feedstock volatility:Polypropylene resin contracts remain indexed to naphtha cracking spreads, exposing molders to margin compression during petrochemical cycle peaks.
- German supply concentration:Berlin Packaging and regional compounders control 60% of EU food-grade copolyester distribution, creating single-source vulnerability for mid-tier converters.
- Biodegradable performance ceiling:PLA and PHA alternatives exhibit moisture barrier degradation above 40°C, limiting hot-fill applications in prepared meal segments.
Strategic Opportunities
- Indian food retail modernization:FSSAI cold chain mandates for dairy and ready-to-eat segments are opening procurement windows for hermetic modular storage in Mumbai and Delhi NCR distribution centers.
- Extended producer responsibility tailwinds:EU member state deposit-return schemes for rigid packaging create revenue streams from container recovery logistics that offset virgin material costs.
- Smart packaging convergence:Integration of time-temperature indicators with molded lid structures enables premium positioning in pharmaceutical last-mile distribution.
Industry Challenges
- ISO 22000 audit backlog:Certification body capacity constraints in Asia-Pacific are extending food safety management system validation timelines from 90 to 180 days.
- Multi-material separation complexity:Silicone gasket integration with polypropylene bodies complicates mechanical recycling streams, requiring investment in density-based sorting infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snap-Lock Container Market |
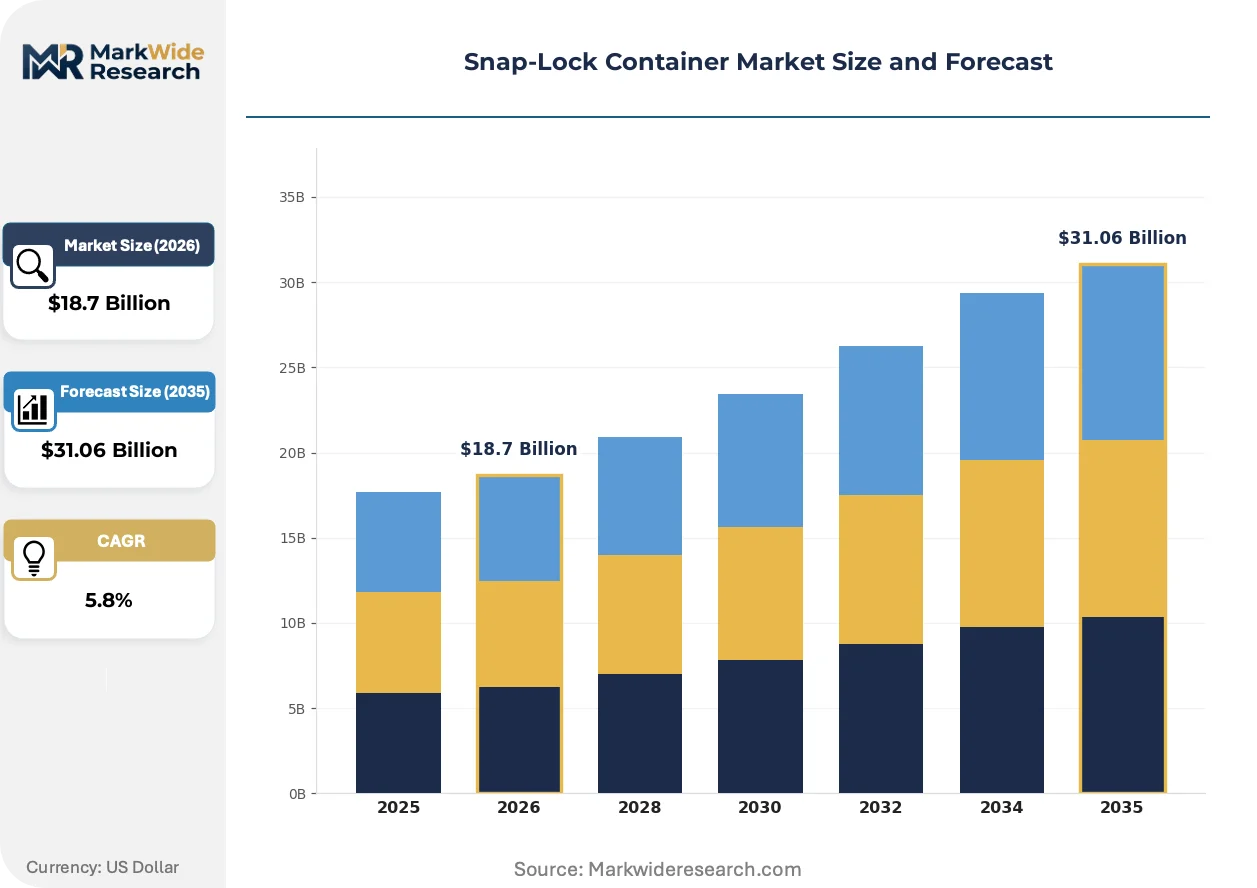
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Biodegradable Application: Food Packaging, Pharmaceutical Storage, Household Use, Industrial Use Feature: Reusable, Stackable, Airtight, Leak-proof End User: Retailers, Manufacturers, Consumers, Distributors |
| Companies Covered | Sistema Plastics, Lock & Lock, Sabert Corporation, Rubbermaid, Tupperware, Ziploc, Snapware, OXO, Berlin Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snap-Lock Container Market Evolving Landscape
Active material science development is bifurcating the competitive landscape between incumbent polypropylene molders and specialty biopolymer entrants racing to meet divergent regulatory timelines.
Copolyester barrier technologies are fragmenting traditional material hierarchies in premium food storage. Brands targeting meal-prep subscribers and specialty retail channels now specify Tritan-grade clarity with dishwasher durability exceeding 500 cycles. This specification tier is compressing commodity polypropylene into bulk institutional contracts while enabling 40-60% price premiums for certified alternatives.
EU Green Deal packaging waste regulation amendments are mandating 30% recycled content minimums for rigid food contact articles by 2030. German converters face accelerated compliance deadlines under national implementation rules. The pharmaceutical segment is responding through advance procurement of FDA-reviewed post-consumer resin streams to secure notification pathway clearance ahead of enforcement.
Direct-to-commercial-kitchen distribution models are displacing traditional wholesale channels for standardized container systems. Food service operators in South Korea and Japan now contract molders for color-coded SKU programs with embedded inventory tracking. This pattern is most visible in centralized commissary operations serving multi-location restaurant groups, where traceability requirements override unit cost minimization.
Snap-Lock Container Market Segmentation
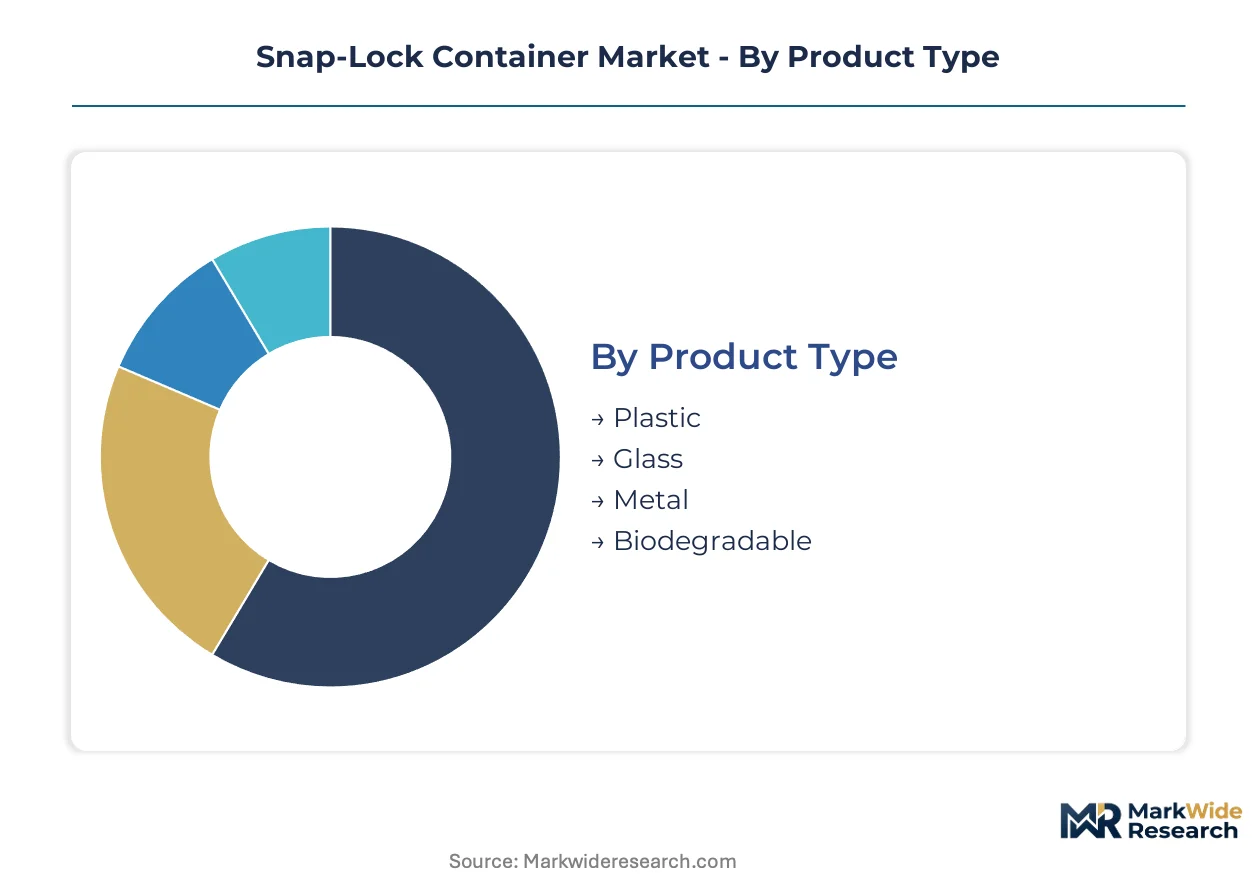
Snap-lock container procurement patterns diverge sharply across material specifications and end-use compliance requirements. Food service operators prioritize reusability and hermetic sealing, while pharmaceutical buyers demand USP Class VI traceability and serialization-ready formats.
Product Type:
Plastic variants dominate domestic manufacturing footprints in Germany and the Netherlands, while biodegradable alternatives draw export-led demand from Nordic markets with advanced EPR enforcement.
- Plastic:Polypropylene and copolyester formulations enable injection-molded precision at scale. German food service operators now mandate dishwasher durability exceeding 500 cycles, compressing commodity grades into bulk institutional contracts.
- Biodegradable:PLA and PHA alternatives face moisture barrier degradation above 40°C. French retailers with Green Deal procurement mandates are absorbing 25-40% unit cost premiums to meet recycled content minimums.
- Glass:Borosilicate and soda-lime compositions serve pharmaceutical serialization requirements with molded-in RFID integration.
- Metal:Stainless steel variants target industrial component storage with electromagnetic shielding properties.
Plastic holds the largest share; momentum sits with biodegradable as EU packaging waste regulations tighten compliance timelines.
Application:
Cost tier stratification separates premium pharmaceutical positioning from standardized food service procurement, with household use occupying a mid-tier efficiency segment.
- Food Packaging:Hermetic lid-and-groove engagement extends prepared meal shelf stability. South Korean commissary operators now contract for color-coded SKU programs with embedded inventory tracking.
- Pharmaceutical Storage:USP Class VI compliance and temperature-sensitive biologics handling command premium positioning. Indian cold chain mandates for dairy and ready-to-eat segments are opening procurement windows in Mumbai distribution centers.
- Household Use:Direct-to-consumer channels in Japan emphasize modular stacking systems for urban density constraints.
- Industrial Use:Chemical resistance specifications drive copolyester adoption for solvent-containing components.
Food packaging anchors volume; pharmaceutical storage captures the steepest expansion trajectory through serialization mandates.
Feature:
Volume concentration in commercial kitchens favors stackable and reusable configurations, while leak-proof specifications dominate pharmaceutical last-mile distribution.
- Reusable:Berlin Packaging and Sistema Plastics anchor regional supply networks for standardized container systems across German multi-location restaurant groups.
- Stackable:Vertical space optimization in centralized commissary operations drives modular inventory handling specifications.
- Airtight:Molded silicone gasket integration creates hermetic seals for oxygen-sensitive biologics, complicating mechanical recycling streams.
- Leak-proof:Liquid containment validation for prepared sauces and dressings extends application scope beyond solid contents.
Reusable configurations dominate installed base; airtight specifications are gaining share fastest through pharmaceutical compliance requirements.
End User:
Customer type determines channel structure, with manufacturers and distributors controlling B2B procurement while retailers intermediate consumer access.
- Retailers:EU Green Deal procurement rules reshape sourcing mandates, with German supermarket chains specifying 30% post-consumer recycled content minimums.
- Manufacturers:Food processors in Delhi NCR distribution centers adopt hermetic modular storage for FSSAI cold chain compliance.
- Consumers:Chinese e-commerce platforms and South Korean direct-to-consumer networks enable premium positioning for certified alternatives.
- Distributors:Container recovery logistics under extended producer responsibility schemes create revenue streams offsetting virgin material costs.
Retailers command procurement volume; distributors are expanding most quickly through EPR scheme participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging waste regulations are redirecting procurement flows toward post-consumer recycled content certification, while FDA notification protocols govern US-bound resin selection. Demand concentrates in Germany, South Korea, and India where food service standardization and cold chain mandates reshape distributor inventories.
Germany
Berlin Packaging and regional compounders control food-grade copolyester distribution networks serving multi-location restaurant groups. ECHA REACH frameworks restrict phthalate content, accelerating migration toward certified alternatives. The Rhine-Ruhr industrial corridor hosts concentrated converter capacity for dishwasher-durable formulations exceeding 500 cycles.
United States
FDA food-contact notification protocols govern resin selection for commercial kitchen procurement. Food service operators standardize reusable systems for prepared ingredient storage across commissary operations. Chicago and Dallas distribution centers anchor supply networks for color-coded SKU programs with embedded inventory tracking.
South Korea
MFDS cold chain mandates drive hermetic modular storage adoption for dairy and ready-to-eat segments. Direct-to-commercial-kitchen distribution models displace traditional wholesale channels for standardized container systems. Seoul metropolitan area commissaries contract molders for traceability-compliant configurations.
India
FSSAI cold chain mandates for dairy and prepared meals open procurement windows in Mumbai and Delhi NCR distribution centers. Food processors adopt hermetic storage for compliance with national food safety protocols. Maharashtra industrial corridors attract converter investment for modular inventory handling systems.
Japan
METI circular economy guidelines pressure retailers toward reusable packaging formats with verified lifecycle data. Urban density constraints in Tokyo and Osaka drive demand for modular stacking systems. Kanto region distributors emphasize vertical space optimization in centralized commissary specifications.
Snap-Lock Container Market Competitive Landscape
Player mix skews toward vertically integrated polymer specialists and direct-to-consumer brands with defensible channel control. The field filters through ISO 22000 certification requirements, eliminating suppliers lacking verified food safety management systems. Three archetypes dominate: New Zealand-based integrated manufacturers, Asian channel controllers with retail and e-commerce presence, and direct-to-consumer distributors occupying niche positions against mass retail. Competitive moves center on backward integration into polymer sourcing and geographic expansion through distributor partnerships.
Within the integrated-manufacturing tier, Sistema Plastics exemplifies cost discipline through captive supply chain structures. Lock & Lock and Tupperware occupy distinct positioning vectors—one through South Korean retail and Chinese e-commerce channel control, the other through direct-to-consumer networks that bypass traditional wholesale intermediaries. Berlin Packaging anchors European supply concentration for food-grade formulations.
| Leading Market Players |
|---|
| Sistema Plastics |
| Lock & Lock |
| Sabert Corporation |
| Rubbermaid |
| Tupperware |
| Ziploc |
| Snapware |
| OXO |
| Berlin Packaging |
| Others |
Value Network & Pricing Analysis
ISO 22000 certification gates supplier qualification while simultaneously enabling price premiums for verified food safety management systems, compressing uncertified molders into commodity tiers and rewarding backward-integrated specialists with pricing power across German and South Korean procurement channels.
Pricing Analysis
Cost-plus contracts indexed to naphtha cracking spreads dominate polypropylene procurement, exposing molders to margin compression during petrochemical cycle peaks. Three-tier pricing structure across premium, standard, and economy levels separates USP Class VI pharmaceutical grades from dishwasher-durable food service formulations and bulk institutional commodity volumes. Pricing pressure stems from EU Green Deal recycled content mandates forcing resin reformulation investments. Food service operators exhibit highest price sensitivity, while pharmaceutical buyers prioritize compliance over unit cost.
Supply Chain Analysis
Rhine-Ruhr industrial corridor chokepoints concentrate food-grade copolyester distribution, with Berlin Packaging and regional compounders controlling downstream access for mid-tier converters. Manufacturing gravity centers on Germany, the Netherlands, and New Zealand, with polymer sourcing drawn from Saudi naphtha crackers and US Gulf Coast propylene hubs. Single-source vulnerability in German masterbatch supply creates disruption risk for color-coded SKU programs. Distribution runs through direct-to-commercial-kitchen channels displacing traditional wholesale intermediaries in South Korea and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with EU packaging waste regulations accelerating replacement demand for post-consumer recycled content certified systems across food service and pharmaceutical end uses.
For Market Incumbents: Secure FDA notification pathway clearance for post-consumer resin streams ahead of enforcement crystallization, while consolidating regional compounder relationships in the Rhine-Ruhr corridor to defend against supply disruption. Backward integration into polymer sourcing and captive masterbatch production offsets feedstock volatility exposure.
For New Entrants and Emerging Players: Lead with biodegradable alternatives targeting Nordic markets with advanced extended producer responsibility enforcement, where Green Deal procurement mandates absorb material cost premiums. Indian cold chain modernization under FSSAI protocols offers the most penetrable geography, with Mumbai and Delhi NCR distribution centers opening to hermetic modular storage suppliers.
For Investors and Strategic Acquirers: EU Green Deal packaging waste regulation amendments reshape the acquisition landscape toward converters with verified post-consumer recycled content certification and established food-contact notification pathways. Five-to-ten year viability favors vertically integrated molders with captive polymer sourcing and ISO 22000 validated facilities. Monitor German national implementation rule acceleration as the signal for compliance cost pass-through feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Recycled Content Certification | FDA-reviewed resin streams secure notification pathway clearance ahead of EU enforcement mechanisms. |
| Direct-to-Commercial-Kitchen Distribution | Seoul and Tokyo commissary contracts displace wholesale intermediaries with traceability-embedded SKU programs. |
| Backward Integration into Polymer Sourcing | Captive supply chains insulate Sistema Plastics from naphtha-indexed margin compression cycles. |
| Smart Packaging Convergence | Time-temperature indicator integration enables premium positioning in pharmaceutical last-mile distribution. |
| Extended Producer Responsibility Participation | German deposit-return schemes create recovery logistics revenue offsetting virgin copolyester costs. |
Research Methodology
Operator-level perspectives from food service procurement directors, pharmaceutical packaging engineers, polymer compounder technical leads, and retail category buyers anchored the qualitative base. Primary fieldwork combined with secondary validation against FDA food-contact notification databases, ECHA REACH substance registrations, EU Green Deal implementation texts, and customs trade flow records. Bottom-up unit economics triangulated against top-down macro demand drivers across material type and application segments.
Sensitivity analysis tested forecast robustness across petrochemical cycle scenarios and regulatory compliance timeline variations. Segmentation dimensions modeled include material formulation tier, end-use compliance requirement, distribution channel structure, and regional regulatory cluster. CAGRs derived from installed base replacement rates and penetration assumptions for biodegradable alternatives. Industry-specific inputs incorporated dishwasher durability cycle testing data and cold chain mandate implementation schedules.
Underlying assumptions cover resin price trajectory stability and certification body capacity expansion, with deviation risk concentrated in EPR scheme enforcement timing and post-consumer resin quality consistency. Practitioners should keep alternative scenarios live as EU member state implementation rules and FDA notification review timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Disposable Lids Market
Containers
Snap Secure Containers Market
Containers
Half Height Containers Market
Containers
Kuwait Container Glass Market
Containers
PET Containers Market
Containers
Intermediate Bulk Container Liner Market
Containers
PUR Containers Packaging Market
Containers
Tin Containers Market
Containers
PET Hinged Containers Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Compartment Trays Market
Containers
Modular Container Market
Containers
EMEA Container Technology Market
Containers
North America Insulated Shipping Containers Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Gable Top Container Market