
 Durable Insulated Containers Market | 2026-2036
Durable Insulated Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Durable Insulated Containers Market Foresight
Modular container configurations with swappable insulation inserts is hardening buyer preference away from fixed-wall designs. YETI Holdings Inc leverages its rotomolded manufacturing base to sustain premium positioning across outdoor and commercial segments. Pelican Products, Inc. anchors its portfolio in mil-spec durability standards that differentiate performance under extreme transit conditions.
Durable insulated containers are engineered thermal retention vessels constructed with multi-layer walls—typically polyurethane foam cores sealed within polymer or metal shells—designed to maintain stable internal temperatures across ambient external conditions for periods ranging from hours to multiple days. Stainless steel variants command the highest margin pools due to material longevity and corrosion resistance, while plastic constructions dominate unit volume through lower price accessibility and lighter shipping weights. Insulated bags represent the fastest-expanding configuration as last-mile food delivery and grocery logistics operators prioritize collapsible, route-efficient thermal protection.
The US FDA and EPA jointly shape product requirements through pharmaceutical cold chain validation protocols and material safety standards for food-contact surfaces. The EU REACH framework restricts certain chemical additives in foam insulation, redirecting formulation R&D toward bio-based alternatives. Stakeholders must monitor how diverging regional compliance thresholds will fragment supply chain certification requirements and reshape sourcing geography decisions.
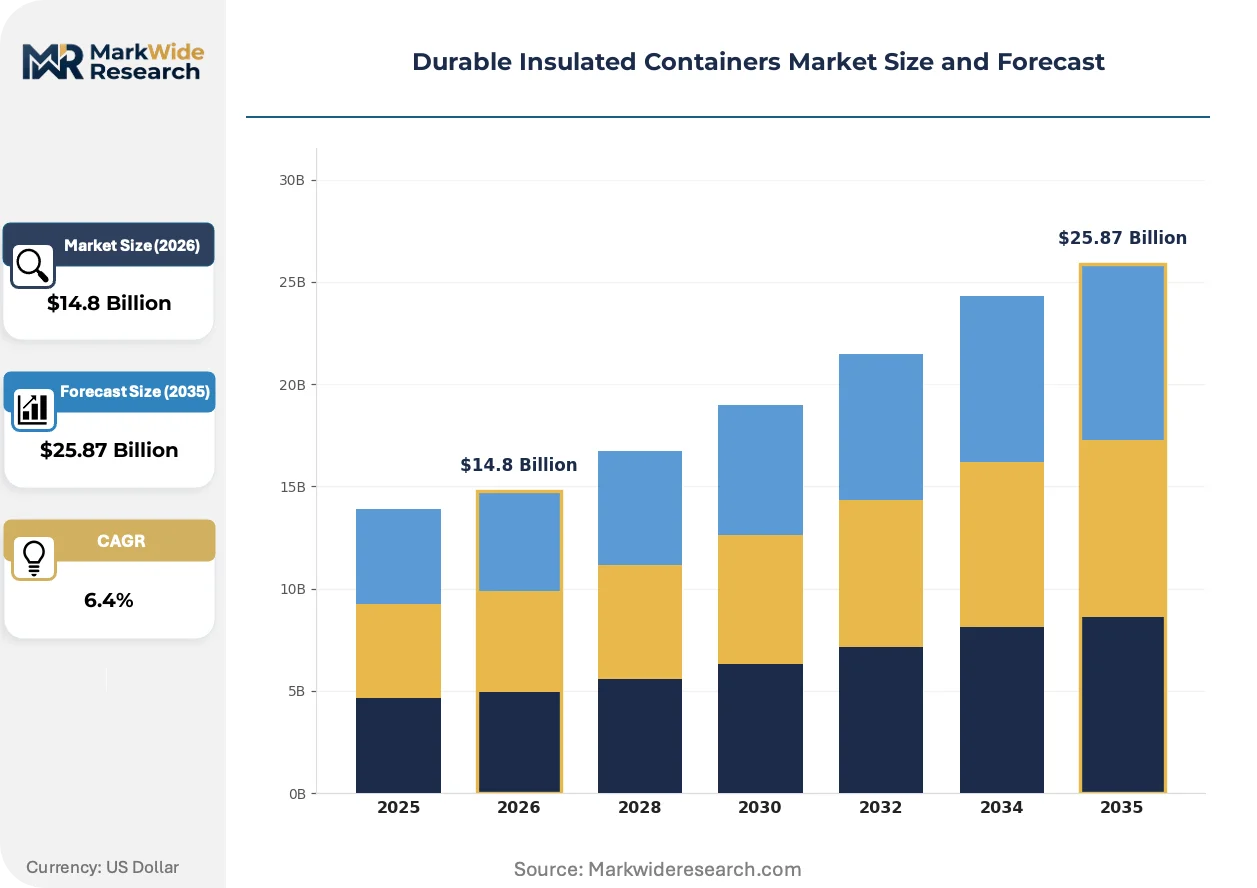
Market Dynamics
Cold chain logistics operators are consolidating procurement around modular container systems that reduce per-trip thermal protection costs while meeting tightening pharmaceutical validation standards.
Growth Catalysts
- REACH chemical restrictions:The EU ECHA framework is redirecting foam insulation R&D toward bio-based polyurethane alternatives, opening formulation partnerships between chemical suppliers and container manufacturers.
- Last-mile grocery delivery:Food logistics operators in dense urban corridors are deploying collapsible insulated bags at scale to optimize vehicle cube utilization and driver route efficiency.
- FDA cold chain validation:Updated pharmaceutical transport guidelines are mandating documented thermal performance across distribution legs, pulling demand toward certified multi-day retention systems.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings compress margin pools for premium container variants, forcing manufacturers toward hybrid polymer-metal constructions.
- Specialized rotomolding capacity:Production of complex double-wall geometries concentrates among a limited supplier base in North American and German industrial clusters.
- Reusable bag durability ceiling:Fabric-based thermal protection faces mechanical wear limits that cap service life in high-frequency courier operations.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO cold chain requirements for temperature-sensitive biologics are creating certified container demand at domestic manufacturing hubs and air cargo terminals.
- Solar-powered active cooling:Photovoltaic panel integration with phase-change material systems is unifying passive and active thermal management for off-grid vaccine distribution.
- Leased container pools:Asset-light operating models are emerging as pharmaceutical 3PLs seek to convert capital expenditure into per-shipment service fees.
Industry Challenges
- Thermal engineer scarcity:Specialized expertise in multi-physics simulation for insulation optimization is concentrated among a narrow workforce pool, extending product development timelines.
- Cross-border certification stacking:Containers serving international pharmaceutical lanes must satisfy sequential FDA, EMA, and WHO validation protocols, multiplying compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durable Insulated Containers Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coolers, Thermoses, Insulated Bags, Food Storage Containers Material: Stainless Steel, Plastic, Glass, Aluminum End User: Retail Customers, Restaurants, Catering Services, Outdoor Enthusiasts Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Sonoco ThermoSafe, Pelican Products, Inc., Cold Chain Technologies, YETI Holdings Inc, Igloo Products Corp, Thermos LLC, Stanley, Zojirushi Corporation, Coleman Company Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durable Insulated Containers Market Shifts & Advancements
Container architecture is pivoting from fixed-wall monoliths toward adaptable systems that accommodate variable payload geometries and multi-temperature zone requirements within single shipments.
Vacuum-insulated panel technology is unifying extreme thermal performance with reduced wall thickness, enabling pharmaceutical distributors to maximize payload density in aircraft and compact delivery vehicles. Cold chain operators in Germany and Switzerland are adopting VIP-core containers for high-value biologics requiring sub-zero stability across multi-day transit. The technology is compressing the performance gap between passive containers and active refrigerated units, reshaping capital allocation decisions in regional distribution networks.
The US FDA and EPA are jointly tightening material safety standards for food-contact surfaces and pharmaceutical cold chain validation, forcing manufacturers to maintain dual certification documentation. This regulatory convergence is raising compliance costs for multi-use containers that serve both food and medical end-uses. Container suppliers are responding by segmenting product lines into dedicated pharmaceutical and food-service variants with distinct material traceability systems.
Buyer procurement is consolidating around total-cost-of-ownership metrics that weigh container acquisition price against thermal failure risk and reuse cycle counts. Large pharmaceutical 3PLs are displacing spot purchasing with multi-year fleet management contracts that bundle container supply, maintenance, and compliance documentation. This shift is most visible in North American and Western European markets where cold chain liability exposure drives preference for vendor-managed inventory arrangements.
Durable Insulated Containers Market Segmentation
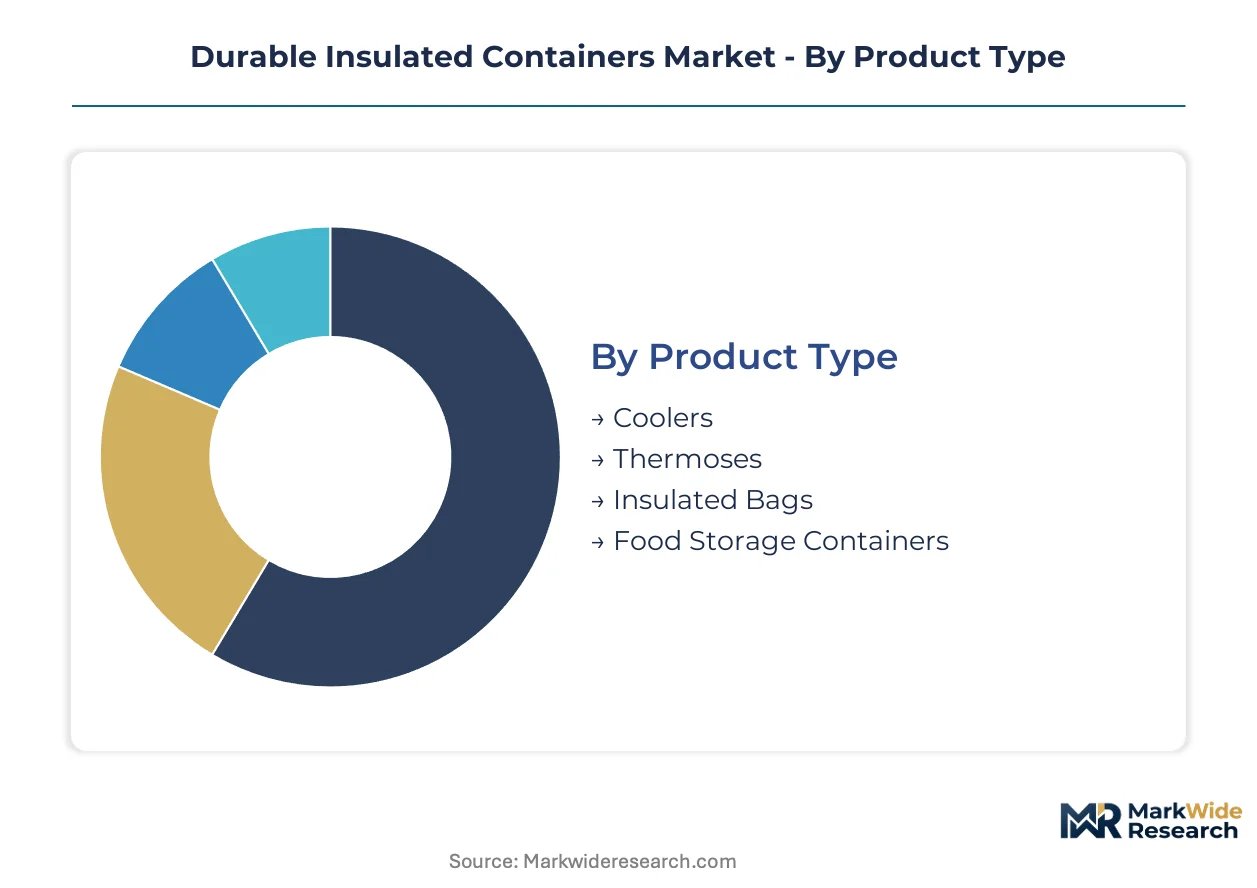
Durable insulated containers fragment across four structural dimensions that reshape competitive positioning. Product architecture and material selection drive margin stratification, while end-use concentration and channel access determine volume capture.
Product Type:
Coolers dominate absolute volume through rotomolded manufacturing scale, yet insulated bags are gaining share fastest in last-mile logistics applications.
- Coolers:Double-wall polymer shells with polyurethane foam cores deliver multi-day thermal retention for pharmaceutical and outdoor end-uses. Demand concentrates in North American cold chain networks where FDA validation requirements favor documented performance over collapsible alternatives.
- Insulated Bags:Fabric-wrapped phase-change material panels offer collapsible thermal protection optimized for courier route density. German grocery logistics operators deploy these at scale to maximize vehicle cube utilization across dense urban delivery zones.
- Thermoses:Vacuum-insulated stainless steel vessels command premium positioning in personal hydration and medical specimen transport.
- Food Storage Containers:Modular polymer designs with removable insulation inserts serve commercial catering and meal-prep subscription services.
Today's leader: Coolers. Tomorrow's challenger: Insulated Bags.
Material:
Stainless steel anchors premium positioning through corrosion resistance and regulatory acceptance, while plastic constructions dominate unit economics through lighter shipping weights and lower mold costs.
- Stainless Steel:Medical-grade 304 and 316 alloys satisfy FDA and EMA pharmaceutical contact requirements with service lives exceeding ten years. Swiss biologics distributors specify these for high-value cargo requiring sub-zero stability across multi-day international lanes.
- Plastic:Rotomolded polyethylene and injection-molded polypropylene enable complex double-wall geometries at production scales unreachable by metal forming. Indian pharmaceutical exporters source these for CDSCO-compliant domestic distribution where acquisition cost outweighs reuse intensity.
- Glass:Borosilicate variants with silicone sleeves serve premium food-service presentation and laboratory sample visibility requirements.
- Aluminum:Lightweight rolled-sheet constructions fill mid-tier outdoor recreation and commercial catering segments where dent resistance matters less than mass reduction.
Stainless steel owns the premium tier. Plastic owns the volume tier. Aluminum sits in structural retreat.
End User:
Restaurants and catering services drive replacement cycles through mechanical wear, while outdoor enthusiasts sustain brand premiumization through performance validation.
- Restaurants:High-frequency thermal cycling and commercial dishwasher exposure compress service life, creating recurring procurement demand for NSF-certified polymer containers.
- Catering Services:Event-based logistics require collapsible inventory that deploys for single-day use then stores compactly, favoring insulated bag configurations.
- Retail Customers:Weekend recreation and lunch-prep applications prioritize aesthetic differentiation and brand signaling over thermal performance specifications.
- Outdoor Enthusiasts:Expedition-grade durability requirements sustain premium pricing for rotomolded coolers with bear-resistant certification and multi-week ice retention.
Restaurants provide the base load. Outdoor enthusiasts provide the margin.
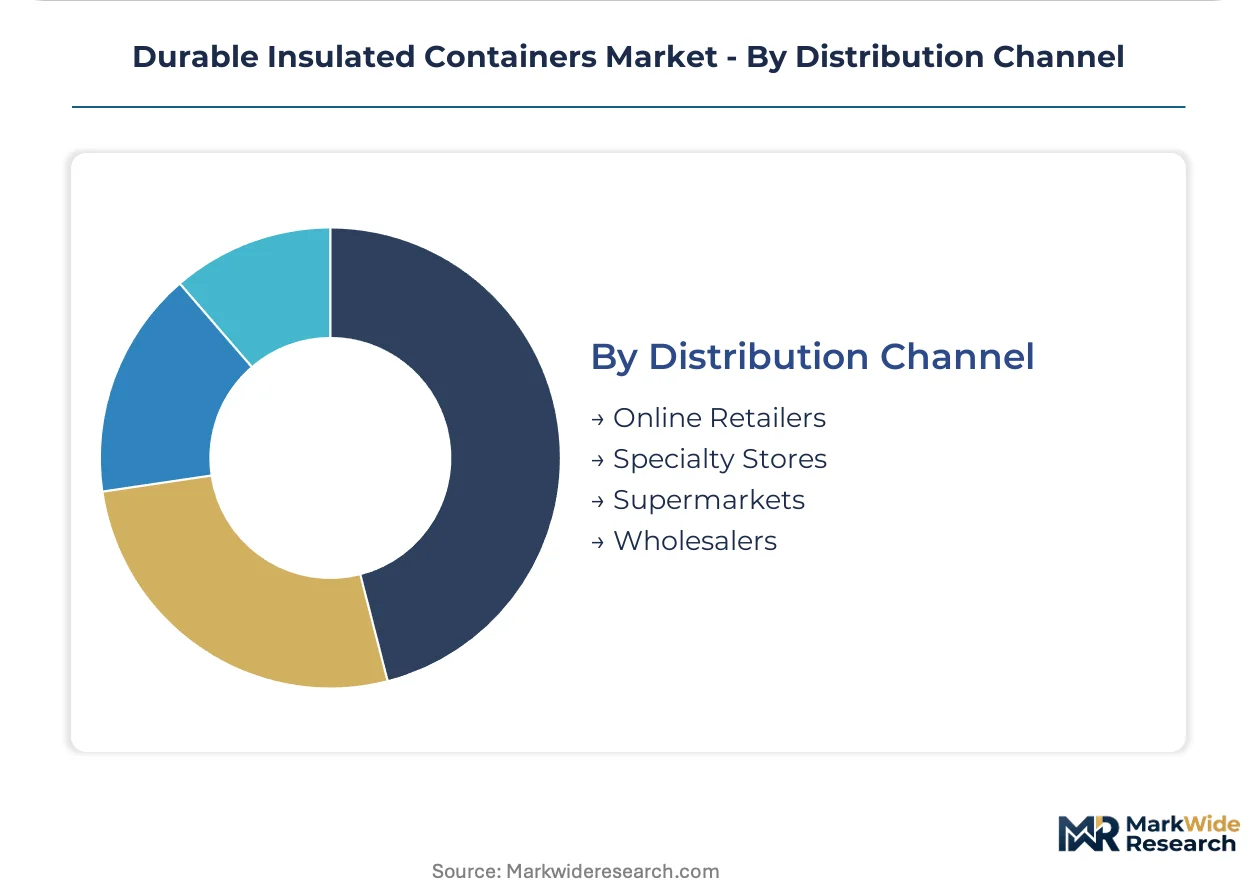
Distribution Channel:
Specialty stores anchor premium brand positioning through tactile evaluation, while online retailers displace unit volume through subscription replenishment and fleet procurement.
- Online Retailers:Direct-to-consumer platforms and B2B procurement portals enable pharmaceutical 3PLs to consolidate multi-year fleet contracts with vendor-managed inventory terms. North American cold chain operators increasingly source certified containers through these channels to streamline compliance documentation.
- Specialty Stores:Outdoor recreation and restaurant supply showrooms allow thermal performance demonstration through live ice-retention displays. German precision engineering standards favor these channels for advanced container systems requiring technical consultation.
- Supermarkets:Mass-market coolers and personal thermoses move through seasonal promotional cycles tied to summer recreation demand.
- Wholesalers:Broadline foodservice distributors bundle insulated containers with disposable packaging for restaurant and catering procurement efficiency.
Online retailers capture the growth trajectory. Specialty stores defend the premium perimeter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotomolded cooler manufacturing originated in the United States during the mid-20th century, establishing thermal retention engineering traditions that spread to German precision clusters and Asian export hubs.
United States
FDA cold chain validation protocols and EPA material safety standards govern pharmaceutical and food-contact container specifications. The agency's updated pharmaceutical transport guidelines mandate documented thermal performance across distribution legs. Cold chain logistics operators in the Midwest and Southeast consolidate procurement around modular container systems with vendor-managed inventory arrangements.
Germany
REACH chemical restrictions through ECHA redirect foam insulation R&D toward bio-based polyurethane alternatives. Precision engineering standards and dense cold chain infrastructure create premium positioning for advanced container systems. Manufacturing clusters in Bavaria and Baden-Württemberg specialize in vacuum-insulated panel technology for high-value biologics distribution.
India
CDSCO cold chain requirements for temperature-sensitive biologics drive certified container demand at domestic manufacturing hubs and air cargo terminals. Pharmaceutical exporters source rotomolded polyethylene containers for compliant domestic distribution. Production concentrates in Gujarat and Maharashtra where chemical suppliers form formulation partnerships with container fabricators.
China
NMPA pharmaceutical transport standards and MIIT industrial quality frameworks shape domestic manufacturing requirements. Mass-scale rotomolding capacity serves both export markets and expanding domestic cold chain networks. Yangtze River Delta industrial clusters supply collapsible insulated bag configurations to last-mile grocery logistics operators across dense urban corridors.
Switzerland
Swissmedic pharmaceutical validation protocols and sub-zero stability requirements anchor demand for premium stainless steel container variants. Biologics distributors specify medical-grade 304 and 316 alloys for multi-day international transit lanes. Basel and Zurich pharmaceutical clusters drive specification standards that cascade through European distribution networks.
Durable Insulated Containers Market Competitive Landscape
The competitive structure tilts toward specialty manufacturers with rotomolded expertise and diversified consumer goods conglomerates with thermal product divisions. Market position stratifies across three tiers: premium performance brands commanding bear-resistant certification and multi-week ice retention, mid-tier outdoor recreation suppliers competing on seasonal promotional cycles, and commercial cold chain specialists focused on FDA-validated pharmaceutical transport systems. Dominant competitive moves include backward integration into polyurethane foam formulation and geographic expansion through leased container pool operating models.
Among premium-tier specialists, YETI Holdings Inc exemplifies rotomolded manufacturing depth across outdoor and commercial segments, while Pelican Products, Inc. represents mil-spec durability standards that differentiate performance under extreme transit conditions. Cold Chain Technologies occupies a position within pharmaceutical-validated systems serving 3PL fleet procurement requirements.
| Leading Market Players |
|---|
| Sonoco ThermoSafe |
| Pelican Products, Inc. |
| Cold Chain Technologies |
| YETI Holdings Inc |
| Igloo Products Corp |
| Thermos LLC |
| Stanley |
| Zojirushi Corporation |
| Coleman Company Inc |
| Others |
Supply & Pricing Matrix
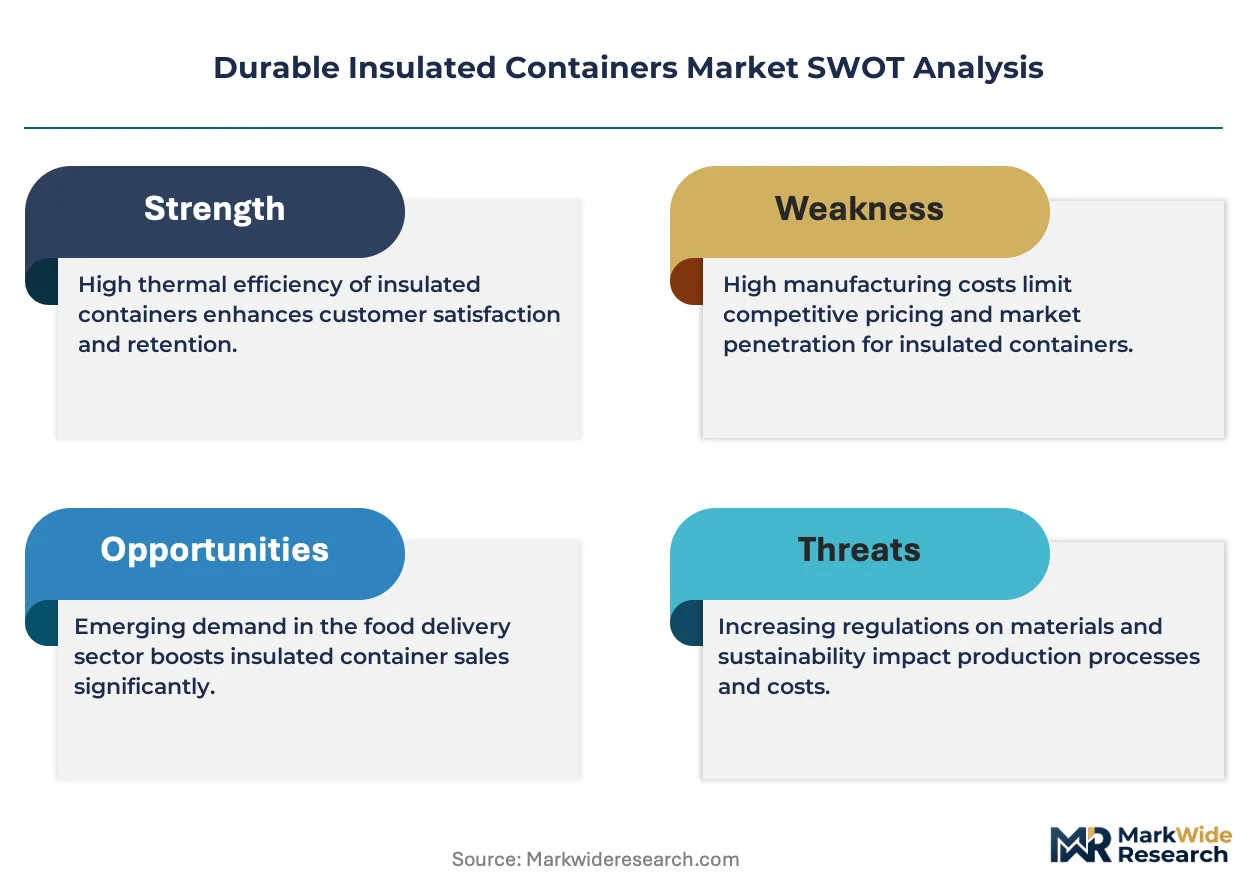
Nickel and chromium price volatility on the London Metal Exchange cascades through stainless steel input costs, compressing margin pools for premium container variants and forcing manufacturers toward hybrid polymer-metal constructions or bio-based polyurethane formulations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from NSF-certified foodservice units and basic outdoor recreation models. Price differentiation hinges on certification grade and thermal performance duration, with stainless steel variants commanding the highest tier. Cost compression in the mid-tier is intensifying because rotomolded polyethylene capacity concentrates among limited North American and German suppliers. Pharmaceutical 3PLs show the least price sensitivity due to cold chain liability exposure, while mass-market outdoor buyers drive the most aggressive procurement negotiations.
Supply Chain Analysis
Ocean freight rate fluctuations between Asia and North America directly impact landed costs for collapsible insulated bag configurations sourced from Yangtze River Delta manufacturing clusters. Supply concentrates in China for mass-scale rotomolding, Germany for vacuum-insulated panel technology, and India for CDSCO-compliant pharmaceutical containers. Raw material dependencies span nickel-chromium alloys for medical-grade stainless steel, bio-based polyurethane precursors under REACH restrictions, and phase-change material formulations. Single-source vulnerability in specialized rotomolding equipment creates bottleneck risk. Distribution runs through pharmaceutical 3PL fleet procurement portals, outdoor specialty retail showrooms, and broadline foodservice wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: manufacturers can capture margin expansion by producing in India under CDSCO frameworks for export to markets with stricter EMA validation requirements, exploiting the cost-differential between regulatory tiers.
For Market Incumbents: Deploy backward integration into polyurethane foam formulation to secure supply of REACH-compliant bio-based alternatives before chemical redirect restrictions harden. Incumbent rotomolders should add capacity in Gujarat to serve Indian pharmaceutical export growth while defending North American market share against emerging Asian competitors through FDA validation documentation superiority. For New Entrants and Emerging Players: Direct-to-consumer online platforms offer the most penetrable route for collapsible insulated bag specialists targeting German grocery logistics operators. New entrants should prioritize last-mile food delivery segments in dense European urban corridors where route-efficiency demands outpace incumbent cooler manufacturers' product development cycles, using subscription-based fleet replacement models to bypass capital-intensive rotomolding infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier specialists possessing vacuum-insulated panel manufacturing expertise but lacking pharmaceutical certification infrastructure. Long-term viability across the analysis window favors acquisition targets with dual-use container platforms serving both food and medical end-uses. Investors should monitor CDSCO inspection backlog clearance rates as the inflection signal for Indian pharmaceutical export container demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Foam | REACH chemical restrictions through ECHA redirect formulation partnerships toward compliant polyurethane alternatives. |
| Leased Container Pool Operating Model | Pharmaceutical 3PLs convert capital expenditure into per-shipment service fees, expanding addressable market. |
| Vacuum-Insulated Panel Technology Scale-Up | Swiss biologics distributors specify VIP-core systems for sub-zero stability across multi-day international transit lanes. |
| Indian Manufacturing Footprint Expansion | CDSCO cold chain requirements create certified container demand at domestic pharmaceutical hubs and air cargo terminals. |
| Solar-Powered Active Cooling Integration | Photovoltaic panel unification with phase-change material systems enables off-grid vaccine distribution in infrastructure-limited regions. |
Research Methodology
Direct dialogue with cold chain logistics operators, pharmaceutical procurement managers, rotomolding plant engineers, and polyurethane formulation chemists grounded the qualitative foundation. Secondary validation drew from FDA guidance documents, ECHA REACH restriction updates, CDSCO cold chain circulars, customs trade data for insulated container classifications, and SEC filings of publicly traded container manufacturers. Bottom-up demand modeling triangulated against top-down market sizing across product architecture, material grade, end-use concentration, and distribution channel dimensions.
Segment-level value and volume estimates emerged from thermal performance tier stratification, reuse cycle intensity assumptions, and regional regulatory compliance cost differentials across the projection horizon. The analytical framework modeled coolers, insulated bags, thermoses, and food storage containers by stainless steel, plastic, glass, and aluminum material splits, with end-use segmentation spanning restaurants, catering services, retail customers, and outdoor enthusiasts. CAGRs derived from pharmaceutical cold chain expansion rates, last-mile grocery delivery penetration curves, and outdoor recreation equipment replacement cycles.
The model assumes a particular technology adoption path; alternative pathways for vacuum-insulated panel cost reduction would alter the outlook by accelerating displacement of active refrigerated units. Forecasts reflect assumptions about REACH chemical restriction enforcement timelines and FDA validation protocol harmonization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Container Mouth Inner Seal Market
Containers
Acrylic Container Market
Containers
USA and Canada Packer Bottle Market
Containers
Concentrate Containers Market
Containers
Stackable Plastic Trays Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Pinch Grip Jars Market
Containers
Half Height Containers Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Stackable Container Market
Containers
Asia and Africa Food Cans Market
Containers
EPS Shippers Market
Containers
Wooden Barrels Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Canning Jars Market
Containers
Car Lube Container Market