
 Turkey Construction Market | 2026-2036
Turkey Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Construction Market Outlook
ISO 9001 quality management certification is unwinding the competitive landscape for mid-tier Turkish contractors bidding on public infrastructure tenders. Cengiz İnşaat leverages its vertically integrated quarry-to-project model across hydropower and transportation megaprojects. Rönesans Holding anchors its position through hospital and mixed-use developments spanning Istanbul, Moscow, and Central Asian capitals. Tekfen Holding differentiates via specialized oil and gas construction expertise in the Caspian and Middle East basins.
Turkey construction encompasses the planning, design, and physical assembly of buildings and civil works using reinforced concrete, structural steel, and composite systems engineered to seismic Zone 1 specifications with minimum 8.0 magnitude resistance ratings. Its primary purpose spans housing delivery, commercial facility creation, and transport-energy-water infrastructure enabling economic circulation. Residential construction dominates volume but yields thinner margins, while mega projects in the infrastructure category concentrate the largest contract values and longest execution timelines. Government end users channel the majority of public spending through TOKİ and the General Directorate of Highways, whereas private developers concentrate in Istanbul, Ankara, and İzmir premium commercial segments.
Turkish Standards Institution (TSE) seismic compliance protocols and the Ministry of Environment, Urbanization and Climate Change building codes govern material testing, structural design approval, and post-earthquake damage assessment workflows. The Banking Regulation and Supervision Agency (BDDK) and Capital Markets Board (SPK) jointly shape project finance availability through construction sector exposure limits and REIT fundraising rules. Stakeholders must monitor whether the Council of State rulings on environmental impact assessments for Black Sea and Mediterranean coastal projects tighten further, as this would redirect developer capital toward inland urban renewal corridors.
Market Dynamics
Seismic retrofit mandates and building amnesty regulations from Turkey's Ministry of Environment, Urbanization and Climate Change are compressing contractor qualification timelines while redirecting capital toward Marmara and southeastern Anatolian corridors.
Growth Catalysts
- Urban Renewal Mandates:Post-2023 seismic retrofit requirements under TSE protocols are generating sustained demand for structural reinforcement services across residential and commercial building stocks.
- Hydropower Infrastructure:State-backed energy security priorities are accelerating dam and hydroelectric facility construction in eastern Anatolian river basins.
- Transportation Megaprojects:Kanal İstanbul and highway corridor expansions are concentrating long-duration contracts with integrated design-build delivery models.
Market Restraints
- Steel Price Volatility:Reinforcing bar and structural steel input costs fluctuate with import dependency on Black Sea and Ukrainian supply routes.
- Cement Supply Concentration:Domestic clinker production clusters in Afyon and Çanakkale create geographic vulnerability to energy cost shocks.
- Skilled Labor Scarcity:Certified welders and seismic structural engineers remain concentrated in İstanbul and Ankara, constraining project scaling.
Strategic Opportunities
- Modular Prefabrication:Factory-built housing components offer quality-controlled alternatives to on-site casting for earthquake-zone residential delivery.
- Green Building Certification:BREEAM and LEED-adjacent standards are opening premium pricing for energy-efficient commercial developments in İzmir.
- Cross-Border Contracting:Turkish contractors with ISO 9001 credentials are securing transportation and healthcare infrastructure awards in Central Asian republics.
Industry Challenges
- Permitting Velocity:Environmental impact assessment approvals for Black Sea coastal projects face extended Council of State review cycles.
- Technology Integration:Building Information Modeling adoption lags among mid-tier contractors, fragmenting coordination on multi-stakeholder developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Construction Market |
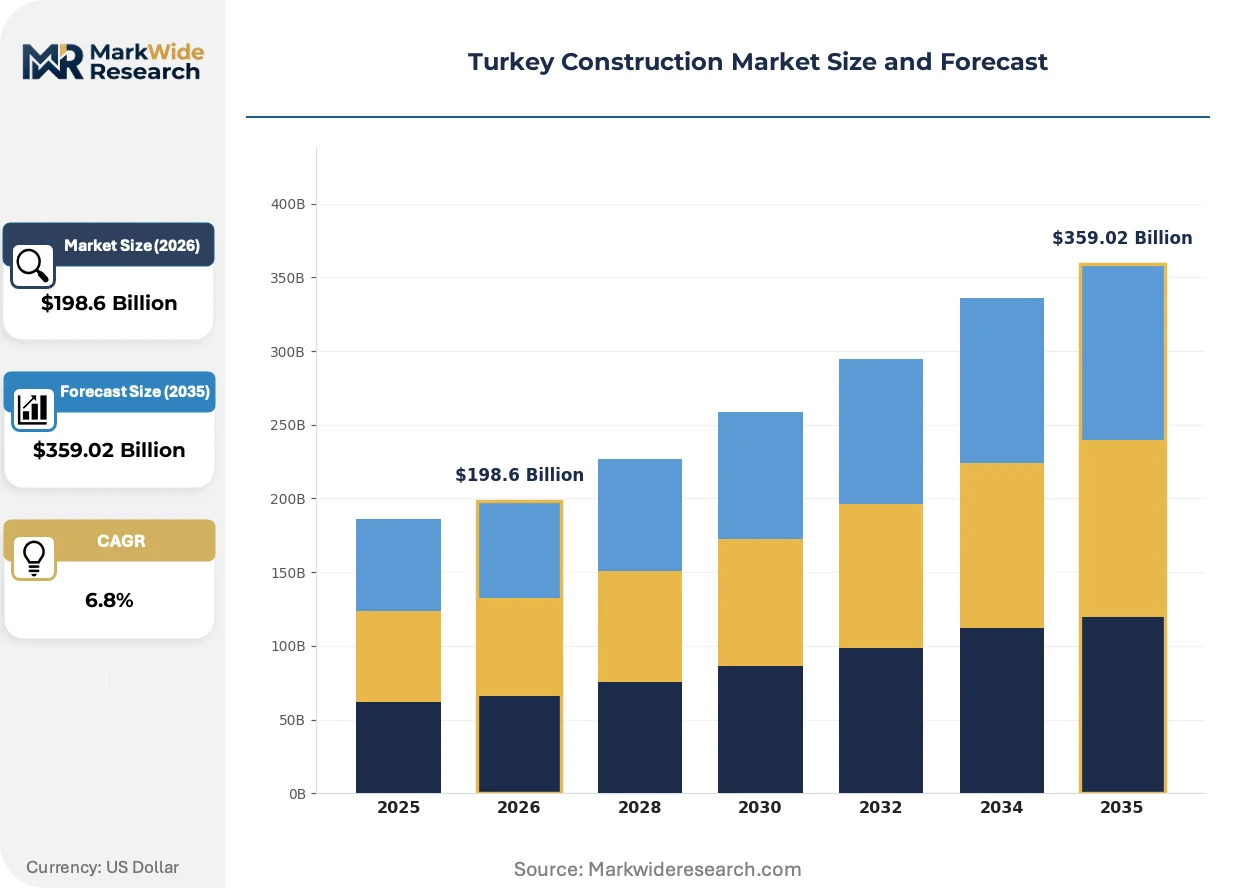
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $359.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Residential, Commercial, Infrastructure, Industrial Material: Concrete, Steel, Wood, Glass End User: Government, Private Developers, NGOs, Corporations Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | TAV Construction, Cengiz İnşaat, Rönesans Holding, Tekfen Holding, Yapı Merkezi Holding, Limak İnşaat, Alarko Contracting Group, Nurol Construction and Trading, ENKA İnşaat ve Sanayi A.Ş., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Construction Market Strategic Shifts
Digital fabrication methods and regulatory compliance automation are compressing traditional construction timelines while elevating material traceability requirements across Turkish project delivery.
Self-compacting concrete formulations with fiber-reinforced polymer additives are bifurcating quality tiers in high-rise structural applications. TOKİ social housing developments are specifying these mixes for accelerated formwork cycling. The technology is bifurcating contractor capabilities between certified batch-plant operators and conventional ready-mix suppliers.
TSE seismic compliance protocols now mandate real-time structural health monitoring systems for public buildings exceeding defined occupancy thresholds. Sensor network integration is becoming a design-phase requirement rather than post-construction retrofit. Hospital and education facility tenders in Marmara provinces are embedding these specifications as technical minimums.
Developer procurement of construction services is consolidating around design-build-operate-maintain contracts with decade-long performance guarantees. Traditional lump-sum general contracting is retreating to smaller-scale residential and light commercial segments. This restructuring is most pronounced in Ankara's healthcare infrastructure pipeline, where ministry-backed projects favor integrated service providers.
Turkey Construction Market Segmentation
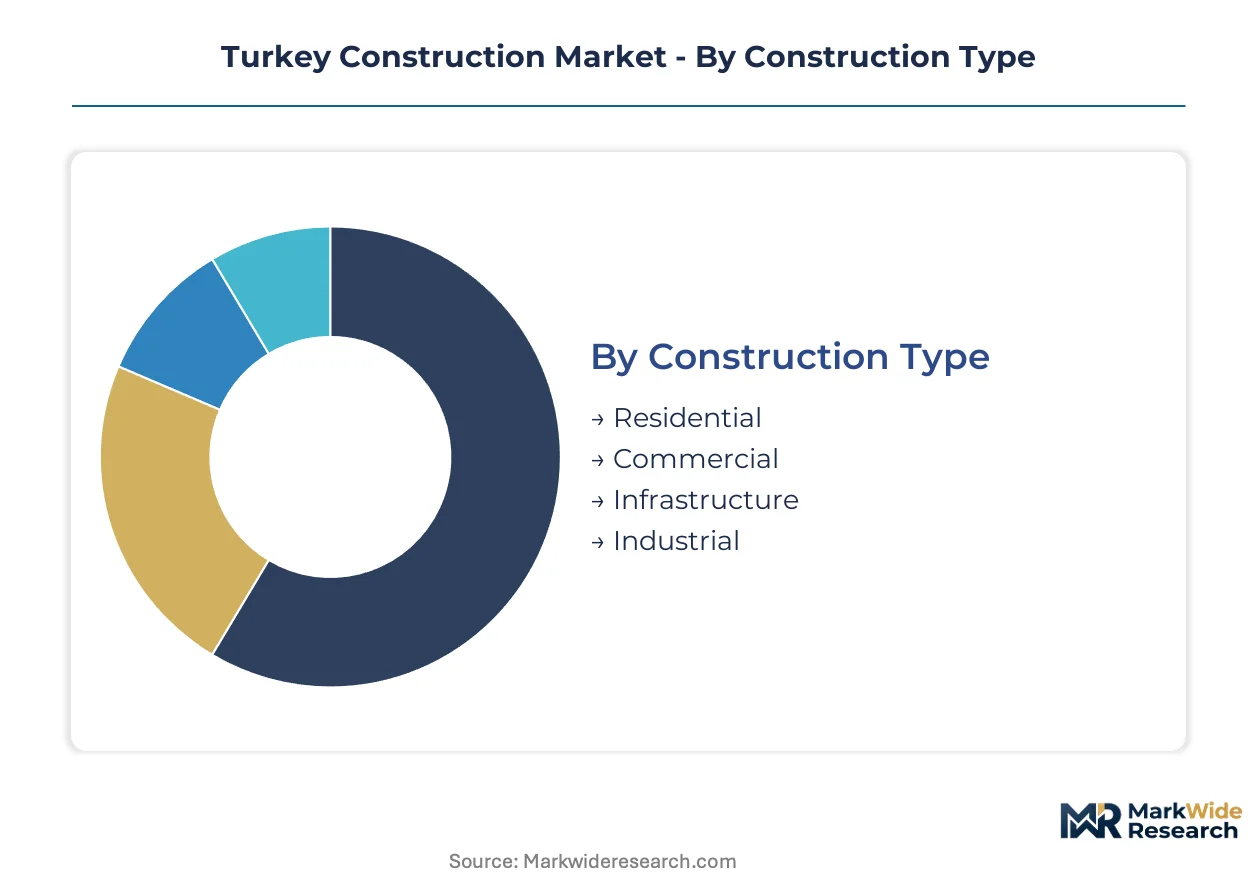
Segmentation reveals where capital concentrates across Turkey's construction sector. Material sourcing patterns and project scale thresholds determine contractor qualification requirements and margin structures.
Construction Type:
Margin pools concentrate in infrastructure megaprojects with decade-long execution timelines, while residential volume generates thinner returns through standardized delivery.
- Residential:Reinforced concrete frame construction dominates housing delivery across Marmara and Aegean provinces. TOKİ social housing programs in Gaziantep and Şanlıurfa drive demand for seismic-compliant mid-rise developments.
- Commercial:Mixed-use towers and retail complexes in Istanbul's finance districts command premium pricing for BREEAM-adjacent specifications. Ankara's healthcare infrastructure pipeline favors integrated design-build-operate-maintain contracts with performance guarantees.
- Infrastructure:Highway corridor expansions and Kanal İstanbul works concentrate the largest contract values with state-backed payment security.
- Industrial:Manufacturing facility construction clusters around Kocaeli and Bursa automotive corridors with specialized foundation engineering for heavy machinery loads.
The dominant share belongs to Residential, while Infrastructure is closing the gap fastest.
Material:
Cost tier stratification separates commodity inputs from engineered systems with certification premiums.
- Concrete:Self-compacting formulations with fiber-reinforced polymer additives bifurcate quality tiers in high-rise structural applications. TOKİ developments specify these mixes for accelerated formwork cycling in earthquake zones.
- Steel:Reinforcing bar and structural steel face import dependency on Black Sea supply routes, creating price volatility that reshapes contractor hedging strategies.
- Wood:Cross-laminated timber gains traction in low-rise residential and hospitality segments across Mediterranean coastal provinces with sustainable sourcing credentials.
- Glass:Curtain wall systems with thermal break specifications command specification in Ankara and Izmir premium commercial towers.
Concrete retains the volume leadership position, though Steel is expanding most quickly in infrastructure applications.
End User:
Customer type determines payment security profiles and contract duration structures across the project pipeline.
- Government:TOKİ and the General Directorate of Highways channel majority public spending through standardized tender protocols with TSE compliance mandates.
- Private Developers:Istanbul, Ankara, and Izmir premium commercial segments concentrate speculative development with REIT fundraising through Capital Markets Board rules.
- NGOs:International development organizations fund earthquake-resistant school and clinic construction in southeastern Anatolian provinces.
- Corporations:Energy and logistics majors commission industrial facilities with captive maintenance provisions.
Government contracts anchor the revenue base, while Private Developers are gaining share fastest in mixed-use segments.
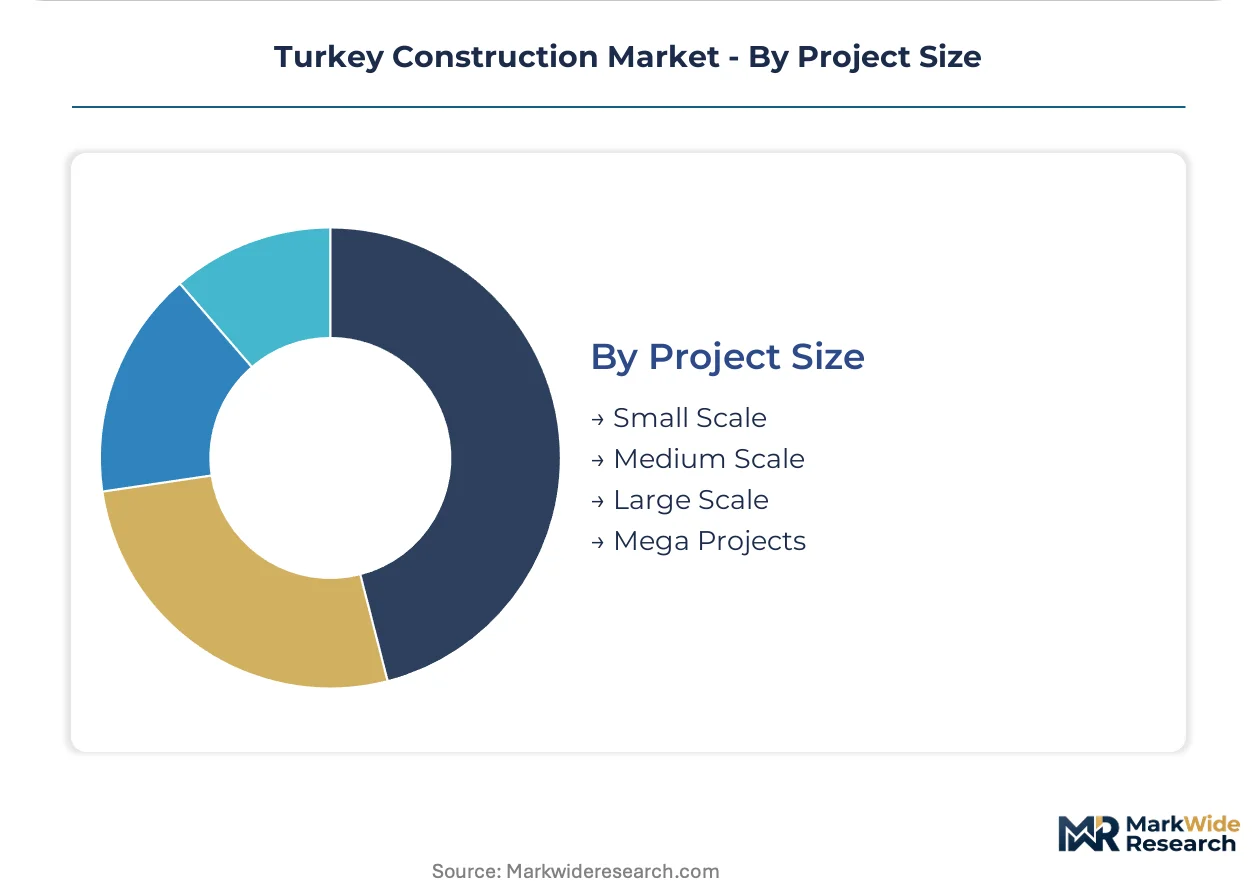
Project Size:
Scale thresholds filter contractor capabilities and financing access across the competitive landscape.
- Small Scale:Single-family residential and light commercial renovations dominate volume with localized contractor networks.
- Medium Scale:Multi-unit residential and mid-rise office buildings concentrate in urban renewal corridors with seismic retrofit specifications.
- Large Scale:Hospital and education facility tenders in Marmara provinces embed real-time structural health monitoring as technical minimums.
- Mega Projects:Hydropower dams and transportation corridors in eastern Anatolian basins require decade-long execution with integrated design-build delivery.
Small Scale projects occupy the volume leadership, yet Mega Projects are climbing the fastest as state-backed energy security priorities accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government buyers and private developers concentrate capital flows across Turkey's seven geographic regions. Each corridor presents distinct regulatory environments, material sourcing patterns, and project scale thresholds that reshape contractor qualification requirements.
Marmara Region
Istanbul's Kanal İstanbul megaproject and urban renewal corridors drive infrastructure and residential demand. The Ministry of Environment, Urbanization and Climate Change mandates TSE seismic compliance for all public tenders. Kocaeli and Bursa automotive clusters generate industrial facility construction with specialized foundation engineering.
Aegean Region
İzmir premium commercial towers command BREEAM-adjacent specifications for energy-efficient curtain wall systems. The Banking Regulation and Supervision Agency's REIT fundraising rules channel private developer capital into mixed-use developments. Manisa and Aydın manufacturing zones sustain mid-scale industrial construction.
Mediterranean Region
Antalya and Mersin hospitality developments adopt cross-laminated timber for low-rise sustainable construction. Council of State environmental impact assessments face extended review cycles for coastal projects. Adana's logistics hubs drive warehouse and distribution facility demand.
Central Anatolia Region
Ankara's healthcare infrastructure pipeline favors design-build-operate-maintain contracts with decade-long performance guarantees. The Capital Markets Board governs REIT capital access for speculative commercial development. Konya's industrial zones concentrate manufacturing facility construction.
Southeastern Anatolia Region
Gaziantep and Şanlıurfa TOKİ social housing programs drive seismic-compliant mid-rise residential delivery. International development organizations fund earthquake-resistant school and clinic construction. State-backed hydropower dams in eastern river basins require integrated design-build execution.
Turkey Construction Market Competitive Environment
Player mix skews toward vertically integrated conglomerates with captive quarry and batch-plant operations. The competitive structure tiers across ISO 9001-certified megaproject specialists, regional mid-cap contractors, and niche seismic retrofit providers. Strategic archetypes include state-backed infrastructure builders, healthcare-focused integrated service providers, and cross-border Central Asian contractors. Dominant competitive moves encompass backward integration into material supply and design-build-operate-maintain contract consolidation.
Among Turkey-based conglomerates, Cengiz İnşaat and Rönesans Holding occupy positions representing vertically integrated and healthcare-specialized archetypes respectively. Tekfen Holding exemplifies the cross-border oil and gas construction specialist tier. These anchors reflect the sector's bifurcation between domestic megaproject execution and international contract expansion.
| Leading Market Players |
|---|
| TAV Construction |
| Cengiz İnşaat |
| Rönesans Holding |
| Tekfen Holding |
| Yapı Merkezi Holding |
| Limak İnşaat |
| Alarko Contracting Group |
| Nurol Construction and Trading |
| ENKA İnşaat ve Sanayi A.Ş. |
| Others |
Value Chain & Pricing Dynamics
Self-compacting concrete with fiber-reinforced polymer additives is displacing conventional ready-mix formulations across Turkey's high-rise segment, simultaneously shifting batch-plant geography toward ISO-certified operators near Marmara urban corridors and compressing margins for non-certified suppliers locked into commodity pricing.
Pricing Analysis
Cost-plus contracts with steel rebar indexation to Black Sea import benchmarks dominate infrastructure megaprojects, insulating contractors from volatility while passing risk to government end users. Price differentiation hinges on TSE seismic certification tier and captive quarry access, with integrated operators commanding premiums over material-dependent rivals. Cost compression in residential concrete supply is intensifying because clinker production clusters in Afyon and Çanakkale face energy cost shocks. Private developers in Istanbul's premium commercial segment show lowest price sensitivity, whereas TOKİ social housing programs drive aggressive tender competition.
Supply Chain Analysis
Strategic stockpiling of reinforcing bar and structural steel precedes Black Sea shipping seasons, with contractors accumulating inventory ahead of Ukrainian supply route disruptions. Geographic supply concentration centers on Turkey's domestic clinker production, Ukrainian and Russian steel exports, and German polymer additive imports. Raw material dependencies encompass Portland cement, high-tensile rebar, and seismic-grade admixtures. Single-source vulnerability runs through Black Sea maritime chokepoints. Distribution feeds from captive quarry-to-project networks for vertically integrated conglomerates, while mid-tier contractors rely on spot-market ready-mix procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's construction sector is emerging from a post-earthquake cyclical trough, with urban renewal mandates and state-backed infrastructure commitments providing sustained demand visibility across the projection horizon.
For Market Incumbents: Compound defensive positioning through backward integration into Afyon and Çanakkale clinker production and ISO 9001 certification maintenance for TOKİ tender eligibility. Steel price volatility from Black Sea supply disruptions threatens margin stability. Captive batch-plant networks anchor pricing power against material-dependent competitors.
For New Entrants and Emerging Players: TSE seismic certification fast-tracks unlock participation in Marmara province hospital and education tenders where real-time structural health monitoring is now mandatory. White-space targets include modular prefabrication for earthquake-zone residential delivery and cross-border Central Asian transportation contracts. Partner with established German or Austrian engineering firms to accelerate credential recognition.
For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors vertically integrated operators with captive material supply and design-build-operate-maintain contract portfolios. Long-term viability rests on exposure to decade-long infrastructure execution timelines rather than cyclical residential development. Watch Council of State environmental ruling velocity for Black Sea coastal projects as the inflection signal redirecting capital toward inland urban renewal corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clinker Production | Captive supply from Afyon and Çanakkale insulates margins against energy cost volatility. |
| TSE Seismic Certification Investment | Compliance unlocks TOKİ and General Directorate of Highways tender participation. |
| Design-Build-Operate-Maintain Contract Pursuit | Ankara healthcare infrastructure pipeline favors integrated service providers with performance guarantees. |
| Cross-Border Central Asian Expansion | ISO 9001 credentials secure transportation and healthcare awards in Kazakh and Uzbek markets. |
| Modular Prefabrication Capability Buildout | Factory-built components address skilled welder scarcity while accelerating earthquake-zone delivery. |
Study Parameters
The analysis maps residential, commercial, infrastructure, and industrial construction segments, each validated through project directors at Cengiz İnşaat and Rönesans Holding, procurement officers at TOKİ, seismic engineers at TSE-certified consultancies, and ready-mix plant operators across Marmara and Aegean provinces. Secondary sources encompass Ministry of Environment, Urbanization and Climate Change building code filings, Banking Regulation and Supervision Agency construction sector exposure reports, Capital Markets Board REIT fundraising disclosures, and Turkish Statistical Institute building permit databases. Bottom-up project pipeline enumeration triangulates against top-down GDP construction value-add estimates.
Consistency checks validated volume and value outputs against General Directorate of Highways highway corridor expenditure plans and TOKİ social housing unit delivery schedules. Segmentation dimensions encompass construction type, material specification, end-user category, and project scale tier across the modeling period. CAGRs derive from regression against historical building permit issuance and fixed capital formation trends, with hydropower dam commissioning timelines and Kanal İstanbul phase completions as industry-specific trajectory inputs.
Underlying assumptions cover sustained government infrastructure commitment, stable Black Sea steel supply routes, and TSE protocol enforcement continuity, with deviation risk concentrated in Council of State environmental ruling tightening and energy cost shocks to domestic clinker production. Revision becomes warranted when steel import dependency or seismic retrofit mandate scope crosses thresholds altering contractor qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Qatar Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
South Korea Data Center Construction Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
Europe Prefab Wood Buildings Market
Building Construction
Vietnam Construction Market
Building Construction
Vertical Garden Construction Market