
 Turkey Commercial Construction Market | 2026-2036
Turkey Commercial Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Commercial Construction Market Insights
Project finance through build-operate-transfer and leasing structures is narrowing the field to contractors with balance-sheet depth and sovereign relationships. ENKA İnşaat ve Sanayi A.Ş. leverages its ENKA-PPP vehicle to anchor transport-linked commercial nodes. Rönesans Holding sustains competitive tension through hospital-to-hotel conversion expertise. Limak Holding dominates airport-adjacent logistics parks where land assembly requires state coordination.
Turkey commercial construction encompasses the design, engineering, and assembly of non-residential structures using reinforced concrete frames, composite steel decking, and curtain-wall glazing systems rated for local seismic zones. These facilities serve retail distribution, corporate tenancy, tourism accommodation, and third-party logistics operations. Office buildings command premium rents in Istanbul's Levent-Maslak axis while warehouses represent the fastest-growing project type as fulfillment networks expand. Green building systems attract ESG-linked financing from European development banks, though traditional reinforced concrete remains the volume leader across Anatolian secondary cities.
Turkey's Ministry of Environment, Urbanization and Climate Change enforces seismic design codes under the Disaster Risk Reduction Regulation, while the Capital Markets Board governs REIT disclosures that channel institutional capital into commercial assets. The Turkish Standards Institution certifies structural steel and concrete admixtures for market access compliance. Stakeholders must monitor whether earthquake-zone insurance mandates shift developer preferences toward modular building systems with faster depreciation schedules.
Market Dynamics
Seismic retrofit mandates from Turkey's Ministry of Environment, Urbanization and Climate Change are forcing wholesale reconstruction of existing commercial stock, redirecting contractor capacity from greenfield development toward structural reinforcement and code-compliant rebuilds.
Growth Catalysts
- E-commerce fulfillment networks:Third-party logistics operators are commissioning cold-chain warehouses across Anatolia's secondary cities to serve next-day delivery expectations.
- Disaster Risk Reduction Regulation:Mandatory structural assessments of pre-2000 commercial buildings are generating sustained engineering and reconstruction demand.
- Steel-concrete composite frames:These systems now dominate mid-rise office construction in Istanbul's Levent corridor due to faster erection cycles.
Market Restraints
- Imported structural steel volatility:Turkish contractors face margin compression from lira-denominated procurement exposure to Black Sea metallurgical supply.
- Cement sector oligopoly:Domestic clinker production concentrates in three holding groups, limiting price negotiation leverage for mid-tier developers.
- Seismic zone insurance mandates:Mandatory commercial property coverage under Turkey's Disaster and Emergency Management Authority raises total project cost bases.
Strategic Opportunities
- Izmir industrial free zones:Port-adjacent land assembly for automotive supplier parks remains underdeveloped relative to Istanbul capacity constraints.
- European Bank for Reconstruction and Development green financing:LEED-equivalent certification unlocks preferential lending for logistics and office assets.
- Building Information Modeling and prefabrication:Convergence of these technologies compresses design-to-occupancy timelines for repetitive hotel and retail formats.
Industry Challenges
- Structural engineer scarcity:Turkey's Council of Higher Education has not expanded seismic-specialist graduate programs to match retrofit mandate volumes.
- Capital Markets Board REIT disclosure timelines:Extended approval cycles for real estate investment trusts delay project financing closes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Commercial Construction Market |
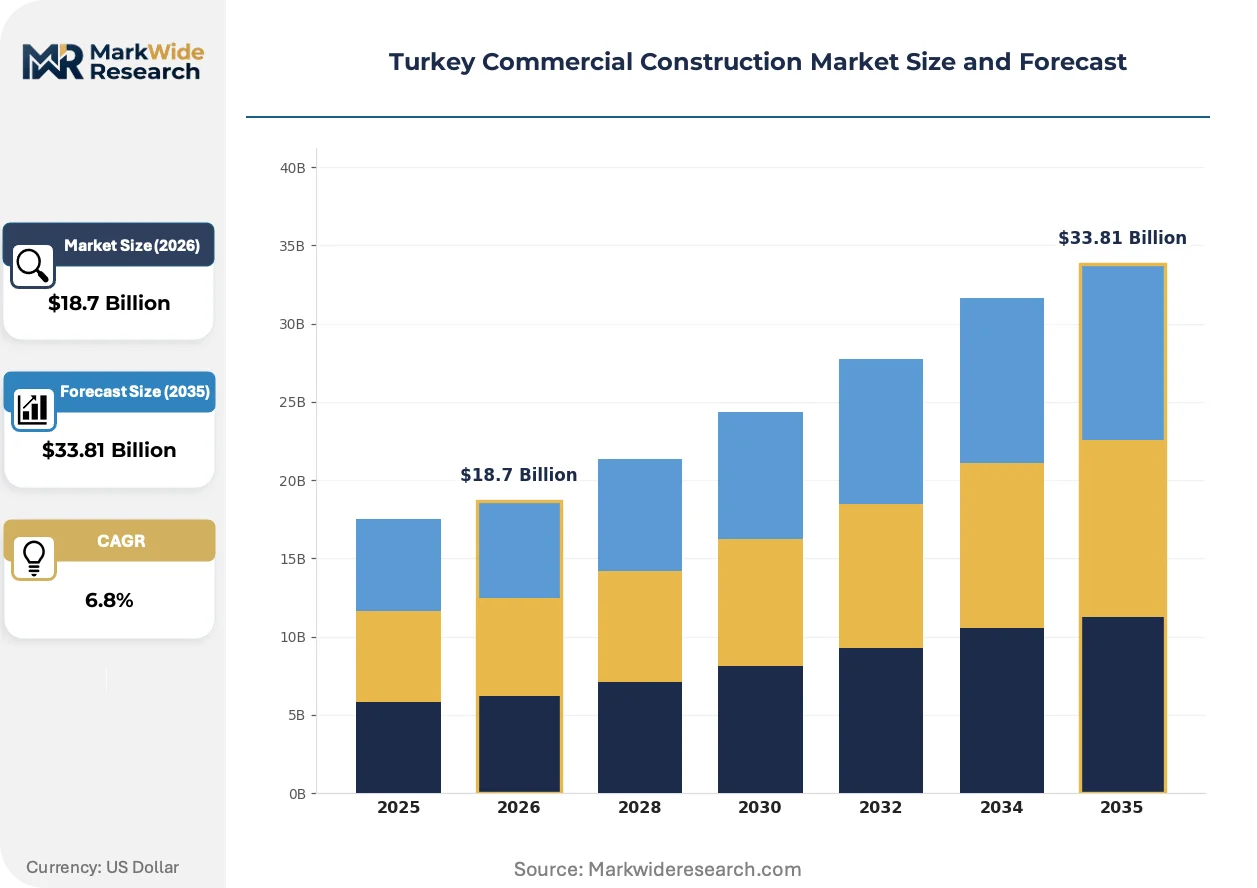
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Office Buildings, Retail Spaces, Hospitality Venues, Warehouses Construction Material: Concrete, Steel, Wood, Glass End User: Government, Corporations, Private Investors, Developers Building System: Modular, Traditional, Smart Building, Green Building |
| Companies Covered | ENKA İnşaat ve Sanayi A.Ş., Rönesans Holding, Limak Holding, Yapı Merkezi Holding, GAP İnşaat, Tekfen Construction, Kolin Construction, Nurol Construction, IC İçtaş Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Commercial Construction Market Trends and Innovations
Digital fabrication and modular assembly are compressing traditional construction timelines, while regulatory pressure on embodied carbon and seismic performance forces material specification changes across Turkey's commercial building stock.
Cross-laminated timber and engineered bamboo composites are collapsing conventional concrete-steel dominance in low-rise commercial and hospitality projects. Boutique hotel developers in Antalya and Bodrum are specifying mass timber for accelerated permitting and differentiated guest experience. The structural consequence is collapsing the traditional 18-month hotel construction cycle toward 10-month turnkey delivery, pressuring conventional contractors to retool or exit the segment.
Turkey's Ministry of Environment, Urbanization and Climate Change has tightened embodied carbon disclosure requirements for public-procured commercial buildings above 10,000 square meters. Developers must now submit Environmental Product Declarations for structural concrete and steel to qualify for state-leased land tenders. Istanbul's A-grade office pipeline is most affected, with several planned towers redesigning for lower-carbon concrete mixes to maintain eligibility.
Institutional investors are consolidating direct development relationships, bypassing traditional general contractor intermediaries. Pension funds and sovereign wealth vehicles now contract design-build firms for core-plus logistics assets in Ankara and Bursa. This disintermediation is most visible in the warehouse sector, where build-to-suit agreements with e-commerce operators specify performance guarantees that only integrated design-build entities can underwrite.
Turkey Commercial Construction Market Segmentation
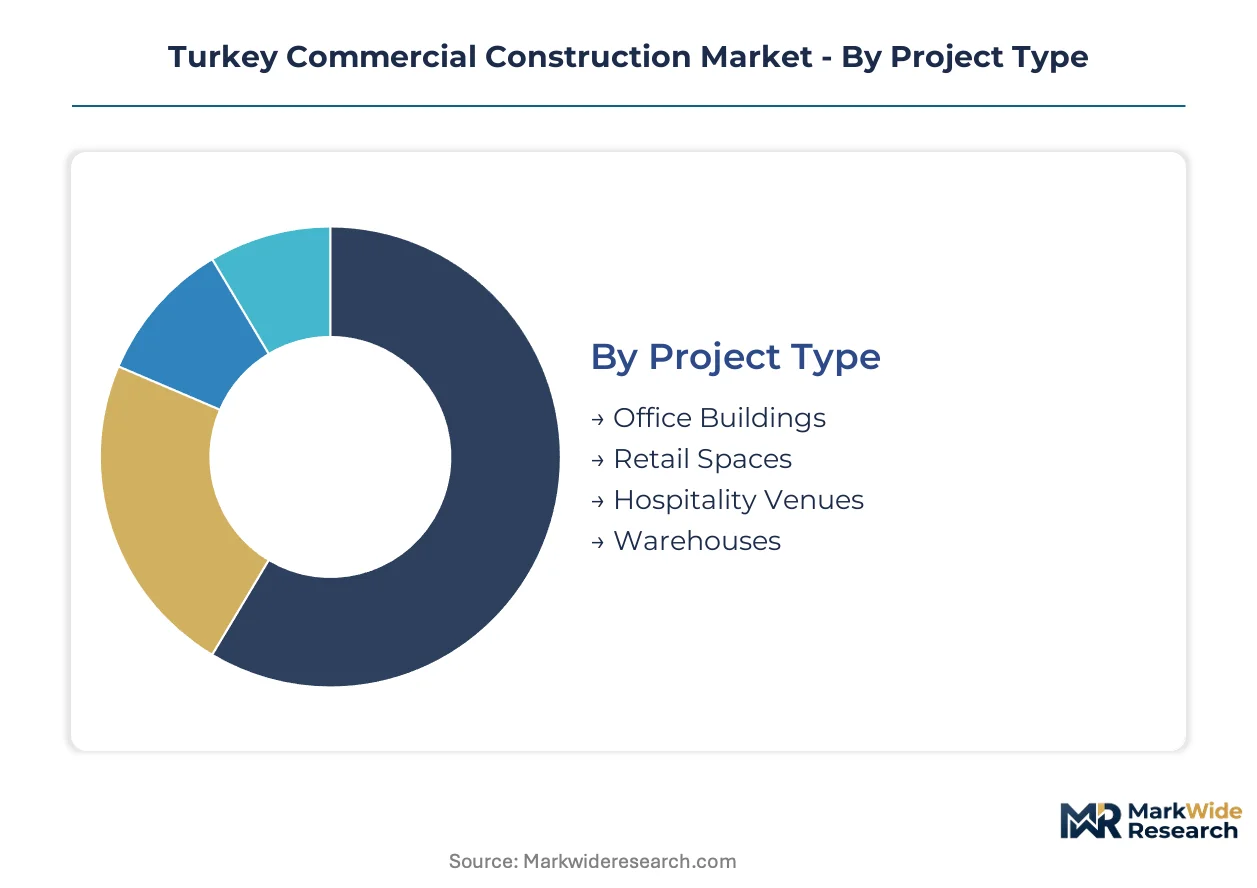
Segmentation in Turkey's commercial construction market reveals how seismic retrofit mandates, e-commerce logistics expansion, and green financing eligibility reshape contractor specialization and material procurement strategies across distinct project categories.
Project Type:
Application focus determines contractor capability requirements and financing structure access in Turkey's commercial pipeline.
- Office Buildings:Steel-concrete composite frames dominate Istanbul's Levent-Maslak corridor where A-grade specifications command premium tenancy rates. The Ministry of Environment, Urbanization and Climate Change now mandates embodied carbon disclosures for public-leased towers above 10,000 square meters, forcing redesigns toward lower-carbon concrete mixes.
- Warehouses:Cold-chain fulfillment centers commissioned by third-party logistics operators represent the steepest expansion trajectory across Anatolia's secondary cities, with steel portal frames preferred for rapid erection cycles and seismic resilience.
- Retail Spaces:Shopping mall developers in Istanbul and Izmir prioritize curtain-wall glazing systems with seismic-rated connections.
- Hospitality Venues:Boutique hotel projects in Antalya and Bodrum are adopting mass timber for accelerated permitting and compressed construction timelines.
Office Buildings hold installed capacity. Warehouses is rotating up the share rankings.
Construction Material:
Supply concentration and import exposure differentiate material selection economics across Turkey's commercial sites.
- Concrete:Reinforced concrete frames remain the volume leader across Anatolian secondary cities, though domestic clinker production concentrates in three holding groups that limit mid-tier developer price negotiation leverage. Seismic retrofit mandates are redirecting substantial contractor capacity toward structural reinforcement using high-performance concrete admixtures.
- Steel:Black Sea metallurgical supply exposes Turkish contractors to lira-denominated procurement volatility and margin compression, particularly for imported structural sections specified in airport-adjacent logistics parks.
- Glass:Curtain-wall glazing systems rated for local seismic zones command specification in Istanbul's A-grade office pipeline.
- Wood:Cross-laminated timber and engineered bamboo composites are collapsing conventional construction cycles in low-rise hospitality projects.
Concrete dominates existing stock. Steel is rotating up the share rankings.
End User:
Balance-sheet depth and sovereign relationship access determine which stakeholder categories can execute complex build-operate-transfer structures.
- Corporations:Direct development relationships with institutional investors are bypassing traditional general contractor intermediaries, particularly for build-to-suit logistics assets in Ankara and Bursa where performance guarantees require integrated design-build underwriting.
- Government:State-leased land tenders now require Environmental Product Declarations for structural materials, filtering developer eligibility.
- Private Investors:Capital Markets Board REIT disclosure timelines create extended approval cycles that delay project financing closes.
- Developers:Mid-tier developers face squeezed margins from cement oligopoly pricing and mandatory seismic zone insurance mandates.
Corporations hold installed capacity. Government is rotating up the share rankings.
Building System:
Technology maturity and certification eligibility separate system categories in Turkey's evolving commercial construction standards.
- Green Building:LEED-equivalent certification unlocks preferential lending from the European Bank for Reconstruction and Development for logistics and office assets, concentrating demand in Istanbul's premium pipeline where ESG-linked financing differentiates project viability.
- Smart Building:Integrated building automation systems are specified in A-grade office towers targeting institutional tenancy.
- Modular:Prefabrication convergence with Building Information Modeling compresses design-to-occupancy timelines for repetitive hotel and retail formats.
- Traditional:Concrete-dominant methods persist where seismic retrofit mandates redirect engineering capacity from greenfield development.
Traditional systems hold installed capacity. Green Building is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey's Ministry of Environment, Urbanization and Climate Change has deployed seismic retrofit mandates and embodied carbon disclosure requirements that redirect construction investment toward code-compliant rebuilds and green-certified new builds. These policy instruments concentrate capital flows in high-risk seismic zones and state-leased land tenders.
Marmara Region
Istanbul's Levent-Maslak corridor generates premium office demand from financial services and technology tenants requiring A-grade specifications. The Ministry mandates Environmental Product Declarations for public-leased towers exceeding 10,000 square meters. Contractors here redesign projects for lower-carbon concrete mixes to maintain eligibility for state tenders.
Aegean Region
Izmir's industrial free zones attract automotive supplier parks and port-adjacent logistics assembly. The Disaster Risk Reduction Regulation forces structural assessments of pre-2000 commercial stock. Land assembly in Alsancak and Çiğli requires coordination with the Ministry for seismic-compliant rebuilds of existing warehouse facilities.
Mediterranean Region
Antalya and Bodrum hospitality developers specify mass timber for accelerated permitting and compressed construction timelines. The Ministry's tightened embodied carbon rules affect boutique hotel projects seeking state-leased coastal land. Timber specialists collapse traditional 18-month cycles toward 10-month turnkey delivery.
Central Anatolia Region
Ankara's logistics corridors experience build-to-suit demand from e-commerce operators commissioning cold-chain warehouses. The Capital Markets Board governs REIT disclosures that channel institutional capital into commercial assets. Pension funds contract design-build firms directly for core-plus warehouse assets in Sincan and Etimesgut.
Black Sea Region
Samsun and Trabzon port cities face imported structural steel volatility from Black Sea metallurgical supply exposure. The Turkish Standards Institution certifies structural steel for market access compliance. Contractors here negotiate lira-denominated procurement contracts that compress margins on steel-intensive logistics projects.
Turkey Commercial Construction Market Competitive Landscape
On the supply side, the industry is consolidating around contractors with balance-sheet depth and sovereign relationship access capable of executing build-operate-transfer structures. The field narrows to holding groups with dedicated PPP vehicles and hospital-to-hotel conversion expertise. Three strategic archetypes dominate: state-linked infrastructure specialists, diversified conglomerates with vertical construction arms, and design-build integrators serving institutional capital. Competitive tension centers on M&A activity to secure engineering capacity and strategic partnerships with European development banks for green financing eligibility.
Among Turkey-based contractors, ENKA İnşaat ve Sanayi A.Ş., Rönesans Holding, and Limak Holding occupy distinct positions within this structure. ENKA exemplifies the state-linked infrastructure archetype through its dedicated PPP vehicle anchoring transport-linked commercial nodes. Rönesans represents diversified holding capability spanning hospital conversions and hospitality assets. Limak sits within the airport-adjacent logistics specialization where land assembly demands sovereign coordination. These three anchors demonstrate how contractor differentiation now depends on financing structure access rather than pure construction execution.
| Leading Market Players |
|---|
| ENKA İnşaat ve Sanayi A.Ş. |
| Rönesans Holding |
| Limak Holding |
| Yapı Merkezi Holding |
| GAP İnşaat |
| Tekfen Construction |
| Kolin Construction |
| Nurol Construction |
| IC İçtaş Construction |
| Others |
Pricing and Supply Chain Analysis
Imported structural steel volatility from Black Sea metallurgical supply exposes Turkish contractors to lira-denominated procurement risk that widens pricing spreads between domestically sourced concrete-dominant projects and steel-intensive logistics developments. This currency-driven input cost divergence forces developers to recalibrate material specifications and supplier relationships across project portfolios.
Pricing Analysis
Certification level creates the primary spread between LEED-equivalent green building premiums and traditional reinforced concrete baselines. Project-based contracting dominates, with price differentiation driven by seismic zone insurance mandates and embodied carbon disclosure compliance for state-leased tenders. Cost compression in steel-intensive segments is intensifying because lira volatility against dollar-denominated Black Sea imports erodes fixed-price contract viability. Mid-tier developers exhibit highest price sensitivity due to cement oligopoly pricing power, while sovereign-linked contractors with PPP vehicle access face least pressure.
Supply Chain Analysis
Export-control regimes on advanced seismic monitoring equipment and Building Information Modeling software limit technology flows into Turkish engineering capacity. Geographic supply concentration centers on domestic clinker production from three holding groups, Ukrainian and Russian metallurgical supply for structural sections, and German-engineered curtain-wall systems. Raw material dependencies include high-performance concrete admixtures, seismic-rated steel connections, and low-carbon cement formulations. Single-source vulnerability runs through Black Sea steel procurement corridors. Distribution runs through state-coordinated land assembly for airport-adjacent logistics parks and direct institutional contracting for build-to-suit warehouse assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pension funds and sovereign wealth vehicles that now contract design-build firms directly, bypassing traditional general contractor intermediaries and compressing margins for conventional construction execution.
For Market Incumbents: Build sovereign relationship moats through dedicated PPP vehicles that anchor transport-linked commercial nodes. Deepen engineering capacity reserves to absorb seismic retrofit mandate volumes before structural specialist scarcity worsens. Defend against disintermediation by integrating design-build capabilities that underwrite performance guarantees for institutional capital. For New Entrants and Emerging Players: Izmir's industrial free zones offer underpenetrated port-adjacent land assembly for automotive supplier parks relative to Istanbul capacity constraints. Target boutique hospitality in Antalya and Bodrum where mass timber specialization collapses conventional construction cycles and escapes cement oligopoly pricing. Enter through design-build partnerships with European development banks that unlock green financing eligibility for LEED-equivalent logistics assets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors contractors with balance-sheet depth and state coordination capabilities. Long-term viability across the projection horizon hinges on seismic retrofit mandate sustainability and e-commerce logistics expansion durability. Acquisition target archetypes include design-build integrators with institutional capital relationships and modular construction technology holders. Monitor Capital Markets Board REIT disclosure timeline reforms as the inflection signal for financing velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Retrofit Capacity Expansion | Captures mandated reconstruction demand from Turkey's Disaster Risk Reduction Regulation. |
| Green Certification Investment | Unlocks European Bank for Reconstruction and Development preferential lending for logistics assets. |
| Mass Timber Specialization | Collapses hotel construction cycles in Antalya and Bodrum coastal markets. |
| Design-Build Integration | Enables direct institutional contracting and performance guarantee underwriting for warehouse projects. |
| PPP Vehicle Development | Secures sovereign coordination access for airport-adjacent logistics land assembly. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial construction project directors, seismic engineering specialists, Ministry of Environment procurement officers, and institutional capital allocation managers. Secondary validation drew from Turkey's Capital Markets Board REIT disclosures, Turkish Standards Institution certification records, European Bank for Reconstruction and Development project finance databases, and Disaster Risk Reduction Regulation compliance filings. Bottom-up project pipeline aggregation and top-down sectoral expenditure analysis were triangulated to reconcile volume estimates.
Calibration against historical retrofit mandate execution rates and logistics absorption patterns anchored the analytical framework across the analysis window. Segmentation dimensions modeled include project type, construction material, end user category, building system technology, and regional regulatory cluster. CAGRs were derived from trend extrapolation moderated by policy implementation lags. Industry-specific forecast inputs incorporated e-commerce fulfillment network expansion trajectories and seismic zone insurance mandate coverage penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-linked infrastructure specialists or accelerated modular technology adoption by new entrants would shift outcomes. Material shifts in lira stability against dollar-denominated steel procurement or wholesale revision of embodied carbon disclosure thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
China Building Construction Market
Building Construction
Thailand Construction Market
Building Construction
Early Production Facility Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
Poland Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
Eastern Europe Construction Market
Building Construction
United States Commercial Construction Market
Building Construction
North America Construction Market
Building Construction
Cold Storage Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
India Commercial Construction Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market