
 Plastic-Metal Hybrids Market | 2026-2036
Plastic-Metal Hybrids Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic-Metal Hybrids Market Analytics
Aftermarket service revenue for bonded hybrid component repair and refurbishment is rewriting how suppliers capture lifetime value from automotive and aerospace installations. BASF leverages its polymer science depth to anchor high-performance composite formulations for under-the-hood applications. Covestro AG sustains competitive positioning through specialized polyurethane-metal bonding systems that dominate European automotive interiors. DuPont differentiates via fluoropolymer-metal laminates that occupy premium niches in medical device housings.
Plastic-metal hybrids are engineered material systems combining thermoplastic or thermoset matrices with metallic substrates through mechanical interlocking, adhesive bonding, or overmolding processes, typically achieving weight reductions of 20-40% versus all-metal equivalents while preserving structural rigidity and electromagnetic shielding capacity. Their primary purpose is to satisfy simultaneous demands for lightweighting, functional integration, and cost-efficient manufacturability in mass-production environments. Metal-plastic composites lead volume adoption in automotive crash structures where load-bearing requirements persist, while additive manufacturing represents the fastest-expanding technology segment as aerospace manufacturers qualify topology-optimized hybrid brackets with embedded metallic load paths. Molded parts remain the most mature product category, with margin pools concentrating in coated components that combine corrosion-resistant metallic skins with chemically resistant polymer cores for medical equipment suppliers.
EPA fuel-economy standards and the EU F-Gas Regulation shape material selection by penalizing weight-intensive designs and restricting certain bonding-agent chemistries, while REACH compliance mandates disclosure of adhesive constituents across European supply chains. FDA device-grade material requirements and ISO 10993 biocompatibility protocols govern medical applications in the United States and internationally, creating certification barriers that favor established compounders with regulatory dossiers. Stakeholders must monitor evolving collision-repair protocols and end-of-life recyclability mandates as jurisdictions develop shredding and separation standards for multi-material assemblies.
Market Dynamics
Automotive OEMs are reconfiguring their lightweighting roadmaps around hybrid material systems as EPA fuel-economy standards tighten and battery-electric architectures demand mass reduction without sacrificing crashworthiness. This structural pressure is compressing development cycles and forcing tier-one suppliers to integrate polymer science capabilities that previously sat outside their core metallurgical expertise.
Growth Catalysts
- EPA Fuel-Economy Standards:Corporate Average Fuel Economy mandates in the United States are compelling Detroit automakers to substitute hybrid brake pedals, oil pans, and front-end modules for pure steel stampings, creating pull-through demand for bonding-grade engineering polymers.
- Topology-Optimized Additive Manufacturing:Aerospace manufacturers are qualifying laser-sintered hybrid brackets with embedded titanium load paths, reducing buy-to-fly ratios while maintaining fatigue performance for satellite and unmanned aerial vehicle structures.
- German Precision Manufacturing Clusters:Stuttgart and Munich anchor concentrated development ecosystems where Fraunhofer institutes, BASF formulation labs, and BMW Group procurement teams co-locate, accelerating prototype-to-production cycles for under-the-hood hybrid components.
Market Restraints
- Adhesive Raw Material Volatility:Polyurethane bonding systems depend on isocyanate and polyol feedstocks whose pricing tracks crude oil and natural gas indices, compressing margin predictability for European automotive interior suppliers.
- Recyclability Infrastructure Gaps:Multi-material assemblies require shredding and density-separation capabilities that remain concentrated in German and Japanese industrial waste streams, limiting end-of-life options in North American markets lacking dedicated hybrid-component recycling lines.
- All-Aluminum Substitution Threat:Cast aluminum crash structures from Novelis and Constellium are reclaiming share in luxury vehicle segments where OEMs prioritize single-material recyclability over maximum weight reduction.
Strategic Opportunities
- Indian Automotive Localization:Maruti Suzuki and Tata Motors are qualifying hybrid pedal boxes and steering column brackets for domestic compact vehicle platforms, creating first-mover advantages for compounders establishing technical service laboratories in Pune and Chennai.
- EU F-Gas Regulation Tailwinds:Restrictions on hydrofluorocarbon blowing agents for polyurethane foams are accelerating adoption of physical foaming and nitrogen-assisted molding technologies that improve metal-polymer interfacial bonding.
- Medical Device Channel Expansion:Fluoropolymer-metal laminates for MRI-compatible housings and surgical instrument handles are penetrating distributor networks serving ambulatory surgical centers, bypassing traditional hospital procurement committees.
Industry Challenges
- Multi-Material Simulation Expertise Gap:Finite element analysis of hybrid assemblies requires coupled thermal-mechanical solvers and adhesive degradation models that few tier-two suppliers have integrated into their engineering workflows.
- ISO 10993 Certification Timelines:Biocompatibility testing for implantable device housings extends qualification cycles to 18-24 months, freezing out compounders lacking pre-submitted regulatory dossiers with FDA and notified bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic-Metal Hybrids Market |
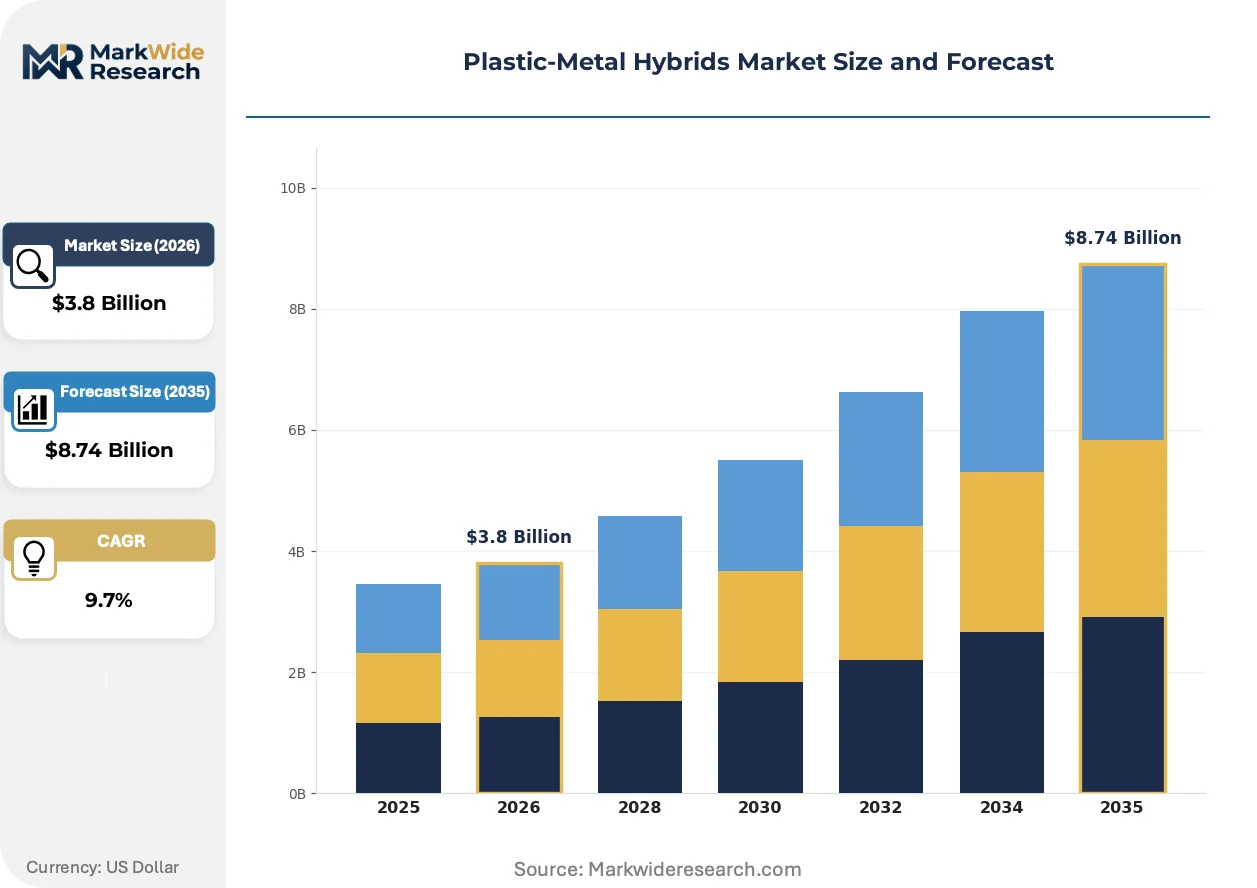
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal-Plastic Composites, Molded Parts, Assemblies, Coated Components Application: Automotive Interiors, Aerospace Structures, Consumer Electronics, Medical Devices Technology: Injection Molding, Extrusion, Additive Manufacturing, Hybrid Joining End User: Automotive OEMs, Aerospace Manufacturers, Electronics Firms, Medical Equipment Suppliers |
| Companies Covered | BASF, Covestro AG, DuPont, Celanese Corporation, SABIC, Solvay, Evonik, Arkema, Visteon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic-Metal Hybrids Market Evolving Landscape
Digital thread technologies are collapsing the boundary between material design and manufacturing execution, enabling real-time adjustment of bonding parameters based on in-line surface energy measurements. This convergence is redefining how hybrid component suppliers guarantee performance consistency across dispersed production networks.
Process analytical technology is digitizing quality assurance for adhesive bonding operations. Automotive tier-one suppliers are deploying inline infrared spectroscopy and laser profilometry to verify surface preparation and cure kinetics on every bonded assembly, compressing defect detection from batch release to real-time feedback loops. This capability is digitizing warranty risk management and enabling predictive maintenance of bonding equipment.
REACH Article 33 disclosure requirements are forcing supply chain transparency for adhesive constituents across European automotive and medical device value chains. Compounders must now document Substances of Very High Concern concentrations exceeding 0.1% w/w in hybrid assemblies, driving substitution of legacy epoxy hardeners and accelerating qualification of bio-based polyurethane systems. German medical equipment manufacturers are responding by consolidating supplier bases to reduce documentation burden.
Aftermarket service unbundling is fragmenting traditional OEM captive repair networks. Independent collision repair shops in the United States are acquiring induction heating equipment and structural adhesive dispensing systems to service bonded hybrid components, displacing dealership monopoly on warranty repairs. This pattern is most visible in California and Texas, where insurer-direct repair programs are steering volume toward certified independent facilities.
Plastic-Metal Hybrids Market Segmentation
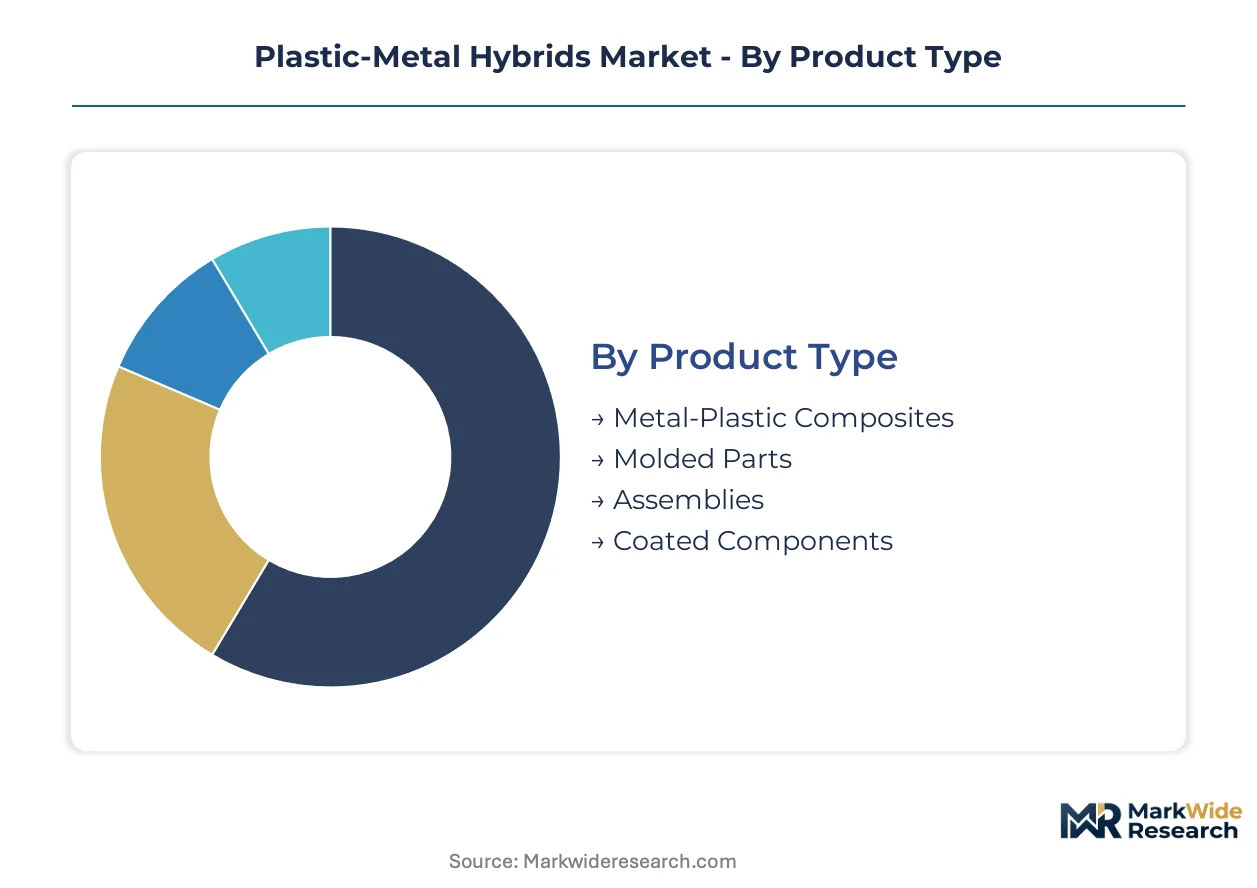
Segmentation in plastic-metal hybrids reveals how material science capabilities align with distinct performance requirements and manufacturing economics across end-use verticals. Each dimension—product form, application environment, production technology, and customer type—carries different margin structures and qualification barriers.
Product Type:
Cost tier differentiation separates commodity-form hybrids from engineered assemblies with embedded functional integration.
- Metal-Plastic Composites:Continuous fiber-reinforced thermoplastic tapes bonded to aluminum or steel substrates deliver specific stiffness targets for structural load paths. German automotive OEMs specify these for battery enclosure frames where crash energy absorption must coexist with electromagnetic shielding.
- Molded Parts:Overmolded metallic inserts in polyamide or PBT matrices dominate high-volume production of brake pedals and steering column brackets. Stuttgart-based tier-one suppliers operate captive molding cells to protect proprietary bonding process IP.
- Assemblies:Multi-component hybrid systems integrate stamped metal carriers with injection-molded functional elements for HVAC housings and fluid management modules.
- Coated Components:Thin metallic skins laminated to polymer cores serve corrosion-critical medical equipment housings requiring repeated sterilization cycles.
Molded parts hold installed capacity. Metal-plastic composites are rotating up the share rankings.
Application:
Application environment dictates material specification severity, from cosmetic interior surfaces to structural airframe elements.
- Automotive Interiors:Hybrid brackets and pedal assemblies reduce mass in cockpit modules where haptic quality and vibration damping matter. EPA fuel-economy credits drive substitution of these components for steel stampings in Detroit-produced light trucks.
- Aerospace Structures:Topology-optimized hybrid brackets with embedded titanium load paths serve satellite and UAV applications where buy-to-fly ratio reduction justifies premium unit economics. Additive manufacturing qualification timelines here extend 24-36 months.
- Consumer Electronics:Metal-polymer hybrid chassis combine electromagnetic interference shielding with injection-molded antenna windows for 5G-enabled devices.
- Medical Devices:Fluoropolymer-metal laminates for MRI-compatible surgical instrument handles must satisfy ISO 10993 biocompatibility protocols, creating multi-year qualification moats.
Automotive interiors hold installed capacity. Aerospace structures are rotating up the share rankings.
Technology:
Process maturity separates high-throughput molding operations from emerging additive workflows with distinct capital intensity profiles.
- Injection Molding:Two-shot and insert molding processes bond engineering polymers to pretreated metallic substrates at cycle times under 60 seconds. German precision manufacturing clusters around Stuttgart anchor global process development for under-the-hood hybrid components.
- Hybrid Joining:Laser-assisted tape placement and induction bonding integrate continuous fiber reinforcement with metallic load-bearing elements for aerospace primary structures.
- Extrusion:Continuous pultrusion of metal-polymer profiles serves linear structural elements with consistent cross-sections.
- Additive Manufacturing:Laser powder bed fusion with in-situ polymer infiltration enables topology-optimized brackets with embedded metallic reinforcement, expanding most quickly as aerospace manufacturers qualify satellite components.
Injection molding holds installed capacity. Additive manufacturing is rotating up the share rankings.
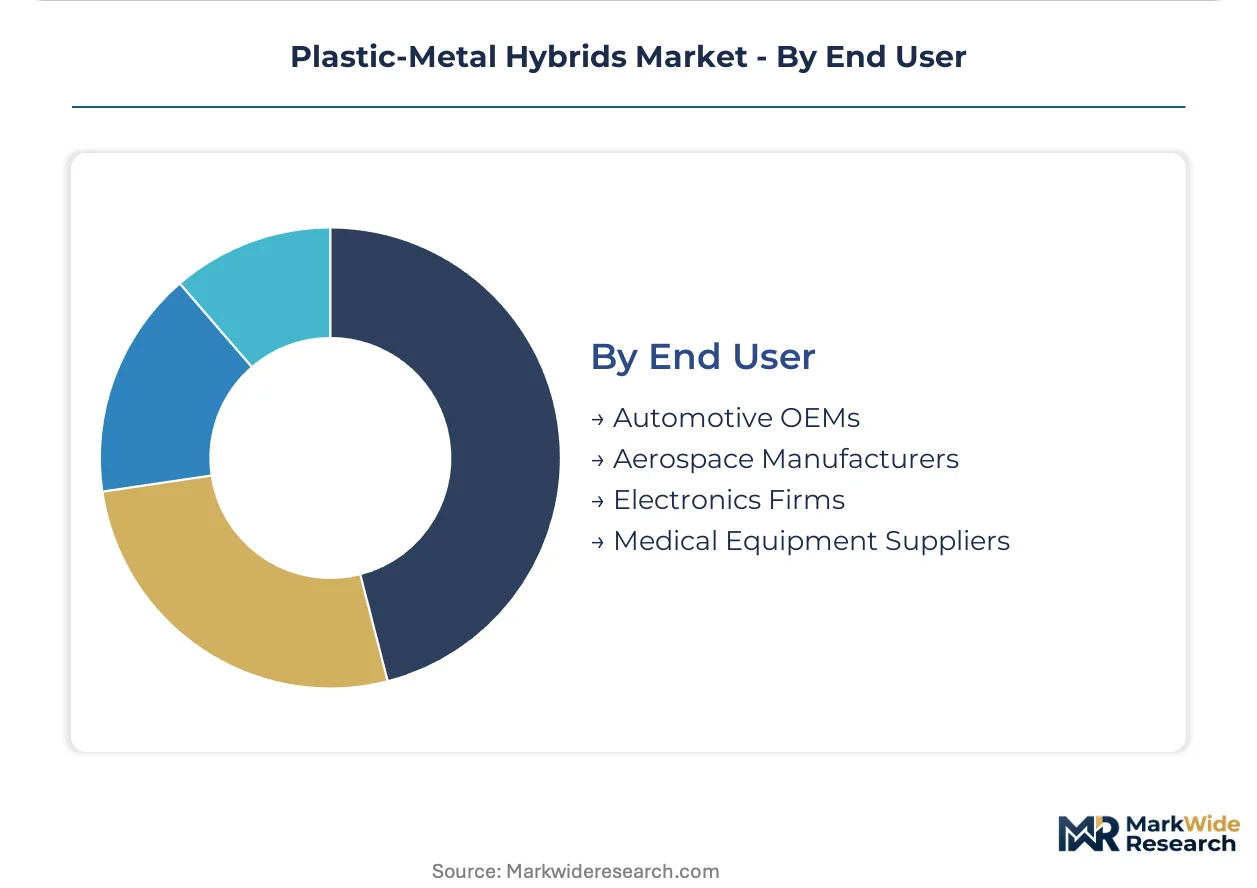
End User:
Customer type concentration determines procurement leverage, with automotive OEMs extracting scale economics and medical suppliers accepting premium pricing for regulatory dossiers.
- Automotive OEMs:Detroit and German premium manufacturers specify hybrid brake pedals, oil pans, and front-end modules to satisfy Corporate Average Fuel Economy mandates. Tier-one suppliers face compressed development cycles as battery-electric architectures demand mass reduction without sacrificing crashworthiness.
- Medical Equipment Suppliers:Device manufacturers source coated hybrid housings for surgical instruments and diagnostic equipment where FDA device-grade material requirements govern supplier qualification.
- Aerospace Manufacturers:Satellite and UAV producers qualify hybrid brackets for weight-critical applications with extended fatigue life requirements.
- Electronics Firms:Consumer device assemblers specify hybrid chassis for 5G antenna integration and thermal management.
Automotive OEMs hold installed capacity. Medical equipment suppliers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: German automakers prioritize crash-optimized battery enclosures, US manufacturers emphasize EPA-driven brake pedal substitution, and Japanese suppliers concentrate on precision-molded steering components. These demand-mix differences shape where capacity investments flow and which regulatory frameworks dominate supplier qualification timelines.
Germany
Stuttgart and Munich anchor Europe's densest precision manufacturing ecosystem for under-the-hood hybrid components. REACH Article 33 disclosure mandates force compounders to document adhesive constituent concentrations exceeding 0.1% w/w, accelerating substitution of legacy epoxy systems. Fraunhofer institutes co-located with BASF formulation labs compress prototype-to-production cycles for BMW Group procurement teams.
United States
Detroit automakers specify hybrid brake pedals, oil pans, and front-end modules to satisfy Corporate Average Fuel Economy mandates. EPA fuel-economy standards tighten annually, compelling material substitution away from pure steel stampings. Independent collision repair shops in California and Texas acquire induction heating equipment to service bonded hybrid components, fragmenting traditional OEM captive repair networks.
Japan
Tokyo-Nagoya industrial corridors concentrate development of precision-molded steering column brackets and pedal boxes. METI industrial standards govern adhesive bonding qualification protocols for automotive tier-one suppliers. Toyota and Honda procurement teams source from compounders with captive technical service laboratories in Osaka and Yokohama.
China
Yangtze River Delta manufacturing clusters scale insert-molding operations for domestic electric vehicle platforms. MIIT new energy vehicle mandates accelerate lightweighting roadmaps for battery-electric architectures. BYD and NIO procurement teams qualify hybrid structural components from compounders with localized bonding process IP in Shanghai and Suzhou.
India
Pune and Chennai technical service laboratories support qualification of hybrid pedal boxes for Maruti Suzuki and Tata Motors compact vehicle platforms. BIS automotive material standards govern adhesive selection for under-the-hood applications. Domestic OEMs prioritize cost-optimized bonding systems that satisfy emerging crashworthiness requirements without premium European formulation costs.
Plastic-Metal Hybrids Market Competitive Landscape
Capability concentration sits with specialized compounders possessing polymer-metallurgy interface expertise; scale advantage sits with diversified chemical majors with global formulation networks. The vendor base stratifies into three tiers: integrated polymer science leaders, regional bonding-system specialists, and captive tier-one supplier operations. Consolidation pressure intensifies as automotive OEMs reduce approved vendor lists to simplify supply chain transparency documentation. Dominant competitive moves include strategic partnerships for recycling infrastructure access and geographic expansion into Indian and Southeast Asian automotive manufacturing corridors.
Within the polymer science leadership tier, BASF anchors high-performance composite formulations through its Ludwigshafen-centered research infrastructure. Covestro AG exemplifies European bonding-system specialization through polyurethane-metal expertise concentrated in Leverkusen. DuPont occupies a position in premium medical device applications through fluoropolymer-metal laminate capabilities. These three entities represent distinct competitive archetypes: diversified chemical major, regional technology specialist, and premium niche differentiator.
| Leading Market Players |
|---|
| BASF |
| Covestro AG |
| DuPont |
| Celanese Corporation |
| SABIC |
| Solvay |
| Evonik |
| Arkema |
| Visteon |
| Others |
Value Network & Pricing Analysis
Isocyanate feedstock volatility compresses margin predictability for European automotive interior suppliers and determines both pricing tier spreads and supply chain shape across the plastic-metal hybrids market. This raw material instability forces compounders to index long-term contracts to crude oil benchmarks while spot purchasers absorb margin compression in volatile quarters.
Pricing Analysis
Long-term offtake agreements dominate procurement between German automotive OEMs and tier-one bonding-system suppliers, insulating volume purchasers from polyol price spikes while spot buyers in Indian and Southeast Asian markets absorb feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified medical laminates from automotive-grade formulations and uncertified commodity hybrids. Pricing pressure stems from cast aluminum substitution in luxury vehicle crash structures, compressing margins for mid-tier metal-plastic composites. Automotive OEMs exhibit highest price sensitivity due to CAFE mandate compliance costs, while medical device manufacturers accept premium pricing for ISO 10993 dossiers.
Supply Chain Analysis
Contract manufacturing capacity concentrates with specialized compounders in Germany, Japan, and the United States where Fraunhofer-affiliated technical centers and OEM-integrated labs protect bonding process IP. Supply chains draw from isocyanate and polyol feedstocks anchored in Belgian and Dutch petrochemical complexes, with fluoropolymer resin supply tethered to Japanese and US specialty chemical producers. Single-source vulnerability runs through German precision molding clusters where Stuttgart-based tier-one suppliers operate captive production cells. Distribution runs through automotive tier-one supplier networks and medical device contract manufacturers, bypassing traditional chemical distributor channels for qualification-critical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
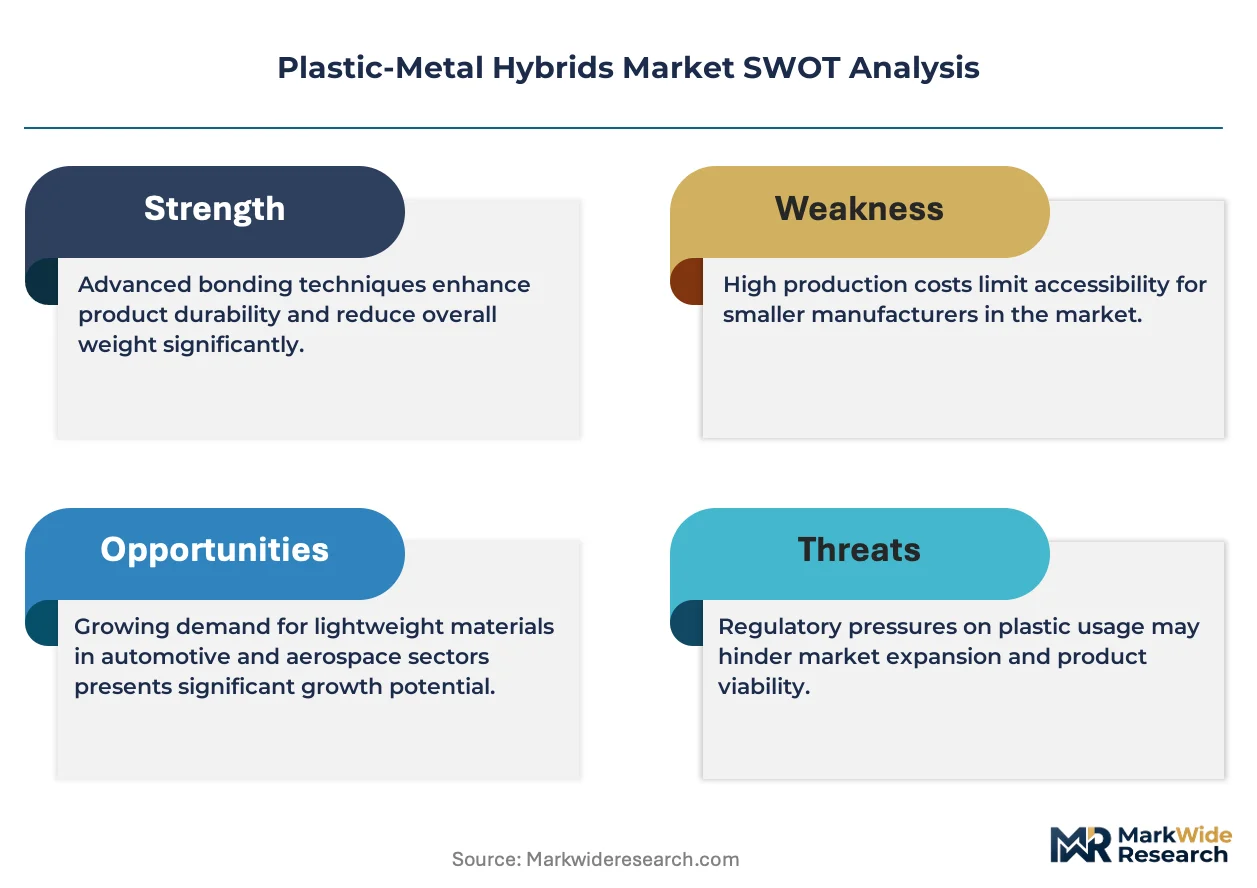
Incumbents must navigate all-aluminum crash structure substitution in luxury segments where OEMs prioritize single-material recyclability over maximum weight reduction.
For Market Incumbents: Entrench regulatory dossier advantages by accelerating ISO 10993 pre-submissions with FDA and notified bodies, freezing out compounders lacking biocompatibility testing infrastructure. Deepen backward integration into polyurethane formulation capabilities to offset isocyanate feedstock volatility and protect margin predictability for European automotive interior contracts. Defend against cast aluminum substitution by demonstrating end-of-life recyclability advantages through German shredding and density-separation partnerships. For New Entrants and Emerging Players: Build out technical service laboratories in Pune and Chennai to capture first-mover positioning with Maruti Suzuki and Tata Motors as they qualify hybrid pedal boxes for domestic compact platforms. Target aerospace additive manufacturing brackets where 24-36 month qualification timelines create entry barriers for established suppliers lacking topology-optimization expertise. Penetrate through distributor networks serving ambulatory surgical centers for fluoropolymer-metal laminates, bypassing hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: REACH Article 33 disclosure mandates reshape the acquisition landscape by consolidating supplier bases as German medical equipment manufacturers reduce documentation burden through vendor list rationalization. Five-to-ten year viability favors compounders with pre-submitted regulatory dossiers and captive bonding process IP in precision manufacturing clusters. Signal to monitor: qualification timelines for laser-sintered hybrid brackets with embedded titanium load paths in satellite and UAV applications as aerospace manufacturers expand topology-optimized component adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Formulation | Captive isocyanate blending insulates BASF and Covestro from crude oil index volatility. |
| Medical Device Certification Investment | ISO 10993 dossiers with FDA create multi-year qualification moats for DuPont fluoropolymer laminates. |
| Indian Technical Service Laboratory Buildout | Pune and Chennai facilities capture Maruti Suzuki hybrid pedal box qualification cycles. |
| Additive Manufacturing Qualification Partnership | Laser-sintered hybrid bracket validation with aerospace OEMs opens satellite and UAV supply positions. |
| Recycling Infrastructure Joint Venture | German shredding and density-separation capabilities address end-of-life mandates for multi-material assemblies. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with automotive tier-one supplier procurement officers, OEM platform engineers, medical device regulatory affairs leads, and aftermarket service heads; and secondary validation through SEC 10-K filings, customs and trade data, EPA CAFE compliance reports, and REACH Article 33 disclosure databases. Bottom-up triangulation across adhesive formulation volumes and top-down reconciliation against automotive production forecasts anchored market sizing.
Forecast inputs considered vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster segmentation across the projection horizon. CAGRs were derived from regression analysis of historical substitution rates for steel stampings in brake pedals and oil pans, coupled with aerospace additive manufacturing qualification pipeline visibility. Topology-optimized bracket adoption curves and battery-electric architecture lightweighting roadmaps served as industry-specific demand drivers.
Stress conditions across isocyanate price volatility bands, REACH disclosure timeline extensions, and aluminum substitution share reclamation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EPA fuel-economy standard stringency and EU F-Gas Regulation enforcement. Quarterly review of aerospace qualification pipeline progress and Indian OEM localization announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Forgings Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
North America Green Steel Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Tungsten Titanium Carbide Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Thulium Silicide Market