
 Middle East and Africa Aluminum Casting Market | 2026-2036
Middle East and Africa Aluminum Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Aluminum Casting Market Foresight
Maintenance contracts for die-casting tooling and mold lifecycle management is shifting how foundries monetize customer relationships beyond unit sales. Emirates Global Aluminium leverages its integrated smelting capacity to anchor premium billet supply for captive and third-party casting operations. Gulf Metal Foundry competes on rapid turnaround for complex sand-cast industrial components serving Saudi Aramco's domestic procurement mandates. National Metal Manufacturing and Casting Company Maadaniyah specializes in permanent mold processes for electrical infrastructure buyers across the GCC.
Aluminum casting in the Middle East and Africa denotes the pouring of molten aluminum alloys into molds to produce engineered components with precise dimensional tolerances and mechanical properties, typically achieving tensile strengths between 150-350 MPa depending on alloy grade and heat treatment. The process serves critical functions in reducing vehicle weight, dissipating electrical heat, and providing corrosion-resistant structural elements for coastal construction. Die castings command the largest value share due to automotive transmission housings and engine block demand from assembly plants in Morocco and South Africa. Sand castings retain dominance in industrial machinery and large-format construction hardware where low tooling costs accommodate variable batch sizes. High-pressure casting technology leads growth as Turkish and Egyptian suppliers upgrade equipment to serve European automotive tier-one contracts.
SASO in Saudi Arabia and the UAE's Ministry of Industry and Advanced Technology enforce conformity assessment protocols that determine market access for imported aluminum castings used in building structures and electrical installations. South Africa's National Regulator for Compulsory Specifications mandates pressure-equipment standards that shape foundry certification investments for boiler and pipeline component suppliers. Egypt's Egyptian Organization for Standardization and Quality aligns industrial material specifications with broader Arab regional trade protocols. Stakeholders must monitor how carbon-border adjustment mechanisms in European destination markets will reshape the competitiveness of MEA-sourced castings in automotive and machinery export channels.
Market Dynamics
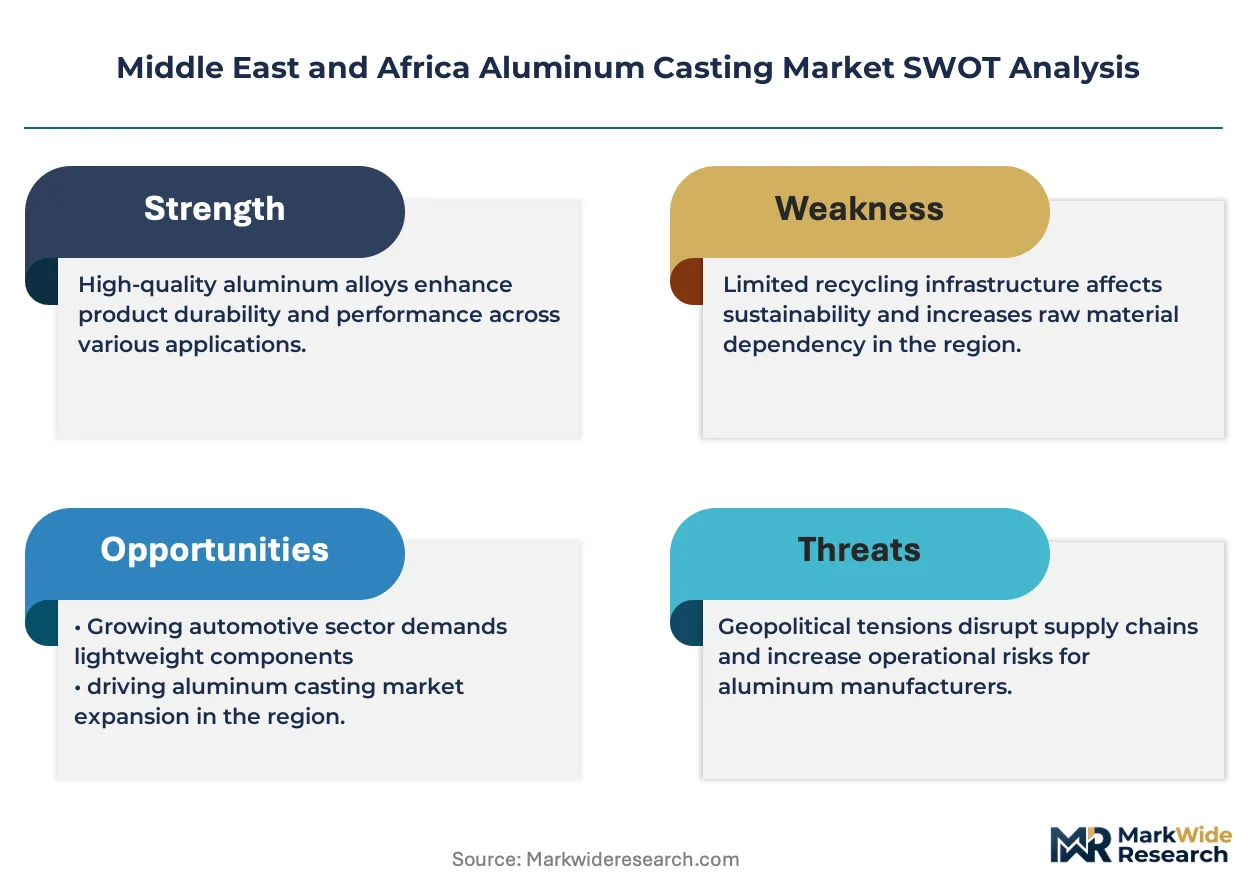
Gulf-based smelter-to-foundry integration is compressing lead times for aerospace and automotive buyers while SASO certification requirements are fragmenting import competition for domestic Saudi producers.
Growth Catalysts
- Automotive lightweighting mandates:GCC assembly plants are expanding die-cast transmission housing and engine block sourcing from regional facilities to meet fuel efficiency targets.
- SASO technical regulations:Saudi Arabia's tightening quality certification requirements for imported castings are redirecting procurement toward domestic foundries with verified compliance.
- High-pressure die casting:Turkish and Egyptian equipment upgrades are capturing European automotive tier-one contracts previously served by Asian suppliers.
Market Restraints
- Primary aluminum price volatility:LME-linked ingot costs expose regional foundries to margin compression when Gulf smelter premiums spike.
- Tooling capex concentration:Die-casting mold investments cluster in the UAE's Jebel Ali corridor, creating geographic dependency for complex component production.
- Steel substitution in construction:Rebar and structural steel retain cost advantages for large-format coastal infrastructure, limiting aluminum penetration in building frames.
Strategic Opportunities
- Egyptian foundry modernization:Arab regional trade protocol alignment is opening duty-advantaged export channels to North African electrical infrastructure markets.
- Carbon-border adjustment positioning:European destination market regulations will reward MEA smelters with verified low-carbon billet supply for automotive export contracts.
- Maintenance contract unbundling:Die-casting tooling lifecycle management services represent recurring revenue streams beyond unit sales for foundries serving Saudi Aramco procurement mandates.
Industry Challenges
- Heat treatment technician scarcity:Achieving 150-350 MPa tensile strength specifications requires specialized metallurgical expertise that outpaces regional vocational training output.
- Multi-standard certification timelines:South Africa's National Regulator for Compulsory Specifications pressure-equipment approvals create six-to-nine month qualification delays for boiler component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Aluminum Casting Market |
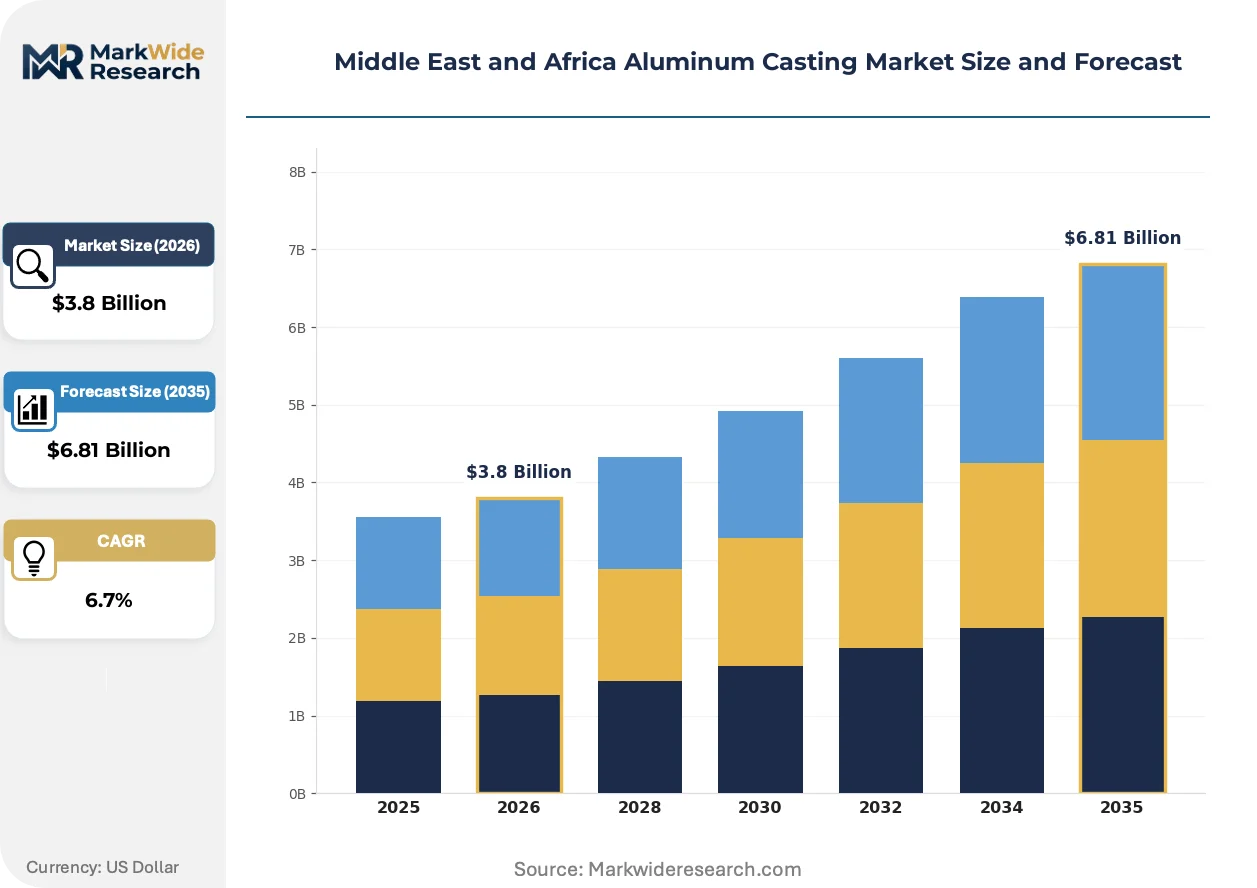
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sand Castings, Die Castings, Permanent Mold Castings, Investment Castings End User: Automotive, Aerospace, Construction, Electrical Technology: Gravity Casting, Low-Pressure Casting, High-Pressure Casting, Rapid Prototyping Application: Machinery, Consumer Goods, Transportation, Industrial Components |
| Companies Covered | Emirates Global Aluminium, Gulf Metal Foundry, National Metal Manufacturing and Casting Company Maadaniyah, Oman Aluminium Rolling Company, Qatar Aluminium Manufacturing Company, Sohar Aluminium, Oman Aluminium Cast, Specialized Industrial Casting Company Sicast, Mozal Aluminium, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Aluminum Casting Market Shifts & Advancements
Digital mold thermal monitoring and low-carbon billet traceability systems are restructuring how Gulf foundries qualify for aerospace and European automotive supply chains.
Real-time cavity temperature sensing combined with predictive maintenance algorithms is electrifying process control in high-pressure die casting cells. Emirates Global Aluminium's captive foundry operations are deploying these systems across transmission housing production lines. The technology is compressing defect rates and enabling just-in-sequence delivery contracts that were previously uneconomical for regional suppliers.
SASO's updated industrial material standards are mandating batch-level chemical certification for structural castings used in Saudi building projects. The regulation is forcing import-dependent distributors to establish local testing partnerships or cede share to domestic producers with in-house spectrometry capabilities. Electrical infrastructure buyers are now specifying SASO-compliant suppliers for substation hardware, accelerating foundry investment in Riyadh and Dammam industrial zones.
Integrated smelter-to-die-casting complexes are capturing maintenance and mold refurbishment contracts previously held by independent service providers. Gulf Metal Foundry and Maadaniyah are bundling tooling lifecycle management with component supply for Saudi Aramco and SEC procurement teams. The shift is most visible in the Eastern Province, where long-term service agreements now exceed unit sales value for complex sand-cast industrial components.
Middle East and Africa Aluminum Casting Market Segmentation
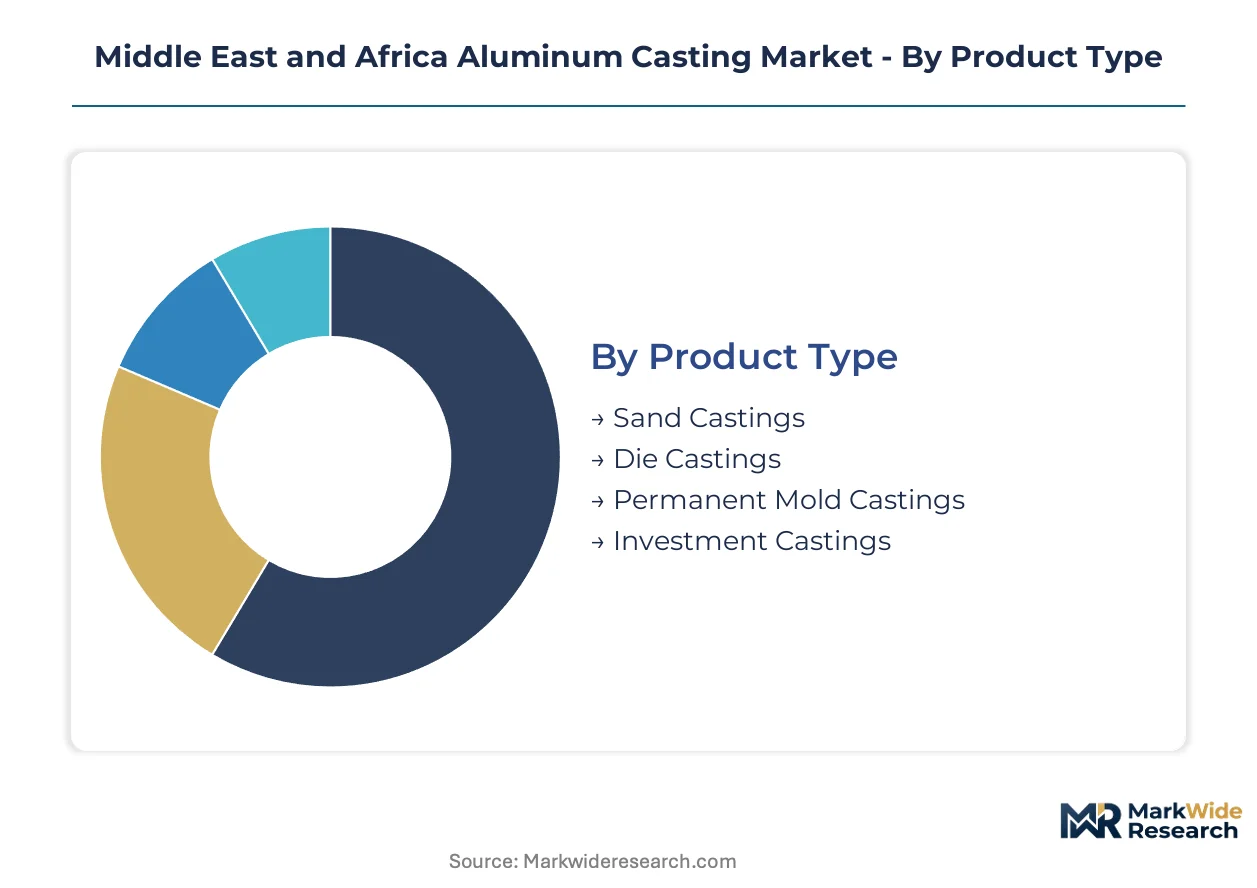
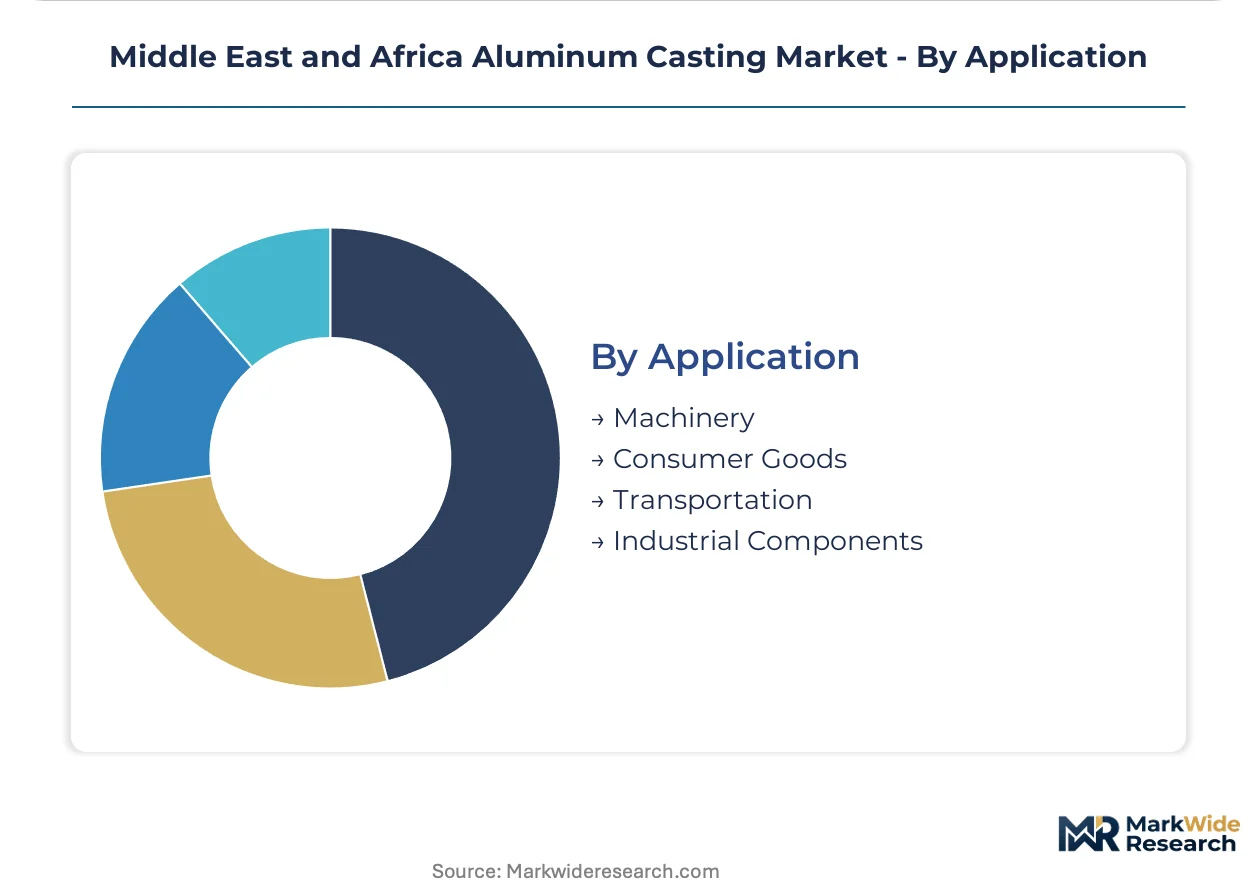
Aluminum casting procurement patterns across the Middle East and Africa diverge sharply by production technology and end-use certification requirements. Foundries serving GCC automotive and aerospace buyers compete on die-casting precision and heat-treatment capability, while industrial machinery demand favors sand-cast flexibility for variable batch sizes.
Product Type:
Supply concentrates in die-casting corridors where high-volume automotive contracts justify capital-intensive tooling investments.
- Die Castings:High-pressure injection of molten aluminum into hardened steel molds achieves dimensional tolerances within ±0.05 mm for transmission housings and engine blocks. Demand clusters in Morocco and South Africa assembly plants sourcing lightweight components from Turkish and Egyptian tier-one suppliers upgrading equipment for European automotive contracts.
- Sand Castings:Green sand or chemically bonded molds accommodate low tooling costs and design flexibility for large-format industrial components. Saudi Aramco procurement mandates for complex sand-cast hardware drive foundry investment in the Eastern Province, where maintenance contract bundling now exceeds unit sales value.
- Permanent Mold Castings:National Metal Manufacturing and Casting Company Maadaniyah specializes in gravity-fed permanent mold processes for electrical infrastructure buyers across the GCC.
- Investment Castings:Lost-wax precision casting serves aerospace blade and vane applications requiring near-net-shape capability with minimal machining.
Today's leader: Die Castings. Tomorrow's challenger: Permanent Mold Castings.
End User:
Application pull varies by the stringency of national conformity assessment protocols governing structural and pressure-equipment deployment.
- Automotive:GCC assembly plants expand sourcing of die-cast transmission housings and engine blocks from regional facilities to meet fuel efficiency targets. SASO technical regulations on imported castings redirect procurement toward domestic Saudi foundries with verified quality certification.
- Electrical:Substation hardware and heat-dissipating enclosures command batch-level chemical certification under SASO's updated industrial material standards. Riyadh and Dammam industrial zones attract foundry investment to serve SEC procurement teams specifying compliant suppliers.
- Aerospace:Emirates Global Aluminium anchors premium billet supply for captive and third-party casting operations serving UAE-based MRO facilities.
- Construction:Coastal infrastructure projects face steel substitution pressure as rebar retains cost advantages for large-format building frames, limiting aluminum penetration.
Automotive commands current volume. Electrical infrastructure offers the steepest expansion trajectory as grid investment accelerates across the GCC.
Technology:
Process selection trades capital efficiency against the metallurgical expertise required to achieve 150-350 MPa tensile strength specifications.
- High-Pressure Casting:Turkish and Egyptian equipment upgrades capture European automotive tier-one contracts previously served by Asian suppliers through real-time cavity temperature sensing and predictive maintenance algorithms.
- Gravity Casting:Lower equipment costs suit foundries serving variable-batch industrial machinery demand where heat treatment technician scarcity constrains output expansion.
- Low-Pressure Casting:Controlled fill rates reduce porosity in wheel and suspension components for premium automotive applications.
- Rapid Prototyping:Additive manufacturing of sand molds and 3D-printed patterns compresses lead times for aerospace qualification samples and custom industrial components.
High-Pressure Casting dominates automotive sourcing. Rapid Prototyping is gaining share fastest as digital mold thermal monitoring restructures qualification timelines.
Application:
Customer procurement patterns split between long-term maintenance contracts for industrial hardware and spot purchasing for consumer durables.
- Industrial Components:Boiler and pipeline hardware faces six-to-nine month qualification delays under South Africa's National Regulator for Compulsory Specifications pressure-equipment standards.
- Transportation:Jebel Ali integrated smelter-to-foundry complexes compress lead times for aerospace and automotive buyers requiring just-in-sequence delivery.
- Machinery:Gulf Metal Foundry competes on rapid turnaround for complex sand-cast components serving Saudi Aramco domestic procurement mandates.
- Consumer Goods:Cookware and appliance housings compete with Asian imports on cost, with limited regional foundry participation.
Industrial Components anchor revenue stability. Transportation offers the fastest volume climb as GCC assembly plant localization deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as Gulf smelter-to-foundry integration compresses compliance costs that burden import-dependent competitors elsewhere.
Saudi Arabia
SASO technical regulations on industrial material standards are tightening quality certification requirements for imported versus domestically produced castings. Domestic foundries with in-house spectrometry capabilities capture share from import-dependent distributors. Riyadh and Dammam industrial zones attract foundry investment to serve SEC procurement teams specifying compliant suppliers.
United Arab Emirates
Emirates Global Aluminium anchors premium billet supply for captive and third-party casting operations serving aerospace and electrical infrastructure buyers. The UAE's Ministry of Industry and Advanced Technology enforces conformity assessment protocols that determine market access for imported aluminum castings. Jebel Ali integrated smelter-to-foundry complexes compress lead times for buyers requiring just-in-sequence delivery.
Egypt
Turkish and Egyptian equipment upgrades capture European automotive tier-one contracts previously served by Asian suppliers. The Egyptian Organization for Standardization and Quality aligns industrial material specifications with broader Arab regional trade protocols. Cairo and Alexandria industrial corridors attract modernization investment to serve duty-advantaged export channels to North African electrical infrastructure markets.
South Africa
The National Regulator for Compulsory Specifications mandates pressure-equipment standards that shape foundry certification investments for boiler and pipeline component suppliers. Six-to-nine month qualification delays create barriers for new entrants serving industrial machinery demand. Gauteng and Western Cape foundry clusters concentrate capacity for domestic automotive assembly plant sourcing.
Turkey
High-pressure die casting technology upgrades position Turkish suppliers for European automotive tier-one contracts. Real-time cavity temperature sensing and predictive maintenance algorithms electrify process control in production cells. Bursa and Istanbul industrial zones anchor equipment modernization serving export-oriented automotive component demand.
Middle East and Africa Aluminum Casting Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated smelter operators capturing premium billet supply while independent foundries compete on rapid turnaround for complex industrial components. The vendor base organizes around three strategic archetypes: captive smelter-affiliated operations, independent sand-cast specialists serving energy procurement mandates, and permanent mold foundries targeting electrical infrastructure buyers. Capacity expansion and maintenance contract bundling represent the dominant competitive moves as tooling lifecycle management services displace pure unit sales relationships.
Within the integrated smelter tier, Emirates Global Aluminium represents the archetype of backward-linked operations controlling premium billet supply for regional casting demand. Among independent specialists, Gulf Metal Foundry and National Metal Manufacturing and Casting Company Maadaniyah exemplify contrasting positioning—one competing on rapid turnaround for complex sand-cast industrial components, the other specializing in permanent mold processes for electrical infrastructure buyers across the GCC. These three entities anchor the competitive structure through their divergent integration depths and end-use specializations.
| Leading Market Players |
|---|
| Emirates Global Aluminium |
| Gulf Metal Foundry |
| National Metal Manufacturing and Casting Company Maadaniyah |
| Oman Aluminium Rolling Company |
| Qatar Aluminium Manufacturing Company |
| Sohar Aluminium |
| Oman Aluminium Cast |
| Specialized Industrial Casting Company Sicast |
| Mozal Aluminium |
| Others |
Supply & Pricing Matrix
Sovereign-backed smelter operators and family-owned foundry clusters anchor supply discipline across the Middle East and Africa aluminum casting market, compressing margin variability for buyers locked into long-term offtake agreements with Emirates Global Aluminium and Gulf Metal Foundry while fragmenting pricing power among import-dependent distributors facing SASO certification costs.
Pricing Analysis
Capacity additions in the UAE's Jebel Ali corridor are reshaping price floors for die-cast automotive components as integrated smelter-to-foundry complexes bundle tooling lifecycle management with unit supply. Three-tier pricing structure across premium billet, certified domestic, and import-dependent tiers separates Emirates Global Aluminium's captive operations from independent foundries and SASO-noncompliant imports. Price differentiation hinges on spectrometry certification and heat-treatment capability, with electrical infrastructure buyers at Saudi Electricity Company showing lowest price sensitivity due to procurement mandate requirements, while construction hardware distributors face margin tightening from steel substitution pressures.
Supply Chain Analysis
SASO batch-level chemical certification and South Africa's National Regulator for Compulsory Specifications pressure-equipment approvals gate market access for imported castings used in Saudi building projects and industrial boiler applications. Supply concentrates in the UAE, Saudi Arabia, and Turkey, with Egyptian foundries capturing duty-advantaged export channels to North African electrical markets. Raw material flows draw from Gulf smelter billet, European tooling steel, and Chinese auxiliary equipment, exposing regional foundries to commodity price volatility in LME-linked aluminum ingot. Distribution runs through direct OEM contracts for automotive and aerospace buyers, with project-based procurement dominating industrial machinery and energy sector sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO's tightened industrial material standards function as a regulatory compounder, redirecting procurement toward domestic Saudi foundries with verified compliance and accelerating investment in Riyadh and Dammam industrial zones.
For Market Incumbents: Deploy maintenance contract bundling to lock in Saudi Aramco and Saudi Electricity Company procurement teams beyond unit sales relationships. Gulf Metal Foundry's rapid turnaround capability for complex sand-cast components exemplifies defensive positioning against Turkish and Egyptian equipment upgrades capturing European automotive tier-one contracts. Backward integration into premium billet supply, as demonstrated by Emirates Global Aluminium's captive foundry operations, anchors margin protection against primary aluminum price volatility. For New Entrants and Emerging Players: Digital mold thermal monitoring systems offer entry wedge into aerospace qualification timelines previously uneconomical for regional suppliers. White-space targets concentrate in Egyptian electrical infrastructure export channels duty-advantaged under Arab regional trade protocols, and in rapid prototyping services compressing lead times for custom industrial components. Go-to-market positioning should emphasize carbon-border adjustment readiness for European automotive export contracts, leveraging low-carbon billet traceability systems as qualification differentiator. For Investors and Strategic Acquirers: Valuations sit cheapest among independent sand-cast specialists serving energy procurement mandates without spectrometry capabilities, as SASO compliance investments strain working capital. Long-term viability across the analysis window favors foundries with bundled tooling lifecycle management revenue streams and verified low-carbon billet supply chains. Acquisition target archetype: permanent mold foundries in Riyadh and Dammam industrial zones with SEC procurement relationships. Signal to watch: European carbon-border adjustment mechanism implementation timelines reshaping competitiveness of MEA-sourced castings in automotive export channels.| Strategic Initiative | Industry Significance |
|---|---|
| Smelter-to-Foundry Integration | Emirates Global Aluminium's captive operations compress lead times for aerospace buyers requiring just-in-sequence delivery. |
| SASO Certification Investment | Domestic Saudi foundries capture share from import-dependent distributors lacking in-house spectrometry capabilities. |
| Maintenance Contract Bundling | Gulf Metal Foundry and Maadaniyah exceed unit sales value through tooling lifecycle management for Saudi Aramco. |
| High-Pressure Die Casting Upgrade | Turkish and Egyptian suppliers capture European automotive tier-one contracts previously served by Asian competitors. |
| Carbon-Border Adjustment Positioning | Low-carbon billet traceability systems qualify MEA smelters for European automotive export contract eligibility. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with foundry operations managers, Tier 1 automotive procurement leads, Saudi Electricity Company technical specifications officers, and heat treatment technicians with secondary validation from SASO regulatory filings, South Africa's National Regulator for Compulsory Specifications pressure-equipment standards, Emirates Global Aluminium sustainability disclosures, and Gulf smelter production data. Triangulation across these sources anchors volume and value estimates for die-casting, sand-casting, and permanent mold segments.
Input-output matrices map aluminum alloy consumption by process technology against automotive lightweighting mandates, electrical infrastructure investment cycles, and aerospace MRO demand patterns across the projection horizon. Segmentation dimensions include casting process type, end-use certification requirements, heat treatment capability tier, and regional regulatory cluster. CAGRs derive from equipment upgrade timelines, smelter capacity expansion schedules, and procurement mandate enforcement trajectories without reliance on single-source extrapolation.
The model holds under sustained SASO enforcement and stable Gulf smelter premium structures; deviation in European carbon-border adjustment implementation timelines or primary aluminum price volatility spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Brazing Alloys Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Forgings Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Global Aluminum Alloys Market