
 Europe Vehicle Rental Market | 2026-2036
Europe Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vehicle Rental Market Foresight
Multi-source fleet procurement is recalibrating how rental operators balance asset ownership against third-party leasing partnerships. Europcar Mobility Group leverages its station density across Western Europe to sustain last-mile coverage advantages. SIXT SE anchors premium positioning through technology leadership in digital booking interfaces. Enterprise Holdings Inc. competes by controlling corporate account relationships with integrated travel management tools.
Europe vehicle rental denotes the short-to-medium-term provision of automobiles, vans, and light commercial vehicles through transactional or subscription-based contracts, with fleet composition governed by residual value forecasting and utilization-rate optimization. The primary commercial purpose centers on converting fixed vehicle ownership costs into variable operating expenses for business and leisure mobility consumers. Short-term rentals dominate revenue generation at airport and railway hubs, while car subscription models capture expanding margin pools among urban professionals seeking flexibility without residual risk. SUVs and electric sedans represent the fastest-growing vehicle categories as fleet managers respond to EU emissions standards and consumer preference shifts. Online platforms now command the dominant distribution channel, displacing conventional rental offices in leisure booking flows.
The EU Green Deal and REACH frameworks mandate progressive fleet electrification, compelling operators to restructure procurement around battery-electric vehicles and charging infrastructure partnerships. EMA and national transport regulators across France, Germany, and Spain enforce emissions compliance through vehicle registration restrictions and low-emission zone access rules. CSRD disclosure requirements add reporting burdens on listed rental groups, reshaping capital allocation toward transparent sustainability metrics. Stakeholders must monitor regulatory tightening on internal combustion engine phase-outs and the pace of charging network buildouts to calibrate fleet transition timelines against residual value exposure.
Market Dynamics
The EU Green Deal's phased internal combustion engine restrictions are forcing rental operators to accelerate fleet electrification timelines while managing residual value exposure on depreciating diesel assets.
Growth Catalysts
- Corporate Fleet Electrification Mandates:The EU Green Deal's emissions standards are compelling enterprise accounts to source battery-electric vehicles through rental partnerships rather than direct ownership, expanding contract volumes with integrated charging solutions.
- Urban Low-Emission Zones:Cities including Paris, London, and Berlin are restricting diesel access, creating captive demand for electric rental fleets that maintain zone compliance without customer capital commitment.
- Subscription Model Penetration:Flexible-term vehicle access is displacing traditional leases among urban professionals seeking mobility without residual risk exposure or maintenance burden.
Market Restraints
- Battery Supply Concentration:European rental operators face procurement bottlenecks as cell production concentrates in Asian manufacturing hubs, extending delivery timelines for electric fleet expansion.
- Charging Infrastructure Gaps:Rural and secondary city networks remain underdeveloped, limiting electric fleet deployment outside Nordic urban corridors and Mediterranean tourism hubs.
- Residual Value Uncertainty:Rapid technology obsolescence in battery-electric platforms creates depreciation risk that constrains financing availability for fleet procurement.
Strategic Opportunities
- Eastern European Network Expansion:Poland, Romania, and Czechia exhibit underpenetrated corporate rental markets with accelerating foreign direct investment in manufacturing and logistics sectors.
- Integrated Mobility Platforms:Convergence of rental booking systems with public transit and micromobility apps enables subscription bundling that captures modal shift demand from private vehicle ownership.
- CSRD-Aligned Fleet Reporting:Corporate sustainability disclosure requirements are creating demand for rental partners that provide granular emissions data and Scope 3 reduction verification.
Industry Challenges
- Electrification Skill Shortages:Maintenance technicians qualified on high-voltage battery systems remain scarce across Southern European markets, constraining fleet uptime guarantees.
- Legacy Reservation System Integration:Real-time electric vehicle availability, range forecasting, and charging station status require platform overhauls that strain mid-size operator IT budgets.
- Multi-Country Compliance Fragmentation:Divergent national implementations of EU emissions rules create operational complexity for cross-border fleet utilization and registration transfers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vehicle Rental Market |
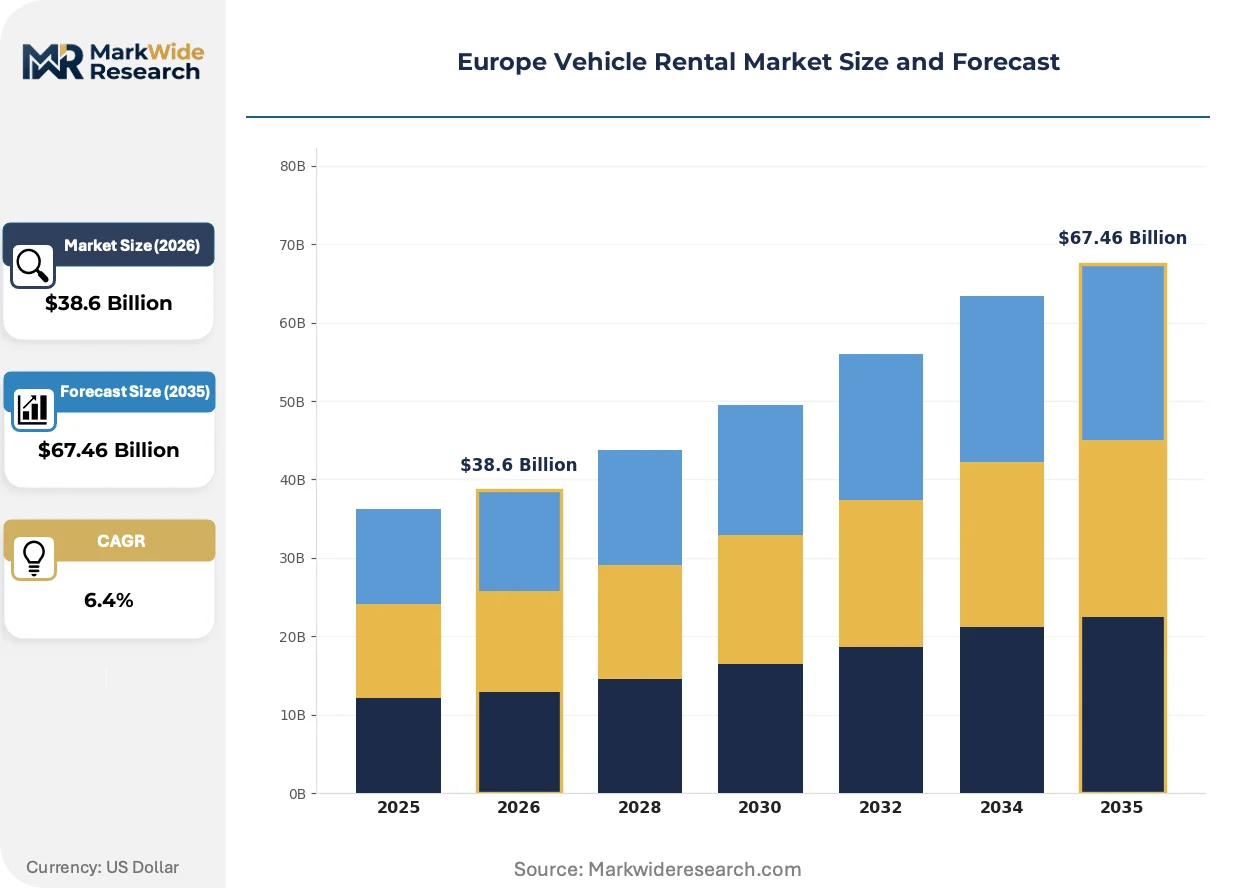
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Rentals, Long-Term Rentals, Car Subscription, Van Rentals Vehicle Type: Sedans, SUVs, Luxury Cars, Vans End User: Business Travelers, Tourists, Local Residents, Ride-Sharing Services Distribution Channel: Online Platforms, Travel Agencies, Conventional Rental Offices, Corporate Accounts |
| Companies Covered | Europcar Mobility Group, OK Mobility Group, Enterprise Holdings Inc., BlaBlaCar, Goldcar Rental S.L., Hertz Global Holdings, SIXT SE, Green Motion International, Avis Budget Group Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vehicle Rental Market Shifts & Advancements
Digital platforms are compressing booking friction while artificial intelligence applications reshape fleet utilization forecasting and dynamic pricing architectures across European markets.
Telematics-enabled predictive maintenance is consolidating operational control for rental operators managing mixed electric and combustion fleets. Fleet managers at airport and railway hub locations are adopting these systems fastest, driven by utilization-rate optimization mandates. The technology is consolidating maintenance spend from reactive service models toward condition-based interventions that extend vehicle service life.
The EU Green Deal's fleet electrification benchmarks are restructuring procurement priorities across national markets. Operators must now secure battery-electric vehicle supply commitments years ahead of delivery to meet 2030 emissions thresholds. Mediterranean tourism corridors face the steepest compliance curves due to seasonal demand spikes that strain charging infrastructure during peak rental periods.
Corporate travel managers are unbundling long-term lease commitments in favor of flexible subscription contracts with embedded maintenance and insurance. This consumption-pattern shift is displacing traditional multi-year fleet management agreements among professional services and technology sectors. Germany and France exhibit the fastest transition velocity, driven by sustainability reporting pressures and talent retention strategies emphasizing mobility benefits over vehicle ownership.
Europe Vehicle Rental Market Segmentation
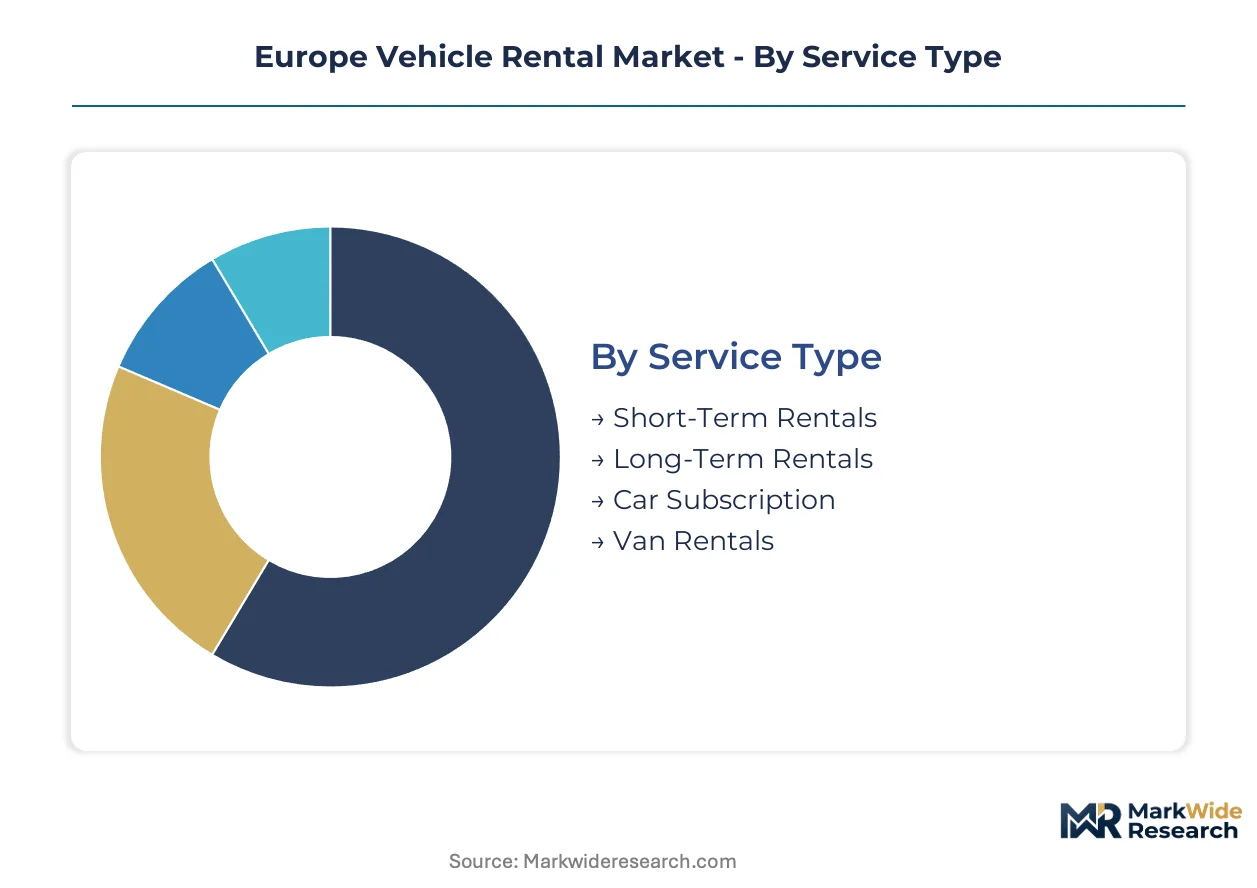
Segmentation in the Europe vehicle rental market reveals how fleet composition, contract duration, and booking interfaces align with distinct mobility consumption patterns. Rental operators calibrate asset allocation and pricing architectures around these divides to optimize utilization rates and residual value exposure.
Service Type:
Customization intensity varies from standardized hourly transactions to bespoke multi-year corporate arrangements with embedded maintenance and charging infrastructure.
- Short-Term Rentals:Hourly to daily transactions dominate airport and railway hub locations, where Europcar and SIXT leverage station density for last-mile capture. Demand concentrates in Mediterranean tourism corridors during peak seasons, constrained by charging infrastructure gaps for electric fleet deployment.
- Car Subscription:Flexible monthly access without residual risk is displacing traditional leases among urban professionals in Germany and France. CSRD-aligned sustainability reporting pressures corporate travel managers toward this model for Scope 3 emissions verification.
- Long-Term Rentals:Multi-month contracts serve project-based corporate mobility needs with predictable cost structures.
- Van Rentals:Light commercial provision supports logistics and trade sectors across secondary cities.
Leading the category by volume: Short-Term Rentals. Expanding most quickly: Car Subscription.
Vehicle Type:
Margin profiles diverge sharply between commoditized compact segments and premium electrified platforms commanding technology premiums.
- SUVs:Higher ground clearance and cargo capacity align with family leisure demand and Nordic urban mobility requirements. Fleet managers in France and Germany prioritize these models for corporate account retention, though battery supply concentration from Asian manufacturing hubs extends delivery timelines.
- Sedans:Battery-electric variants represent the fastest-growing electrification pathway as EU Green Deal phase-outs approach. Paris, London, and Berlin low-emission zones create captive demand, constrained by rural charging infrastructure gaps outside Nordic corridors.
- Luxury Cars:Premium positioning through technology leadership in digital interfaces sustains margin pools at SIXT and Enterprise.
- Vans:Light commercial configurations serve last-mile logistics with utilization-rate optimization mandates.
Dominant by fleet value: SUVs. Steepest expansion trajectory: Sedans.
End User:
Customer acquisition costs and retention mechanics differ fundamentally between transactional leisure segments and sticky corporate relationships.
- Business Travelers:Integrated travel management tools and sustainability data disclosure requirements shape procurement decisions. Corporate accounts in Germany and France are accelerating fleet electrification mandates through rental partnerships rather than direct ownership.
- Tourists:Seasonal demand spikes strain Mediterranean charging infrastructure during peak rental periods, with online platforms now commanding dominant distribution.
- Local Residents:Urban mobility zones in Nordic cities drive subscription adoption for zone compliance without capital commitment.
- Ride-Sharing Services:Platform-enabled fleet provision supports gig economy drivers with maintenance-inclusive terms.
Highest revenue concentration: Business Travelers. Gaining share fastest: Local Residents.
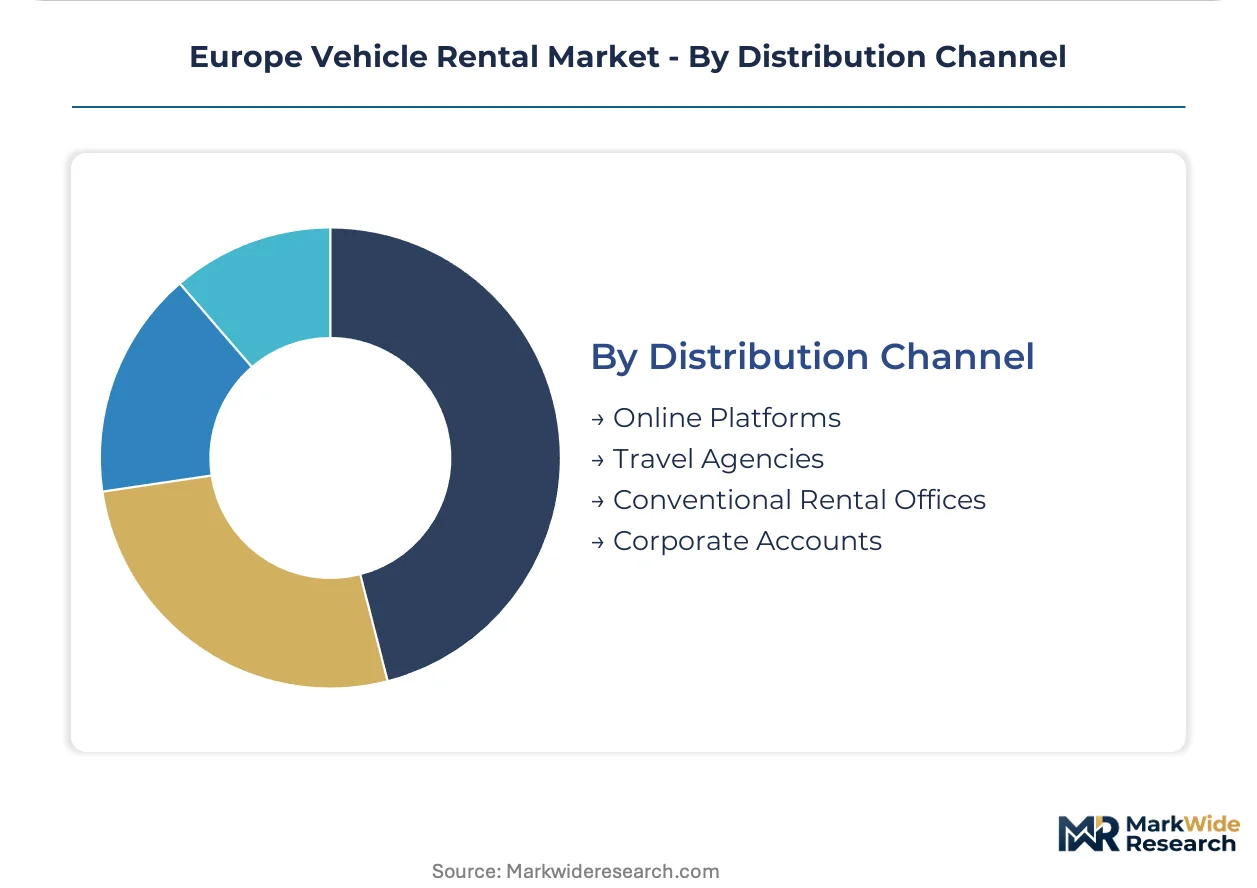
Distribution Channel:
Channel economics reflect divergent customer acquisition costs and lifetime value profiles across digital-native and relationship-driven pathways.
- Online Platforms:Real-time availability, dynamic pricing, and range forecasting for electric vehicles compress booking friction. Legacy reservation system integration strains mid-size operator IT budgets, particularly for charging station status synchronization.
- Corporate Accounts:Direct relationships with integrated travel management tools and granular emissions reporting sustain contract stickiness. Enterprise Holdings competes through control of these relationships with CSRD-aligned verification capabilities.
- Travel Agencies:Bundled leisure packaging maintains relevance in Mediterranean tourism corridors.
- Conventional Rental Offices:Station-based service persists for complex transactions and vehicle handovers.
Capturing dominant share: Online Platforms. Growing most quickly: Corporate Accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crude oil refining capacity in Rotterdam and Antwerp anchors fleet fuel cost structures across Northwestern Europe. Mediterranean tourism corridors concentrate seasonal demand spikes. Nordic urban mobility zones drive electrification infrastructure buildouts.
Germany
Corporate fleet electrification mandates from manufacturing and professional services sectors dominate procurement volumes. The KBA enforces emissions compliance through vehicle registration restrictions and low-emission zone access rules. Munich and Stuttgart clusters concentrate premium rental demand near automotive headquarters and airport hubs.
France
Urban low-emission zones in Paris and Lyon create captive demand for electric fleet compliance without customer capital commitment. The EU Green Deal's phased ICE restrictions accelerate procurement timelines through ANSM-aligned national transport frameworks. The Île-de-France region anchors business traveler concentration with integrated rail-air connectivity.
United Kingdom
Corporate travel managers unbundle long-term leases in favor of flexible subscription contracts with embedded maintenance. London's Ultra Low Emission Zone restrictions filter fleet composition toward battery-electric platforms. The Southeast England corridor sustains airport-hub rental density at Heathrow and Gatwick.
Spain
Seasonal tourism spikes strain Mediterranean charging infrastructure during peak rental periods. EMA-aligned national regulators enforce emissions disclosure requirements on listed rental groups operating in Barcelona and Madrid. The Costa del Sol and Balearic Islands concentrate leisure demand with underdeveloped rural charging networks.
Italy
Corporate accounts in Lombardy and Emilia-Romagna accelerate fleet electrification through rental partnerships rather than direct ownership. REACH frameworks mandate progressive fleet electrification with residual value exposure on depreciating diesel assets. Milan's urban mobility zone drives subscription adoption among professionals seeking flexibility without ownership burden.
Europe Vehicle Rental Market Competitive Landscape
Global majors compete with regional champions across station density and digital platform integration. The vendor base clusters around three tiers: integrated mobility conglomerates with multinational station networks, premium-positioned technology specialists, and niche operators targeting sustainability-conscious segments. Consolidation pressures intensify as electrification capital requirements favor scale. Dominant competitive moves include charging infrastructure partnerships and corporate account control through integrated travel management tools.
Among Western European-based operators, Europcar Mobility Group, SIXT SE, and Enterprise Holdings Inc. occupy distinct archetype positions. Europcar exemplifies station-density-driven last-mile coverage across airport and railway hubs. SIXT anchors premium positioning through technology leadership in digital booking interfaces. Enterprise represents corporate account relationship control with integrated travel management capabilities. These three structures illustrate how scale, technology, and relationship depth segment competitive positioning.
| Leading Market Players |
|---|
| Europcar Mobility Group |
| OK Mobility Group |
| Enterprise Holdings Inc. |
| BlaBlaCar |
| Goldcar Rental S.L. |
| Hertz Global Holdings |
| SIXT SE |
| Green Motion International |
| Avis Budget Group Inc. |
| Others |
Supply & Pricing Matrix
Corporate fleet electrification mandates from German and French enterprise accounts are pressuring rental operators to restructure procurement around battery-electric vehicles, compressing margins on legacy diesel assets while inflating acquisition costs for compliant fleets.
Pricing Analysis
Maintenance-inclusive subscription contracts command premium positioning against unbundled short-term rentals. Three-tier pricing structure across premium, standard, and economy levels separates SIXT's technology-enabled interfaces from Europcar's station-density coverage and budget-tier operators. Cost compression in the economy tier is intensifying because fleet managers prioritize utilization-rate optimization over per-transaction yield. Corporate accounts exhibit lowest price sensitivity due to CSRD-aligned sustainability reporting requirements.
Supply Chain Analysis
CE marking and EU Green Deal compliance certification gates battery-electric vehicle procurement for European rental operators. Cell production concentrates in China, South Korea, and Japan, creating procurement bottlenecks that extend delivery timelines. Fleet composition rests on lithium-ion battery packs, power electronics modules, and charging hardware from Asian manufacturing hubs. Single-source vulnerability in semiconductor supply for telematics and fleet management systems threatens uptime guarantees. Distribution runs through OEM direct allocation agreements and third-party leasing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's vehicle rental market is becoming a vertical-integration race as operators pursue upstream control over charging infrastructure to secure zone compliance advantages and downstream integration into corporate travel management platforms.
For Market Incumbents: To counter residual value uncertainty on depreciating diesel assets, Europcar and SIXT must accelerate backward integration into charging infrastructure partnerships across Mediterranean tourism corridors and Nordic urban mobility zones. Certification investment in high-voltage technician training programs addresses electrification skill shortages constraining fleet uptime guarantees in Southern European markets. For New Entrants and Emerging Players: Capture underpenetrated corporate rental demand in Poland, Romania, and Czechia where foreign direct investment in manufacturing and logistics sectors outpaces incumbent station density. A subscription-first go-to-market angle with embedded CSRD emissions reporting targets sustainability-conscious professional services firms unbundling from traditional fleet management agreements. For Investors and Strategic Acquirers: The window for entry favors mid-size operators with established charging infrastructure partnerships and corporate account relationships. Long-term viability hinges on fleet electrification execution speed against EU Green Deal phase-out timelines. The signal to monitor is battery supply agreement announcements from Asian cell manufacturers to European rental groups.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Secures zone compliance in Paris, London, and Berlin low-emission corridors. |
| Corporate Account Platform Integration | Captures travel management tool procurement from Enterprise Holdings. |
| Battery Supply Agreement | Locks cell allocation from Chinese and South Korean manufacturers. |
| CSRD-Aligned Fleet Reporting | Enables Scope 3 verification for German and French enterprise accounts. |
| Eastern European Network Expansion | Targets manufacturing and logistics FDI in Poland and Czechia. |
Research Methodology
Independent corroboration across fleet procurement directors at Europcar Mobility Group and SIXT SE, corporate travel managers at German manufacturing headquarters, and EMA regulatory affairs specialists underwrites the qualitative findings. Primary interviews with charging infrastructure developers, residual value forecasting analysts at European leasing subsidiaries, and sustainability officers at CSRD-reporting enterprises combined with secondary validation from EU Green Deal implementation documents, KBA vehicle registration databases, and ANSM transport framework filings. Bottom-up triangulation across station-level utilization data and top-down fleet composition analysis anchored market sizing.
Comparable-period anchoring to pre-pandemic utilization baselines and post-electrification mandate procurement patterns structured the forecast window. The analytical framework segmented by service type, vehicle propulsion architecture, end-user category, and distribution channel across the projection horizon. CAGRs derived from fleet replacement cycle modeling and corporate contract renewal velocity incorporated battery-electric vehicle adoption curves and charging network buildout assumptions.
The model holds under stable EU emissions enforcement timelines and continued corporate sustainability reporting expansion; deviation in battery supply chain disruptions or accelerated ICE phase-outs would shift fleet transition trajectories. Forecasts reflect assumptions about residual value stabilization and charging infrastructure density. A model refresh is warranted upon material change in EU Green Deal implementation pace or battery cell allocation agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Vehicle Management System Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Thailand Car Rental Market
Transportation Services
Airport Handling Service Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Global Taxi Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Bike Rental Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Cross Docking Services Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Bulk Transportation Services Market