
 Waste Collection Vehicle Market | 2026-2036
Waste Collection Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Collection Vehicle Market Outlook
Municipal fleet procurement is rebalancing toward electrified refuse collection as cities phase out diesel contracts. Heil leverages its North American dealer network to sustain aftermarket parts revenue across legacy and electric platforms. BYD Company anchors battery supply through in-house cell production, reducing exposure to external lithium pricing. Fujian Longma Environmental Sanitation Equipment dominates domestic tenders in China's tier-one cities through localized manufacturing scale.
Waste collection vehicles are purpose-built chassis-cab systems with compacted hopper capacities ranging from standard to heavy-duty, designed to lift, compress, and transport municipal solid waste under repetitive stop-start duty cycles. Front loader configurations lead commercial and industrial routes where containerized pickup efficiency determines fleet economics, while electric fuel type represents the fastest-expanding segment as battery energy density improvements enable full-shift route completion without midday charging. Rear loader units occupy the mature municipal residential segment where replacement cycles follow predictable budget appropriations.
EPA Phase 3 greenhouse gas standards and the EU Green Deal's clean mobility framework are forcing OEMs to certify zero-emission variants or forfeit municipal tender eligibility in regulated jurisdictions. China's MIIT new energy vehicle mandates and GB standards for commercial electrification create parallel compliance obligations for suppliers serving state-owned sanitation bureaus. Stakeholders must monitor battery recycling infrastructure readiness and charging depot capital requirements before committing fleet conversion timelines.
Market Dynamics
Zero-emission mandates across municipal procurement are compressing diesel replacement cycles and forcing OEMs to certify battery-electric and hydrogen fuel cell platforms or forfeit tender eligibility in regulated jurisdictions.
Growth Catalysts
- EPA Phase 3 Standards:US greenhouse gas regulations for heavy-duty vehicles mandate emission reductions that accelerate fleet electrification timelines and disqualify conventional diesel bids in coastal states.
- China's MIIT NEV Mandates:Ministry of Industry and Information Technology production quotas for new energy commercial vehicles concentrate state procurement toward domestic electric sanitation equipment manufacturers.
- Battery Energy Density Gains:Lithium iron phosphate cell chemistry improvements enable 200+ kilometer route completion without midday charging, resolving range anxiety barriers for municipal operators.
Market Restraints
- Lithium Price Volatility:Raw material cost swings for cathode active materials compress electric chassis margins and deter long-term fleet conversion commitments from budget-constrained municipalities.
- Charging Depot Capital Requirements:Grid infrastructure upgrades and depot charging hardware demand 7-figure capital outlays that strain sanitation department appropriations beyond vehicle acquisition costs.
- Hydrogen Fuel Cell Infrastructure Gaps:Limited gaseous hydrogen dispensing networks in North American and European secondary cities restrict fuel cell refuse truck deployment to pilot corridors.
Strategic Opportunities
- India's Swachh Bharat Infrastructure:Central government urban sanitation modernization allocates capital toward mechanized waste collection in tier-two metropolitan clusters previously served by informal labor.
- Battery Recycling Infrastructure:Emerging closed-loop lithium recovery ecosystems create aftermarket revenue streams and reduce virgin material dependence for OEMs with captive recycling partnerships.
- Autonomous Hopper Loading:Computer vision and robotic arm convergence enables single-operator collection routes that compress labor costs and address driver shortage constraints in Japanese and German markets.
Industry Challenges
- High-Voltage Technician Scarcity:Fleet maintenance departments lack certified electricians capable of servicing 600-volt battery architectures, forcing reliance on OEM service networks with constrained geographic coverage.
- Multi-Platform Parts Complexity:Municipal garages must simultaneously stock diesel, CNG, battery-electric, and hydrogen fuel cell component inventories, fragmenting purchasing power and inflating carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Collection Vehicle Market |
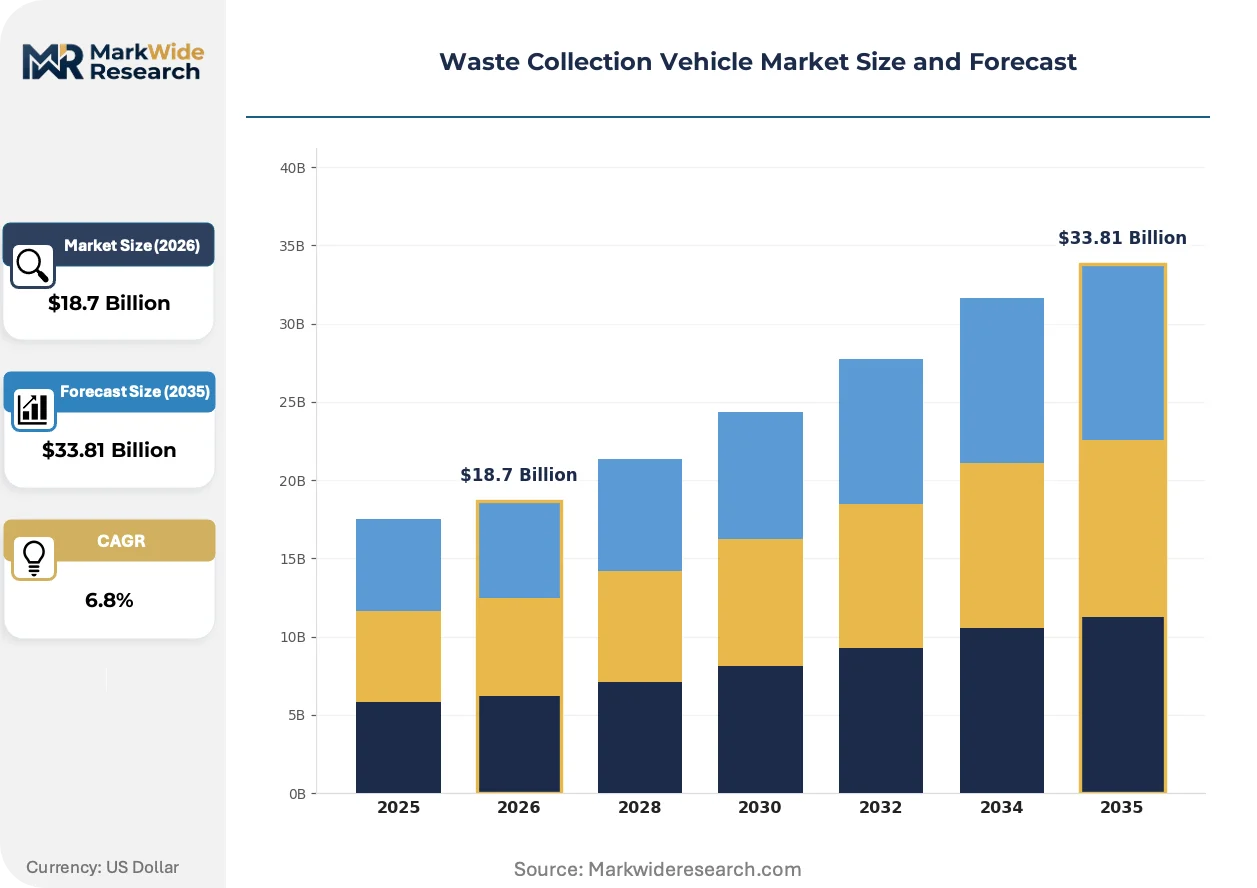
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Front Loader, Rear Loader, Side Loader, Roll-Off Fuel Type: Diesel, CNG, LNG, Electric End User: Municipalities, Private Contractors, Waste Management Companies, NGOs Capacity: Standard, Heavy-Duty, Compact, Super Compact |
| Companies Covered | New Way, Autocar, McNeilus Truck and Manufacturing, BYD Company, Fujian Longma Environmental Sanitation Equipment, Heil, Peterbilt, Kässbohrer Geländefahrzeug, Labrie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Collection Vehicle Market Strategic Shifts
Electrification is converging with automation and connectivity to redefine fleet economics, shifting competitive advantage from chassis durability to software-defined energy management and predictive maintenance capabilities.
Automated side-loader arms equipped with machine vision are automating container recognition and grip-force calibration, reducing per-stop dwell time and enabling single-operator routes. Municipal fleets in California and the Netherlands are deploying these systems at pilot scale ahead of anticipated labor contract renegotiations. The technology is automating manual lifting tasks that previously required two-person crews, compressing operating costs and injury liability exposure.
The EU Green Deal's clean mobility targets mandate 100% zero-emission urban bus procurement by 2030, with parallel pressure extending to refuse collection through the European Clean Vehicles Directive. OEMs without certified electric or hydrogen variants face exclusion from municipal tenders in France, Germany, and the Netherlands. Battery-electric rear loaders are capturing the majority of new tender volume in Scandinavian cities with established charging infrastructure.
Fleet-as-a-service contracting is displacing traditional capital purchase models among North American municipalities facing budget appropriation constraints. Private operators and OEM financing arms assume vehicle ownership and maintenance responsibility, charging per-ton or per-route fees that align vendor incentives with uptime performance. California and New York sanitation departments are piloting these arrangements to circumvent debt ceiling limitations while accelerating diesel phase-out timelines.
Waste Collection Vehicle Market Segmentation
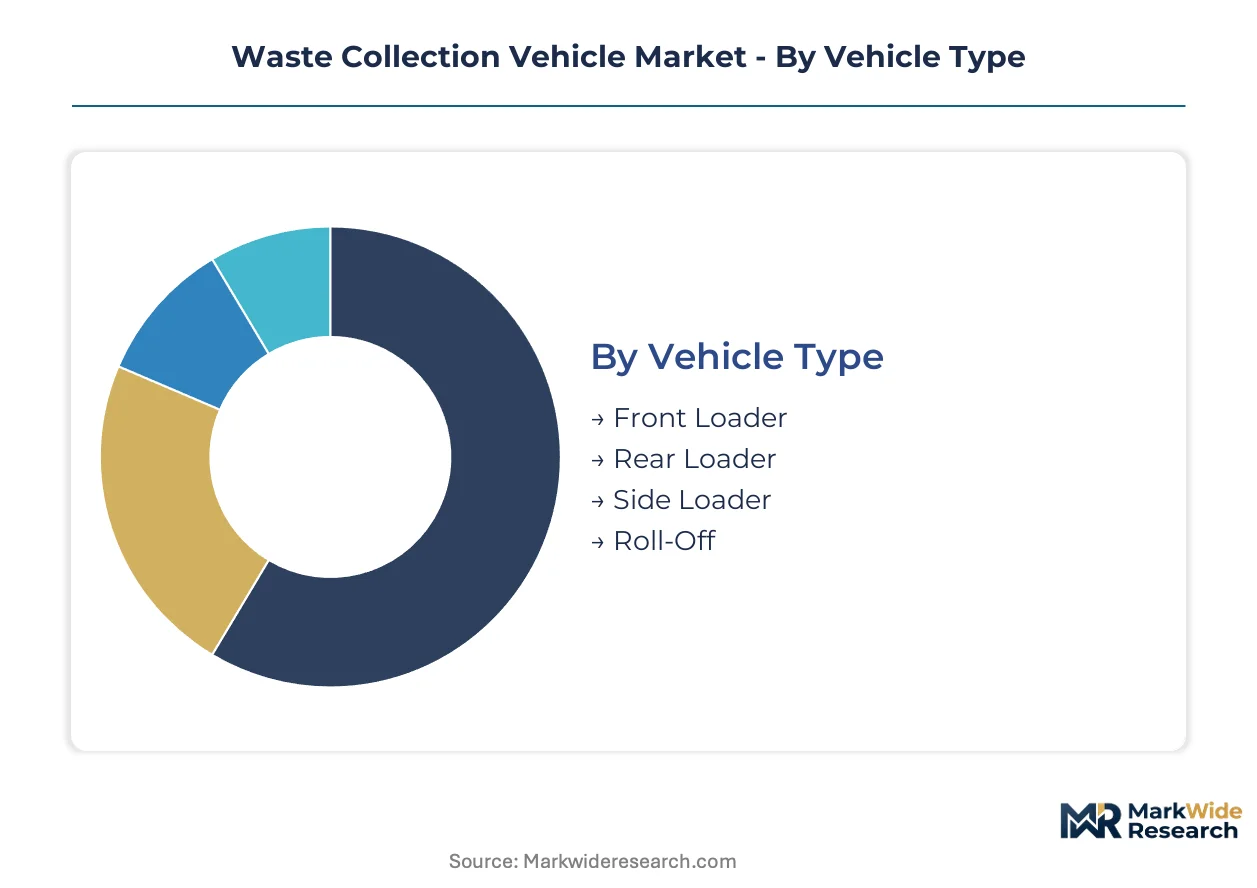
Waste collection vehicle procurement splits across four distinct category hierarchies. Fleet operators prioritize payload efficiency, route density, and fuel infrastructure compatibility when matching chassis configurations to municipal contract requirements.
Vehicle Type:
Route economics and labor productivity separate buyers across loader configurations, with container access patterns and crew size requirements driving selection.
- Front Loader:Articulated arm systems lift standardized commercial containers from the curb, compressing dense urban routes into single-operator shifts. Demand concentrates in California and Texas metropolitan contracts where containerized commercial waste volumes justify premium chassis acquisition costs.
- Rear Loader:Traditional hopper-fed designs accommodate manual bagged waste deposit from residential alleys and narrow streets. Municipalities in Germany and France maintain replacement cycles for rear loaders as residential collection remains labor-intensive and route-proven.
- Side Loader:Automated arm mechanisms grab residential carts from the curb, eliminating manual lifting. These units dominate new procurement in the Netherlands and Scandinavian cities with established automated collection infrastructure.
- Roll-Off:Hook-lift chassis transport open-top containers for construction debris and bulk waste transfer. Private contractors serving industrial zones in Ohio and Pennsylvania favor roll-off flexibility for variable payload contracts.
Rear loaders lead volumes today; front loaders are gaining share fastest in commercial route electrification.
Fuel Type:
Regulatory compliance timelines and total cost of ownership calculations split procurement between incumbent internal combustion and emerging zero-emission platforms.
- Diesel:Compression-ignition engines dominate legacy fleet composition with established service networks and parts availability. Municipalities in budget-constrained markets continue diesel procurement where charging infrastructure remains undeveloped.
- CNG:Compressed natural gas systems reduce particulate emissions and qualify for alternative fuel subsidies. California Air Resources Board incentives sustain CNG demand in Los Angeles and San Francisco fleets during transition periods.
- LNG:Liquefied natural gas extends range for regional haul routes with cryogenic tank storage. Limited adoption concentrates in Texas and Oklahoma where wellhead gas pricing compresses fuel costs.
- Electric:Battery-electric chassis with lithium iron phosphate packs enable zero-emission route completion. China's MIIT production quotas and EPA Phase 3 standards accelerate electric tender eligibility in Beijing, Shenzhen, and coastal US states.
Diesel retains installed base dominance; electric platforms are climbing the fastest on new order books.
End User:
Capital structure and operational risk tolerance distinguish procurement actors, from tax-funded municipal garages to leveraged private operators.
- Municipalities:City sanitation departments issue multi-year fleet contracts tied to budget appropriation cycles. Procurement in Illinois and Michigan follows predictable replacement calendars with diesel phase-out mandates accelerating conversion timelines.
- Private Contractors:Investor-owned waste services firms optimize asset utilization across route density and fuel hedging. WM and Republic Services electrification commitments in Florida and Arizona reshape supplier R&D priorities.
- Waste Management Companies:Integrated collection-processing-disposal operators specify chassis durability for high-cycle landfill shuttle routes. Vertical integration into fleet ownership compresses per-ton logistics costs.
- NGOs:Non-governmental organizations pilot informal sector formalization with low-capacity vehicles. India's Swachh Bharat infrastructure channels equipment toward tier-two city cooperatives previously dependent on manual collection.
Private contractors lead capital deployment today; municipalities are expanding fastest through fleet-as-a-service adoption.
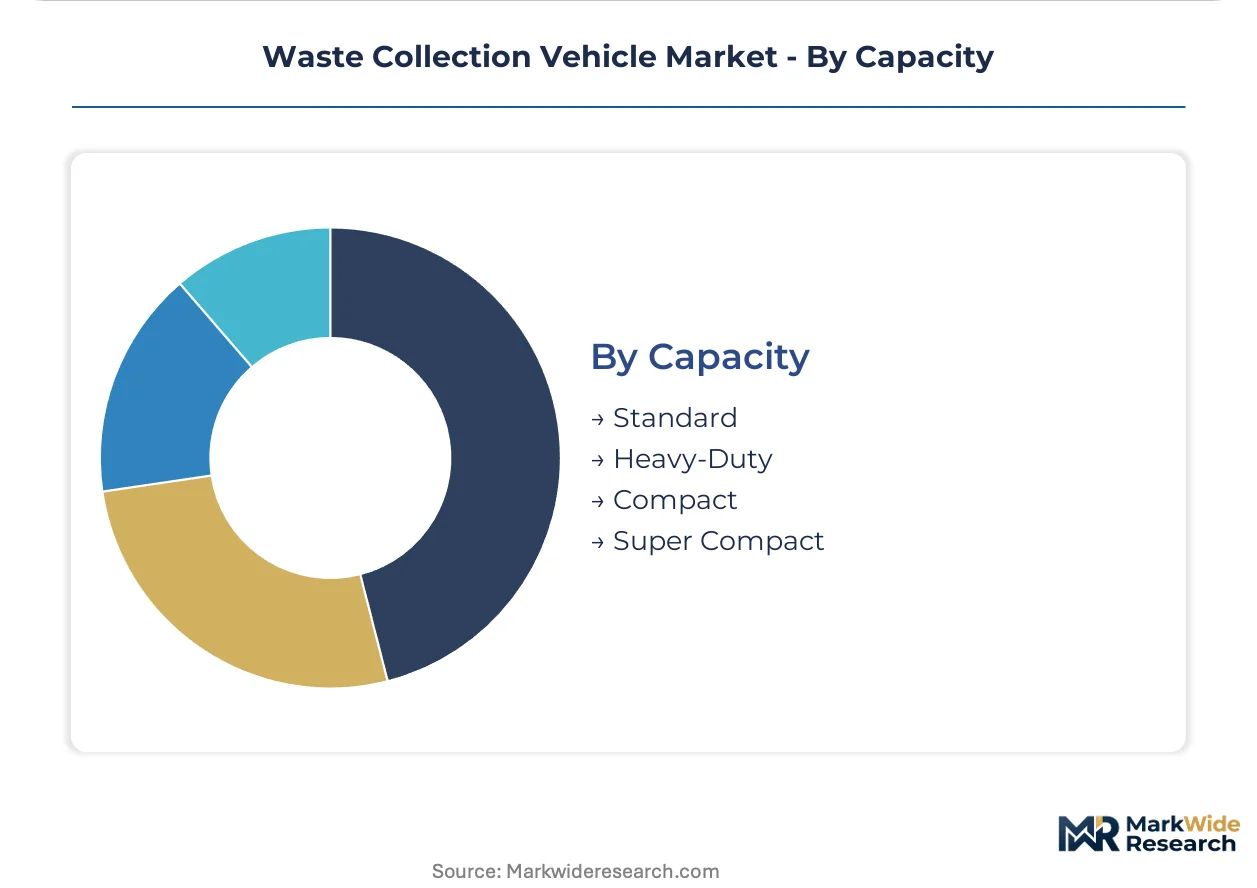
Capacity:
Payload volume and maneuverability trade-offs align chassis selection with street width constraints and route consolidation economics.
- Standard:Mid-range hopper volumes between heavy-duty and compact classifications suit mixed residential-commercial routes. These units balance payload efficiency with garage storage footprint in dense Japanese and Korean cities.
- Heavy-Duty:Maximum legal axle load configurations transport compacted municipal solid waste over extended distances to regional landfills. Demand clusters in Texas and Alberta where transfer station spacing requires highway-capable chassis.
- Compact:Reduced wheelbase designs navigate historic city centers and narrow alley networks. Rome and Barcelona procurement specifications prioritize compact maneuverability in UNESCO-protected districts.
- Super Compact:Miniaturized chassis with sub-3.5-ton gross vehicle weight classifications serve pedestrian zones and indoor facilities. Airport terminals and university campuses in Switzerland and Austria specify super compact units for restricted access environments.
Standard capacity leads unit shipments today; heavy-duty configurations are expanding most quickly on long-haul electrification trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting manufacturing investment toward jurisdictions with subsidized battery supply chains and lenient commercial vehicle emission timelines. OEMs now site final assembly where MIIT production quotas or EPA Phase 3 compliance costs determine tender eligibility.
United States
California Air Resources Board mandates and New York State diesel phase-out orders compress municipal replacement cycles. EPA Phase 3 greenhouse gas standards disqualify conventional diesel bids in coastal states. Los Angeles and San Francisco sanitation departments concentrate electric refuse truck pilots through CARB incentive programs.
China
MIIT new energy vehicle production quotas channel state procurement toward domestic electric chassis manufacturers. GB standards for commercial electrification create compliance obligations for suppliers serving state-owned sanitation bureaus. Shenzhen and Beijing municipal bureaus anchor battery-electric rear loader deployment through centralized tendering.
Germany
EU Green Deal clean mobility targets and the European Clean Vehicles Directive mandate zero-emission urban fleet procurement. KBA type-approval processes for alternative fuel chassis favor established OEMs with certification infrastructure. Berlin and Hamburg sanitation authorities lead hydrogen fuel cell refuse truck trials alongside battery-electric adoption.
India
Swachh Bharat Mission infrastructure allocations mechanize waste collection in tier-two metropolitan clusters previously dependent on informal labor. Central government urban sanitation modernization directs capital toward compact electric vehicles for narrow street networks. Maharashtra and Gujarat municipal corporations concentrate procurement through state-level sanitation corporation tenders.
Netherlands
European Clean Vehicles Directive transposition mandates 100% zero-emission municipal fleet procurement by 2030. National noise ordinances accelerate electric chassis adoption for early-morning residential collection routes. Amsterdam and Rotterdam anchor automated side-loader deployment with established curb-cart infrastructure.
Waste Collection Vehicle Market Competitive Environment
Platform diversification dominates the current landscape as OEMs certify electric and hydrogen variants to retain municipal tender eligibility. The vendor base stratifies across three tiers: diversified automotive conglomerates with captive battery supply, specialized refuse equipment fabricators with regional dealer networks, and state-backed Chinese manufacturers serving domestic procurement quotas. Two strategic archetypes have emerged: full-line chassis-body integrators pursuing fleet-as-a-service contracts, and component specialists supplying automated lifting mechanisms across OEM platforms. Competitive intensity centers on certification speed for zero-emission variants and backward integration into battery cell supply.
Within the diversified automotive tier, BYD Company exemplifies vertical control through in-house lithium iron phosphate cell production, insulating procurement from external commodity swings. Heil and McNeilus Truck and Manufacturing occupy positions as North American full-line integrators with established aftermarket parts networks spanning legacy diesel and emerging electric platforms. Fujian Longma Environmental Sanitation Equipment anchors the state-backed specialist archetype, concentrating on tier-one city tenders through localized manufacturing scale and MIIT compliance alignment.
| Leading Market Players |
|---|
| New Way |
| Autocar |
| McNeilus Truck and Manufacturing |
| BYD Company |
| Fujian Longma Environmental Sanitation Equipment |
| Heil |
| Peterbilt |
| Kässbohrer Geländefahrzeug |
| Labrie |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed Chinese producers and North American dealer-network specialists dominate ownership structures, compressing margin recovery through captive battery supply and aftermarket parts bundling while municipal procurement rules enforce transparent tender pricing.
Pricing Analysis
Distributor margins on electric chassis average 12-18 points above legacy diesel equivalents, reflecting certification scarcity and high-voltage technician training subsidies bundled into upfront quotes. Three-tier pricing structure across premium certified-electric, standard CNG-transition, and economy diesel-surplus levels separates fleet-as-a-service vendors from capital-sale operators. Cost compression in battery-electric tiers is intensifying because lithium iron phosphate cell oversupply from Chinese producers is eroding pack premiums. Municipal sanitation departments exhibit highest price sensitivity due to fixed appropriation cycles, while private contractors with route-optimization software show lowest sensitivity due to fuel-cost hedging visibility.
Supply Chain Analysis
Regional distribution centers in Ohio, Texas, and California anchor hub-and-spoke patterns for North American aftermarket parts, with Shenzhen, Ningbo, and Changzhou feeding finished chassis into ASEAN and European assembly nodes. The supply chain draws from Chilean lithium, Indonesian nickel, and Australian spodumene for cathode active materials, while axle and hydraulic systems rest on German and Japanese Tier 1 supply bases. Single-source vulnerability concentrates in lithium hydroxide processing capacity located within Chinese chemical parks. Distribution runs through municipal procurement cooperatives in the United States and state-owned sanitation bureau tendering platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Phase 3 greenhouse gas standards and EU Green Deal clean mobility mandates lock in zero-emission procurement timelines that outpace organic demand growth.
For Market Incumbents: Lock in battery supply agreements with lithium iron phosphate producers before cathode material allocation tightens around automotive passenger vehicle demand. Secure high-voltage technician certification programs through community college partnerships to reduce OEM service network dependency. Defend municipal tender eligibility by accelerating hydrogen fuel cell platform certification alongside battery-electric variants. For New Entrants and Emerging Players: Autonomous side-loader arm technology with machine vision recognition offers a technology-first wedge into Japanese and German markets facing acute driver shortage constraints. Target India's tier-two municipal corporations under Swachh Bharat infrastructure allocations where mechanized collection penetration remains below metropolitan benchmarks. Pursue fleet-as-a-service contracting models that transfer capital burden to private balance sheets and align revenue with uptime performance. For Investors and Strategic Acquirers: Valuations sit cheapest among regional refuse equipment fabricators lacking electric platform certification but possessing established aftermarket parts networks in coastal US states. Long-term viability hinges on conversion speed from diesel service revenue to electric platform recurring maintenance. Battery recycling infrastructure partnerships serve as the critical inflection signal for OEM margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium iron phosphate cell allocation from Chinese producers ahead of automotive demand competition. |
| High-Voltage Technician Certification Program | Builds maintenance capacity independent of constrained OEM service networks in Midwest municipalities. |
| Hydrogen Fuel Cell Platform Certification | Maintains tender eligibility in German and Dutch markets pursuing dual zero-emission technology pathways. |
| Autonomous Side-Loader Arm Development | Enables single-operator routes that compress labor costs in Japanese markets with aging workforce demographics. |
| Battery Recycling Partnership | Creates closed-loop material recovery revenue and reduces virgin lithium dependence for European regulatory compliance. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with municipal fleet managers, sanitation equipment procurement officers, OEM platform engineers, and aftermarket service directors alongside secondary validation. Secondary sources include EPA regulatory filings, EU Clean Vehicles Directive implementation reports, MIIT production quota disclosures, and municipal tender documentation from California, New York, Germany, and China. Bottom-up route-density modeling and top-down fleet replacement cycle analysis triangulate volume estimates.
Rate-of-change decomposition separates vehicle class adoption curves, propulsion architecture transitions, and regional regulatory enforcement intensity across the projection horizon. Segmentation dimensions span loader configuration, fuel type, end-user capital structure, and payload capacity tier. CAGRs derive from logistic diffusion modeling of zero-emission procurement mandates against infrastructure readiness constraints. Forecast inputs incorporate battery energy density improvement trajectories and charging depot capital appropriation cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium price volatility, hydrogen dispensing network buildout delays, and municipal debt ceiling constraints affecting fleet-as-a-service adoption. Outputs reflect documented assumptions around regulatory enforcement consistency and battery recycling infrastructure scaling. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Spain Car Rental Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Global Taxi Market
Transportation Services
Truck Rental Market
Transportation Services
Car Rental Service Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Car Rental Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Middle East Car Rental Market