
 United States Vehicle Rental Market | 2026-2036
United States Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
United States Vehicle Rental Market Analytics
Subscription-based fleet access is rewriting profit allocation across the United States vehicle rental sector. Enterprise Holdings leverages its neighborhood network density to sustain replacement-cycle advantages against airport-dependent rivals. Turo competes through peer-to-peer asset utilization, while Avis Budget Group anchors commercial accounts with centralized billing infrastructure.
United States vehicle rental denotes the short-term commercial provision of motorized road vehicles through contractual hire, encompassing passenger automobiles, light commercial vans, and heavy-duty trucks with odometer thresholds typically below 150,000 miles. The primary purpose is mobility substitution for travelers, temporary project logistics, and fleet overflow management. Car rental commands the largest revenue pool among service types, though electric vehicle categories are attracting disproportionate capital allocation. Leisure travelers generate the highest transaction volume, while corporate clients yield superior per-rental margins through negotiated rate structures.
FAA regulations governing airport concession agreements shape terminal counter placement and fee structures for on-site operators. EPA emissions standards and California Air Resources Board zero-emission mandates are accelerating fleet turnover timelines and capital expenditure requirements. NHTSA safety recall protocols affect vehicle availability and liability exposure for rental providers. Stakeholders must monitor state-level electrification mandates and airport concession renegotiations to align fleet composition with evolving access requirements.
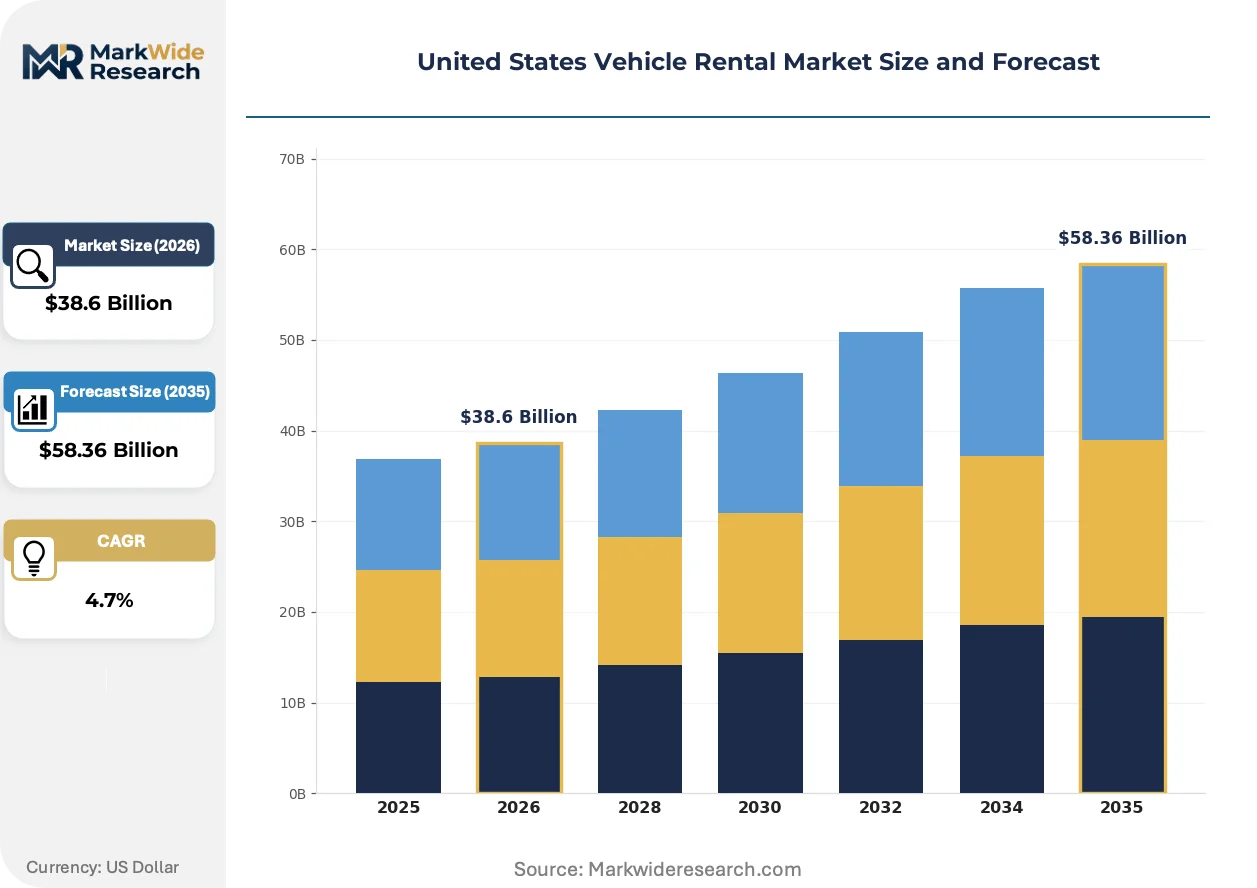
Market Dynamics
Fleet electrification mandates from California Air Resources Board are compressing replacement cycles and forcing capital reallocation toward battery electric vehicle procurement across the United States vehicle rental sector.
Growth Catalysts
- Airport Traffic Recovery:FAA concession agreements at Dallas-Fort Worth, Miami International, and Los Angeles International sustain utilization premiums for on-terminal operators. Leisure travel density in these hubs drives transaction volume.
- Corporate Fleet Outsourcing:Enterprise procurement teams are shifting overflow vehicle needs from owned fleets to short-term rental contracts. This redirects capital from depreciation reserves to operating expenditures.
- Zero-Emission Mandates:California Air Resources Board's Advanced Clean Cars II rule is compelling rental providers to electrify airport shuttle and local fleet segments ahead of 2035 deadlines.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based chip fabrication bottlenecks delay OEM delivery schedules for rental fleet replenishment. Extended order-to-delivery timelines strain vehicle availability during peak travel seasons.
- Lithium-Ion Battery Cost Volatility:Cathode material price swings and refining capacity constraints in Chile and Australia inflate electric vehicle acquisition premiums. This compresses margin structures for electrification-mandated fleet segments.
- Substitution from Ride-Hailing:Uber and Lyft urban density reduces impulse rental demand among business travelers in metropolitan cores. Smartphone-enabled on-demand mobility displaces short-duration car rental for sub-50-mile trips.
Strategic Opportunities
- Subscription Fleet Access:Monthly vehicle-as-a-service models penetrate underbanked consumer segments in Texas and Florida. These arrangements convert ownership-averse demographics into recurring revenue streams.
- Telematics-Insurance Convergence:Usage-based coverage integration with rental contracts creates ancillary revenue pools. Progressive and State Farm partnerships with rental providers monetize driving behavior data.
- Last-Mile Commercial Electrification:Light commercial van electrification serves construction and film production logistics in California. CARB commercial vehicle mandates accelerate this segment's capital deployment.
Industry Challenges
- Technician Certification Gaps:High-voltage battery service training lags electric vehicle fleet penetration. NHTSA safety protocols require specialized handling procedures that strain maintenance workforce development.
- Legacy Reservation System Integration:Real-time charge-state visibility and range-based pricing algorithms must interface with decades-old mainframe infrastructure. API middleware investments consume IT budgets without immediate revenue yield.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Vehicle Rental Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Car Rental, Van Rental, Truck Rental, Bus Rental Rental Duration: Short-term, Long-term, Monthly, Daily Vehicle Type: SUV, Sedan, Luxury, Electric Customer Type: Leisure Travelers, Business Travelers, Government Agencies, Corporate Clients |
| Companies Covered | Sixt SE, National Car Rental, Enterprise Holdings, Budget Rent a Car, Alamo Rent A Car, Avis Budget Group, Turo, Advantage Rent A Car, Hertz Global Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Vehicle Rental Market Evolving Landscape
Digital infrastructure is compressing the traditional counter-based rental transaction into smartphone-mediated vehicle access. This shift reconfigures real estate requirements and labor models across airport and neighborhood locations.
Telematics-enabled fleet management is virtualizing the traditional odometer-and-fuel-check return process. Rental providers now capture real-time vehicle health, location, and utilization metrics through embedded cellular modules. Airport operators at Hartsfield-Jackson Atlanta and Denver International are adopting this technology to reduce turnaround labor and accelerate reconditioning workflows.
California Air Resources Board zero-emission vehicle mandates are accelerating battery electric model penetration in airport shuttle and local rental segments. These rules force capital reallocation from internal combustion procurement toward charging infrastructure and electric vehicle supply agreements. Texas and Florida operators face competitive pressure to match California fleet composition for national account consistency.
Leisure travelers are compressing booking lead times through mobile-native platforms that aggregate inventory across rental providers and peer-to-peer alternatives. This behavior fragments demand forecasting accuracy and compresses yield management response windows. Miami and Orlando destination markets exhibit the shortest advance-booking intervals, forcing dynamic pricing algorithm investments.
United States Vehicle Rental Market Segmentation
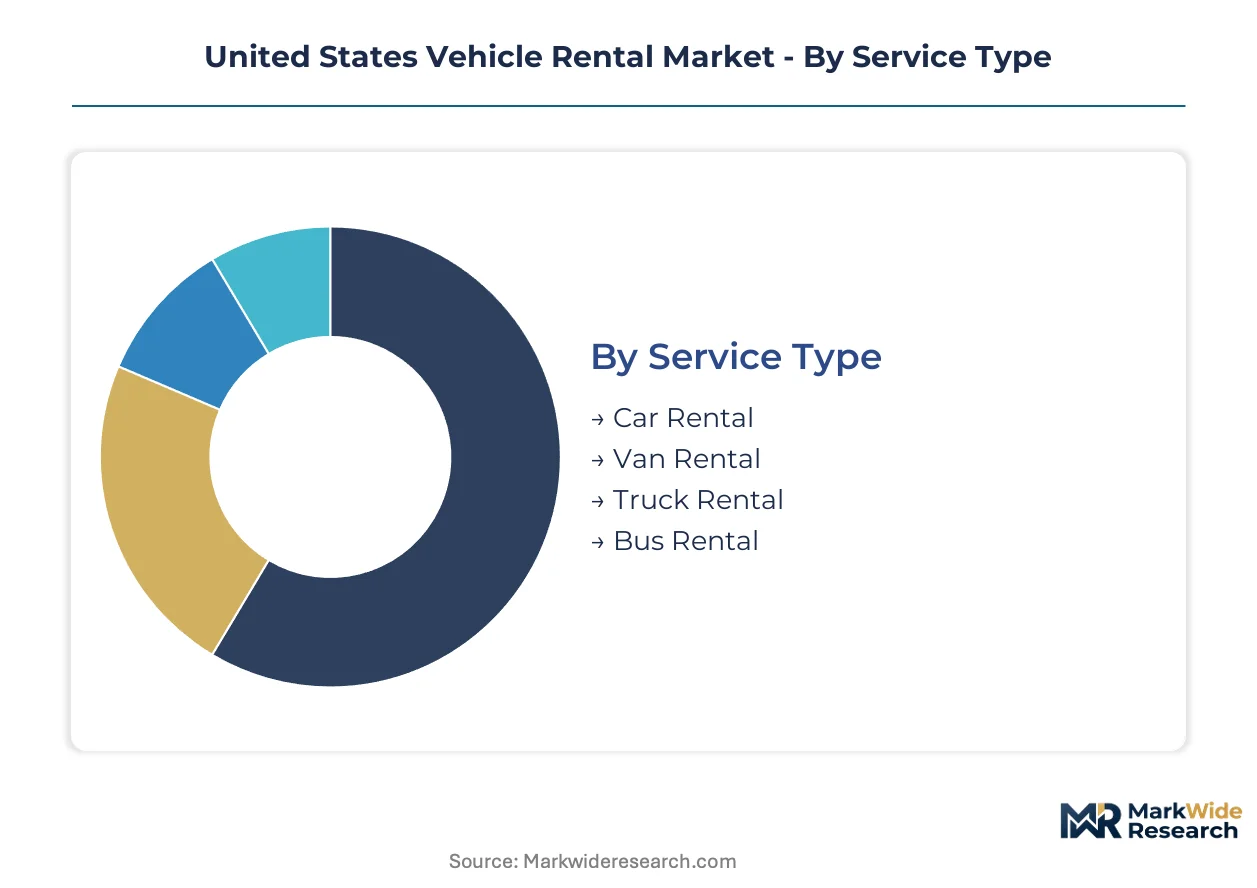
Segmentation in the United States vehicle rental market reveals distinct capital allocation patterns and operational requirements across service configurations. Fleet composition, rental duration economics, and customer procurement behaviors create divergent margin profiles that reshape competitive positioning.
Service Type:
Passenger mobility and commercial logistics generate fundamentally different utilization cycles and maintenance protocols across the service spectrum.
- Car Rental:Passenger automobile provision dominates transaction volume through airport counters and neighborhood locations. Leisure demand concentrates at Dallas-Fort Worth and Miami International terminals, while corporate accounts sustain weekday utilization premiums.
- Van Rental:Light commercial vehicles serve construction logistics and film production mobility in California. CARB commercial mandates accelerate electrification capital deployment for this segment.
- Truck Rental:Heavy-duty capacity supports temporary fleet overflow and project-based freight needs. Regional operators in Texas maintain specialized maintenance facilities for diesel powertrains.
- Bus Rental:Group transport contracts serve educational institutions and event logistics. Seasonal demand spikes strain driver certification availability during summer travel peaks.
Established volume favors car rental; emerging adoption favors van rental.
Rental Duration:
Contract length determines depreciation risk allocation and pricing algorithm complexity across operator portfolios.
- Short-term:Daily and weekly contracts maximize revenue per vehicle day through dynamic yield management. Airport operators at Los Angeles International capture premium rates from impulse leisure bookings.
- Long-term:Extended agreements transfer residual value risk to fleet operators while locking utilization commitments. Corporate procurement teams favor 90-day structures for project-based workforce mobility.
- Monthly:Subscription models penetrate ownership-averse demographics in Florida and Texas. These arrangements convert depreciation exposure into recurring revenue streams with embedded insurance products.
- Daily:Ultra-short transactions face displacement from ride-hailing in dense urban cores. Smartphone-mediated alternatives capture sub-50-mile trips that previously defaulted to rental counters.
Long-term contracts anchor fleet planning stability; monthly subscriptions are expanding most quickly.
Vehicle Type:
Powertrain technology and cabin configuration segment procurement budgets and charging infrastructure requirements.
- SUV:Elevated seating capacity and cargo volume command rate premiums in leisure destination markets. Family travel clusters in Orlando and Denver drive disproportionate SUV selection at airport counters.
- Sedan:Fuel-efficient compact and mid-size configurations dominate corporate account specifications. Business travelers in government and consulting sectors prioritize parking maneuverability over cargo capacity.
- Luxury:Premium marques serve executive replacement cycles and special occasion demand. Limited fleet depth constrains availability during conference seasons in metropolitan hubs.
- Electric:Battery electric models face CARB procurement mandates for airport shuttle and local rental segments. Charging infrastructure investments and technician certification gaps constrain rollout velocity.
Sedan inventory maintains broadest deployment; electric categories face steepest expansion trajectory.
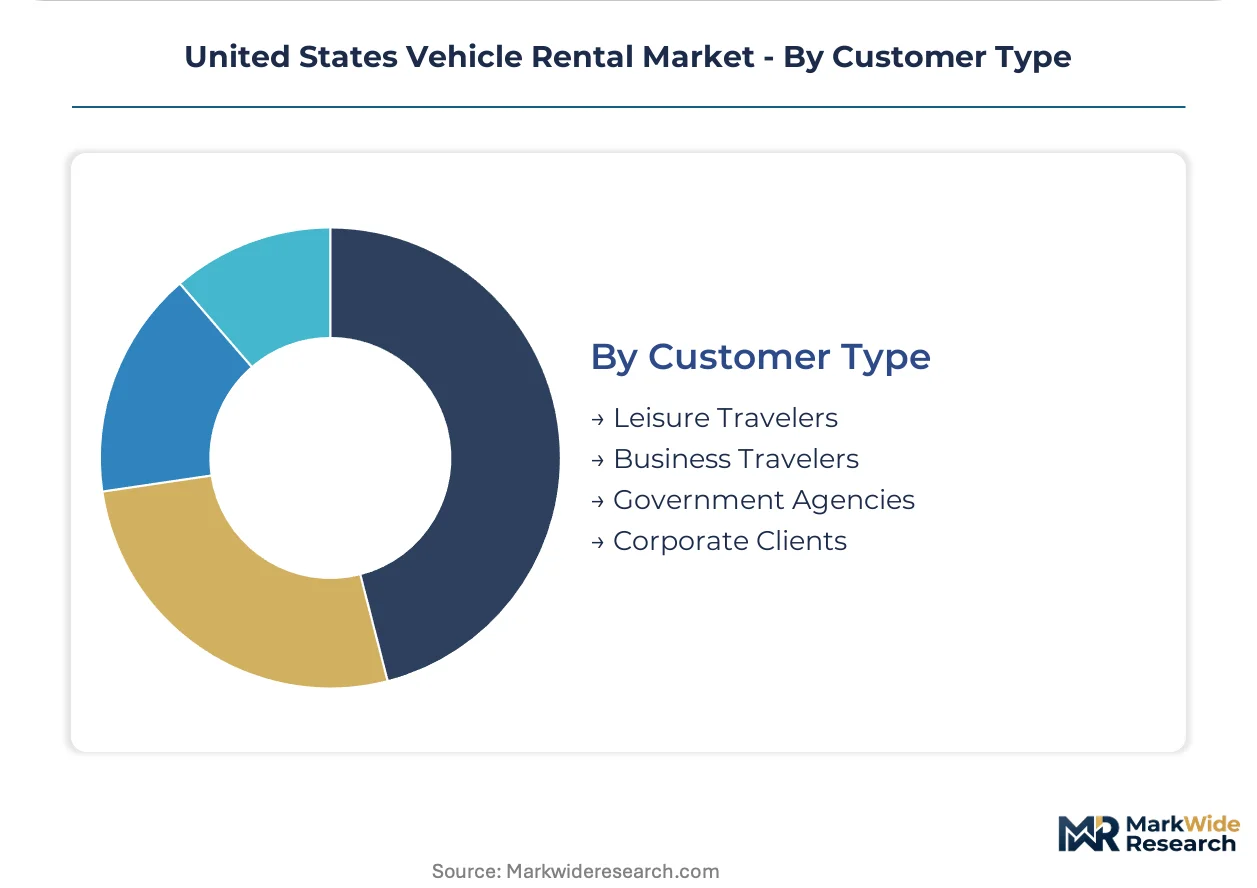
Customer Type:
Procurement authority and rate negotiation leverage create divergent margin structures across demand sources.
- Leisure Travelers:Individual bookings through aggregator platforms generate highest transaction volume with compressed lead times. Mobile-native booking behavior in Miami and Orlando forces dynamic pricing algorithm investments.
- Business Travelers:Corporate travel policies and centralized billing sustain per-rental margin premiums. Negotiated rate structures with Fortune 500 accounts lock out competitive alternatives.
- Government Agencies:Federal and state procurement vehicles operate under mandated small-business set-asides and domestic content requirements. GSA schedule compliance adds administrative overhead to contract execution.
- Corporate Clients:Fleet overflow outsourcing redirects capital from depreciation reserves to operating expenditures. Enterprise procurement teams shift owned-vehicle thresholds toward short-term rental contracts.
Leisure travelers drive transaction velocity; corporate clients capture margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas, Florida, and California deploy rental fleet capacity toward fundamentally different demand profiles. Texas concentrates on energy sector logistics and suburban mobility substitution. Florida prioritizes leisure destination throughput and snowbird seasonal migration. California channels investment toward regulatory compliance and electrification infrastructure.
Texas
Houston and Dallas-Fort Worth airport complexes sustain the nation's highest commercial vehicle transaction density. FAA concession agreements at Dallas-Fort Worth International lock in terminal counter placement for incumbent operators. Midland-Odessa energy corridor demand drives heavy-duty truck rental utilization for Permian Basin logistics.
Florida
Orlando and Miami International terminals process leisure travelers with the shortest booking lead times in the country. Florida Department of Transportation port access programs facilitate cruise passenger vehicle turnover. Tampa Bay construction logistics sustain light commercial van rental demand through winter peak seasons.
California
Los Angeles International and San Francisco International anchor the nation's strictest zero-emission fleet transition timeline. California Air Resources Board Advanced Clean Cars II mandates compress electric vehicle procurement deadlines. Silicon Valley corporate shuttle contracts redirect fleet investment toward battery electric airport transfer segments.
Illinois
Chicago O'Hare and Midway International sustain Midwest business travel corridor density. Illinois Commerce Commission motor carrier regulations shape interstate truck rental permitting workflows. Rockford logistics clusters support manufacturing overflow fleet demand through just-in-time supply chain volatility.
Arizona
Phoenix Sky Harbor International captures snowbird seasonal migration and spring training tourism velocity. Arizona Department of Transportation highway expansion projects sustain construction equipment rental demand. Tucson semiconductor fabrication site development drives temporary workforce mobility contracts.
United States Vehicle Rental Market Competitive Landscape
Capability concentration sits with neighborhood-network specialists; scale advantage sits with airport-terminal incumbents. The market structures around three tiers: integrated holding companies with multi-brand portfolios, technology-mediated peer-to-peer platforms, and regional specialists with fleet-type concentration. Competitive moves center on electrification infrastructure partnerships and subscription-model capability acquisition.
Among integrated holding company structures, Enterprise Holdings and Avis Budget Group represent archetypal scale-and-scope positioning. Turo occupies a distinct peer-to-peer asset utilization tier. These three entities exemplify the strategic divergence between owned-fleet density and distributed-owner marketplace models.
| Leading Market Players |
|---|
| Sixt SE |
| National Car Rental |
| Enterprise Holdings |
| Budget Rent a Car |
| Alamo Rent A Car |
| Avis Budget Group |
| Turo |
| Advantage Rent A Car |
| Hertz Global Holdings |
| Others |
Value Network & Pricing Analysis
Taiwan-based semiconductor fabrication concentration directly determines fleet procurement timelines and rate volatility for United States vehicle rental operators. OEM delivery delays compress vehicle availability during peak seasons, forcing dynamic pricing algorithms to absorb demand spikes into rate premiums.
Pricing Analysis
Long-term corporate offtake agreements anchor rate stability for Fortune 500 accounts, while leisure bookings through aggregator platforms trade at spot-market volatility. Pricing stratifies across premium SUV tiers, standard sedan configurations, and economy compact segments based on cabin capacity and fuel efficiency ratings. Cost compression in electric vehicle categories is intensifying because lithium-ion cathode material volatility inflates acquisition premiums above internal combustion baselines. Corporate procurement teams exhibit lowest price sensitivity through negotiated master service agreements, whereas mobile-native leisure travelers in Miami and Orlando demonstrate highest elasticity to real-time rate fluctuations.
Supply Chain Analysis
Tariff exposure between the United States and Mexico dominates fleet replenishment risk for light commercial van segments serving Texas construction logistics. Vehicle assembly draws from Mexico, South Korea, and Japan for passenger automobile supply, with heavy-duty truck sourcing concentrated in domestic Michigan and Indiana production clusters. Lithium carbonate, nickel sulfate, and semiconductor chip dependencies expose electric vehicle procurement to Chilean mining output and Taiwanese fabrication capacity. Single-source vulnerability in battery management system components threatens electrification rollout timelines. Distribution runs through airport concession networks and neighborhood service centers, with peer-to-peer platforms disintermediating traditional counter-based transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States vehicle rental sits in early-cycle expansion as fleet electrification mandates force capital reallocation toward battery electric procurement ahead of regulatory deadlines. Subscription-based access models and telematics-insurance convergence create new margin pools beyond traditional per-day rate structures.
For Market Incumbents: Entrench neighborhood network density against peer-to-peer displacement by converting owned-fleet depreciation exposure into recurring subscription revenue streams. Secure exclusive charging infrastructure partnerships at Dallas-Fort Worth and Los Angeles International terminals before CARB mandates lock in competitor placement. Vertical integration into telematics data monetization with Progressive and State Farm anchors ancillary revenue against ride-hailing substitution in urban cores. For New Entrants and Emerging Players: Establish a beachhead in monthly subscription fleet access for ownership-averse demographics in Texas and Florida, where credit-thin consumers seek vehicle-as-a-service alternatives to traditional financing. Target light commercial van electrification for California construction and film production logistics, where CARB commercial mandates accelerate capital deployment into underserved segments. Deploy smartphone-native vehicle access platforms that bypass legacy mainframe reservation systems through API middleware. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists holding concentrated fleet-type exposure in heavy-duty truck or bus rental categories. Five-to-ten year viability hinges on electrification infrastructure execution and technician certification pipeline development. Watch California Air Resources Board zero-emission mandate enforcement velocity as the inflection signal for national fleet composition convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Exclusive terminal placement at LAX and DFW locks in utilization premiums against airport-dependent rivals. |
| Telematics-Insurance Integration | Progressive and State Farm partnerships monetize driving behavior data into usage-based coverage revenue pools. |
| Subscription Model Capability Acquisition | Monthly vehicle-as-a-service platforms convert depreciation exposure into recurring revenue with embedded insurance products. |
| Electric Fleet Procurement Acceleration | CARB Advanced Clean Cars II compliance ahead of 2035 deadlines secures national account consistency for California operators. |
| Peer-to-Peer Platform Technology Licensing | Turo-style asset utilization models expand fleet capacity without capital-intensive vehicle ownership balance sheets. |
Research Methodology
A standing panel of fleet operations directors, airport concession managers, corporate travel procurement leads, and telematics platform engineers provided ongoing calibration against operating reality. Primary interview insights combined with secondary validation from FAA concession agreement filings, EPA emissions compliance databases, NHTSA safety recall protocols, and California Air Resources Board regulatory dockets. Bottom-up fleet utilization metrics and top-down market sizing triangulated across vehicle registration data and airport passenger throughput statistics.
Scenario-bracketing around semiconductor supply recovery trajectories and lithium-ion cost volatility bands framed the analytical envelope across the projection horizon. Segmentation modeling incorporated service type, rental duration, vehicle powertrain architecture, and customer procurement authority dimensions. CAGRs derived from vehicle replacement cycle compression and electrification capital deployment curves, with electric vehicle penetration rates and charging infrastructure buildout schedules as core forecast inputs.
Stress conditions across cathode material price swings, Taiwan fabrication bottlenecks, and CARB mandate acceleration timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about corporate travel policy normalization and leisure booking lead time compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Corporate Car Sharing Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
Russia Car Rental Market
Transportation Services
Car Rental Market
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
India Car Rental Market
Transportation Services
Truck Rental Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Car Rental Service Market
Transportation Services
Peer-To-Peer (P2P) Car-Sharing Market
Transportation Services
Refuse Truck Market
Transportation Services
Taxi and Ride-Hailing Services Market