
 Europe Excavator and Loaders Market | 2026-2036
Europe Excavator and Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Excavator and Loaders Market Foresight
Single-source supply arrangements for hydraulic systems and powertrain components is consolidating into multi-year framework agreements with tier-one suppliers. Volvo Construction Equipment leverages its captive axle and transmission production to control lead times across Nordic project sites. Caterpillar Inc. anchors its European position through an extensive dealer service network spanning Germany, France, and Poland. Komatsu Corp. differentiates via integrated machine control and telematics platforms that tie equipment productivity to contract billing cycles.
Europe excavator and loaders comprise self-propelled earthmoving machinery with operating weights from one to ninety metric tons, utilizing hydraulic circuits to generate breakout forces exceeding two hundred kilonewtons for trenching, grading, and material transport. Steel fabrication dominates chassis production, with boom and arm assemblies requiring high-strength plate welding to withstand cyclic loading in demolition environments. Crawler excavators occupy the largest revenue pool given their deployment in German foundation work and French rail corridor upgrades, while electric and autonomous technologies represent the fastest-expanding technology segment as contractors face Stage V compliance deadlines and labor scarcity on tight urban job sites. Compact loaders sustain margin density through attachment versatility in landscaping and agricultural utility roles across Benelux and Northern Italy.
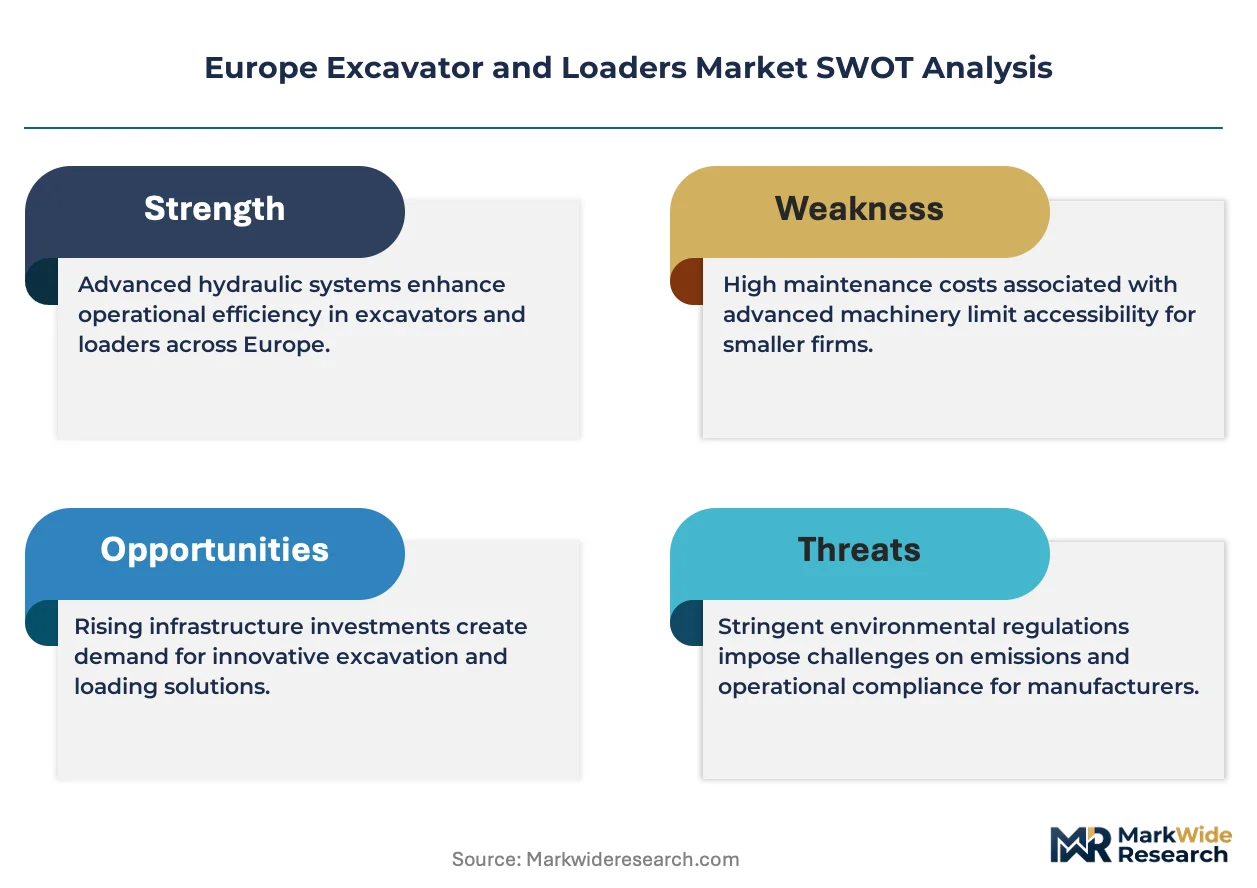
The EU Green Deal and Stage V emission standards enforced by the European Commission constrain diesel-powered equipment sales and redirect capital toward electric-hybrid platforms. CE marking requirements under the Machinery Directive establish conformity benchmarks for hydraulic safety and operator visibility that non-European exporters must satisfy for market access. ECHA REACH regulations govern chemical composition in hydraulic fluids and surface coatings, adding compliance layers to aftermarket parts distribution. Stakeholders must monitor battery supply chain localization policies and charging infrastructure buildouts as electrification shifts total cost of ownership calculations across contractor fleets.
Market Dynamics
Stage V emission standards under EU regulation are compressing diesel equipment lifecycles and forcing capital redeployment toward electric-hybrid powertrains across German and French municipal fleets.
Growth Catalysts
- EU Green Deal infrastructure allocation:German and French municipal contractors are expanding equipment procurement for rail corridor upgrades and urban foundation work, directing public capital toward compliant machinery.
- Electric powertrain maturation:Battery energy density improvements and onboard charging systems are enabling full-shift operation in compact excavators deployed across Nordic mining corridors.
- Autonomous machine control:Integrated telematics platforms that tie equipment productivity data directly to contract billing cycles are accelerating adoption among large civil engineering consortiums.
Market Restraints
- Lithium-ion supply concentration:Battery cell production clusters in East Asia create import dependency and lead time volatility for European OEMs assembling electric excavators.
- Steel alloy cost volatility:High-strength plate welding requirements for boom and arm assemblies expose fabricators to scrap metal and alloy surcharge fluctuations.
- Stage V retrofit limitations:Legacy diesel units in Benelux contractor fleets face technical barriers to exhaust after-treatment upgrades, accelerating premature retirement.
Strategic Opportunities
- Polish equipment leasing penetration:Underdeveloped rental infrastructure in Eastern European construction markets creates channel expansion potential for fleet-as-a-service models.
- Hydrogen fuel cell convergence:Proton exchange membrane systems paired with electric drivetrains offer zero-emission alternatives for heavy crawler excavators beyond battery range limits.
- CE marking compliance services:Non-European exporters seeking Machinery Directive conformity create aftermarket revenue pools for certification and hydraulic safety validation.
Industry Challenges
- High-voltage technician scarcity:Electric powertrain maintenance requires specialized training that vocational programs in Northern Italy and Spain have not yet scaled to fleet demand.
- Charging infrastructure capex:Urban job sites in German construction zones lack grid capacity for simultaneous multi-machine fast-charging, requiring contractor investment in on-site battery storage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Excavator and Loaders Market |
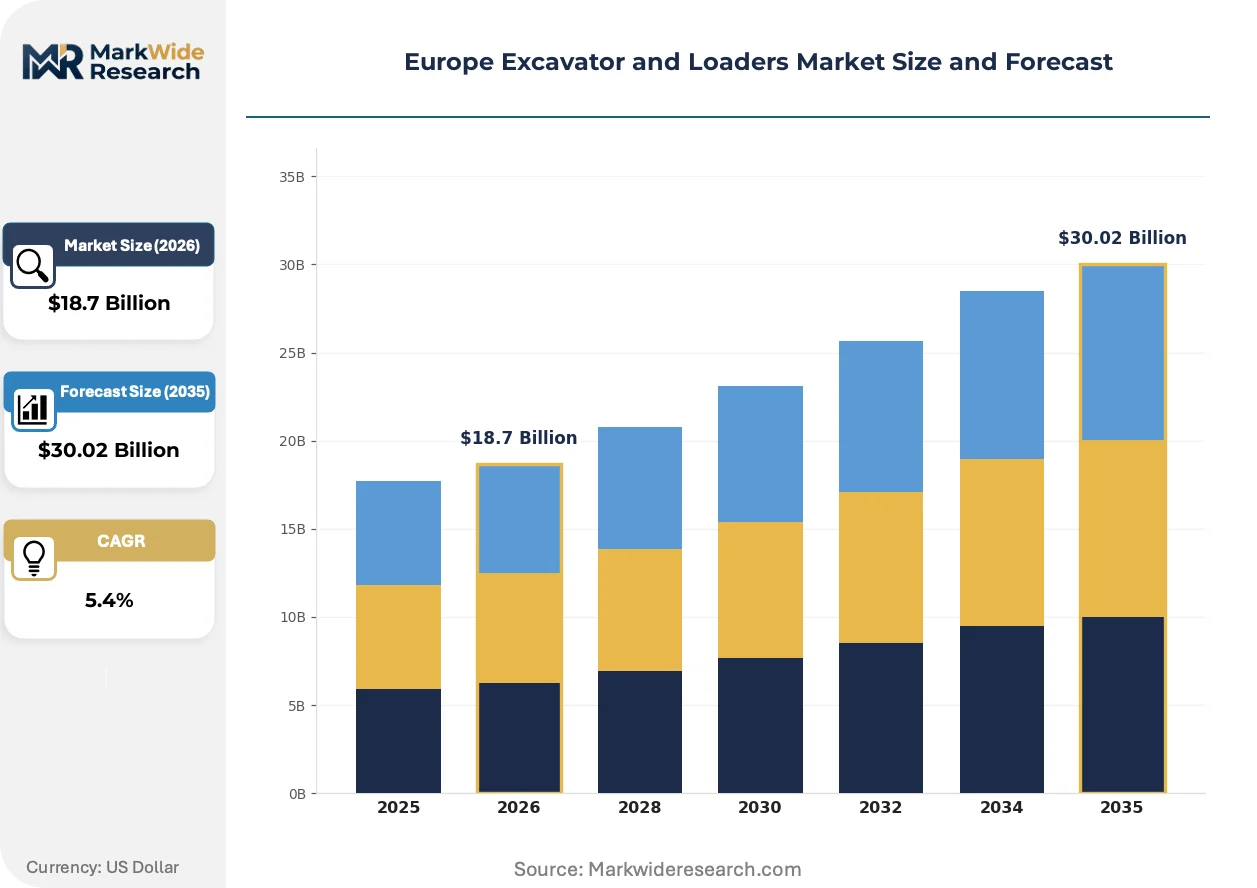
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Excavators, Crawler Excavators, Wheeled Loaders, Compact Loaders End User: Construction, Mining, Landscaping, Agriculture Technology: Hydraulic, Electric, Autonomous, Diesel Application: Earth Moving, Material Handling, Demolition, Site Preparation |
| Companies Covered | Volvo Construction Equipment, Hitachi Construction Machinery, Caterpillar Inc., Doosan Bobcat Co., CNH Industrial N.V., Komatsu Corp., JCB, Kobelco Construction Machinery, Liebherr Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Excavator and Loaders Market Shifts & Advancements
Electrification, autonomous control systems, and servitized procurement models are restructuring how European contractors acquire, operate, and maintain earthmoving equipment across fragmented municipal and mining end-uses.
Machine learning-based predictive maintenance algorithms are converging with hydraulic system sensor networks to enable condition-based component replacement. Large civil engineering contractors in France are piloting these platforms to compress unplanned downtime intervals. The technology is converging with fleet management software to reshape aftermarket parts logistics and dealer service scheduling.
CE marking requirements under the EU Machinery Directive are tightening conformity benchmarks for hydraulic safety circuits and operator visibility standards. Non-European exporters must now satisfy extended documentation and testing protocols before market access. Compact loader segments face the steepest compliance timeline compression as third-country manufacturers recertify product lines.
Rental and leasing penetration is displacing outright purchase in German municipal procurement as public sector budget constraints favor operational expenditure treatment. Equipment-as-a-service contracts now bundle maintenance, telematics, and uptime guarantees into single monthly rates. This shift is most visible in urban construction zones where project duration uncertainty makes fleet flexibility more valuable than asset ownership.
Europe Excavator and Loaders Market Segmentation
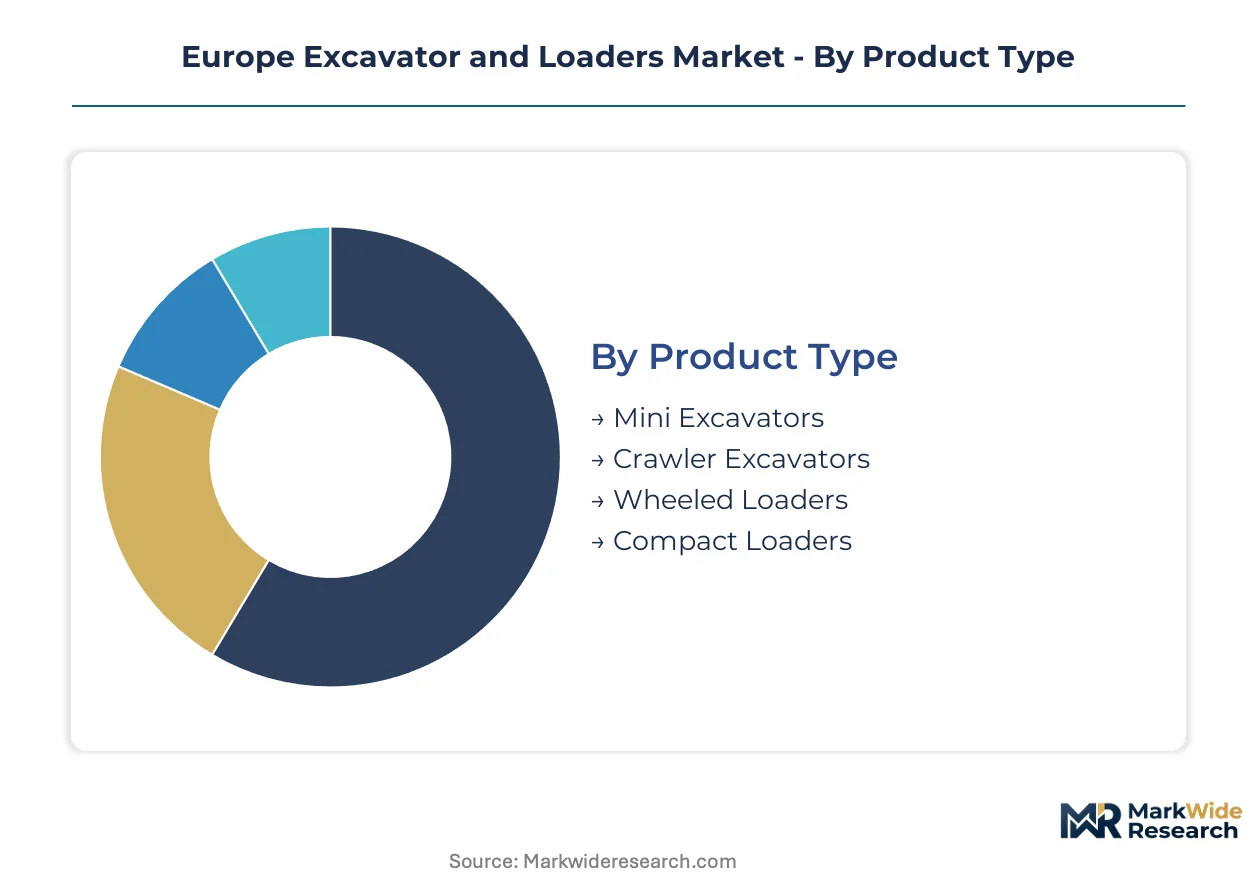
Equipment specification tiers determine financing structures and fleet depreciation schedules across European contractor operations. Segmentation clarity enables procurement officers to align powertrain choices with Stage V compliance timelines and project duration profiles.
Product Type:
Capital intensity varies sharply across operating weight classes, with full-size crawler units demanding the highest upfront outlays and longest amortization periods.
- Crawler Excavators:Steel-tracked chassis with operating weights from ten to ninety metric tons generate breakout forces exceeding two hundred kilonewtons for German foundation work and French rail corridor upgrades. Municipal contractors in Nordrhein-Westfalen concentrate procurement here for infrastructure renewal timelines.
- Mini Excavators:Compact hydraulic systems below six metric tons deploy rubber-tracked or wheeled configurations for urban utility trenches and tight-access demolition. Demand clusters in Benelux landscaping fleets where Stage V retrofit costs disproportionately burden older diesel units.
- Wheeled Loaders:Articulated steering and hydrostatic transmissions serve material stockpiling and truck loading across Nordic mining corridors.
- Compact Loaders:Skid-steer and compact track variants sustain attachment versatility for agricultural utility roles in Northern Italy.
Most installed capacity flows through Crawler Excavators. Expansion is steepest in Mini Excavators.
End User:
Customer concentration patterns reveal which segments absorb electrification premiums and which prioritize total cost of ownership.
- Construction:General and civil engineering contractors dominate unit volumes across German urban zones and French municipal projects. Stage V compliance deadlines accelerate fleet turnover in this segment faster than mining or agriculture.
- Mining:Surface extraction operations in Swedish and Finnish ore corridors specify heavy crawler configurations with integrated telematics for productivity-linked contract billing. Battery-electric prototypes face range limitations in 24-hour continuous duty cycles.
- Landscaping:Seasonal demand patterns in Benelux and Northern Italy favor compact loader rentals over ownership.
- Agriculture:Mixed-use utility roles in Poland and Romania prioritize attachment interchangeability and dealer proximity.
Construction commands the largest equipment population. Mining shows the highest specification intensity per unit.
Technology:
Powertrain selection now hinges on regulatory enforcement timelines rather than fuel cost differentials alone.
- Electric:Battery-electric drivetrains with onboard charging enable full-shift operation in compact excavators below eight metric tons. German municipal fleets in Berlin and Hamburg pilot these for zero-emission urban construction zones.
- Hydraulic:Open-center and load-sensing circuits remain standard for heavy breakout applications where electric actuation lacks force density. French demolition contractors specify these for cyclic loading environments.
- Diesel:Stage V-compliant engines with selective catalytic reduction dominate transitional fleets facing premature retirement pressures in Benelux.
- Autonomous:Machine control platforms with GPS guidance and telematics integration tie productivity data to contract billing cycles for large civil engineering consortiums.
Hydraulic systems retain the broadest installed base. Electric configurations are gaining share fastest in compact classes.
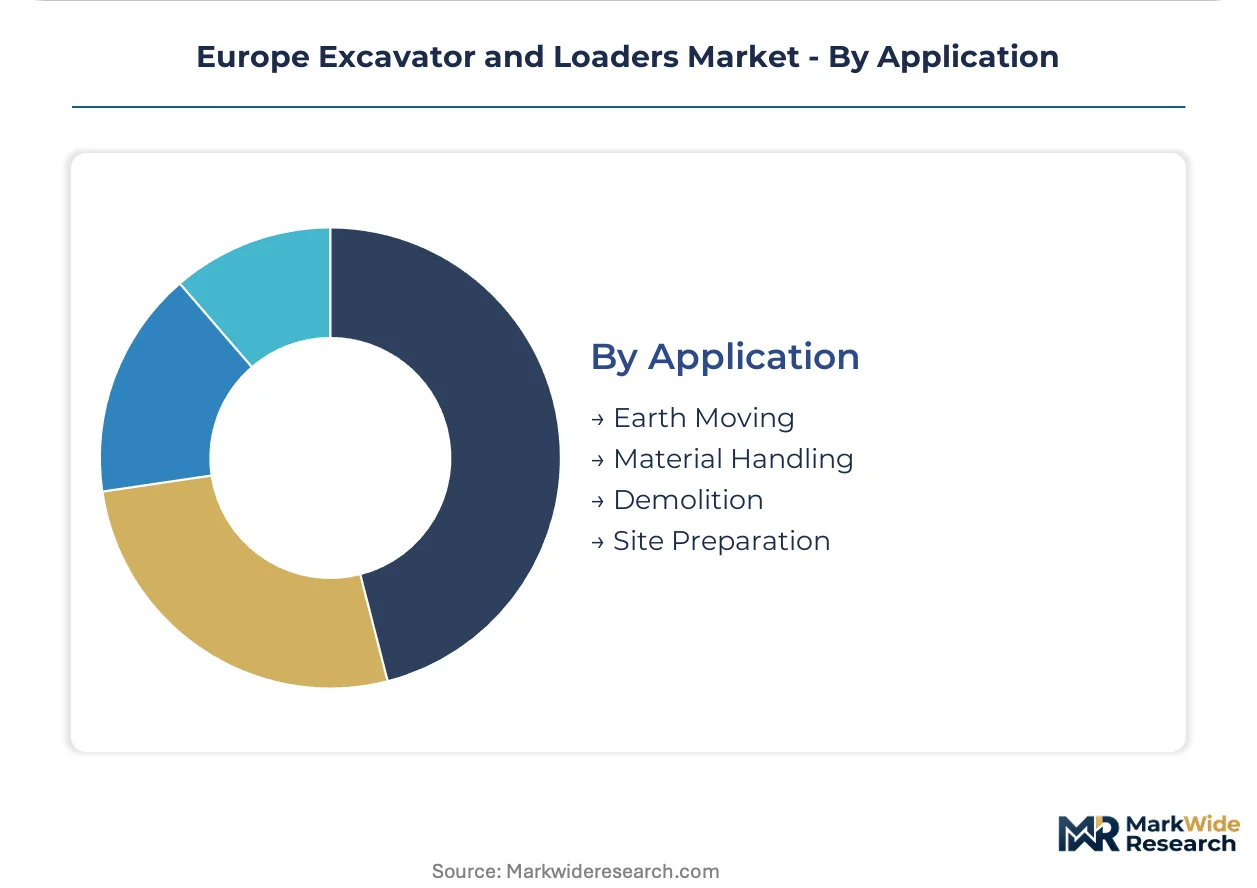
Application:
Task specificity determines attachment economics and machine utilization rates across fragmented job sites.
- Earth Moving:Mass excavation and trenching operations in German foundation work specify high-displacement hydraulic pumps for rapid cycle times. This application absorbs the heaviest depreciation loads per operating hour.
- Demolition:High-reach booms with reinforced structures withstand impact loading in French urban decommissioning projects. CE marking requirements for hydraulic safety circuits are tightest here.
- Material Handling:Load-and-carry cycles in Nordic aggregates processing favor wheeled loader configurations with quick-coupler systems.
- Site Preparation:Grading and leveling tasks across Polish road projects integrate machine control for precision earthworks.
Earth Moving represents the largest application volume. Demolition carries the steepest specification premiums per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region anchors European equipment demand through dense municipal infrastructure networks and concentrated contractor fleets serving German foundation work and rail corridor upgrades.
Germany
Nordrhein-Westfalen municipalities are procuring crawler excavators for urban renewal timelines, while Berlin and Hamburg pilot battery-electric compact units under Stage V enforcement. The KBA enforces emission conformity for diesel-hybrid transitional fleets. Equipment lessors in Munich and Stuttgart are bundling telematics into municipal framework agreements.
France
Île-de-France civil engineering consortiums specify high-reach demolition configurations for urban decommissioning projects, absorbing premium specification costs. The ANSM-aligned machinery safety protocols tighten CE marking documentation for hydraulic circuits. Lyon and Marseille contractors are integrating autonomous machine control platforms that tie productivity data to contract billing cycles.
Sweden
Swedish surface extraction operations in Kiruna and Malmberget deploy heavy crawler configurations with integrated telematics for 24-hour continuous duty cycles. REACH regulations govern hydraulic fluid composition in Arctic operating conditions. Battery-electric prototypes face range limitations in northern ore corridors where charging infrastructure remains sparse.
Poland
Warsaw and Kraków construction zones are absorbing compact loader volumes for road project site preparation, with contractors prioritizing attachment interchangeability. EU Green Deal infrastructure allocation directs public capital toward compliant machinery procurement. Equipment leasing penetration remains underdeveloped across Silesian and Pomeranian Voivodeships, creating channel expansion potential.
Italy
Northern Italian agricultural utility operators in Lombardy and Emilia-Romagna favor compact skid-steer variants for seasonal landscaping cycles. ECHA REACH compliance adds certification layers to aftermarket parts distribution for hydraulic systems. Dealer proximity determines procurement decisions across fragmented Veneto and Piedmont contractor networks.
Europe Excavator and Loaders Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric powertrain specialization and autonomous control integration. The vendor base stratifies across three tiers: integrated OEMs with captive component production, specialized fabricators focused on compact weight classes, and regional assemblers serving price-sensitive Eastern European markets. Dominant competitive moves include multi-year framework agreements with tier-one hydraulic suppliers and backward integration into axle and transmission manufacturing.
Among Sweden-based integrated producers, Volvo Construction Equipment exemplifies the captive supply chain archetype through in-house axle and transmission production. Caterpillar Inc. anchors the extensive service network tier across German, French, and Polish dealer territories. Komatsu Corp. occupies the telematics integration position, with machine control platforms representing the productivity-linked contract billing archetype.
| Leading Market Players |
|---|
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| Caterpillar Inc. |
| Doosan Bobcat Co. |
| CNH Industrial N.V. |
| Komatsu Corp. |
| JCB |
| Kobelco Construction Machinery |
| Liebherr Group |
| Others |
Supply & Pricing Matrix
Stage V certification tiers split procurement economics between compliant electric-hybrid platforms and residual diesel units facing accelerated depreciation. Municipal contractors in Germany and France absorb premium pricing for CE-marked machinery with integrated telematics, while Polish and Romanian fleet operators trade specification depth for dealer proximity and faster delivery windows.
Pricing Analysis
Steel alloy surcharges and lithium-ion cell import costs pass through to equipment list prices with 60-90 day lag structures. Pricing stratifies across premium, standard, and economy tiers based on CE marking documentation depth and captive axle production. Cost compression in compact excavators intensifies as Chinese battery pack suppliers enter Nordic mining corridors. Municipal procurement officers in Berlin and Hamburg show lowest price sensitivity; Polish agricultural contractors exhibit highest.
Supply Chain Analysis
Battery supply chain localization mandates under EU Green Deal industrial policy are redirecting cell procurement from South Korea toward planned European gigafactories. High-strength steel plate draws from German and Swedish mills; hydraulic pumps and motors rest on German and Italian component clusters. Single-source vulnerability concentrates in East Asian battery cell production. Distribution runs through manufacturer-owned dealer networks with captive service territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe excavator and loaders procurement is shifting toward premium electric-hybrid specifications as Stage V enforcement hardens compliance timelines across German and French municipal fleets.
For Market Incumbents: To counter emerging electric-specialist entrants from Asia, deepen backward integration into battery pack assembly and axle manufacturing. Secure multi-year framework agreements with tier-one hydraulic suppliers to lock in capacity. Anchor dealer service networks in Eastern European expansion zones where leasing penetration remains underdeveloped. For New Entrants and Emerging Players: Launch via equipment-as-a-service contracts targeting Polish municipal contractors with bundled maintenance and uptime guarantees. Exploit white-space in compact loader rentals across Silesian and Pomeranian Voivodeships. Prioritize CE marking compliance services for non-European exporters seeking Machinery Directive conformity. For Investors and Strategic Acquirers: Consolidation pressure builds where vocational training scarcity constrains electric powertrain maintenance capacity across Northern Italy and Spain. Mid-tier fabricators with captive hydraulic system production represent prime acquisition targets over a five-to-ten year electrification transition. Watch battery supply chain localization announcements as inflection signals for OEM margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Reduces import dependency on East Asian cell suppliers for German OEMs. |
| CE Marking Compliance Service Expansion | Captures aftermarket revenue from Chinese and Turkish exporters entering Europe. |
| Equipment-as-a-Service Platform Launch | Aligns procurement economics with Polish municipal budget constraints. |
| Hydrogen Fuel Cell Prototype Development | Extends zero-emission range beyond battery limits in Swedish ore corridors. |
| Multi-Year Hydraulic Supplier Framework | Locks in component capacity as Stage V compliance accelerates fleet turnover. |
Research Methodology
Coverage spans Western Europe, Nordic region, and Eastern Europe, with primary inputs from each territory combining interviews with municipal procurement officers, fleet maintenance directors, OEM product managers, and aftermarket service heads. Secondary validation draws from EU Machinery Directive filings, ECHA REACH substance registrations, KBA emission conformity databases, and national construction equipment registration statistics. Bottom-up unit demand modeling triangulates against top-down infrastructure spending allocation data.
Granularity extends to operating weight class, powertrain architecture, and end-use application across the projection horizon. Segmentation dimensions include product type, technology tier, customer concentration patterns, and regional regulatory enforcement intensity. CAGRs derive from fitted growth curves anchored to infrastructure renewal timelines and electrification adoption S-curves. Stage V compliance deadlines and battery energy density improvement trajectories serve as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption or accelerated hydrogen fuel cell breakthrough scenarios. Assumptions reflect documented infrastructure allocation schedules and OEM electrification roadmaps. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Crawler Dozers Market
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Bulldozer Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Jackhammer Market
Construction Equipment
Electric Excavators Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Track Mounted Gangway Market
Construction Equipment
North America Drilling Market