
 Down-The-Hole (DTH) Hammer Bits Market | 2026-2036
Down-The-Hole (DTH) Hammer Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Down-The-Hole (DTH) Hammer Bits Market Foresight
Single-source procurement for critical carbide inserts is repositioning toward qualified multi-source arrangements across the DTH hammer bits supply base. Sandvik AB leverages captive tungsten carbide production to sustain margin control across its bit portfolio. Mincon Group PLC anchors its competitive stance through specialized hard-rock geometries optimized for variable ground conditions. Drill King International differentiates by operating dedicated service hubs near active mining districts in the southwestern United States and western Canada.
Down-the-hole hammer bits are percussive drilling tools that transmit impact energy through a piston-driven mechanism directly at the borehole bottom, typically employing cemented tungsten carbide inserts bonded into steel bit bodies to fracture rock formations in blind-hole applications. The tool functions primarily in rotary-percussive drilling rigs where compressed air flushes cuttings while the bit advances. Conic bits dominate surface mining and water well installations where hole deviation tolerance allows aggressive cutting structures. Retractable bits command premium positioning in deep-hole oil and gas exploration where trip-time reduction delivers measurable rig-day savings. Carbide material grades stratify performance tiers, with coarse-grain substrates outperforming in abrasive quartzite while fine-grain variants resist thermal fatigue in geothermal basalt drilling.
ISO 18758 establishes percussion drilling tool performance benchmarking that shapes procurement specifications for mining contractors across Chile and Australia. EPA particulate standards from the United States and REACH substance restrictions from Europe constrain cobalt binder formulations and surface coating chemistries in carbide manufacturing. Mining companies and oil producers must monitor evolving tungsten supply chain traceability requirements from OECD due diligence frameworks as conflict-mineral scrutiny intensifies for strategic metal inputs.
Market Dynamics
Tungsten carbide supply concentration in China is forcing mining contractors to requalify secondary material sources and absorb elevated input costs across DTH bit manufacturing networks.
Growth Catalysts
- Hard-rock mining expansion:Copper extraction in Peru and platinum operations in South Africa are extending drill-meterage requirements, pulling premium bit specifications into procurement tenders.
- ISO 18758 standardization:Performance benchmarking protocols from ISO certification bodies are harmonizing procurement specifications across Australian and Chilean contractor fleets.
- Geothermal drilling acceleration:Basalt penetration rates in Iceland and Kenya are driving thermal-fatigue-resistant carbide formulations into commercial scale.
Market Restraints
- Cobalt binder cost volatility:Cobalt metal price swings from Congolese concentrate supply disruptions are compressing margin predictability for carbide insert fabricators.
- REACH substance restrictions:ECHA surface-coating limitations on hexavalent chromium platings are forcing European bit manufacturers into costly process requalification cycles.
- Substitution by rotary tricone bits:Softer sedimentary formations in Middle Eastern oilfields are permitting roller-cone alternatives to capture selected DTH applications.
Strategic Opportunities
- Underpenetrated lithium brine drilling:Argentina's Salta Province and Chile's Atacama are opening dedicated DTH bit service contracts for salar caprock penetration.
- EU Green Deal carbon border adjustments:CBAM implementation on imported steel bodies is creating first-mover advantage for European carbide-to-bit integrated producers.
- Predictive maintenance convergence:IoT sensor integration with compressed-air monitoring systems is enabling condition-based bit replacement contracts.
Industry Challenges
- Carbide metallurgist scarcity:Specialized sintering process engineers with fine-grain substrate expertise are concentrated at a handful of research institutes and captive operations.
- Multi-source qualification timelines:Mining contractors require 18-24 month field trials before approving secondary carbide insert suppliers for critical blasthole applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Down-The-Hole (DTH) Hammer Bits Market |
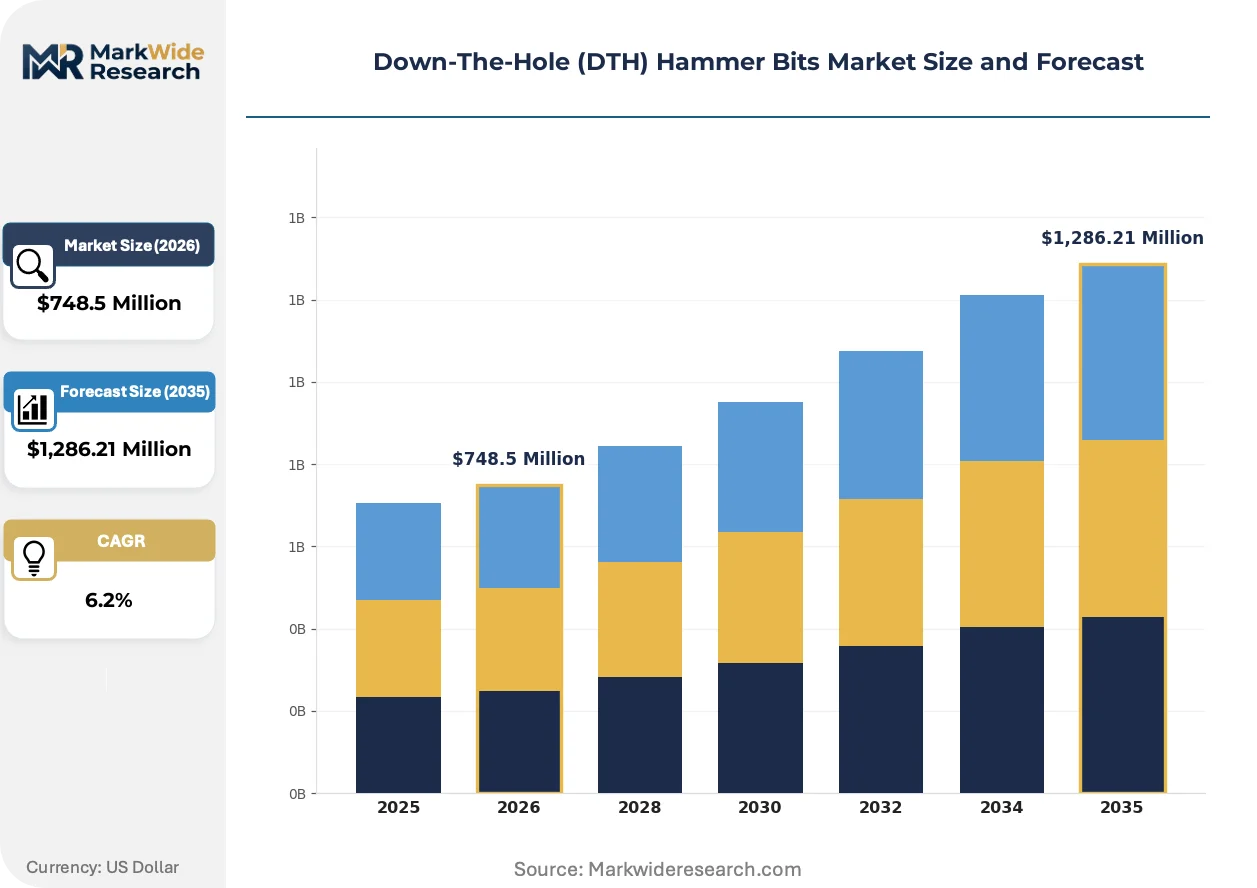
| Market Size in 2026 | $748.5 Million |
| Market Size in 2035 | $1,286.21 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conic Bits, Integral Bits, Retractable Bits, Hammer Bits Material: Carbide, Steel, Alloy, Composite Application: Mining, Water Well Drilling, Oil & Gas, Construction End User: Contractors, Mining Companies, Oil Producers, Water Utilities |
| Companies Covered | Sandvik AB, Epiroc, Mincon Group PLC, Drill King International, Numa Tool Company, Halco Rock Tools, Rockmore International, Boart Longyear, Center Rock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Down-The-Hole (DTH) Hammer Bits Market Shifts & Advancements
Material science advances and compressed-air system integration are redefining performance thresholds across surface and deep-hole drilling segments.
Coarse-grain tungsten carbide substrates with enhanced cobalt binder distribution are absorbing impact stress in abrasive quartzite formations more efficiently than conventional fine-grain alternatives. Australian iron ore contractors are specifying these grades for pit-to-pit transfer rigs where bit replacement intervals directly determine fleet utilization rates. The technology is absorbing maintenance labor costs into capital equipment decisions.
EPA particulate emission standards for drilling operations are constraining compressed-air exhaust systems at US surface mines. Contractors in Arizona and Nevada are retrofitting dust-suppression shrouds and closed-loop air filtration to maintain operating permits. Bit manufacturers are responding with optimized flushing geometries that reduce fugitive dust generation without compromising cuttings evacuation velocity.
After-sales service unbundling is fragmenting traditional bundled supply contracts. Mining contractors in Chile's copper belt are separating bit procurement from technical field support, awarding service contracts to regional drilling specialists independent of original equipment suppliers. This pattern is most visible in Antofagasta Region where contractor consolidation has concentrated buying power among three major fleet operators.
Down-The-Hole (DTH) Hammer Bits Market Segmentation
DTH hammer bit procurement decisions pivot on rock hardness, hole depth requirements, and fleet standardization protocols. Contractors segment their tool inventories across product geometries, substrate materials, and end-use applications to optimize penetration rates and replacement economics.
Product Type:
Buyers prioritize bit geometry based on hole deviation tolerance and trip-time sensitivity in their drilling programs.
- Conic Bits:Aggressive cutting structures with tapered profiles maximize penetration in surface mining and water well installations where deviation limits remain loose. Australian iron ore contractors specify conic geometries for pit-to-pit transfer rigs demanding high meterage per shift.
- Retractable Bits:Collapsible cutting structures enable retrieval through drill rods without full string withdrawal, delivering measurable rig-day savings in deep-hole oil and gas exploration. Premium positioning reflects trip-time reduction value in extended-reach geothermal and hydrocarbon targets.
- Integral Bits:One-piece forged construction eliminates joint failure points in shallow blasthole applications with moderate abrasive wear.
- Hammer Bits:Standard percussive configurations serve general-purpose drilling across variable ground conditions without specialized geometry requirements.
Conic bits lead on scale; retractable bits lead on momentum.
Material:
Substrate selection tracks carbide grain structure against formation abrasiveness and thermal loading profiles.
- Carbide:Cemented tungsten carbide inserts with cobalt binder matrices dominate hard-rock fragmentation. Coarse-grain variants absorb impact stress in abrasive quartzite formations across Western Australian iron ore districts, while fine-grain substrates resist thermal fatigue in Iceland's basalt geothermal drilling.
- Steel:Forged alloy steel bodies provide structural integrity for bit shanks and retrieval mechanisms in standard-duty applications.
- Alloy:Nickel-chromium-molybdenum formulations enhance fatigue resistance in high-cycle percussive loading environments.
- Composite:Hybrid metal-matrix constructions reduce weight in specialized retrieval systems without sacrificing impact transmission efficiency.
Carbide commands the value pool; composite formulations are gaining share fastest.
Application:
End-use drilling environments dictate flushing geometry, insert arrangement, and expected bit life.
- Mining:Large-diameter blasthole drilling in copper, platinum, and iron ore extraction drives bulk procurement with aggressive wear-rate specifications. Peru's copper belt and South Africa's platinum districts concentrate demand for premium carbide grades in 200+ meter production holes.
- Oil & Gas:Deep exploration targets in sedimentary basins require deviation-resistant geometries and thermal-stable substrates for extended downhole residence.
- Water Well Drilling:Medium-depth potable water extraction in sedimentary formations permits standard conic configurations with cost-optimized insert densities.
- Construction:Foundation piling and geotechnical investigation employ shorter-life bits with rapid replacement protocols.
Mining anchors procurement volume; oil and gas commands the steepest expansion trajectory.
End User:
Procurement authority concentrates with fleet operators holding consolidated drilling contracts across multiple mine sites.
- Mining Companies:Captive drilling divisions at major copper and platinum producers standardize bit specifications across integrated operations. Direct procurement from carbide-integrated manufacturers secures volume pricing and technical support alignment.
- Contractors:Independent drilling service providers in Chile's Antofagasta Region and Western Australia negotiate unbundled bit supply separate from field service contracts, concentrating buying power among three major fleet operators.
- Oil Producers:Exploration divisions at integrated majors and independents specify premium retractable bits for deep targets where non-productive time carries severe economic penalties.
- Water Utilities:Municipal and regional water authorities procure standard conic bits through distributor networks with limited technical specification involvement.
Mining companies lead on scale; contractors lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Antofagasta Region concentrates procurement authority for copper blasthole drilling, pulling premium carbide specifications into long-term service contracts.
Chile
Copper extraction in the Antofagasta Region and Atacama Desert extends drill-meterage requirements for 200-meter production holes. Mining contractors negotiate unbundled bit procurement separate from technical field support. ISO 18758 certification shapes tender specifications across state-owned and private fleet operators.
Australia
Western Australian iron ore districts specify coarse-grain carbide grades for pit-to-pit transfer rigs where replacement intervals determine fleet utilization. EPA particulate standards constrain compressed-air exhaust systems at surface mines in the Pilbara. Dust-suppression retrofits and optimized flushing geometries are penetrating contractor specifications in Queensland coal basins.
Peru
The copper belt spanning Arequipa, Cusco, and Apurímac drives demand for premium bit specifications in high-altitude hard-rock formations. Ministry of Energy and Mines permitting timelines accelerate exploration drilling programs. Local procurement regulations are steering service contracts toward regional drilling specialists in the southern mining corridor.
South Africa
Platinum operations in the Bushveld Igneous Complex anchor procurement volume for large-diameter blasthole bits. The Department of Mineral Resources and Energy enforces supply chain traceability requirements for strategic metal inputs. Rustenburg and Limpopo mining clusters are extending requalification timelines for secondary carbide insert suppliers.
United States
Southwestern copper districts and western Canadian oil sands drive retractable bit demand for deep-hole applications where trip-time reduction delivers rig-day savings. EPA particulate emission standards are forcing dust-suppression shrouds and closed-loop air filtration retrofits. Arizona and Nevada surface mines are optimizing flushing geometries to maintain operating permits.
Down-The-Hole (DTH) Hammer Bits Market Competitive Landscape
Global majors compete with regional champions across carbide supply integration and field service proximity. The vendor base stratifies into three tiers: integrated carbide-to-bit producers, specialized hard-rock geometry designers, and regional service hub operators. Consolidation pressure concentrates among mid-scale fabricators facing raw material cost volatility. Dominant competitive moves include captive tungsten carbide production and dedicated service hub placement near active mining districts.
Within the integrated production tier, Sandvik AB anchors Scandinavian supply chain control through captive carbide manufacturing. Mincon Group PLC exemplifies specialized hard-rock geometry optimization for variable ground conditions. Drill King International occupies a position among North American service hub operators with regional proximity to southwestern US and western Canadian mining clusters.
| Leading Market Players |
|---|
| Sandvik AB |
| Epiroc |
| Mincon Group PLC |
| Drill King International |
| Numa Tool Company |
| Halco Rock Tools |
| Rockmore International |
| Boart Longyear |
| Center Rock |
| Others |
Supply & Pricing Matrix
Carbide metallurgist scarcity in Western Europe and North America widens labor-cost differentials between integrated producers and mid-scale fabricators, compressing pricing-tier spreads as captive operations absorb specialist premiums into margin structures rather than passing through to buyers.
Pricing Analysis
Input-cost pass-through from tungsten carbide and cobalt binder volatility stratifies pricing across three performance tiers. Premium-mid-economy pricing differentiation rests on ISO 18758 certification status and captive carbide supply integration, with mining contractors in Chile and Australia least sensitive to unit pricing due to fleet-utilization economics, while water utilities and construction operators exhibit acute price elasticity on standard conic configurations.
Supply Chain Analysis
Workforce-availability constraints in cemented carbide sintering operations concentrate manufacturing gravity in China, Sweden, and the United States, where specialized process engineers command placement premiums. Tungsten concentrate, cobalt binder alloys, and forged alloy steel bodies feed fabrication networks exposed to single-source vulnerability in Chinese tungsten processing. Distribution runs through manufacturer-direct contracts for mining majors and regional distributor networks for fragmented construction and water well segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on cobalt cost stabilization and premium-tier pull from geothermal and deep-hole oil applications, where thermal-fatigue-resistant carbide formulations command service-contract premiums.
For Market Incumbents: Deploy captive tungsten carbide production to defend against raw material cost volatility from Congolese concentrate disruptions. Anchor procurement relationships through 18-24 month field trial commitments that lock out secondary supplier qualification, while expanding technical service headcount in Chile's Antofagasta Region to counter unbundling trends separating bit supply from field support.
For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Europe open a window for integrated carbide-to-bit producers with low-carbon steel body sourcing to capture first-mover advantage under CBAM implementation. Target Argentina's Salta Province lithium brine drilling with salar caprock penetration specialists, entering through dedicated service contracts rather than equipment supply to bypass entrenched manufacturer relationships.
For Investors and Strategic Acquirers: Mining contractors with captive drilling divisions are the most active acquirer in this space, seeking carbide-integrated targets to secure supply chain control. Five-to-ten year viability favors producers with backward integration into tungsten processing and ISO 18758 certification infrastructure. Watch cobalt price volatility as the inflection indicator for margin compression versus expansion cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide | Captive sintering operations in Sweden and China insulate Sandvik from cobalt price swings. |
| Geographic Service Hub Expansion | Dedicated facilities in Arizona and Nevada position Drill King International for EPA compliance retrofit demand. |
| ISO 18758 Certification Investment | Performance benchmarking alignment unlocks Australian and Chilean contractor fleet standardization contracts. |
| Thermal-Fatigue-Resistant Formulation R&D | Fine-grain substrate development captures Iceland and Kenya geothermal drilling premiums. |
| Long-Term Supply Agreement Structuring | Fixed-price cobalt binder contracts with Congolese concentrate traders stabilize margin predictability. |
Research Methodology
Direct dialogue with carbide metallurgists, mining contractor procurement directors, drilling fleet maintenance heads, and aftermarket service managers grounded qualitative insights, cross-referenced against SEC filings from integrated tool manufacturers, OECD tungsten supply chain traceability reports, EPA particulate emission enforcement records, and Chilean Ministry of Energy permitting databases. Bottom-up rig-count modeling and top-down carbide consumption estimates were triangulated against trade flow data.
Bottom-up penetration rate modeling across conic, retractable, integral, and hammer bit geometries was layered against coarse-grain and fine-grain carbide grade demand, mining versus oil and gas application splits, and end-user procurement authority concentration. CAGRs were derived from rig-day cost economics and replacement interval elasticity. Forecast inputs incorporated geothermal drilling acceleration curves and lithium brine exploration permit timelines.
Revisions become necessary when cobalt concentrate supply disruptions, REACH coating restriction expansions, or ISO standard updates materialize beyond baseline assumptions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Extrusion Machinery Market
Construction Equipment
Global Cut and Bend Equipment Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
Fogging Machine Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Road Roller Market
Construction Equipment
Piles Turner Market
Construction Equipment
BRICS Aerial Work Platforms Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Radial Drilling Machine Market