
 Truck Mounted Cranes Market | 2026-2036
Truck Mounted Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Mounted Cranes Market Analytics
The capital-intensity divergence between hydraulic system in-house producers and outsourced assemblers is reorganizing competitive tiers in truck mounted cranes. Liebherr Group leverages captive manufacturing of telescopic booms to sustain margin control across European utility fleets. SANY Group anchors its position through integrated chassis-crane production lines serving domestic infrastructure programs. Palfinger AG competes via modular knuckle-boom architectures that navigate diverse municipal specification requirements.
Truck mounted cranes integrate a rotating superstructure with telescopic or articulating boom assemblies onto commercial vehicle chassis, typically achieving lifting capacities from five to twenty tons through hydraulic cylinder extension and winch mechanisms. Their primary purpose centers on mobile material handling where site-fixed equipment proves impractical, spanning utility repair, construction erection, and emergency recovery operations. All-wheel drive deployment types command premium positioning in off-road oilfield and mining support roles across Siberian and Middle Eastern terrains. Construction application segments concentrate volume demand in residential high-rise markets across Southeast Asian metropolitan zones. Emergency services configurations represent a developing margin pool as municipalities standardize unified disaster response fleets.
FAA crane operation proximity rules near airports constrain boom height specifications in US urban corridors, while EU F-Gas Regulation phases hydraulic fluid formulations toward lower global warming potential alternatives. China's MEE enforces GB standards on noise emissions and structural fatigue testing for domestic chassis integrations. Brazil's ANVISA-aligned municipal safety codes govern operator certification and load moment limiter calibration in urban deployment zones. Stakeholders must monitor evolving carbon border adjustment mechanisms that threaten to reclassify imported steel-intensive crane structures across Atlantic trade routes.
Market Dynamics
Utility infrastructure maintenance fleets across North America are accelerating crane procurement as aging grid assets drive emergency repair frequency, while China's MEE tightens GB certification standards that filter lower-tier domestic producers from municipal bidding pools.
Growth Catalysts
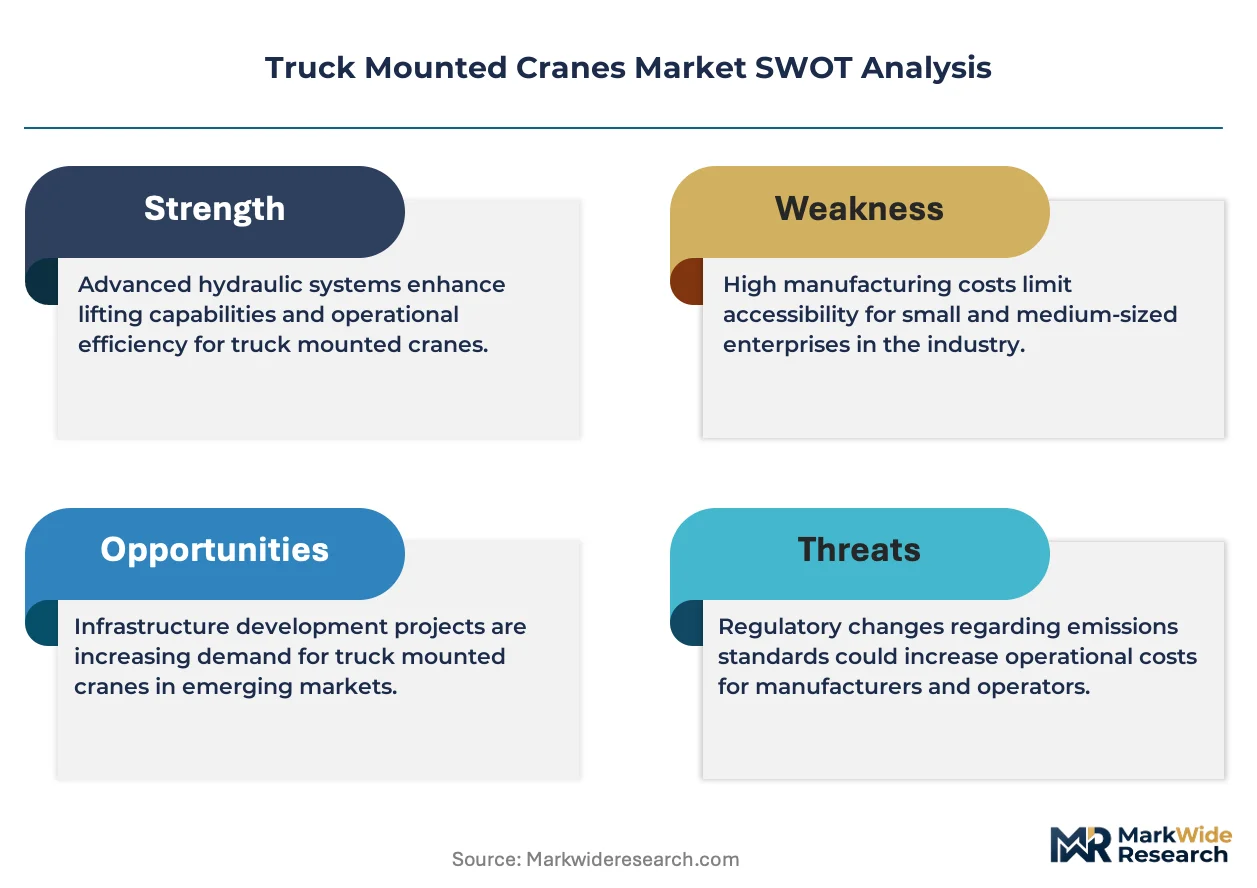
- Utility grid modernization mandates:US IRA-funded transmission upgrades expand crane deployment for transformer replacement and storm recovery operations.
- Urban freight corridor densification:Brazil's knuckle-boom configurations dominate last-mile heavy lifting in São Paulo and Rio de Janeiro logistics zones.
- All-wheel drive premium positioning:Off-road oilfield support roles across Siberian terrains command specialized chassis integrations with enhanced ground clearance.
Market Restraints
- Steel input cost volatility:Carbon border adjustment mechanisms threaten to reclassify imported steel-intensive crane structures across Atlantic trade routes.
- Hydraulic fluid formulation shifts:EU F-Gas Regulation phases legacy formulations toward lower global warming potential alternatives, compressing supplier margins.
- Chassis integration complexity:Domestic certification requirements in China force foreign producers into joint venture structures with local chassis manufacturers.
Strategic Opportunities
- Unified disaster response fleet standardization:Emergency services configurations represent a developing margin pool as municipalities consolidate procurement specifications.
- Modular knuckle-boom architectures:Municipal specification diversity creates openings for adaptable superstructure designs serving fragmented urban requirements.
- Telescopic boom captive manufacturing:In-house production of boom assemblies enables margin control independent of hydraulic system supplier pricing.
Industry Challenges
- Operator certification calibration:Brazil's ANVISA-aligned municipal safety codes govern load moment limiter calibration protocols, extending deployment timelines.
- FAA proximity compliance:US urban corridor crane operation near airports constrains boom height specifications, limiting equipment applicability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Mounted Cranes Market |
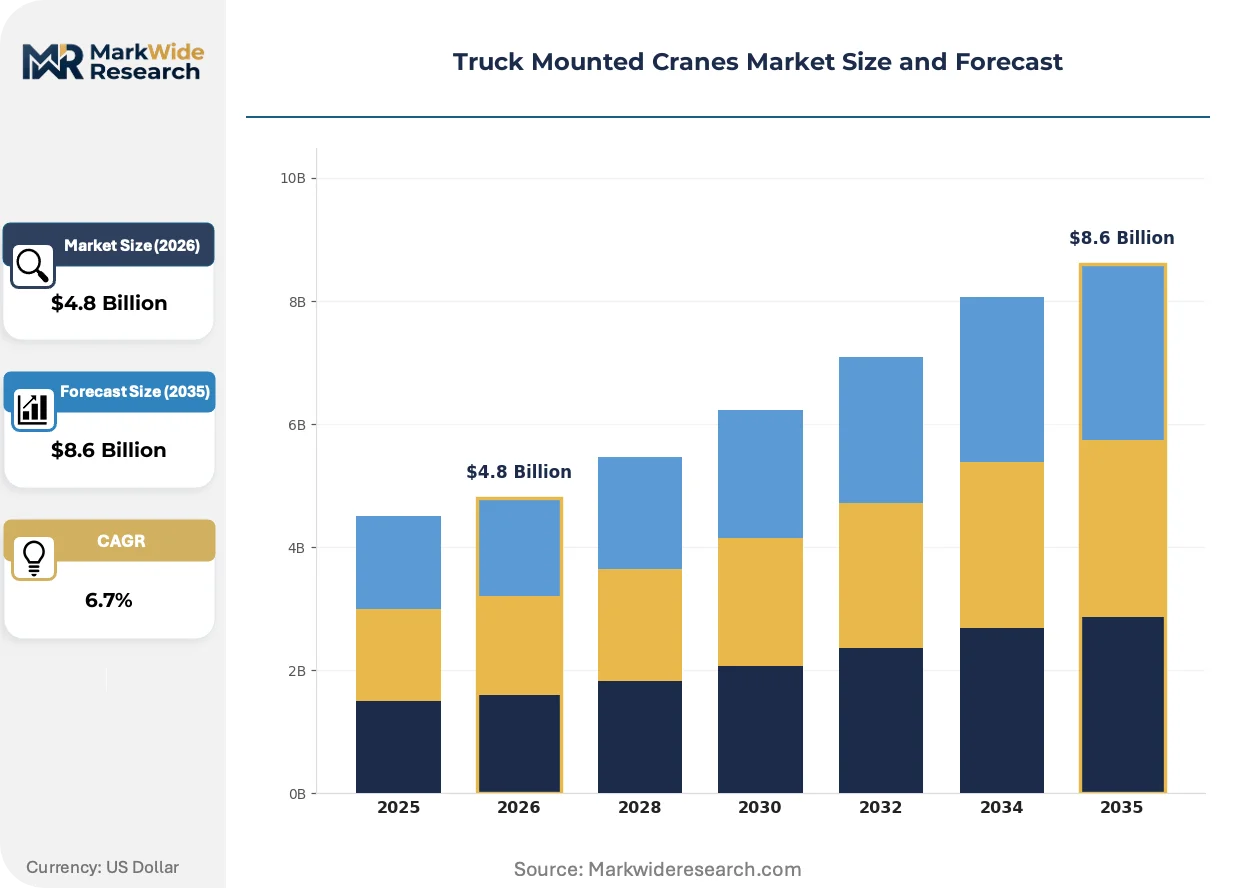
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weight Capacity: 5 Tons, 10 Tons, 15 Tons, 20 Tons Deployment Type: Urban, Construction Sites, Industrial, Off-Road Drive Type: Four-Wheel Drive, All-Wheel Drive, Rear-Wheel Drive, Front-Wheel Drive Application: Construction, Maintenance, Emergency Services, Transportation |
| Companies Covered | Tadano Ltd., Liebherr Group, Terex Corporation, SANY Group, Palfinger AG, XCMG Group, Zoomlion Heavy Industry, Manitex International, Link-Belt Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Mounted Cranes Market Evolving Landscape
Electrification pressures and regulatory fluid mandates are actively restructuring hydraulic system architectures, while demand-side procurement consolidation reshapes aftermarket service expectations across utility and construction verticals.
Electro-hydraulic hybrid drive systems are bifurcating the power transmission landscape in truck mounted cranes. European utility fleets are adopting these configurations for urban noise-restricted zones. The technology is bifurcating competitive tiers between integrated producers with in-house motor-controller capabilities and outsourced assemblers dependent on tiered supplier pricing.
EU F-Gas Regulation mandates lower global warming potential hydraulic fluid formulations by specified phase-out deadlines. Crane manufacturers face reformulation costs and compatibility testing with existing seal materials. Telescopic boom producers serving North Sea offshore logistics are accelerating fluid transition timelines to maintain charter fleet eligibility.
Rental fleet operators are consolidating maintenance contracts into multi-year service agreements bundling inspection, fluid replacement, and structural fatigue monitoring. Equipment lessors are displacing transactional parts sales with subscription-based uptime guarantees. This consolidation is most visible in German municipal utility fleets standardizing on single-source crane service providers.
Truck Mounted Cranes Market Segmentation
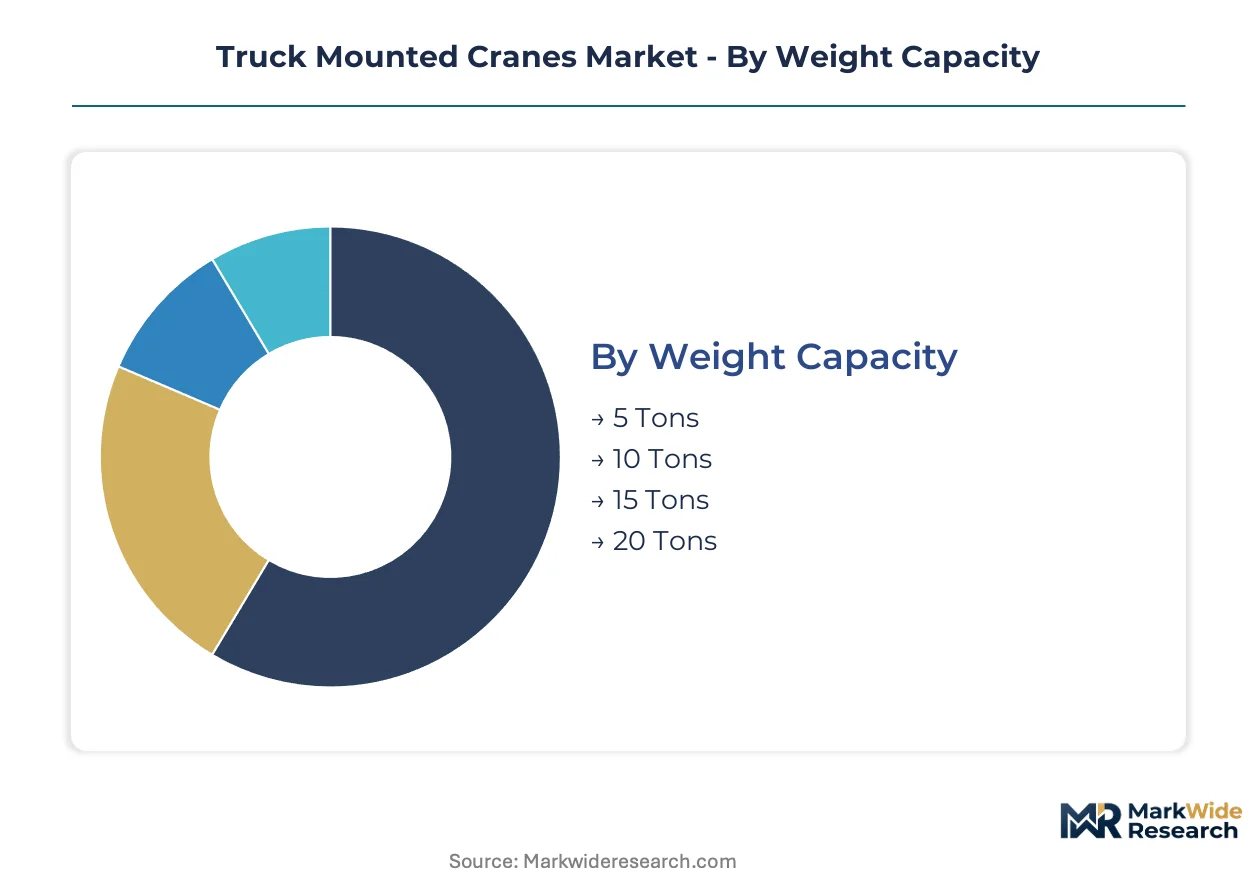
Truck mounted crane procurement patterns diverge sharply across weight classes and terrain specifications, with chassis integration requirements and operator certification protocols creating distinct competitive arenas. Segmentation clarity enables suppliers to align hydraulic system architectures with specific duty cycles and regulatory environments.
Weight Capacity:
Domestic infrastructure programs in China and Brazil favor mid-range capacities for municipal fleets, while export markets in the Middle East and Africa concentrate procurement at the upper tonnage bands for oilfield logistics.
- 5 Tons:Compact knuckle-boom configurations dominate last-mile urban freight corridors in São Paulo and Rio de Janeiro, where ANVISA-aligned safety codes govern load moment limiter calibration. Brazilian logistics operators specify these units for dense commercial districts with restricted boom height clearance.
- 10 Tons:Telescopic boom assemblies serve North American utility maintenance fleets replacing aging transformers under IRA-funded grid modernization. US procurement concentrates in storm-prone southeastern states where emergency repair frequency drives fleet expansion.
- 15 Tons:Mid-range capacity bridges construction and industrial applications across German municipal fleets standardizing on unified service contracts.
- 20 Tons:Maximum capacity units command premium positioning in Siberian oilfield support roles requiring enhanced ground clearance and all-wheel drive chassis integration.
10 Tons holds the largest share; momentum sits with 5 Tons as urban freight densification accelerates.
Deployment Type:
Cost tier differentiation separates premium off-road specifications from standardized urban configurations, with chassis modifications and hydraulic system complexity driving margin stratification.
- Urban:Noise-restricted zones in European metropolitan areas specify electro-hydraulic hybrid drive systems. EU F-Gas Regulation compliance adds fluid reformulation costs that compress supplier margins on legacy equipment retrofits.
- Construction Sites:Southeast Asian high-rise residential markets concentrate volume demand for telescopic boom cranes with rapid setup cycles. Chinese GB certification standards filter lower-tier domestic producers from municipal bidding pools.
- Industrial:Factory maintenance and heavy manufacturing logistics favor rear-wheel drive configurations with precise load positioning.
- Off-Road:All-wheel drive premium positioning commands specialized chassis integrations across Middle Eastern desert terrain and Russian extraction zones.
Construction Sites holds the largest share; Off-Road configurations are climbing the fastest on oilfield logistics demand.
Drive Type:
Customer type segmentation separates fleet operators seeking total cost optimization from specialized contractors prioritizing terrain capability over acquisition price.
- Four-Wheel Drive:Balanced traction specifications serve North American utility fleets operating across mixed paved and unpaved access roads during storm recovery operations.
- All-Wheel Drive:Enhanced ground clearance and torque distribution dominate Siberian and Middle Eastern extraction support roles where terrain variability demands maximum mobility.
- Rear-Wheel Drive:Standard configuration for urban freight logistics in Brazilian corridors where paved surface density reduces traction requirements.
- Front-Wheel Drive:Compact chassis integrations suit narrow European municipal streets with weight-restricted bridge crossings.
Rear-Wheel Drive holds the largest share; All-Wheel Drive is gaining share fastest on energy sector fleet renewal.
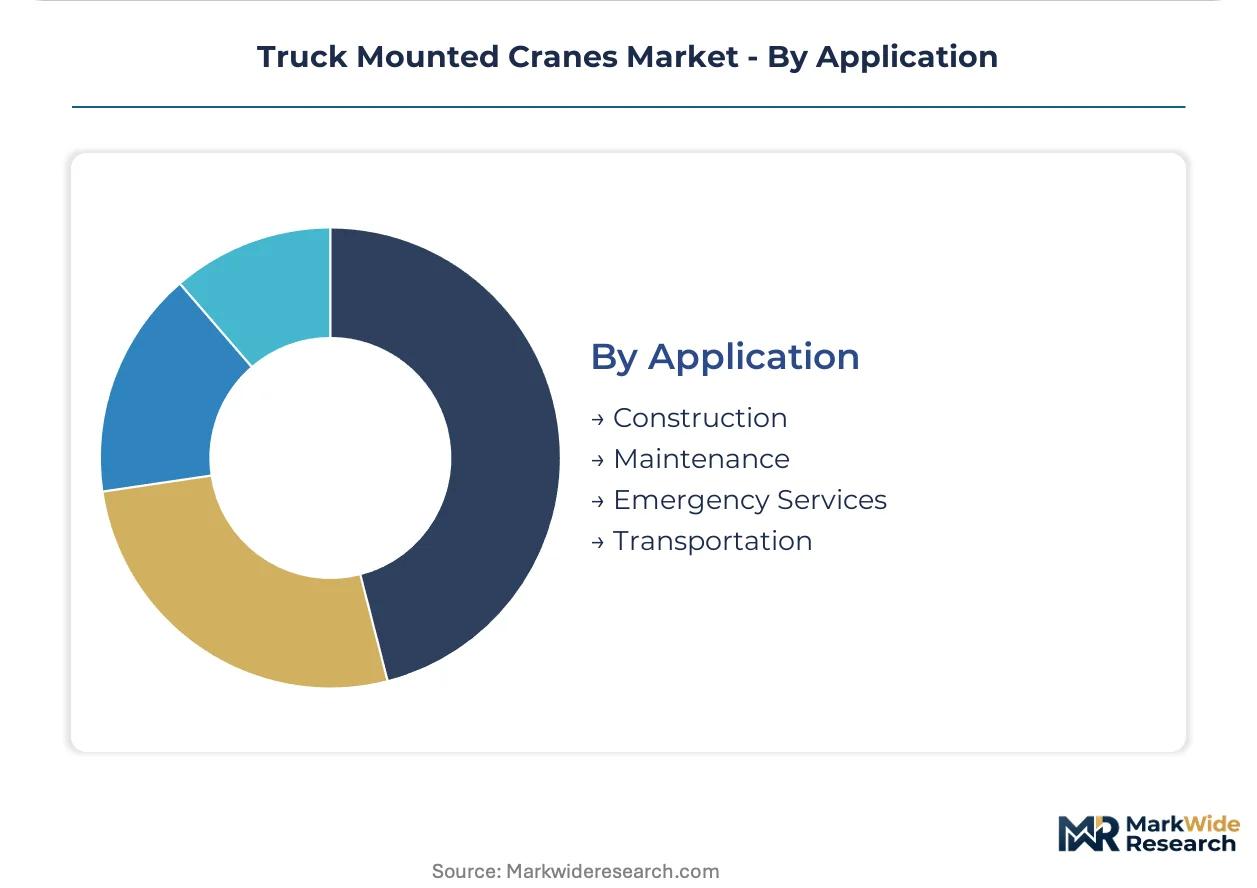
Application:
Supply concentration in hydraulic system architectures creates divergent margin profiles across end-use verticals with distinct certification and service contract structures.
- Construction:Residential high-rise erection in Southeast Asian metropolitan zones drives volume procurement of telescopic boom configurations. Chinese MEE enforcement of GB standards on structural fatigue testing shapes domestic chassis integration requirements.
- Maintenance:North American utility infrastructure fleets are consolidating procurement into multi-year service agreements bundling inspection and structural fatigue monitoring. German municipal operators displace transactional parts sales with subscription-based uptime guarantees.
- Emergency Services:Unified disaster response fleet standardization creates developing margin pools as municipalities consolidate specifications across police, fire, and medical rescue functions.
- Transportation:Freight logistics corridors in Brazil and India specify knuckle-boom architectures for cargo handling efficiency at distribution hubs.
Construction holds the largest share; Emergency Services shows the steepest expansion trajectory on municipal fleet consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German utility fleet contracts while Brazilian municipal procurement operates on compressed margins driven by knuckle-boom specification density. This asymmetry shapes regional investment priorities across the forecast window.
United States
IRA-funded transmission upgrades accelerate crane deployment for transformer replacement and storm recovery operations across southeastern states. FAA proximity rules near airports constrain boom height specifications in urban corridors, limiting equipment applicability. Houston and Dallas utility clusters drive fleet standardization toward multi-year service agreements bundling inspection and structural fatigue monitoring.
China
Domestic infrastructure programs favor mid-range capacity procurement for municipal fleets under integrated chassis-crane production lines. MEE enforcement of GB standards on mobile crane emissions and noise tightens product certification requirements, filtering lower-tier producers from bidding pools. Yangtze River Delta manufacturing clusters concentrate hydraulic system integration for export-oriented telescopic boom assemblies.
Germany
Municipal utility fleets standardize on unified disaster response specifications, consolidating procurement across police, fire, and medical rescue functions. EU F-Gas Regulation mandates lower global warming potential hydraulic fluid formulations, adding reformulation costs and compatibility testing burdens. North Rhine-Westphalia industrial zones anchor rental fleet operator consolidation into subscription-based uptime guarantees displacing transactional parts sales.
Brazil
Urban freight corridor densification drives knuckle-boom configuration dominance for last-mile heavy lifting in São Paulo and Rio de Janeiro logistics zones. ANVISA-aligned municipal safety codes govern operator certification and load moment limiter calibration, extending deployment timelines. São Paulo state procurement concentrates volume demand for compact units navigating dense commercial districts with restricted boom height clearance.
Saudi Arabia
Energy sector fleet renewal commands premium all-wheel drive configurations for desert terrain oilfield support roles requiring enhanced ground clearance. National infrastructure programs under Vision 2030 expand crane procurement for industrial city construction and logistics hub development. Eastern Province extraction zones anchor specialized chassis integration demand across Aramco contractor supply chains.
Truck Mounted Cranes Market Competitive Landscape
Concentration sits with integrated hydraulic system producers possessing captive boom manufacturing capabilities, while outsourced assemblers compete on specification flexibility for fragmented municipal requirements. Three archetypes dominate: European utility-focused telescopic boom specialists, Chinese domestic infrastructure-anchored integrated producers, and Austrian-German modular knuckle-boom architects. Competitive moves center on backward integration into hydraulic cylinder production and geographic expansion through joint venture structures to satisfy chassis integration mandates.
Among Japanese-German-Swiss heavy machinery fabricators, Tadano Ltd., Liebherr Group, and SANY Group occupy distinct positioning vectors. Tadano exemplifies the premium-tier telescopic boom archetype serving offshore logistics and utility maintenance verticals. Liebherr represents European captive manufacturing concentration with in-house boom assembly production sustaining margin control. SANY anchors the integrated chassis-crane production model serving domestic Chinese infrastructure programs and select export markets. These three entities illustrate the strategic divergence between hydraulic system in-house control and outsourced modular assembly approaches reshaping competitive tiers.
| Leading Market Players |
|---|
| Tadano Ltd. |
| Liebherr Group |
| Terex Corporation |
| SANY Group |
| Palfinger AG |
| XCMG Group |
| Zoomlion Heavy Industry |
| Manitex International |
| Link-Belt Construction Equipment |
| Others |
Value Network & Pricing Analysis
Ninety-day hydraulic cylinder lead times from European suppliers anchor pricing power for integrated boom manufacturers while compressing margins at outsourced assemblers dependent on spot-market chassis procurement. This inventory-to-delivery gap separates captive producers from price-takers across the truck mounted cranes landscape.
Pricing Analysis
Configured-to-order pricing commands a 25-40% premium over standard catalog configurations in the truck mounted cranes market. Three-tier pricing structure across premium, standard, and economy levels stratifies by hydraulic system integration depth and chassis certification grade. Price differentiation stems from after-sales service bundling and MEE GB compliance tier. Pricing pressure intensifies in Brazilian municipal procurement where knuckle-boom specification density compresses supplier margins. Fleet operators in North American utility verticals show lowest price sensitivity due to IRA-funded procurement timelines.
Supply Chain Analysis
Baltic Sea port congestion for specialty steel plate shipments creates chokepoint vulnerability for telescopic boom producers serving North Sea offshore logistics. Manufacturing concentrates in China, Germany, and Austria for hydraulic system integration and boom fabrication. Supply chains draw from Swedish specialty steel, German high-pressure hydraulics, and Chinese chassis platforms. Single-source vulnerability sits with European electro-hydraulic motor-controller suppliers. Distribution runs through OEM-direct sales for utility fleets and rental operator networks for construction verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated rental fleet operators and unified municipal procurement bodies, fragmenting the vendor base into specification-responsive assemblers versus integrated margin defenders.
For Market Incumbents: Secure captive hydraulic cylinder production to insulate margin control from European supplier pricing volatility. Anchor chassis integration joint ventures in China to satisfy MEE GB certification mandates filtering foreign competitors. Defend position against modular knuckle-boom entrants by deepening aftermarket service contract penetration in German utility fleets. For New Entrants and Emerging Players: Aftermarket fluid replacement and structural fatigue monitoring services represent under-served white space where incumbents rely on transactional parts sales. Target Brazilian urban freight corridors with compact 5-ton configurations calibrated to ANVISA load moment limiter protocols. Pursue subscription-based uptime guarantee positioning to displace legacy equipment lessors in Southeast Asian construction markets. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because municipal procurement standardization and rental fleet operator aggregation favor scaled service providers over fragmented assemblers. Acquisition archetypes include hydraulic system-integrated mid-caps with captive boom manufacturing and established certification pathways. Watch for carbon border adjustment mechanism implementation across Atlantic trade routes as margin compression inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Cylinders | Captive production insulates margin control from European supplier pricing volatility. |
| Joint Venture Chassis Integration | Local manufacturing partnerships satisfy MEE GB certification requirements in China. |
| Electro-Hydraulic Hybrid System Launch | EU F-Gas Regulation compliance opens urban noise-restricted zone access. |
| Multi-Year Service Contract Consolidation | German municipal fleet standardization favors single-source crane service providers. |
| Modular Knuckle-Boom Platform Expansion | Specification flexibility captures fragmented Brazilian municipal procurement demand. |
Research Methodology
A spread of perspectives from fleet maintenance directors, OEM procurement managers, hydraulic system engineers, and rental operator executives converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade databases, SEC equipment manufacturer filings, and EU F-Gas Regulation implementation tracking. Bottom-up unit economics triangulated against top-down infrastructure spending forecasts across utility and construction verticals.
Segmentation dimensions modeled include weight capacity tiers, deployment type specifications, drive type configurations, and application verticals across the projection horizon. CAGRs derived from historical procurement patterns, fleet replacement cycles, and regulatory compliance timelines. Industry-specific forecast inputs incorporate IRA transmission upgrade appropriations, MEE GB standard enforcement schedules, and ANVISA operator certification rollout velocity.
Underlying assumptions cover sustained infrastructure spending commitments and stable steel input cost baselines, with deviation risk concentrated in carbon border adjustment mechanism implementation and hydraulic fluid formulation transition costs. Practitioners should keep alternative scenarios live as EU F-Gas phase-out deadlines and Chinese chassis integration mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Compactor Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Modular Conveyor System Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Global Industrial Weighing Equipment Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Global Forklift Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Industrial Racking Systems Market