
 Pneumatic Equipment Market | 2026-2036
Pneumatic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumatic Equipment Market Outlook
The EU F-Gas Regulation is shifting demand toward energy-efficient pneumatic systems across European manufacturing bases. SMC Corporation leverages its integrated valve and actuator portfolio to sustain leadership in compact automation solutions. Festo SE & Co. KG anchors its competitive position through extensive vocational training networks and modular system architectures. Parker Hannifin Corporation dominates aftermarket service channels for industrial pneumatic maintenance across North American energy and rail sectors.
Pneumatic equipment comprises compressed-air-driven machinery—including compressors generating pressures typically from 0.5 to 1.0 MPa, directional control valves, linear and rotary actuators, and pressure or flow sensors—engineered to convert pneumatic energy into mechanical motion for industrial tasks. Actuators command the largest product category due to their ubiquity in factory automation lines, while vacuum technology applications are expanding fastest in electronics handling and cleanroom logistics where contactless gripping prevents contamination. Sensors represent a concentrated margin pool as Industry 4.0 architectures demand real-time pressure and position feedback integrated into predictive maintenance systems.
The US Department of Labor's OSHA standards govern workplace compressed air safety thresholds, while the EU Machinery Directive enforces CE marking conformity for pneumatic system integration. Japan's METI promotes energy efficiency benchmarks that directly influence compressor design specifications for export markets. Stakeholders must weigh regional certification burdens against the cost of modular platform standardization when scaling across multiple jurisdictions.
Market Dynamics
The EU F-Gas Regulation is compressing compressor design cycles while China's eastern manufacturing corridor concentrates demand for high-speed pneumatic automation lines. Factory upgrade cycles in Germany and Japan are synchronizing with energy-efficiency mandates, creating procurement timing clusters that reshape quarterly equipment flows.
Growth Catalysts
- Automotive Assembly Automation:German and Japanese vehicle plants are expanding pneumatic lines for lightweight body-in-white handling. Multi-axis actuator arrays reduce cycle times in welding and sealing stations.
- EU F-Gas Regulation:The regulation mandates lower-emission compressor designs, forcing equipment replacement across European manufacturing bases. CE marking conformity requirements accelerate upgrade decisions.
- Electronics Cleanroom Handling:Vacuum gripper systems enable contactless wafer and PCB transport in semiconductor fabs. Contamination prevention protocols drive specification premiums.
Market Restraints
- Aluminum and Steel Input Volatility:Cylinder and valve casting costs fluctuate with commodity metal markets. Foundry capacity constraints in select regions amplify price transmission.
- Supply Concentration in East Asian Valve Components:Precision solenoid manufacturing clusters in specific coastal zones create single-source exposure. Geopolitical friction risks component availability.
- Electromechanical Actuator Substitution:Servo-electric systems encroach on precision positioning applications. Energy efficiency comparisons favor electric alternatives in low-force, high-accuracy tasks.
Strategic Opportunities
- India Manufacturing Corridor Expansion:PLI scheme incentives attract electronics and automotive component assembly. Greenfield plant construction creates first-mover equipment specification windows.
- Predictive Maintenance Sensor Integration:Pressure and position feedback modules embed into Industry 4.0 architectures. Real-time data streams enable outcome-based service contracting.
- Modular System Architecture:Standardized valve-terminal and actuator interfaces reduce engineering-to-order lead times. System integrators compress project commissioning durations.
Industry Challenges
- Pneumatic Systems Integration Expertise:Compressed air circuit design and troubleshooting skills lag automation demand. Vocational training pipelines require multi-year expansion.
- Multi-Jurisdiction Certification Burden:OSHA, CE marking, and METI efficiency benchmarks impose parallel compliance costs. Modular platform standardization across regions strains R&D allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumatic Equipment Market |
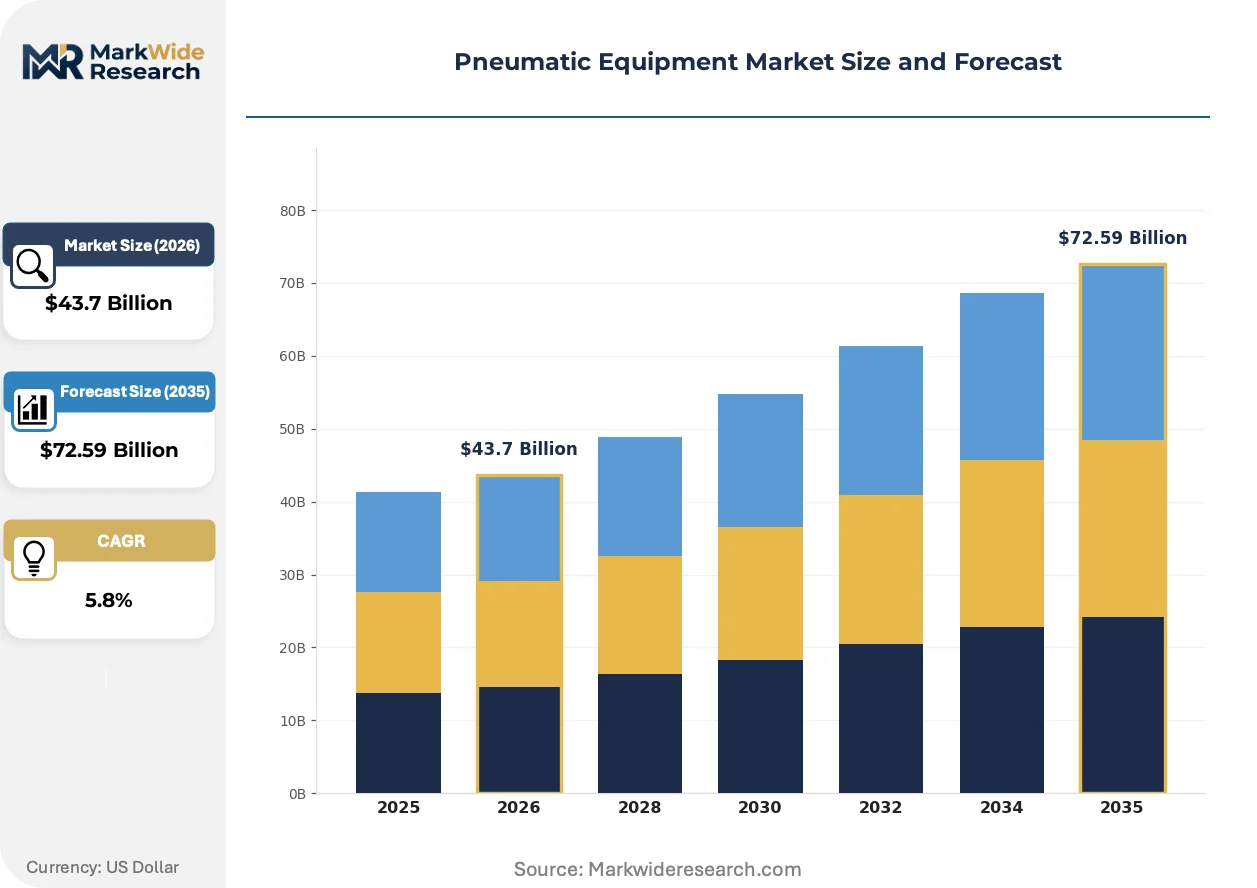
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $72.59 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressors, Valves, Actuators, Sensors End User: Aerospace, Manufacturing, Construction, Healthcare Application: Transportation, Automation, Material Handling, Industrial Processing Technology: Pneumatic Control, Vacuum Technology, Servo Technology, Lubrication Systems |
| Companies Covered | SMC Corporation, Festo SE & Co. KG, Parker Hannifin Corporation, Emerson Electric Co., Bosch Rexroth AG, Atlas Copco, Ingersoll Rand, Camozzi Automation, Norgren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumatic Equipment Market Strategic Shifts
Compressed air system architecture is fragmenting into configurable sub-assemblies that accelerate deployment and reduce field engineering. Energy efficiency mandates and digital integration requirements are compressing product lifecycles across all equipment categories.
Intelligent valve terminals with integrated IO-Link connectivity are modularizing pneumatic control architectures. Automotive tier-one suppliers adopt these systems to compress commissioning timelines for mixed-model assembly lines. The technology is modularizing how system integrators configure distributed control nodes, reducing cabinet space and wiring labor.
The EU F-Gas Regulation tightens emission thresholds for refrigerants used in compressed air drying systems. Equipment manufacturers redesign desiccant and membrane dryer portfolios to maintain compliance without performance degradation. Food and pharmaceutical packaging lines in Germany and France face the steepest retrofit obligations, driving specification shifts toward heatless regeneration technologies.
Compressed air-as-a-service models are displacing capital purchase in North American food processing and packaging operations. Energy monitoring and guaranteed uptime clauses transfer operational risk from plant engineers to equipment vendors. The shift is most visible in Midwest dairy and meat processing facilities where margin pressure favors opex over capex accounting.
Pneumatic Equipment Market Segmentation
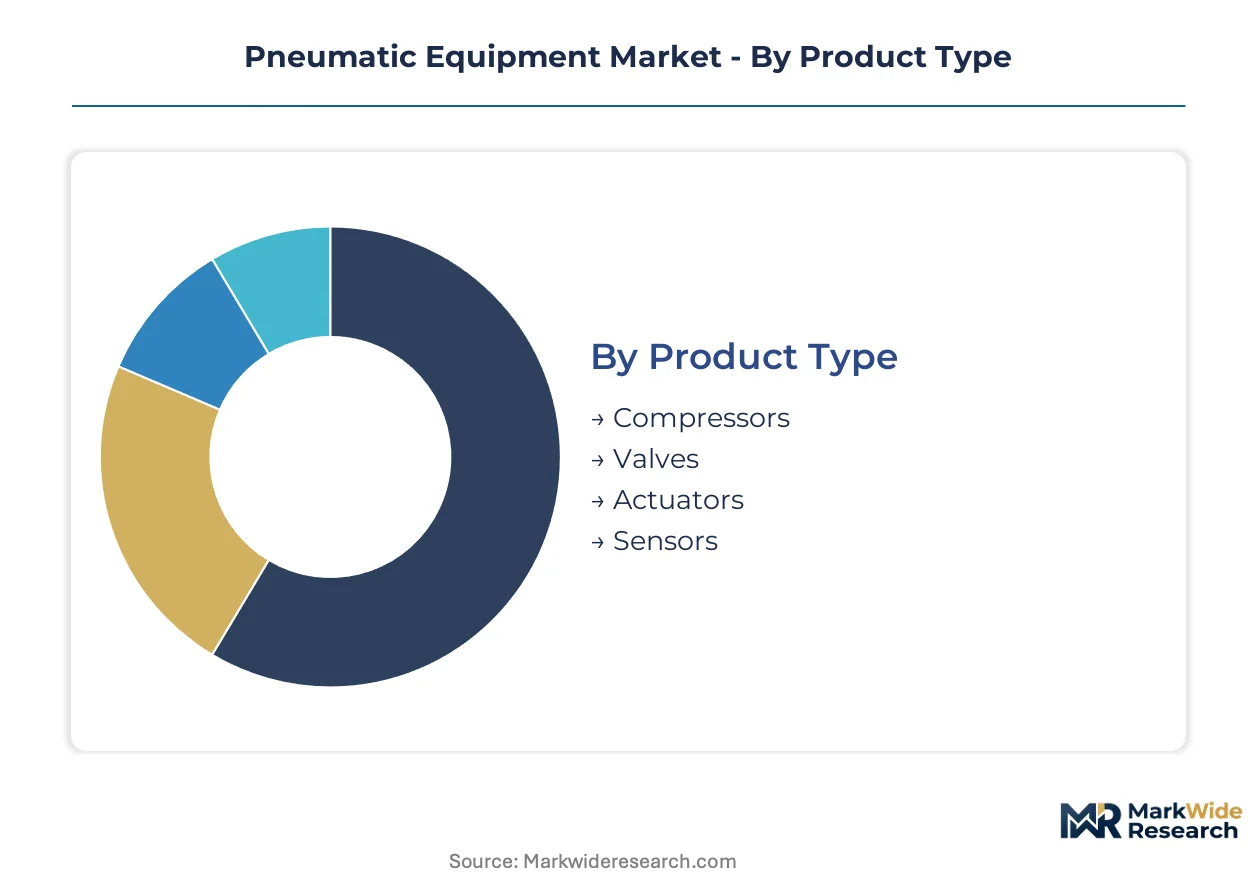
Pneumatic equipment procurement hinges on pressure specifications, cycle speed requirements, and integration complexity with existing factory architectures. Buyers prioritize actuator precision for automation lines, compressor efficiency for energy accounting, and sensor modularity for predictive maintenance retrofitting.
Product Type:
Capital allocation patterns separate high-rotation consumables from long-life infrastructure investments.
- Actuators:Linear and rotary motion devices convert compressed air into mechanical force for positioning tasks. German and Japanese automotive assembly plants specify multi-axis actuator arrays to compress welding and sealing cycle times. Volume sits with actuators; growth tilts toward vacuum-enabled variants for electronics handling.
- Compressors:Pressure generation systems typically operate at 0.5 to 1.0 MPa for industrial distribution networks. EU F-Gas Regulation mandates are forcing redesign cycles for lower-emission compressor architectures across French and German manufacturing bases.
- Valves:Directional control components regulate airflow paths in automated circuits. SMC Corporation and Festo SE compete on valve-terminal modularity to reduce cabinet footprint.
- Sensors:Pressure and position feedback modules enable real-time monitoring in Industry 4.0 architectures. These components command concentrated margins as predictive maintenance systems embed pneumatic diagnostics.
Actuator arrays dominate installed base; sensor attach rates are climbing fastest as digital integration becomes standard.
End User:
Industry-specific contamination protocols and duty cycle requirements reshape specification priorities.
- Manufacturing:Factory automation lines deploy pneumatic systems for repetitive material positioning and assembly operations. China's eastern manufacturing corridor concentrates demand as facility upgrade cycles accelerate.
- Aerospace:Flight-critical actuation and ground support equipment demand certified reliability under extreme temperature and vibration conditions. Boeing and Airbus tier-one suppliers specify MIL-standard pneumatic components for landing gear and flight control testing rigs.
- Healthcare:Medical devices and laboratory automation require oil-free compressed air to prevent contamination. Ventilator and diagnostic equipment manufacturers source specialized miniature pneumatic systems.
- Construction:Portable compressors and pneumatic tools power on-site demolition and fastening operations. Rental fleet operators prioritize durability and field serviceability over energy efficiency metrics.
Manufacturing commands current volume; healthcare applications are expanding most quickly as laboratory automation proliferates.
Application:
Motion complexity and precision tolerances determine system architecture choices.
- Automation:Robotic workcells and fixed automation stations deploy pneumatic actuators for pick-and-place, welding, and sealing operations. Automotive tier-one suppliers in Stuttgart and Nagoya specify high-speed pneumatic lines for mixed-model assembly flexibility.
- Material Handling:Vacuum gripper systems enable contactless transport of wafers, PCBs, and packaged goods. Semiconductor fabs in Hsinchu and Dresden specify contamination-prevention protocols that drive specification premiums.
- Transportation:Vehicle braking, suspension, and door systems incorporate pneumatic actuation for reliability. Commercial truck and bus manufacturers specify air brake systems for heavy-duty applications.
- Industrial Processing:Food packaging, pharmaceutical filling, and chemical processing lines use pneumatic components for hygienic operation. FDA and EFSA compliance requirements shape material selection and cleanability design.
Automation anchors current deployment; material handling gains share fastest as electronics manufacturing expands cleanroom capacity.
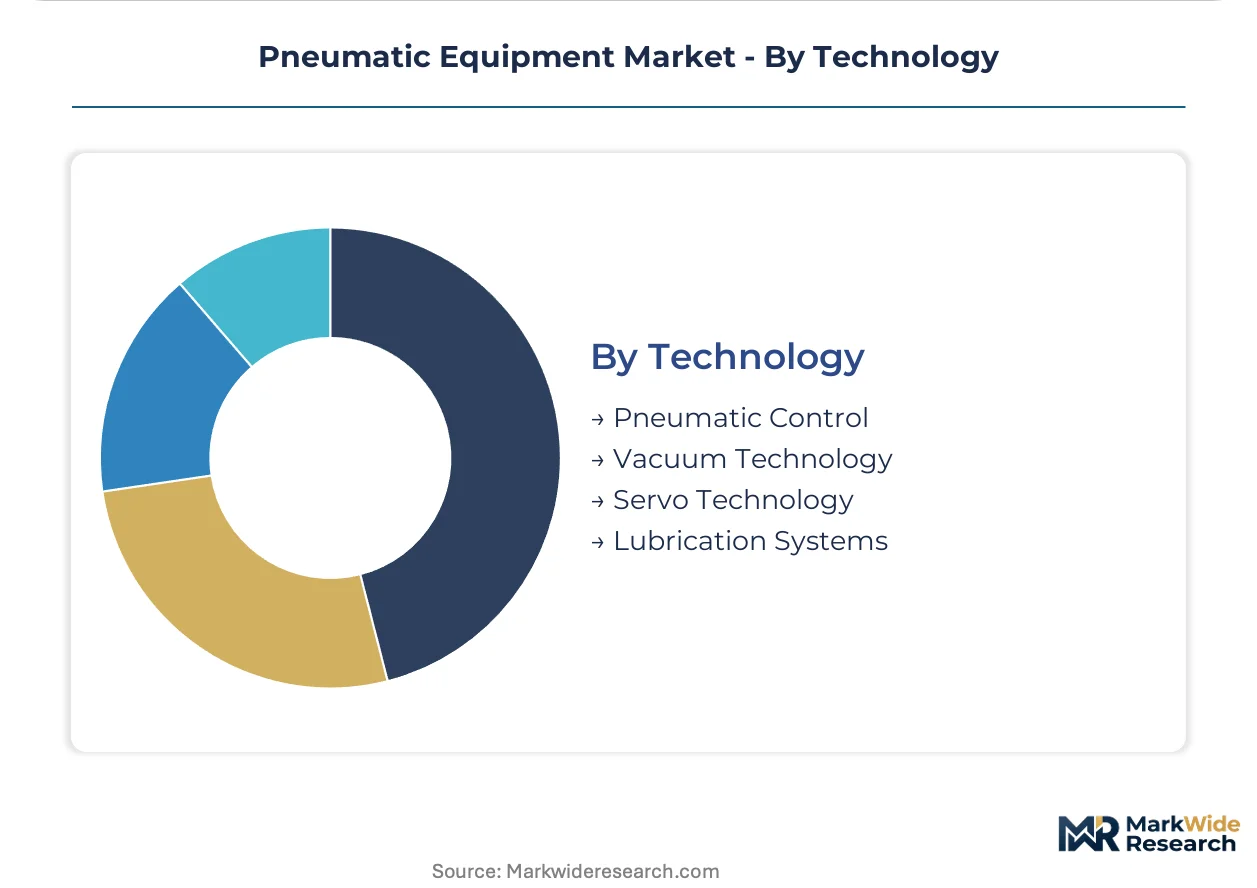
Technology:
Control philosophy and energy recovery mechanisms differentiate competitive offerings.
- Pneumatic Control:Conventional compressed air systems with directional valves and sequential logic remain dominant for cost-sensitive applications. These architectures persist where electromechanical alternatives cannot match power density or explosion safety requirements.
- Vacuum Technology:Suction-based handling systems enable contactless gripping for delicate or contaminant-sensitive components. Electronics cleanroom logistics in Taiwan and South Korea specify vacuum grippers to prevent wafer damage.
- Servo Technology:Closed-loop pneumatic positioning combines air power with electronic feedback for precision tasks. These hybrid systems encroach on electromechanical territory in mid-accuracy applications.
- Lubrication Systems:Oil-mist and micro-dosing architectures extend actuator life in high-cycle environments. Food and pharmaceutical packaging lines specify food-grade lubricants to comply with safety standards.
Pneumatic control retains volume leadership; vacuum technology climbs fastest as semiconductor and electronics manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors pneumatic equipment procurement intensity, where German automotive assembly plants specify multi-axis actuator arrays for body-in-white handling operations.
United States
Midwest dairy and meat processing facilities drive compressed air-as-a-service adoption to convert capital expenditure to operational expenditure. OSHA workplace compressed air safety thresholds govern equipment specification across Illinois and Wisconsin manufacturing bases. Chicago-area food packaging clusters concentrate demand for energy-monitored compressor installations with guaranteed uptime clauses.
Germany
Automotive tier-one suppliers in Baden-Württemberg expand pneumatic automation lines for mixed-model assembly flexibility. EU F-Gas Regulation mandates lower-emission compressor designs, forcing equipment replacement across French and German manufacturing corridors. Stuttgart and Munich industrial zones synchronize factory upgrade cycles with energy-efficiency procurement timing clusters.
China
Eastern manufacturing corridor facility upgrades accelerate demand for high-speed pneumatic automation lines. MIIT industrial equipment efficiency benchmarks influence compressor design specifications for domestic and export markets. Yangtze River Delta factory clusters concentrate procurement for electronics cleanroom handling systems with vacuum gripper specifications.
Japan
Nagoya automotive assembly plants specify pneumatic lines for lightweight component handling and welding station cycle compression. METI energy efficiency benchmarks directly shape compressor design specifications for equipment exported to Asian markets. Chubu region manufacturing bases integrate predictive maintenance sensor modules into Industry 4.0 architectures.
India
PLI scheme incentives attract electronics and automotive component assembly to Maharashtra and Gujarat greenfield sites. BIS certification requirements for industrial pneumatic equipment create specification barriers for imported systems. Pune and Ahmedabad manufacturing corridors present first-mover equipment specification windows for modular valve-terminal architectures.
Pneumatic Equipment Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with integrated automation portfolios. Japanese and German specialists command premium positioning through vocational training networks and modular system architectures. Three archetypes dominate: integrated valve-actuator portfolio holders, compressor-focused energy solution providers, and precision component specialists serving cleanroom applications. Consolidation pressure intensifies through strategic partnerships for sensor-integrated predictive maintenance platforms and geographic expansion into India's manufacturing corridor.
Within the integrated automation tier, SMC Corporation and Festo SE & Co. KG exemplify archetypes combining valve-terminal modularity with actuator portfolio breadth. Parker Hannifin Corporation anchors the aftermarket service vector for industrial pneumatic maintenance across energy and rail sectors. These three occupy positions reflecting divergent strategic emphases: compact automation solutions, vocational training-enabled system integration, and channel dominance in replacement parts logistics.
| Leading Market Players |
|---|
| SMC Corporation |
| Festo SE & Co. KG |
| Parker Hannifin Corporation |
| Emerson Electric Co. |
| Bosch Rexroth AG |
| Atlas Copco |
| Ingersoll Rand |
| Camozzi Automation |
| Norgren |
| Others |
Value Chain & Pricing Dynamics
Captive integration into precision solenoid manufacturing anchors supply positioning for valve-terminal producers while insulating pricing power from East Asian component volatility. German and Japanese specialists leverage in-house actuator casting and machining to defend margin structures against aluminum and steel input fluctuations.
Pricing Analysis
Outcome-based pricing tied to compressed-air-system uptime anchors service contracts for North American food processing facilities. Three-tier pricing structure across premium-certified, standard-industrial, and economy-replacement levels separates OEM specification tiers from aftermarket channels. Cost compression in commodity actuators intensifies because electromechanical substitution threatens precision positioning applications. Automotive tier-one suppliers exhibit lowest price sensitivity due to cycle-time performance requirements, while construction rental fleets prioritize acquisition cost over efficiency metrics.
Supply Chain Analysis
Direct-to-OEM channels handle high-volume automation demand from German and Japanese automotive assembly plants, while distributor networks serve fragmented maintenance-replacement markets. Precision solenoid manufacturing concentrates in coastal China, Taiwan, and South Korea, drawing from aluminum billet, specialty steel, and rare-earth magnet inputs. Single-source exposure in East Asian valve component zones creates tariff-escalation vulnerability for European and North American system integrators. Distribution runs through authorized service partners for predictive maintenance sensor retrofits and compressed-air-as-a-service deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation erects a cost-of-compliance moat that favors established players with R&D scale to redesign compressor architectures, disadvantaging capital-constrained entrants.
For Market Incumbents: Extend predictive maintenance sensor attach rates through outcome-based service contracting in Midwest food processing clusters. Deepen backward integration into precision casting to offset aluminum price volatility threatening cylinder margins. Electromechanical actuator substitution in precision positioning represents the most pressing technology threat requiring hybrid servo-pneumatic R&D response. For New Entrants and Emerging Players: Begin with modular valve-terminal architectures targeting India's PLI-subsidized electronics and automotive greenfield corridors. Cleanroom vacuum handling systems for semiconductor fabs present the most penetrable white space given specification complexity barriers. Partner with German or Japanese vocational training networks to compress system integration expertise gaps. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified industrial conglomerates seeking sensor-integrated automation platforms. Long-term viability favors specialists with captive component manufacturing and established certification pipelines across OSHA, CE marking, and METI jurisdictions. Watch for inflection signals in India's BIS certification enforcement creating import substitution windows.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Integration | Sensor-embedded valve terminals enable outcome-based contracting with food processing OEMs. |
| EU F-Gas Compliance Redesign | Heatless regeneration dryer architectures capture replacement demand from German packaging lines. |
| India Manufacturing Corridor Entry | PLI scheme incentives in Maharashtra create first-mover specification windows for modular systems. |
| Vocational Training Network Expansion | Festo-style apprenticeship pipelines compress commissioning timelines and lock in system integrator loyalty. |
| Compressed Air-as-a-Service Scaling | Energy monitoring and uptime guarantees convert Midwest dairy capex to recurring opex streams. |
Study Parameters
Trade publications, customs and import-export databases, and EU regulatory filings formed the secondary backbone for pneumatic equipment flow analysis. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and system integration specialists validated technical specifications and procurement timing patterns. Bottom-up and top-down triangulation cross-checked installed base estimates against production capacity disclosures.
Bottom-up modeling segmented volume and value across actuator, compressor, valve, and sensor categories, while top-down macroeconomic filters anchored aggregate market boundaries. Product type, end-user industry, application complexity, and regional regulatory cluster dimensions structured the analytical framework. CAGRs derived from equipment replacement cycle analysis and factory automation capital expenditure trajectories. Energy efficiency mandate compliance costs and semiconductor cleanroom capacity expansion served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; standardized compressor and actuator categories carry tighter precision than emerging vacuum handling applications. Forecasts reflect assumptions regarding regulatory enforcement continuity, commodity price stabilization, and electromechanical substitution pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Material Handling Integration Market
Material Handling Equipment
United States Hand Holes Market
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Global Industrial Weighing Equipment Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Fluid Conveyance Systems Market