
 Global Industrial Weighing Equipment Market | 2026-2036
Global Industrial Weighing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Weighing Equipment Market Outlook
Stainless steel is expanding its share in hygienic weighing platforms across food and pharmaceutical processing, replacing coated carbon steel assemblies that risk corrosion-induced contamination. Mettler-Toledo International Inc. leverages its Swiss manufacturing base to dominate high-precision laboratory-to-production workflows. Sartorius AG anchors biopharmaceutical weighing with single-use integration capabilities. Rice Lake Weighing Systems competes through domestic fabrication of custom load-cell configurations for North American agriculture and mining.
Industrial weighing equipment encompasses electromechanical and digital systems engineered to measure mass with resolutions from 0.001 milligrams to 500 tons, utilizing strain-gauge transducers, electromagnetic force compensation, or hydraulic load cells for process control, trade settlement, and regulatory compliance. Load cells generate the largest revenue pool due to their ubiquity across every scale architecture, while digital technology segments capture expanding margin pools as facilities retrofit analog installations for Industry 4.0 connectivity. Bench scales remain mature in light manufacturing, whereas integrated systems penetrate automated packaging lines where wireless data transmission eliminates manual recording errors.
ISO calibration standards, OIML certification requirements, and FDA 21 CFR Part 11 electronic records mandates collectively shape product design priorities and create barriers for uncertified entrants. EPA and OSHA regulations in the United States, alongside EU Machinery Directive conformity obligations, force manufacturers to embed overload protection and hazardous-area ratings into platform specifications. Stakeholders must monitor evolving cybersecurity frameworks for connected weighing devices as NIST and EN standards incorporate data-integrity requirements for cloud-integrated measurement systems.
Market Dynamics
Pharmaceutical manufacturers are accelerating precision-weighing upgrades to meet FDA and EMA compliance mandates for batch consistency. The shift toward strain-gauge load cells with digital signal processing is displacing older analog platforms across certified measurement systems.
Growth Catalysts
- FDA 21 CFR Part 11 mandates:Electronic records requirements force pharmaceutical facilities to retrofit analog scales with digital platforms that provide audit-trail capabilities and data-integrity safeguards.
- Automotive lightweighting programs:German producers require certified measurement systems for ISO 9001 traceability in precision component manufacturing, driving demand for high-resolution load cells.
- Single-use bioprocessing adoption:Biopharmaceutical manufacturers integrate disposable weighing assemblies to eliminate cross-contamination risks between production batches.
Market Restraints
- Stainless steel price volatility:Raw material cost swings for hygienic-grade alloys compress margins on food and pharmaceutical platform assemblies.
- Strain-gauge transducer supply concentration:Specialty sensor manufacturing clusters in Switzerland and Germany create geographic vulnerability for OEM sourcing strategies.
- CE marking complexity:EU Machinery Directive conformity obligations extend certification timelines for non-European manufacturers seeking market access.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO regulatory alignment with ICH guidelines creates upgrade demand for export-certified weighing systems in active pharmaceutical ingredient facilities.
- Wireless Industry 4.0 integration:Convergence of IoT protocols with cloud-integrated measurement systems enables predictive maintenance revenue streams for equipment vendors.
- Brazilian agribusiness modernization:ANVISA traceability requirements for food exporters drive replacement of mechanical scales with digital platforms in grain handling and processing.
Industry Challenges
- Metrology technician scarcity:Specialized calibration expertise for OIML-certified equipment outpaces vocational training program output in multiple manufacturing regions.
- Legacy analog retrofit complexity:Integration of digital signal processing with existing platform infrastructure requires custom engineering that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Weighing Equipment Market |
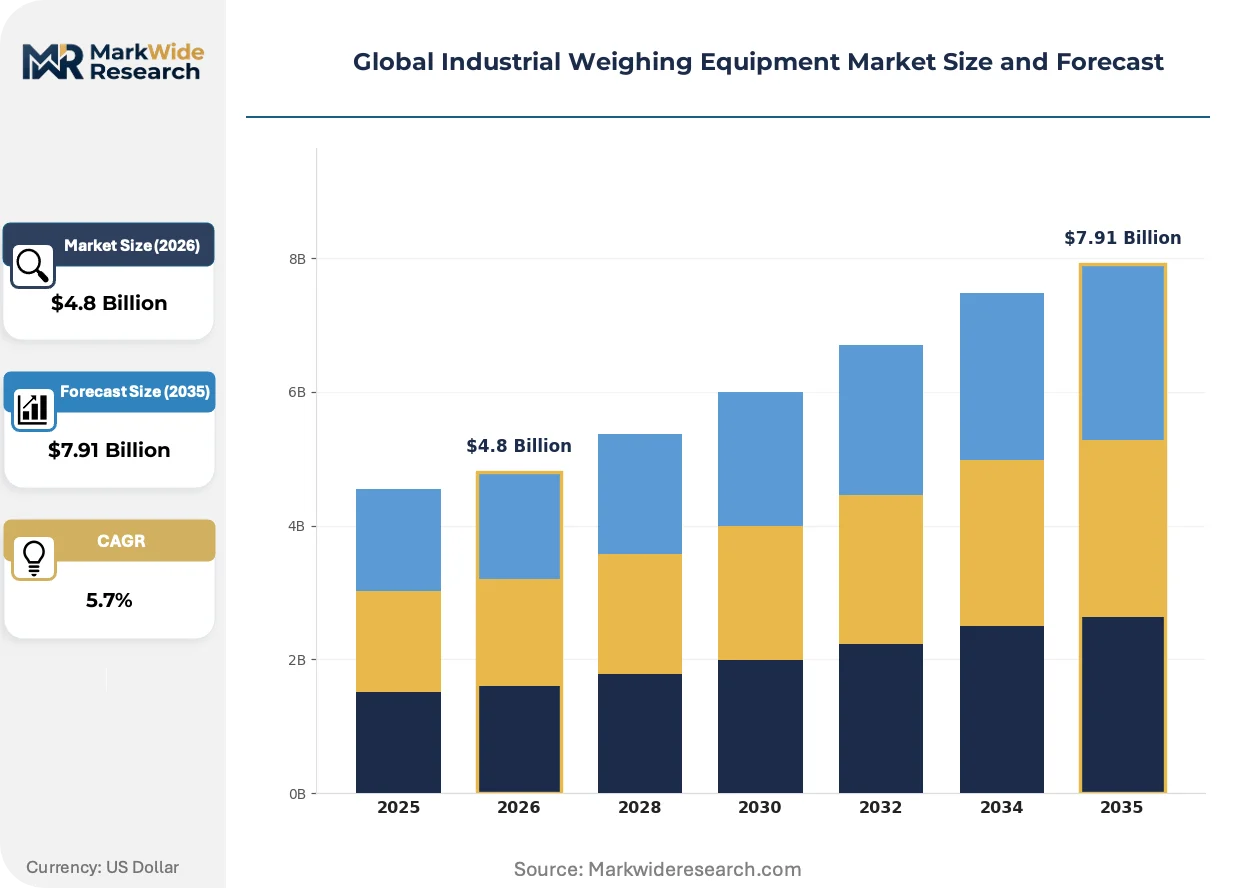
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Load Cells, Weighbridges, Bench Scales, Floor Scales End User: Manufacturing, Food Processing, Pharmaceutical, Logistics Technology: Electromechanical, Analog, Digital, Wireless Installation: Fixed, Portable, Semi-Permanent, Integrated Systems |
| Companies Covered | Minebea Intec GmbH, OHAUS Corporation, Mettler-Toledo International Inc., KERN & SOHN GmbH, Rice Lake Weighing Systems, A&D Weighing, Fairbanks Scales Inc., Sartorius AG, Avery Weigh-Tronix LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Weighing Equipment Market Strategic Shifts
Digital signal processing architectures are actively consolidating market share across industrial weighing platforms. This transformation compresses hardware differentiation and elevates software-enabled service revenues as the primary competitive battleground.
Strain-gauge load cells with embedded digital converters are consolidating their position as the default architecture for precision measurement. Pharmaceutical manufacturers in Germany and Switzerland adopt these platforms fastest to satisfy EMA audit requirements. The technology is consolidating supplier margins toward firmware and calibration services rather than hardware sales alone.
EU Machinery Directive conformity obligations now mandate embedded overload protection and hazardous-area ratings for all new platform installations. This regulatory shift forces redesign of legacy mechanical safety systems into electronic monitoring architectures. Food processing facilities across France and Italy face the steepest compliance curves as they retrofit open-frame bench scales.
After-sales service unbundling is fragmenting traditional equipment procurement patterns. End-users in North American agriculture now purchase calibration and maintenance contracts separately from hardware, pressuring distributor revenue models. This behavioral shift is most visible in grain elevator operations where seasonal usage patterns favor subscription-based metrology verification over capital purchase bundles.
Global Industrial Weighing Equipment Market Segmentation
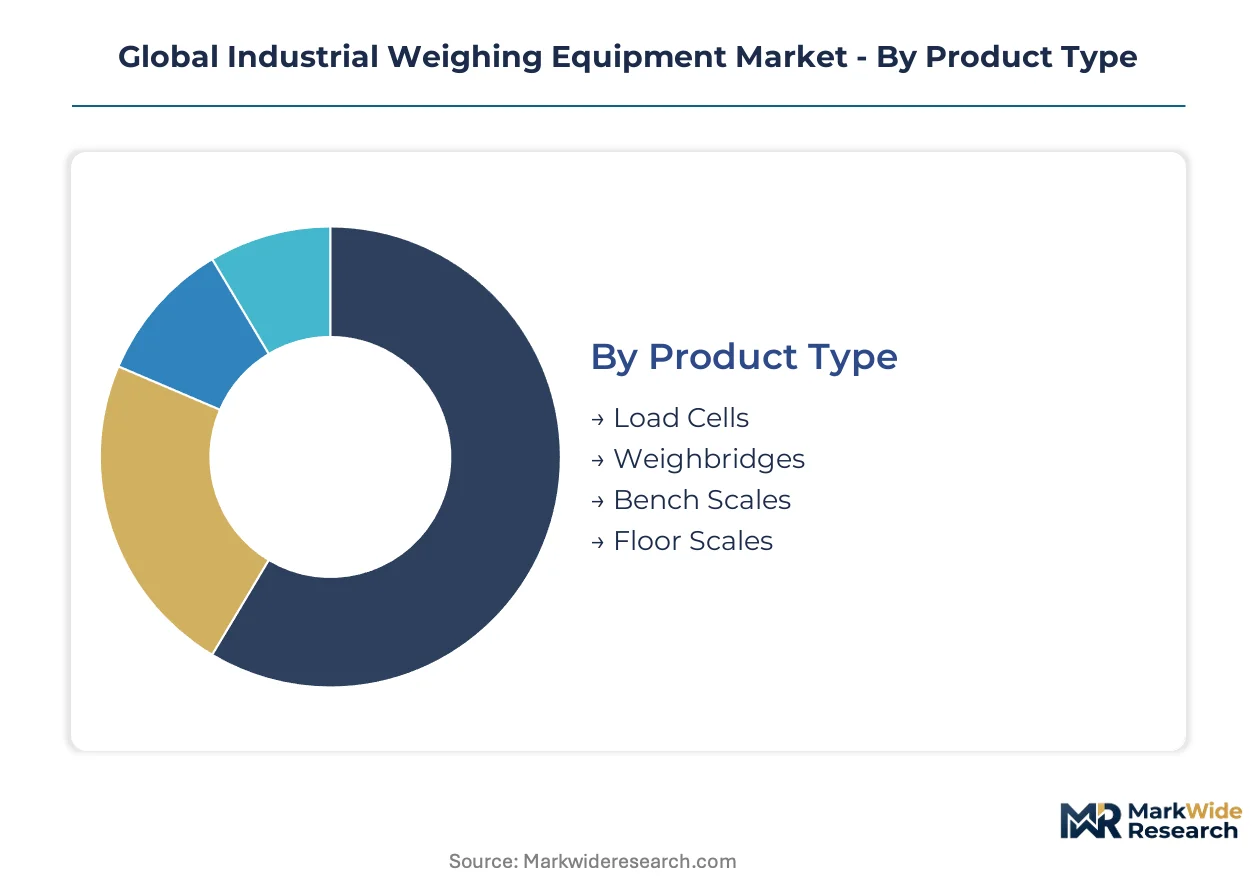
Industrial weighing equipment segmentation reveals how precision requirements, connectivity mandates, and facility constraints fragment procurement patterns across end-use verticals. Buyers prioritize different performance attributes based on regulatory exposure and operational scale.
Product Type:
Cost tier separates commodity purchasers from precision-specification buyers in this category.
- Load Cells:Strain-gauge transducers with digital signal processing convert mechanical force into electrical output for platform integration. Pharmaceutical manufacturers in Germany specify these for EMA-compliant batch weighing systems where traceability documentation is mandatory.
- Weighbridges:Heavy-capacity platforms engineered for truck and railcar measurement in bulk material handling. Brazilian grain exporters deploy these for ANVISA traceability compliance in soybean and corn loading operations.
- Bench Scales:Compact electromechanical units for light manufacturing quality control.
- Floor Scales:Mid-capacity platforms for warehouse and production floor material tracking.
Volume sits with load cells; growth tilts toward weighbridges.
End User:
Application environment dictates hygiene ratings, certification grade, and connectivity specifications.
- Manufacturing:ISO 9001 traceability requirements drive demand for calibrated measurement systems in automotive component production. German producers require certified platforms for lightweighting program quality gates.
- Pharmaceutical:FDA 21 CFR Part 11 mandates force electronic records capabilities into every weighing workflow. Single-use bioprocessing adoption accelerates demand for disposable weighing assemblies that eliminate cross-contamination.
- Food Processing:Stainless steel hygienic platforms replace coated carbon steel in facilities facing corrosion-induced contamination risks.
- Logistics:Wireless data transmission eliminates manual recording errors in automated packaging lines and distribution centers.
Manufacturing commands installed base; pharmaceutical scales are climbing the fastest.
Technology:
Margin structure inverts as hardware commoditizes and firmware becomes the value anchor.
- Digital:Embedded converters with Industry 4.0 protocol support enable predictive maintenance revenue streams. Facilities retrofit analog installations to capture cloud-integrated measurement capabilities and audit-trail functionality.
- Wireless:IoT convergence eliminates cabling infrastructure in automated production environments. North American agriculture favors these platforms for seasonal grain elevator operations where mobility reduces capital deployment.
- Electromechanical:Traditional strain-gauge architectures without signal processing conversion.
- Analog:Legacy voltage-output systems facing displacement by digital retrofit mandates.
Digital holds revenue concentration; wireless protocols gain share fastest.
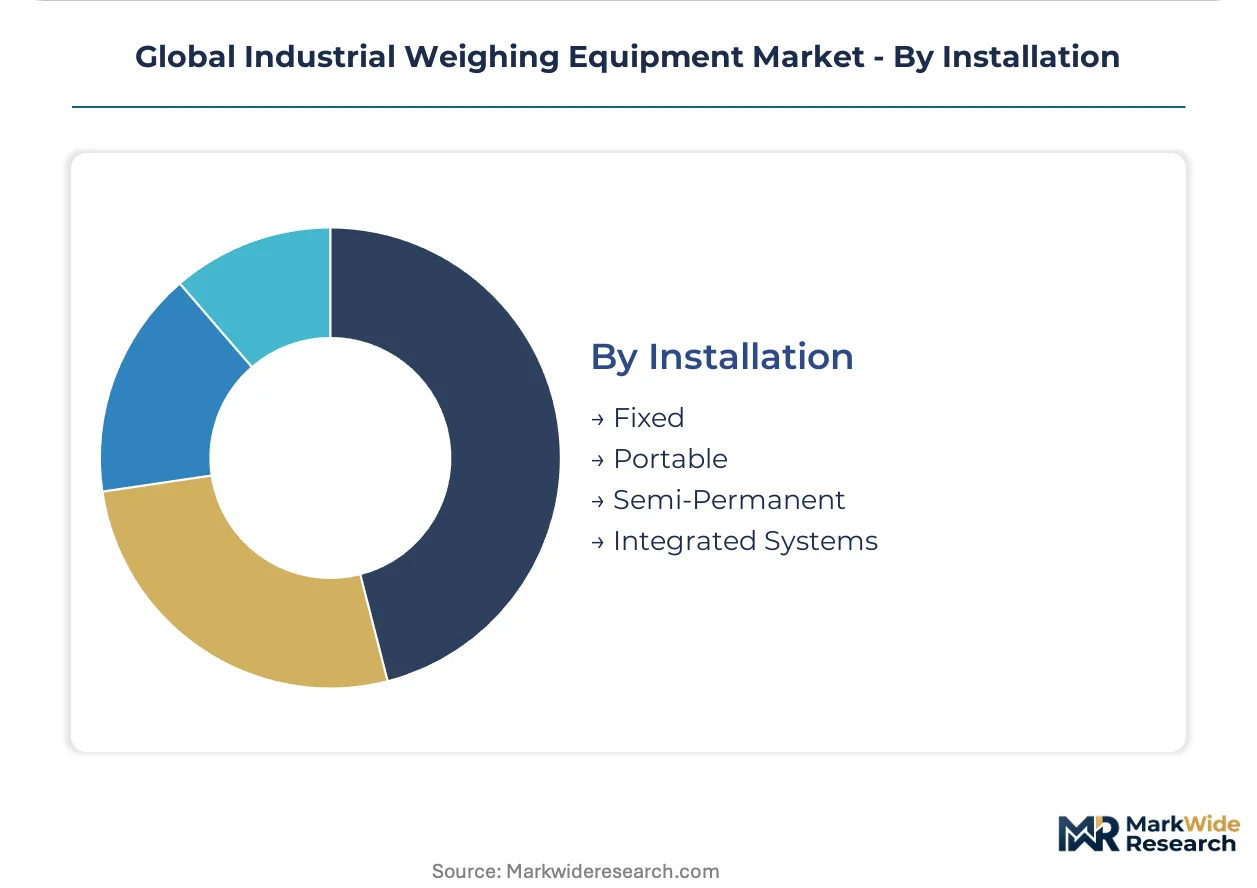
Installation:
Customer type and usage pattern determine capital structure and service contract bundling.
- Integrated Systems:Embedded weighing modules within automated packaging and processing lines. Food processing facilities across France and Italy retrofit open-frame bench scales to meet EU Machinery Directive conformity obligations.
- Fixed:Permanent foundation-mounted platforms for high-volume continuous operations.
- Portable:Mobile units for seasonal or multi-site deployment in agricultural and mining applications.
- Semi-Permanent:Modular platforms allowing relocation without full infrastructure rebuild.
Fixed installations dominate capital expenditure; integrated systems show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for industrial weighing equipment concentrates in manufacturing-intensive economies with stringent regulatory enforcement. Pharmaceutical and automotive producers in Germany, the United States, and Japan drive premium-tier procurement. Emerging markets in India and Brazil expand capacity to meet export certification requirements.
United States
Pharmaceutical manufacturers in New Jersey and North Carolina upgrade facilities to meet FDA 21 CFR Part 11 electronic records mandates. The EPA and OSHA enforce hazardous-area ratings for chemical processing installations. Houston's petrochemical corridor deploys certified measurement systems for trade settlement accuracy.
Germany
Automotive lightweighting programs in Stuttgart and Munich require ISO 9001 traceability for precision component manufacturing. The KBA enforces measurement system certification for production quality gates. Bavaria's chemical producers invest in strain-gauge load cells with digital signal processing.
China
Food processing facilities in Shandong and Jiangsu provinces replace mechanical scales with stainless steel hygienic platforms. The NMPA aligns pharmaceutical weighing standards with ICH guidelines. Shanghai's biopharmaceutical clusters adopt single-use weighing assemblies for batch consistency.
India
Active pharmaceutical ingredient manufacturers in Hyderabad and Ahmedabad retrofit analog installations for CDSCO export certification. The FSSAI mandates digital traceability for food processing weighing operations. Gujarat's chemical corridor demands OIML-certified systems for international shipment compliance.
Brazil
Grain exporters in Mato Grosso and Paraná states deploy weighbridges for ANVISA traceability compliance in soybean loading. The country's national agricultural regulator enforces digital platform adoption for food safety documentation. São Paulo's food processing belt accelerates corrosion-resistant platform procurement.
Global Industrial Weighing Equipment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. The market exhibits tiered concentration with Swiss and German precision specialists commanding premium positioning while regional fabricators compete on customization velocity. Three archetypes dominate: integrated multinational platforms, mid-scale regional specialists, and domestic custom fabricators. Competitive moves center on firmware differentiation for Industry 4.0 connectivity and strategic partnerships for distribution reach in emerging markets.
Within the precision instrumentation tier, Mettler-Toledo International Inc. and Sartorius AG exemplify Swiss and German engineering heritage in pharmaceutical-grade systems. Rice Lake Weighing Systems occupies a position among North American custom fabricators serving agriculture and mining applications. These three anchors represent distinct competitive vectors: multinational platform breadth, biopharmaceutical integration specialization, and domestic customization agility.
| Leading Market Players |
|---|
| Minebea Intec GmbH |
| OHAUS Corporation |
| Mettler-Toledo International Inc. |
| KERN & SOHN GmbH |
| Rice Lake Weighing Systems |
| A&D Weighing |
| Fairbanks Scales Inc. |
| Sartorius AG |
| Avery Weigh-Tronix LLC |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical OEM procurement concentration in Germany and Switzerland anchors contract-based pricing for OIML-certified strain-gauge load cells, with EMA audit requirements forcing buyers toward bundled calibration-service agreements rather than transactional hardware purchases.
Pricing Analysis
Volume concentrates in commodity bench scales and floor platforms where price erosion runs through Asian contract manufacturers, while margin pools concentrate in digital-integrated systems with embedded firmware subscriptions. Certification grade creates the primary price differentiation, with FDA 21 CFR Part 11-compliant platforms commanding substantial premiums over uncertified alternatives. Stainless steel price volatility is compressing margins on hygienic-grade food and pharmaceutical assemblies. Automotive manufacturers in Germany demonstrate the lowest price sensitivity due to ISO 9001 traceability mandates, whereas North American agricultural buyers favor unbundled hardware purchases with separate maintenance contracts.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States operate hub-and-spoke patterns for precision load-cell fulfillment, with specialty sensor manufacturing clusters in Switzerland and Germany creating geographic concentration for OEM sourcing strategies. Strain-gauge transducers, stainless steel alloys, and digital signal processors constitute the critical input dependencies. Single-source vulnerability in Swiss precision sensor fabrication presents structural supply risk. Distribution runs through authorized metrology service partners who bundle installation and calibration certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA 21 CFR Part 11 electronic records mandates erect barrier-to-entry moats favoring incumbent players with established audit-trail firmware and regulatory documentation capabilities.
For Market Incumbents: Acquire calibration service networks in North American agriculture and Brazilian grain handling to capture recurring revenue streams and defend against unbundling pressure from distributor partners. Backward integration into stainless steel fabrication in Germany mitigates raw material cost volatility. Invest in predictive maintenance algorithm development to reinforce software-enabled margin pools as hardware commoditizes. For New Entrants and Emerging Players: System integrators serving Indian pharmaceutical API facilities represent the most penetrable channel partner type, as CDSCO regulatory alignment with ICH guidelines creates upgrade demand without entrenched incumbent relationships. Target wireless Industry 4.0 retrofit opportunities in seasonal agricultural applications where capital constraints favor subscription-based metrology verification over upfront platform purchases. Partner with cloud infrastructure providers for predictive maintenance service bundling. For Investors and Strategic Acquirers: The window for entry favors firmware-specialist mid-cap targets with established OIML certification pathways and installed bases in pharmaceutical verticals. Long-term viability rests on software-enabled service revenue scaling rather than hardware shipment growth. Monitor NIST cybersecurity framework incorporation into cloud-integrated measurement standards as the inflection signal for compliance-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load-Cell Manufacturing | Captive supply of strain-gauge transducers insulates Swiss and German OEMs from geographic sourcing vulnerability. |
| Firmware Subscription Unbundling | Separates predictive maintenance revenue from hardware sales in North American agricultural and mining deployments. |
| Single-Use Bioprocessing Partnership | Disposable weighing assembly integration aligns Sartorius and Mettler-Toledo with biopharmaceutical batch consistency mandates. |
| Wireless Industry 4.0 Certification Investment | IoT protocol compliance enables cloud-integrated measurement penetration in automated packaging lines across France and Italy. |
| Regional Distribution Hub Expansion | Localized metrology service capacity accelerates OIML-certified deployment timelines in Indian pharmaceutical corridors. |
Study Parameters
Multi-period observation of pharmaceutical facility upgrade cycles, automotive lightweighting program procurement patterns, and agricultural seasonal equipment deployment anchored the trend analysis, supplemented by interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers at FDA and EMA-inspected facilities. Secondary validation drew from OIML certification databases, SEC 10-K filings of precision instrumentation manufacturers, customs trade data for load-cell imports, and EU Machinery Directive conformity documentation. Bottom-up shipment analysis triangulated against top-down end-use industry capital expenditure patterns.
Input-output matrices modeled demand across product type, end-use vertical, technology architecture, and installation configuration dimensions throughout the forecast period. CAGRs derived from segment-level growth rate convergence analysis incorporating regulatory mandate implementation timelines, retrofit cycle durations, and emerging market export certification alignment progress. Stainless steel price indices and semiconductor availability for embedded digital converters informed cost-side assumptions.
Caveats apply where NIST cybersecurity framework finalization, EU Machinery Directive enforcement intensity, or Indian CDSCO inspection capacity expansion could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Low Clearance Loaders Market
Material Handling Equipment
Metal Plain Washer Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
North America Conveyor Belt Market