
 Mobile Asphalt Plant Market | 2026-2036
Mobile Asphalt Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Asphalt Plant Market Analytics
The EPA National Ambient Air Quality Standards is recalibrating capital deployment across the mobile asphalt plant sector. Astec Industries leverages vertical integration in burner and control systems to sustain pricing power in drum mix configurations. Ammann Group anchors its position through R&D intensity in low-emission warm mix platforms. Marini India dominates the subcontinent with manufacturing scale that controls regional distribution channels.
A mobile asphalt plant is a relocatable facility that produces hot mix asphalt through drum or batch processes at production rates typically ranging from 100 to 500 tonnes per hour, designed for rapid site-to-site relocation to serve dispersed infrastructure projects. Drum mix configurations lead volume due to lower capital intensity and faster commissioning cycles, while warm mix technology commands expanding share as emissions compliance tightens. Batch mix systems retain margin concentration in airport runway and precision paving applications where specification flexibility carries premium value.
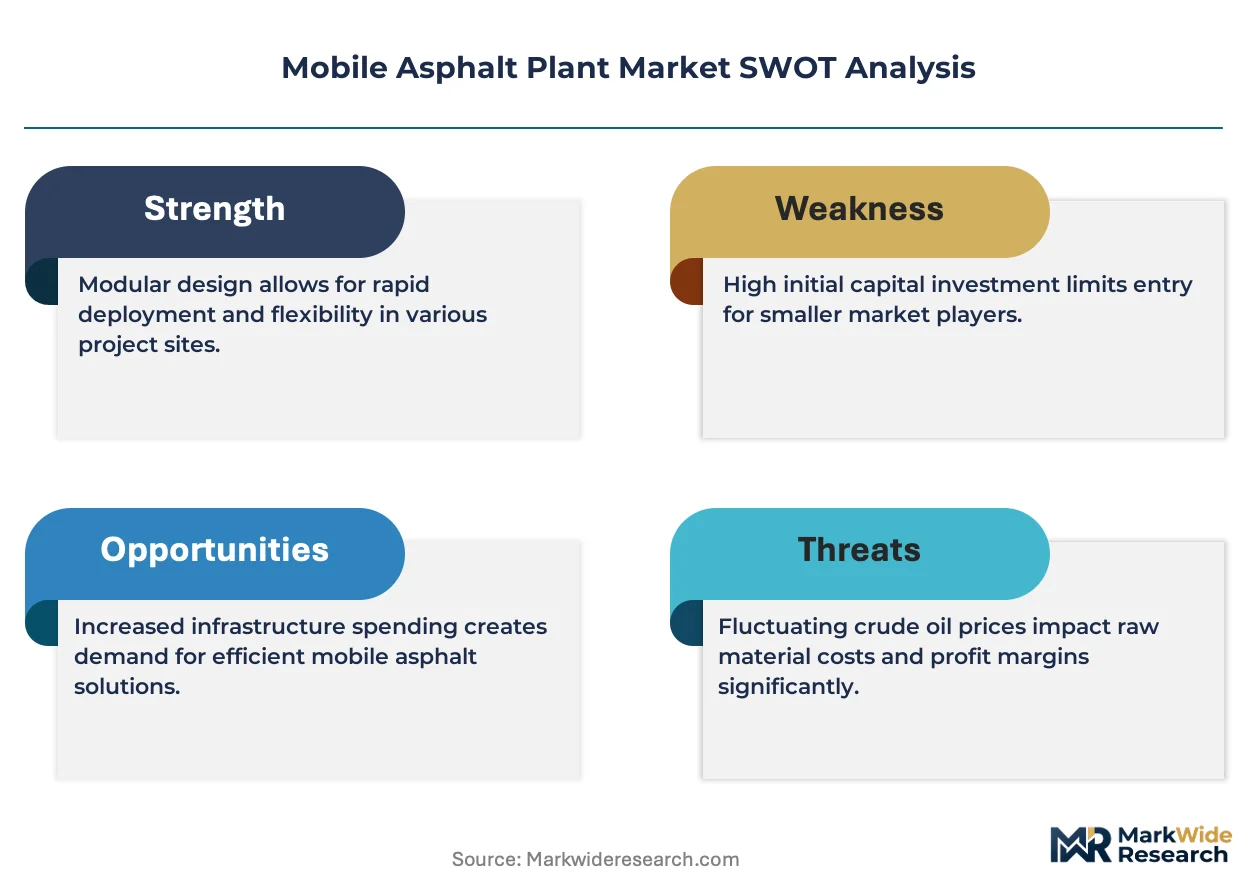
The EPA enforces stack emission limits that shape burner technology selection and baghouse configuration across the United States. India's Central Pollution Control Board aligns state-level consent mechanisms with construction equipment emission norms, creating compliance complexity for cross-border equipment suppliers. The EU F-Gas Regulation and CE marking requirements govern thermal efficiency standards for European deployments. Stakeholders must monitor regulatory divergence between federal and state jurisdictions when configuring fleet specifications for multi-territory operations.
Market Dynamics
The EPA National Ambient Air Quality Standards enforcement is compressing the operational window for conventional drum mix configurations. Highway contractors in India, the United States, and Germany are reallocating capital toward warm mix and low-emission burner systems to maintain project velocity under tightening stack limits.
Growth Catalysts
- Bharatmala Pariyojana expressway buildouts:India's National Highways Authority is tendering multi-year contracts requiring relocatable production capacity. Fleet operators are scaling drum mix deployments to capture rural road completion incentives.
- Warm mix technology maturation:Foaming and chemical additive processes cut fuel consumption by 20-30% while satisfying EPA emission thresholds. State transportation departments are revising specifications to permit lower-temperature paving.
- REACH compliance alignment:European contractors are pre-emptively upgrading baghouse and burner configurations to meet F-Gas Regulation thermal efficiency mandates ahead of enforcement deadlines.
Market Restraints
- Diesel price volatility:Drum mix operations consume 7-12 liters per tonne of asphalt. Indian and Brazilian operators face margin compression when crude benchmarks spike above $85 per barrel.
- Baghouse filter supply concentration:High-temperature aramid and P84 media production centers on German and Japanese specialty fiber suppliers, creating 12-16 week lead times during demand surges.
- Batch mix capital intensity:Precision paving specifications for airport runways require $2.5-4 million commissioning costs versus $800K-1.2 million for comparable drum units, limiting contractor entry.
Strategic Opportunities
- Indonesian trans-Sumatra highway corridor:The 2,700-kilometer toll road program lacks domestic asphalt production infrastructure. Mobile plant lessors can establish operational hubs in Medan and Palembang.
- Reclaimed asphalt pavement integration:Warm mix foaming systems enable 40-50% RAP content in surface courses. State DOTs in Texas and California are raising RAP percentage mandates.
- IoT-enabled predictive maintenance:Burner telemetry and vibration monitoring reduce unplanned downtime. Equipment financiers are bundling sensor packages with lease arrangements.
Industry Challenges
- Warm mix technician certification gaps:Foaming system calibration and additive dosing require specialized training. Contractors in secondary Indian states report 6-month certification backlogs.
- Multi-jurisdiction compliance stacking:Fleet operators serving both EPA-enforced US states and EU F-Gas jurisdictions must maintain dual burner and control system inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Asphalt Plant Market |
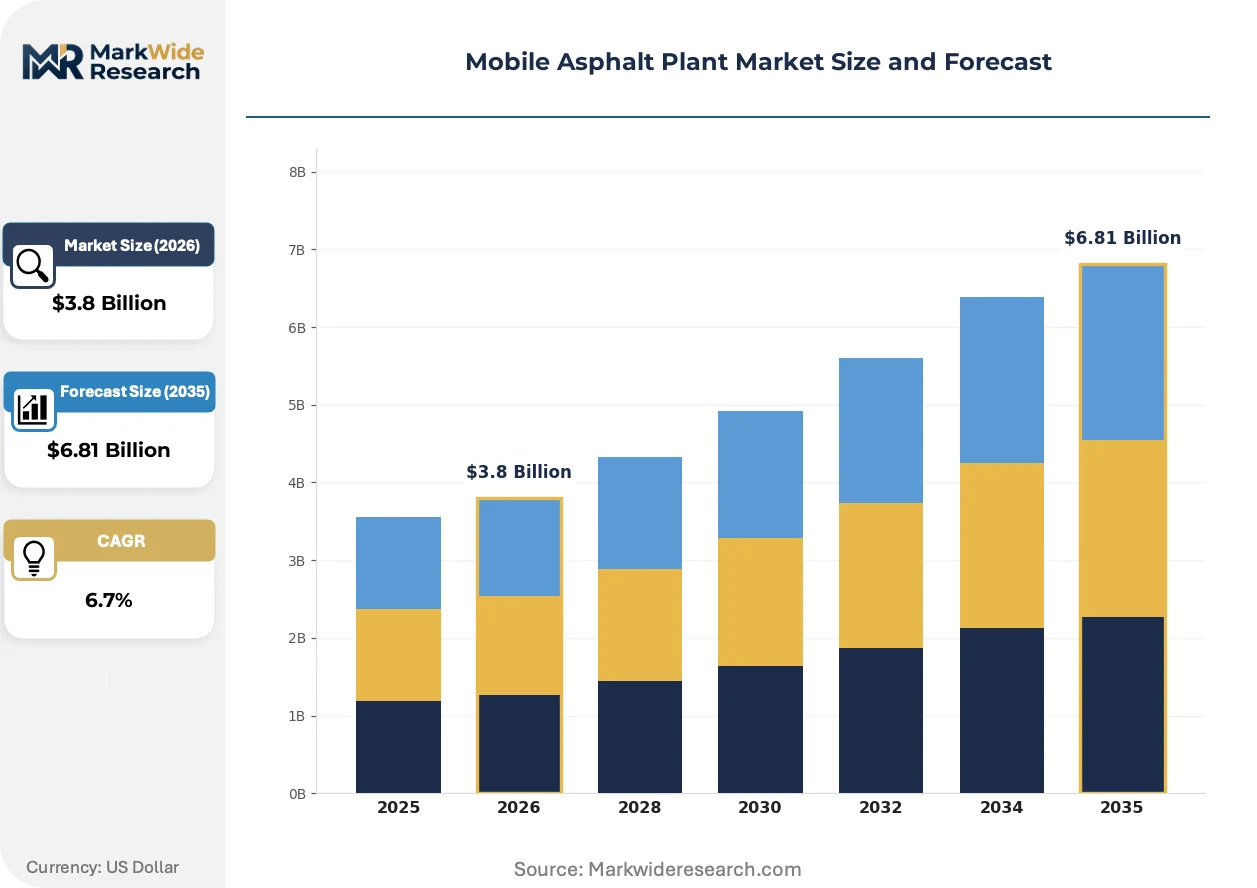
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Mix, Drum Mix, Continuous Mix, Mobile Cold Mix End User: Construction Companies, Paving Contractors, Government Agencies, Road Maintenance Providers Application: Highway Construction, Airport Runways, Urban Development, Parking Lots Technology: Hot Mix, Warm Mix, Cold Mix, Recycled Asphalt |
| Companies Covered | Astec Industries, Ammann Group, Marini India, CMI Roadbuilding, ALmix, Parker Plant Limited, Gencor, Atlas Technologies, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Asphalt Plant Market Evolving Landscape
Warm mix asphalt production methods are overtaking conventional hot mix processes as the default specification for federal and state highway contracts. Three interconnected developments are compressing the technology adoption cycle and rewiring equipment procurement criteria.
Foaming-based warm mix systems inject pressurized water or zeolites into asphalt binder to expand volume and reduce mixing temperatures. State transportation departments in California, Texas, and Florida are mandating warm mix for projects exceeding 50,000 tonnes. Drum mix OEMs are overtaking batch specialists in bid competitiveness as warm mix-enabled drum configurations capture 70% of new highway contractor inquiries.
The EPA National Ambient Air Quality Standards enforcement is tightening stack emission limits for particulate matter and nitrogen oxides. Drum mix operators must retrofit baghouse systems or face project suspension. Contractors in the Ohio River Valley and Los Angeles Basin are prioritizing low-NOx burner upgrades to maintain eligibility for federal highway funding allocations.
Highway authorities are consolidating procurement through multi-year equipment leasing rather than unit purchase. India's National Highways Authority and Germany's federal transport ministry are tendering 5-7 year operational contracts bundling plant, crew, and maintenance. Leasing specialists are displacing traditional equipment distributors in contractor relationships across the Bharatmala Pariyojana and Bundesfernstraßen programs.
Mobile Asphalt Plant Market Segmentation
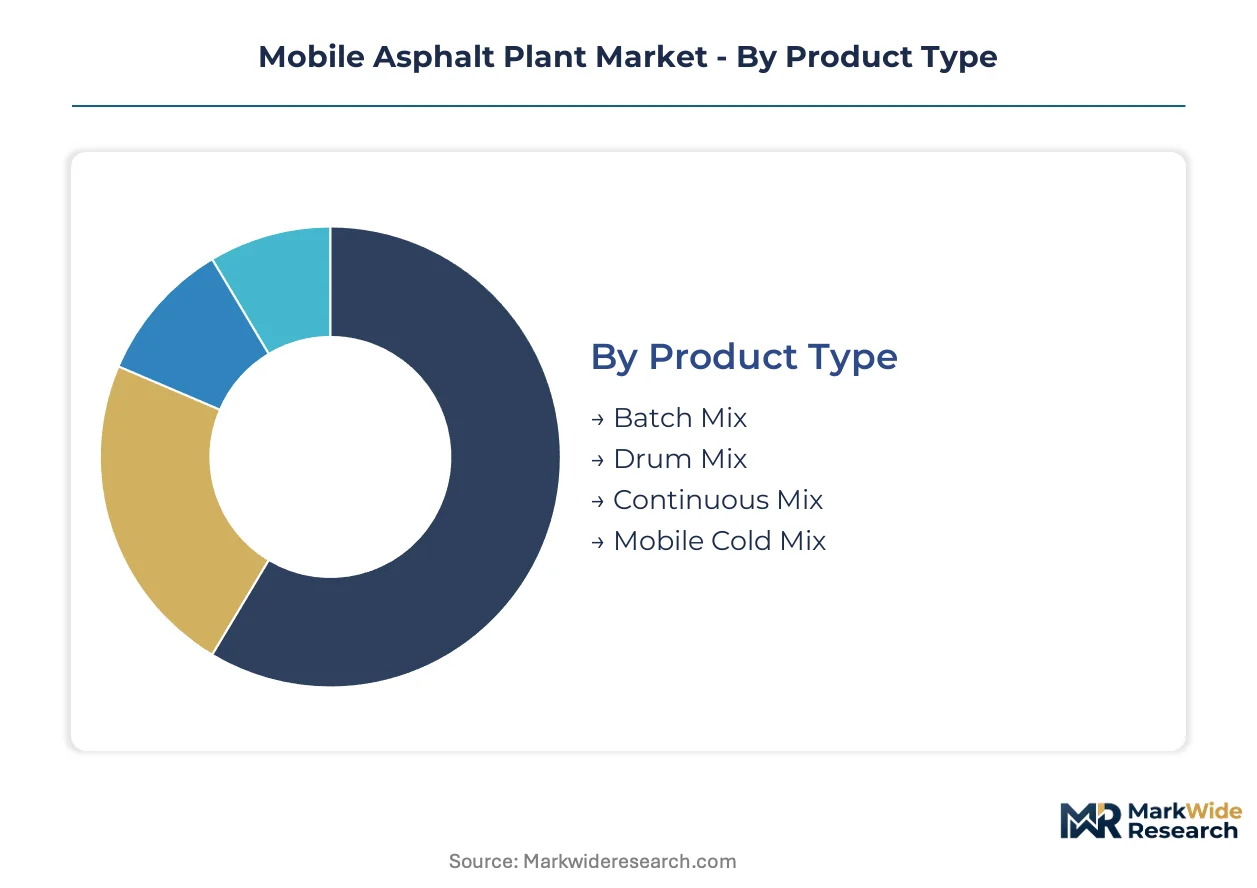
Equipment replacement cycles in mobile asphalt plants vary dramatically by configuration type and regulatory pressure. Contractors align fleet composition with project duration, emission compliance windows, and paving specification complexity.
Product Type:
Upgrade decisions hinge on capital recovery timelines and relocation frequency, with drum mix units dominating highway contractor procurement.
- Drum Mix:Continuous drying and mixing in a single rotating drum enables production rates of 100-500 tonnes per hour with minimal civil foundation requirements. India's Bharatmala Pariyojana contractors favor this configuration for rural expressway segments where rapid site relocation cuts mobilization costs.
- Batch Mix:Discontinuous weighing and mixing of aggregate fractions delivers precise gradation control for polymer-modified binders. Airport runway specifications in Germany and precision paving contracts in Texas sustain demand despite 3-4x capital intensity versus drum alternatives.
- Continuous Mix:Parallel flow drum designs with co-current aggregate and burner positioning suit high-RAP content production. The configuration appeals to European contractors navigating EU F-Gas Regulation thermal efficiency mandates.
- Mobile Cold Mix:Emulsion-based production at ambient temperatures serves remote maintenance operations and temporary road repairs. Brazilian and Indonesian road maintenance providers deploy these units where fuel logistics constrain hot mix operations.
Drum Mix sits at the top of the volume ranking, with Mobile Cold Mix climbing the fastest on rural maintenance outsourcing trends.
End User:
Procurement authority concentrates with entities controlling multi-year paving programs and federal funding access.
- Paving Contractors:Fleet operators bidding on state transportation department contracts drive equipment specification standardization. Warm mix technology adoption accelerates among this segment as EPA emission thresholds tighten eligibility for federal highway allocations.
- Construction Companies:Diversified infrastructure developers integrate asphalt production into vertical project delivery models. Large Indian construction groups deploy captive drum mix fleets across Bharatmala Pariyojana and state highway contracts.
- Government Agencies:Direct procurement by highway authorities and municipal corporations emphasizes lowest-life-cycle-cost evaluation. India's National Highways Authority tenders increasingly bundle plant operation with crew and maintenance.
- Road Maintenance Providers:Specialized resurfacing contractors prioritize rapid-deployment cold mix and warm mix configurations. German Bundesfernstraßen maintenance concessionaires favor mobile units for distributed network coverage.
Paving Contractors command the largest equipment installed base, while Government Agencies are gaining procurement share fastest through operational leasing models.
Application:
Surface specification stringency determines batch versus drum configuration selection and drives technology tier segmentation.
- Highway Construction:High-volume drum mix production dominates federal and state expressway programs. Warm mix specifications now cover 50,000+ tonne projects in California, Texas, and Florida.
- Airport Runways:Precision gradation and binder content requirements sustain batch mix premium positioning. FAA specification compliance demands dedicated quality control infrastructure.
- Urban Development:Noise and emission constraints in dense metropolitan areas favor warm mix and low-NOx burner retrofits. Los Angeles Basin contractors face project suspension risks without stack compliance upgrades.
- Parking Lots:Commercial and municipal surface paving tolerates wider specification bands, enabling cost-optimized drum mix deployment. Seasonal demand concentration in North American and European markets shapes fleet utilization rates.
Highway Construction anchors volume demand, with Urban Development expanding most quickly on warm mix specification adoption.
Technology:
Emission compliance trajectories are compressing the operational window for conventional hot mix processes.
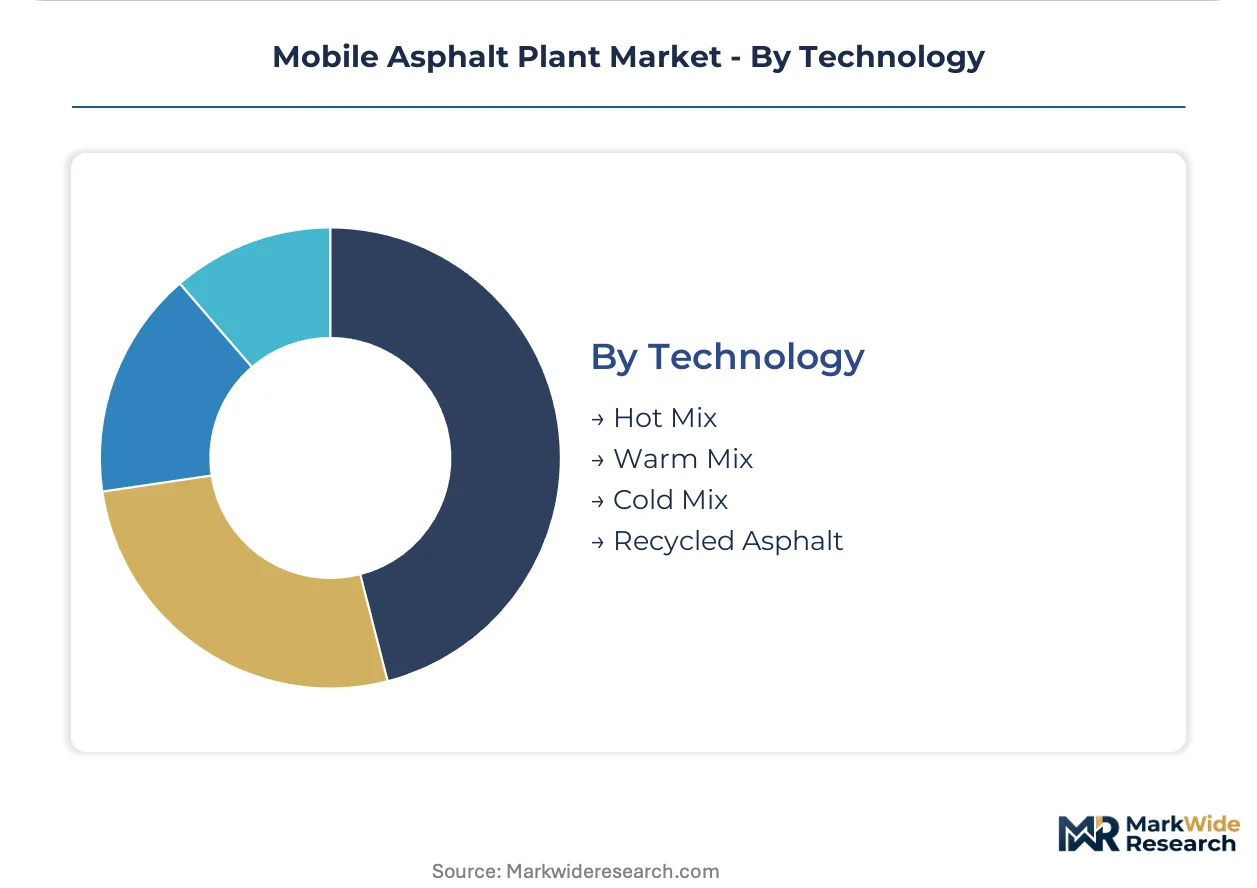
- Warm Mix:Foaming and chemical additive processes cut fuel consumption 20-30% while satisfying EPA particulate and NOx thresholds. State DOT specification revisions now permit lower-temperature paving across the Ohio River Valley and Southeast regions.
- Hot Mix:Conventional 150-180°C production retains share in developing markets with relaxed emission enforcement. Indian state highway contracts in secondary markets still specify hot mix for cost-minimization.
- Cold Mix:Emulsion and cutback technologies serve remote maintenance and emergency repair applications. Indonesian trans-Sumatra highway maintenance contracts create distributed demand.
- Recycled Asphalt:Warm mix foaming systems enable 40-50% RAP integration in surface courses. Texas and California DOTs are raising reclaimed content mandates for environmental compliance credits.
Hot Mix retains volume leadership in absolute terms, with Warm Mix capturing specification share fastest on federal and state contract revisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled equipment operators and maintenance technicians concentrate in highway construction corridors where mobile asphalt plant deployment accelerates. Workforce density in asphalt paving specialties drives regional equipment demand patterns. Regulatory enforcement intensity varies sharply across national jurisdictions.
United States
Highway contractors in the Ohio River Valley and Los Angeles Basin face compressed operational windows under EPA National Ambient Air Quality Standards enforcement. State transportation departments in California, Texas, and Florida now mandate warm mix specifications for projects exceeding 50,000 tonnes. Equipment lessors cluster in Houston and Atlanta to serve federal highway funding allocations.
India
The National Highways Authority accelerates expressway buildouts under Bharatmala Pariyojana, tendering multi-year contracts requiring relocatable production capacity. Central Pollution Control Board emission norms align state-level consent mechanisms with construction equipment standards. Fleet operators scale drum mix deployments across Maharashtra and Gujarat to capture rural road completion incentives.
Germany
Bundesfernstraßen maintenance concessionaires favor mobile units for distributed network coverage across federal highway corridors. EU F-Gas Regulation thermal efficiency mandates govern burner technology selection and baghouse configuration. Equipment fabricators concentrate in North Rhine-Westphalia to serve cross-border infrastructure contracts.
Indonesia
The 2,700-kilometer trans-Sumatra highway corridor lacks domestic asphalt production infrastructure, creating demand for mobile plant lessors. National infrastructure programs prioritize rapid-deployment configurations for remote maintenance operations. Operational hubs emerge in Medan and Palembang to serve toll road construction segments.
Brazil
Road maintenance providers deploy mobile cold mix units where fuel logistics constrain hot mix operations in remote regions. Diesel price volatility above $85 per barrel compresses margins for drum mix operators in secondary markets. Equipment distributors concentrate in São Paulo and Minas Gerais to serve state highway concession programs.
Mobile Asphalt Plant Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers in the mobile asphalt plant sector. Market structure shows moderate concentration with tiered competition between integrated industrial groups and regional equipment fabricators. Three strategic archetypes dominate: full-line asphalt equipment suppliers, burner and control system specialists, and regional manufacturing scale players. Competitive moves center on warm mix technology licensing partnerships and operational leasing model expansion.
Among North American full-line suppliers, Astec Industries and CMI Roadbuilding occupy positions representing integrated equipment and control system capabilities. Ammann Group and Marini India exemplify the geographic specialization archetype, with name-based positioning suggesting European and subcontinental manufacturing footprints respectively. These anchors illustrate how competitive positioning splits between technology-integrated conglomerates and regionally concentrated fabrication scale.
| Leading Market Players |
|---|
| Astec Industries |
| Ammann Group |
| Marini India |
| CMI Roadbuilding |
| ALmix |
| Parker Plant Limited |
| Gencor |
| Atlas Technologies |
| ADM |
| Others |
Value Network & Pricing Analysis
Drum mix versus batch mix capital intensity divergence creates a bifurcated procurement landscape where highway contractors optimize for relocation velocity while airport specialists absorb premium commissioning costs. This tier split manifests in leasing rate spreads and shapes inventory positioning across regional equipment hubs.
Pricing Analysis
Bundled operational contracts versus unbundled equipment-only sales split contractor procurement decisions across the mobile asphalt plant sector. Three-tier pricing structure across premium warm mix configurations, standard drum units, and economy cold mix alternatives reflects burner technology tiers and baghouse sophistication. Cost compression in standard drum configurations is intensifying because diesel price volatility above crude benchmarks compresses per-tonne margins. Government agencies tendering multi-year operational leases show lowest price sensitivity, while independent paving contractors in secondary Indian states exhibit acute cost responsiveness.
Supply Chain Analysis
Warehouse-distribution layer concentration in Houston, Atlanta, and Medan anchors regional spare parts availability for drum mix operators across North American and Southeast Asian highway corridors. Manufacturing scale concentrates in Germany, India, and the United States, with burner control systems and baghouse filter media drawing from Japanese aramid fiber suppliers and German specialty component fabricators. Single-source vulnerability in high-temperature filtration media creates procurement exposure during demand surges. Distribution runs through equipment lessors with captive maintenance crews rather than traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile asphalt plant sector operates as a regulatory compounder where EPA National Ambient Air Quality Standards enforcement accelerates warm mix technology replacement cycles and sustains equipment demand across compliance-driven upgrade windows.
For Market Incumbents: Deploy warm mix technology licensing as the primary lever to capture specification share as state DOTs revise paving standards. Incumbents should anchor burner system backward integration to defend margin position against low-cost drum fabricators entering from China and Turkey. Capacity addition in Maharashtra and Gujarat secures proximity to Bharatmala Pariyojana contract flows. For New Entrants and Emerging Players: Equipment lessors represent the most accessible channel partner type for bypassing established distributor relationships. New entrants should target Indonesian trans-Sumatra highway maintenance contracts where domestic production infrastructure remains underdeveloped. A operational lease-first go-to-market angle bypasses capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with warm mix technology specialists possessing foaming system intellectual property and EPA certification pathways. Long-term viability hinges on regulatory enforcement persistence across multiple jurisdictions rather than cyclical highway funding. Acquisition targets should display burner control system differentiation and established state DOT specification relationships. The signal to watch is F-Gas Regulation alignment progress among European fleet operators as a leading indicator of technology tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Warm Mix Technology Licensing | EPA emission thresholds in Ohio River Valley and Los Angeles Basin accelerate specification adoption. |
| Backward Integration into Burner Systems | Astec Industries and Ammann Group sustain pricing power through captive control technology production. |
| Operational Leasing Model Expansion | India's National Highways Authority tenders displace traditional equipment distributors across Bharatmala Pariyojana. |
| Regional Distribution Hub Establishment | Medan and Palembang hubs serve Indonesian trans-Sumatra corridor maintenance outsourcing demand. |
| IoT Predictive Maintenance Bundling | Sensor telemetry packages reduce unplanned downtime for drum mix fleet operators under tight completion schedules. |
Research Methodology
Multiple input streams — highway contractor procurement directors, equipment OEM technical sales leads, state DOT specification engineers, and aftermarket service managers — were reconciled against customs trade records, EPA enforcement disclosure databases, and National Highways Authority tender documentation. Primary fieldwork with fleet operators in India, Germany, and the United States was cross-validated through bottom-up installation base enumeration and top-down highway funding allocation analysis.
Historical production volume trajectories were cross-referenced against panel input from equipment financiers and leasing specialists to anchor projection assumptions. The analytical framework modeled demand across product type, end user procurement authority, application specification stringency, and technology compliance tier throughout the forecast period. CAGRs were derived from segmented growth rate reconciliation against macro infrastructure spending envelopes and regulatory enforcement intensity indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to crude price volatility, filter media supply disruptions, and multi-jurisdiction compliance stacking complexity. Outputs reflect documented assumptions regarding EPA enforcement continuity and Bharatmala Pariyojana tender pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Construction Lasers Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Hammer Unions Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Fixed Crane Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Global Crane Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Hydraulic Breaker for Excavator Market