
 Axle Shaft Market | 2026-2036
Axle Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Axle Shaft Market Analysis
Commercial vehicle electrification is repositioning axle shaft procurement priorities across OEM supply chains. Dana Holding Corporation leverages its electrified driveline expertise to anchor contracts with hybrid truck platforms. Meritor Inc. competes through specialized e-axle architectures that integrate motor and gearbox functions. American Axle & Manufacturing Inc. sustains its position in conventional heavy-duty segments while navigating the transition toward electrified alternatives.
An axle shaft is a rotating drivetrain component, typically forged from medium-carbon alloy steel and heat-treated to achieve tensile strengths exceeding 800 MPa, that transmits torque from the differential to the wheels while supporting vehicle weight. Its primary purpose is to deliver reliable power transfer under torsional and bending loads across passenger, commercial, and off-highway applications. Hollow axle shafts command expanding share in heavy-duty truck specifications where mass reduction directly improves freight efficiency and fuel economy. Composite axle shafts remain nascent but attract development capital from performance-oriented OEMs seeking corrosion resistance and damping properties. Solid axle shafts dominate aftermarket channels due to lower unit costs and universal fitment across aging vehicle populations.
NHTSA governs axle shaft fatigue testing and dimensional tolerances for vehicles operating on US highways, while EPA emissions standards indirectly shape demand through weight-based compliance incentives. The EU Green Deal and REACH chemical restrictions influence material selection for European-sourced shafts, particularly regarding surface treatment processes. Stakeholders must monitor evolving e-axle integration standards and determine whether to develop in-house motor-axle systems or source modular assemblies from tier-one suppliers.
Market Dynamics
Electrification of commercial drivetrains is fragmenting established axle shaft procurement hierarchies as OEMs recalibrate between conventional forging competencies and integrated e-axle architectures. This structural pivot compresses supplier decision timelines while elevating requirements for thermal management and torque density in next-generation designs.
Growth Catalysts
- EPA Phase 3 Emissions Standards:US freight operators face escalating compliance costs tied to vehicle weight, accelerating hollow axle shaft specifications that trim mass without sacrificing torsional rigidity.
- India's PLI Scheme for Automotive Components:Domestic manufacturers in Pune and Chennai expand heat-treatment capacity to capture incentives targeting advanced alloy processing for export-grade shafts.
- Induction Hardening Process Advances:Surface engineering improvements extend fatigue life in heavy-duty cycles, reducing warranty exposure for fleet operators managing high-mileage assets.
Market Restraints
- Scrap Steel Price Volatility:Medium-carbon alloy feedstock costs swing with Turkish and Vietnamese import flows, squeezing forging margins for tier-two suppliers.
- REACH Chemical Restrictions:EU surface treatment chemistries face substitution mandates, forcing European foundries to retool phosphate coating lines ahead of compliance deadlines.
- Technical Limitation in Composite Joining:Carbon fiber axle shafts struggle with hub interface reliability under cyclic loading, confining deployment to motorsport and limited supercar volumes.
Strategic Opportunities
- Thailand's Eastern Economic Corridor:Japanese and Korean OEMs localize axle forging for ASEAN export, leveraging tariff advantages and port infrastructure at Laem Chabang.
- IRA Clean Vehicle Tax Credits:North American e-axle assembly incentives attract motor-gearbox-shaft integration investments from tier-one suppliers repositioning for electrified platforms.
- Blockchain-Enabled Provenance Tracking:Fleet operators pilot digital material certificates to verify heat-treatment batch compliance, creating subscription revenue streams for data-integrated component vendors.
Industry Challenges
- Electrification Skill Gap:Forging engineers lack training in electromagnetic torque path design, slowing workforce transition at conventional axle plants.
- E-Axle Certification Timelines:NHTSA has not finalized harmonized test protocols for integrated motor-axle assemblies, delaying platform approvals and freezing procurement commitments.
- Legacy ERP Integration:Real-time quality data from induction hardening cells fails to sync with decades-old MRP systems at tier-two forges, blocking digital thread implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Axle Shaft Market |
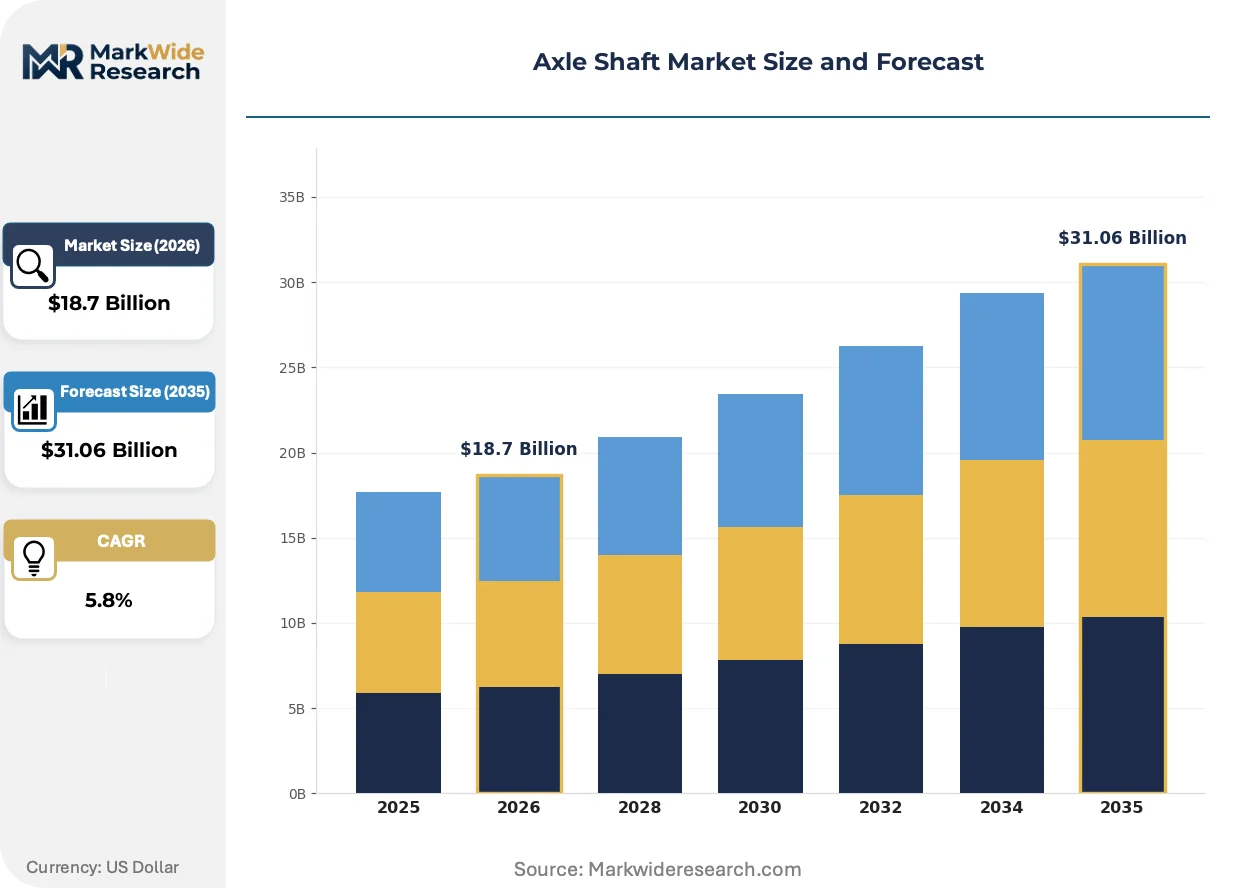
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Axle Shaft, Hollow Axle Shaft, Bi-Metal Axle Shaft, Composite Axle Shaft Vehicle Type: Passenger Cars, Commercial Vehicles, Heavy-Duty Trucks, Two-Wheelers Material: Steel, Aluminum, Carbon Fiber, Alloy End User: OEMs, Aftermarket Providers, Fleet Operators, Custom Builders |
| Companies Covered | JTEKT Corporation, Meritor Inc., Dana Holding Corporation, Nexteer Automotive Group Ltd., Hyundai Wia Corporation, American Axle & Manufacturing Inc., ZF Friedrichshafen AG, NTN Corporation, GKN Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Axle Shaft Market Emerging Trajectories
Axle shaft engineering is converging around three vectors: architecture simplification through integrated subsystems, regulatory pressure on material provenance, and fleet operator demands for lifecycle cost transparency over upfront unit economics.
Additive manufacturing of near-net-shape preforms is modularizing forging workflows at specialized suppliers in Germany and Japan. Tier-one commercial vehicle programs adopt hybrid production lines blending conventional hammer forging with selective laser melting for complex flange geometries. This technology is modularizing supplier tiers by collapsing tool-and-die lead times from months to weeks.
EU CSRD disclosure mandates now require Scope 3 emissions reporting across automotive supply chains, compelling axle shaft producers to document alloy sourcing and heat-treatment energy intensity. Foundries in Italy and Poland invest in electric induction furnaces to replace gas-fired batch operations. Commercial vehicle OEMs serving EU markets prioritize suppliers with validated environmental product declarations.
Fleet operators increasingly specify total cost of ownership contracts that bundle axle shaft replacement cycles with predictive maintenance analytics. Leasing companies displace traditional parts distributors in North American heavy-duty channels. This restructuring is most visible in Texas and California freight corridors where mega-fleets consolidate vendor relationships under single-source service agreements.
Axle Shaft Market Segmentation
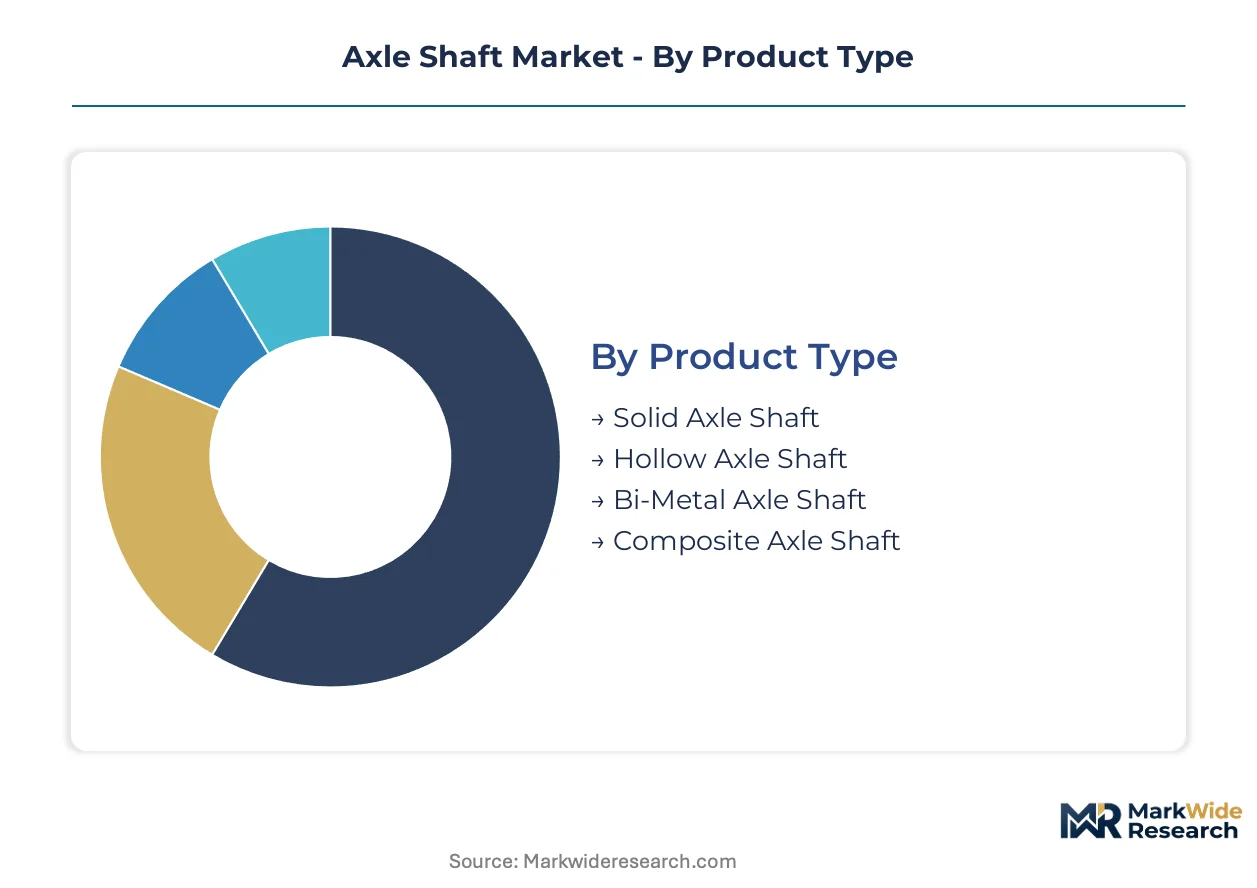
Axle shaft procurement patterns diverge sharply across product architectures, vehicle duty cycles, and supply channel structures. Fleet operators prioritize replacement intervals and total lifecycle cost, while OEMs balance upfront forging investment against electrification roadmaps. Understanding these segment boundaries clarifies where margin pools concentrate and which specifications face displacement risk.
Product Type:
Upgrade and replacement cycles vary dramatically by shaft architecture, with hollow designs commanding premium positioning in fuel-conscious freight fleets while solid shafts dominate high-volume aftermarket turnover.
- Hollow Axle Shaft:Manufactured from medium-carbon alloy steel with precision-machined internal bores, these shafts reduce unsprung mass while maintaining torsional stiffness above 800 MPa. Demand concentrates in North American heavy-duty truck manufacturing, where EPA Phase 3 emissions standards reward every kilogram of weight reduction with measurable fuel savings across million-mile duty cycles.
- Solid Axle Shaft:Forged as monolithic cylinders with induction-hardened bearing surfaces, these components prioritize unit economics over mass efficiency. Replacement volumes cluster in aging commercial vehicle populations across Texas and California freight corridors, where fleet operators minimize capital outlay on secondary assets.
- Bi-Metal Axle Shaft:Hybrid constructions bonding steel journals to aluminum tubes address specific corrosion-prone applications.
- Composite Axle Shaft:Carbon fiber reinforced polymer shafts remain confined to motorsport validation programs due to hub interface durability concerns under cyclic torsional loading.
Volume placements concentrate in solid axle configurations; the faster expansion belongs to hollow shafts.
Vehicle Type:
Cost tier segmentation separates premium integrated e-axle platforms from conventional driveline refresh cycles, with electrification timelines dictating procurement urgency across vehicle classes.
- Heavy-Duty Trucks:Class 8 vehicles specify hollow shafts almost exclusively, with axle loads exceeding 13,000 kg demanding fatigue resistance across 500,000+ mile replacement intervals. Indian manufacturers in Pune and Chennai expand heat-treatment capacity to serve export orders from ASEAN freight operators.
- Commercial Vehicles:Light and medium-duty trucks balance payload efficiency with acquisition cost, creating specification fragmentation between solid and hollow architectures. Thai assembly plants within the Eastern Economic Corridor localize forging to capture Japanese and Korean OEM sourcing.
- Passenger Cars:Unibody platforms increasingly adopt modular rear axle modules with integrated hub bearings.
- Two-Wheelers:Solid shafts dominate motorcycle rear swingarm applications where torsional loads remain modest and cost sensitivity is acute.
Commercial vehicle channels absorb the highest absolute shaft volumes; passenger car electrification is climbing the fastest as e-axle integration eliminates discrete shaft procurement.
Material:
Application-specific loading requirements and regulatory pressure on material provenance determine alloy selection, with surface treatment chemistry facing REACH-driven substitution mandates in European supply chains.
- Steel:Medium-carbon alloys with manganese and chromium additions constitute the baseline specification, with induction hardening extending surface fatigue life in high-mileage commercial deployments. Scrap steel price volatility from Turkish and Vietnamese import flows compresses forging margins unpredictably.
- Alloy:Nickel-chromium-molybdenum formulations serve extreme-duty mining and construction equipment where impact loading exceeds standard material limits.
- Aluminum:Hollow extrusions with steel insert journals target weight-critical passenger EV platforms.
- Carbon Fiber:Torque tube applications in limited-series performance vehicles exploit damping properties and corrosion immunity.
Steel commands current production volumes; alloy specifications are gaining share fastest in off-highway equipment segments.
End User:
Customer type segmentation reveals divergent purchasing logic, with fleet operators consolidating vendor relationships under predictive maintenance contracts while custom builders prioritize specification flexibility over unit cost.
- Fleet Operators:Mega-fleets across North American freight corridors negotiate total cost of ownership agreements bundling shaft replacement cycles with telematics-based wear monitoring. These contracts displace traditional parts distributors in Texas and California markets.
- OEMs:Vehicle manufacturers specify axle shafts at platform development gates, with electrification roadmaps forcing recalibration between conventional forging partnerships and integrated e-axle suppliers. Dana Holding Corporation and Meritor Inc. compete for hybrid truck platform anchoring contracts.
- Aftermarket Providers:Independent distributors serve aging vehicle populations with solid shaft inventory emphasizing universal fitment and immediate availability.
- Custom Builders:Low-volume specialty manufacturers source billet-machined shafts with non-standard spline configurations.
OEM channels anchor current specification authority; fleet operator direct procurement is expanding most quickly as leasing companies consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor concentrates Japanese and Korean OEM axle forging investments, leveraging Laem Chabang port infrastructure for ASEAN export distribution. Tax incentives under Thailand's Board of Investment attract heat-treatment capacity expansion from tier-one suppliers. This zone anchors Southeast Asian production gravity for hollow shaft specifications serving fuel-efficiency mandates.
United States
Class 8 truck manufacturers in Michigan and Ohio specify hollow axle shafts to meet EPA Phase 3 emissions weight targets. NHTSA governs fatigue testing protocols for driveline components operating on interstate highways. Dallas-Fort Worth freight corridors host mega-fleet consolidation of vendor relationships under predictive maintenance contracts.
Germany
Commercial vehicle OEMs in Bavaria and Baden-Württemberg source induction-hardened shafts for million-mile replacement intervals. REACH chemical restrictions force phosphate coating line retooling at foundries ahead of compliance deadlines. Stuttgart industrial clusters pioneer additive manufacturing of near-net-shape preforms for complex flange geometries.
China
Domestic heavy-duty truck production in Shandong and Hubei provinces drives medium-carbon alloy shaft demand for mining and construction equipment. MIIT oversees GB standards for axle component dimensional tolerances. Yangtze River Delta forging clusters expand electric induction furnace capacity to replace gas-fired batch operations.
India
Pune and Chennai manufacturers scale heat-treatment capacity to capture PLI scheme incentives for advanced alloy processing. BIS certification requirements govern tensile strength specifications for export-grade shafts. Tamil Nadu automotive clusters serve ASEAN freight operator procurement from Thai assembly plants.
Axle Shaft Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one integrated suppliers anchoring OEM platform development while tier-two forges serve aftermarket replacement cycles. The vendor base concentrates around three strategic archetypes: forging-heritage suppliers with heat-treatment expertise, e-axle integrators combining motor and gearbox functions, and modular assembly specialists. Dominant competitive moves include capacity expansion in Thailand's Eastern Economic Corridor and strategic partnerships for blockchain-enabled material provenance tracking.
Among Japanese tier-one suppliers, JTEKT Corporation and NTN Corporation occupy positions within the precision bearing and driveline component tier. American Axle & Manufacturing Inc. exemplifies the forging-heritage archetype sustaining conventional heavy-duty positions. Dana Holding Corporation and Meritor Inc. represent the integrated e-axle transition vector competing for hybrid truck platform anchoring contracts. ZF Friedrichshafen AG anchors the German engineering-led tier with Friedrichshafen-based driveline system integration capabilities.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Meritor Inc. |
| Dana Holding Corporation |
| Nexteer Automotive Group Ltd. |
| Hyundai Wia Corporation |
| American Axle & Manufacturing Inc. |
| ZF Friedrichshafen AG |
| NTN Corporation |
| GKN Automotive |
| Others |
Supply Flow & Price Mechanics
Additive manufacturing adoption in German and Japanese forging clusters collapses tool-and-die lead times from months to weeks, simultaneously compressing prototyping costs and concentrating premium pricing power among suppliers mastering hybrid production workflows. This technological inflection reshapes procurement economics as OEMs trade unit price premiums against accelerated platform development cycles.
Pricing Analysis
Short lead-time premiums dominate pricing architecture, with hollow axle shaft specifications commanding substantial markups over solid shaft spot inventory due to precision-machined internal bore complexity. Three-tier pricing structure across premium, standard, and economy levels separates induction-hardened million-mile shafts from conventional aftermarket replacements. Cost compression in standard-grade segments is intensifying because Turkish and Vietnamese scrap steel import volatility squeezes tier-two forging margins. Fleet operators demonstrate lowest price sensitivity, prioritizing total cost of ownership metrics over upfront unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Class 8 truck manufacturers in Michigan and Ohio, while aftermarket distributors serve aging vehicle populations across Texas and California freight corridors. Supply concentration rests on Thailand's Eastern Economic Corridor, Germany's Stuttgart industrial clusters, and India's Pune-Chennai manufacturing belt. Medium-carbon alloy steel feedstock, induction hardening equipment, and phosphate coating chemistries constitute critical input dependencies. Single-source vulnerability around Turkish scrap steel flows creates exposure to margin volatility. Distribution runs through tier-one integrated suppliers anchoring OEM platforms and independent distributors serving replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA Phase 3 emissions standards and REACH chemical restrictions erect substantial barrier-to-entry moats for forging operations with certified heat-treatment and surface engineering capabilities.
For Market Incumbents: Extend certification investments into blockchain-enabled material provenance tracking to capture fleet operator subscription revenue streams. Deepen backward integration into induction hardening equipment supply to insulate margins from Turkish scrap steel volatility. Electrification skill gaps at conventional axle plants represent the most pressing workforce threat requiring targeted electromagnetic torque path training programs. For New Entrants and Emerging Players: Leasing companies displacing traditional parts distributors in North American heavy-duty channels offer the most penetrable entry vector for hollow shaft specifications bundled with predictive maintenance analytics. Target mega-fleet consolidation trends in Texas and California freight corridors where single-source service agreements are restructuring vendor relationships. Pursue white-label forging partnerships with Thai Eastern Economic Corridor facilities to bypass capital-intensive heat-treatment infrastructure requirements. For Investors and Strategic Acquirers: Re-rating potential sits with tier-two forges possessing electric induction furnace capacity and validated environmental product declarations given EU CSRD disclosure mandates accelerating across automotive supply chains. Acquisition focus should center on operations with documented alloy sourcing transparency and Scope 3 emissions reporting infrastructure. The signal to watch is NHTSA finalization of harmonized e-axle test protocols, which would unfreeze procurement commitments and trigger tier-one supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| E-Axle Architecture Development | Integrated motor-gearbox-shaft assemblies capture hybrid truck platform contracts from Dana and Meritor. |
| Induction Hardening Capacity Expansion | Electric furnace investments at Italian and Polish foundries satisfy REACH compliance while reducing batch energy intensity. |
| Blockchain Provenance Implementation | Digital material certificates verify heat-treatment batch compliance for fleet operator subscription contracts. |
| Thailand Manufacturing Localization | Eastern Economic Corridor forging leverages Laem Chabang port infrastructure for ASEAN export distribution. |
| Predictive Maintenance Bundling | Telematics-integrated shaft replacement cycles displace traditional aftermarket distributors in North American freight corridors. |
Methodological Framework
Document review covered SEC 10-K filings from tier-one suppliers, EPA emissions compliance databases, and REACH chemical restriction notices, complemented by interviews with OEM platform engineers, fleet procurement directors, aftermarket distribution heads, and forging plant managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, and customs/trade flow records. Bottom-up shaft volume modeling triangulated against top-down commercial vehicle production forecasts.
Cross-referencing historical procurement patterns against expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include shaft architecture, vehicle duty class, material grade tier, and end-user purchasing behavior. CAGRs were derived from slope-intercept fitting of normalized replacement cycle data and electrification transition assumptions. Forecast inputs incorporated EPA Phase 3 compliance timelines and PLI scheme incentive trajectories.
Several conditions sit outside the modeled scope, including potential NHTSA e-axle protocol delays, unforeseen REACH chemical substitution mandates, and geopolitical disruptions to Turkish scrap steel flows. Forecasts reflect base-case assumptions around electrification penetration rates and fleet operator consolidation velocity. Periodic stress-testing of base assumptions is recommended given regulatory uncertainty and raw material price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
South America Automotive Market
Powertrain
Global Driveline Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Positive Crankcase Ventilation Valve Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Global Automotive Damper Pulley Market
Powertrain
North America Torque Vectoring Market
Powertrain
Natural Gas Engines Market
Powertrain
Torque Limiter Market
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Automotive Engine Market
Powertrain
Automotive Half Shaft Market