
 Slide Top Tins Market | 2026-2036
Slide Top Tins Market Size, Share, and Industry Trends Forecast 2026-2036
Slide Top Tins Market Analytics
The EU Green Deal is broadening compliance obligations for reusable and recyclable packaging across European consumer goods supply chains. Crown Holdings, Inc. leverages its continental manufacturing footprint to serve beverage-to-tin crossover demand. Allstate Can anchors North American production with deep tooling capabilities for custom formats. TinWerks Packaging specializes in decorative finishes that command premium positioning in gift-oriented channels.
Slide top tins are rigid metal containers featuring a friction-fit lid that slides horizontally along a grooved track, typically manufactured from tinplate or aluminum with rolled edges and lithographically printed surfaces; they serve primarily as protective, reclosable packaging for premium consumer goods requiring repeated access. Custom tins and decorative variants capture the highest margin pools as brand owners prioritize unboxing experience and shelf differentiation. Standard tins dominate volume throughput in food packaging, while mini tins gain traction in cosmetic sampling and travel retail formats. Aluminum material grades are displacing heavier tinplate in weight-sensitive logistics corridors.
EMA and EFSA frameworks govern direct food contact materials and migration limits for metal packaging across EU member states, while REACH compliance constrains coating chemistries and surface treatments. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recyclability targets that favor mono-material tin constructions over multi-layer alternatives. Stakeholders must monitor forthcoming delegated acts on minimum recycled content thresholds that will reshape material sourcing strategies and supplier qualification criteria.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing a structural pivot toward mono-material tinplate constructions as brands face mandatory extended producer responsibility and recyclability targets that disqualify multi-layer alternatives.
Growth Catalysts
- EU Green Deal compliance mandates:Extended producer responsibility frameworks now require packaging producers to finance end-of-life collection and recycling, favoring tinplate's established recovery infrastructure over plastic laminates.
- Premium confectionery gift packaging:German and French chocolate brands are expanding slide top tin orders for seasonal collections, driving demand for decorative lithographic finishes and custom embossing.
- Specialty tea and coffee retail expansion:Western European boutique roasters and tea merchants are adopting slide top tins as reusable, shelf-differentiating containers that support premium price positioning.
Market Restraints
- Tinplate input cost volatility:Steel substrate prices fluctuate with energy-intensive smelting economics, compressing converter margins when spot markets spike.
- REACH coating chemistry constraints:ECHA restrictions on epoxy-based internal lacquers force reformulation investments and extended migration testing timelines.
- Aluminum substitution in logistics corridors:Weight-sensitive e-commerce fulfillment networks are favoring lighter aluminum alternatives for shipping cost optimization.
Strategic Opportunities
- Cosmetic sampling and travel retail mini formats:Fragrance houses and skincare brands are piloting pocket-sized slide top tins for trial-size distribution and duty-free channels.
- Minimum recycled content thresholds:Forthcoming EU delegated acts on post-consumer metal content will create first-mover advantages for converters with certified scrap supply chains.
- Direct-to-consumer subscription channels:Specialty food brands are bypassing wholesale to ship refillable tin formats on recurring schedules, building retention through packaging permanence.
Industry Challenges
- Migration testing and EFSA notification backlog:Novel coating systems face extended approval timelines, delaying product launches and freezing specification changes.
- Deep tooling capability scarcity:Custom slide track geometries and rolled-edge precision require specialized press configurations that few contract manufacturers maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slide Top Tins Market |
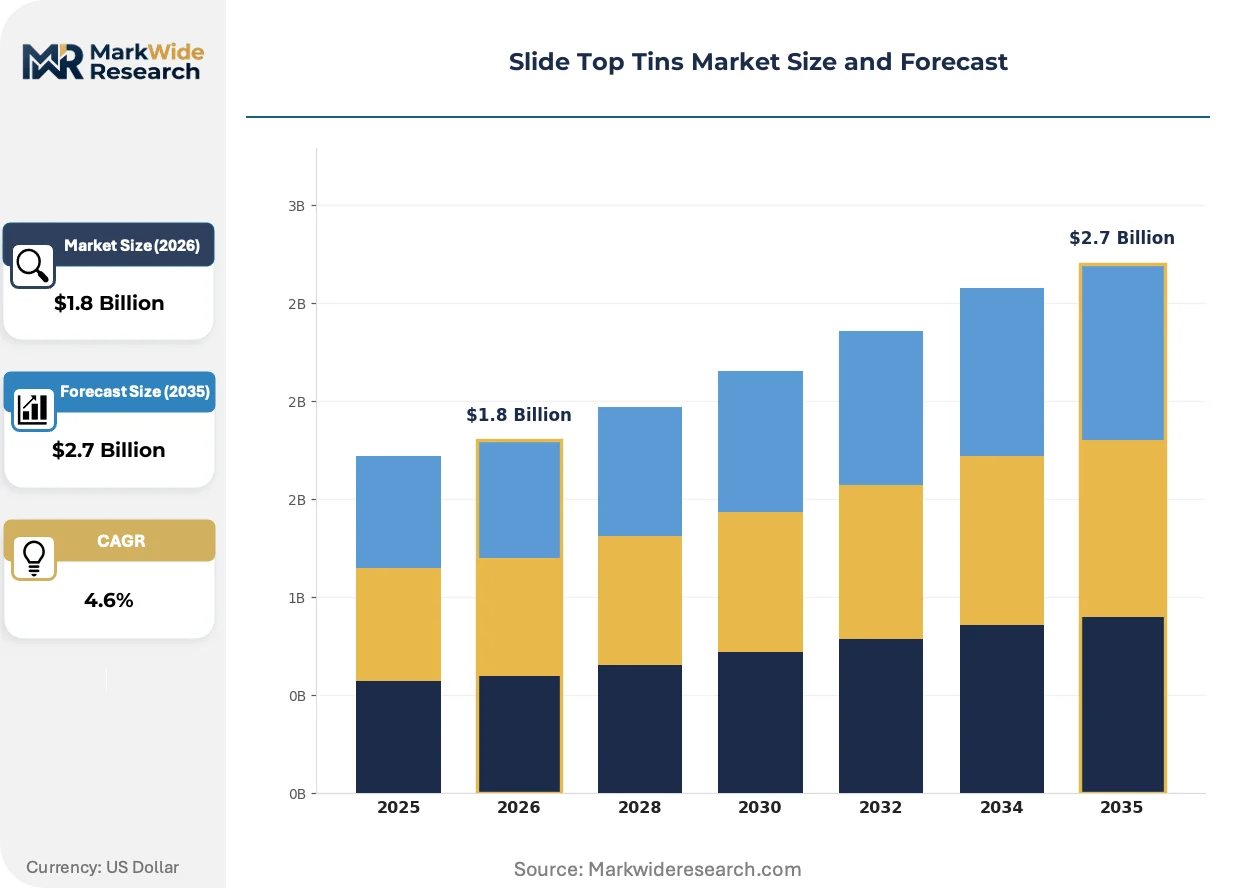
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tins, Custom Tins, Mini Tins, Decorative Tins Material: Aluminum, Tinplate, Plastic, Steel End User: Food Packaging, Cosmetic Industry, Tobacco Products, Pharmaceuticals Size: Small, Medium, Large, Custom Sizes |
| Companies Covered | Allstate Can, TinWerks Packaging, Qingyuan Max Tin Cans Manufacturing, Yum Tin, Dongguan Tinpak, Independent Can, Dongguan City Xin Yu Tin Can Manufactory, Tin-Pac Promotional Packaging, Crown Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slide Top Tins Market Evolving Landscape
Active innovation across the slide top tins market centers on material substitution, regulatory anticipation, and channel-specific format engineering that redefines value capture along the supply chain.
Aluminum alloy grades with enhanced formability are overtaking traditional tinplate in weight-sensitive applications. E-commerce fulfillment operators in Germany and the Netherlands have adopted aluminum slide top tins for premium chocolate shipments, cutting dimensional weight charges by 15-20 percent. This material shift is overtaking established tinplate specifications in logistics corridors where shipping economics dominate packaging selection.
The EU Packaging and Packaging Waste Regulation's recyclability performance grades are reshaping converter investment priorities. Mono-material tinplate constructions now qualify for top-tier labeling that influences retailer procurement decisions. Specialty tea brands in France and Belgium are reformulating specifications to eliminate plastic window films and composite inserts that downgrade recyclability scores.
Buyer concentration among direct-to-consumer specialty food brands is fragmenting order patterns toward smaller runs with faster turnaround. Traditional food service distributors are losing share to platform-native brands that order seasonal designs in 5,000-unit batches. This pattern is most visible in the UK and Scandinavian markets, where subscription coffee merchants rotate tin artwork quarterly to sustain engagement.
Slide Top Tins Market Segmentation
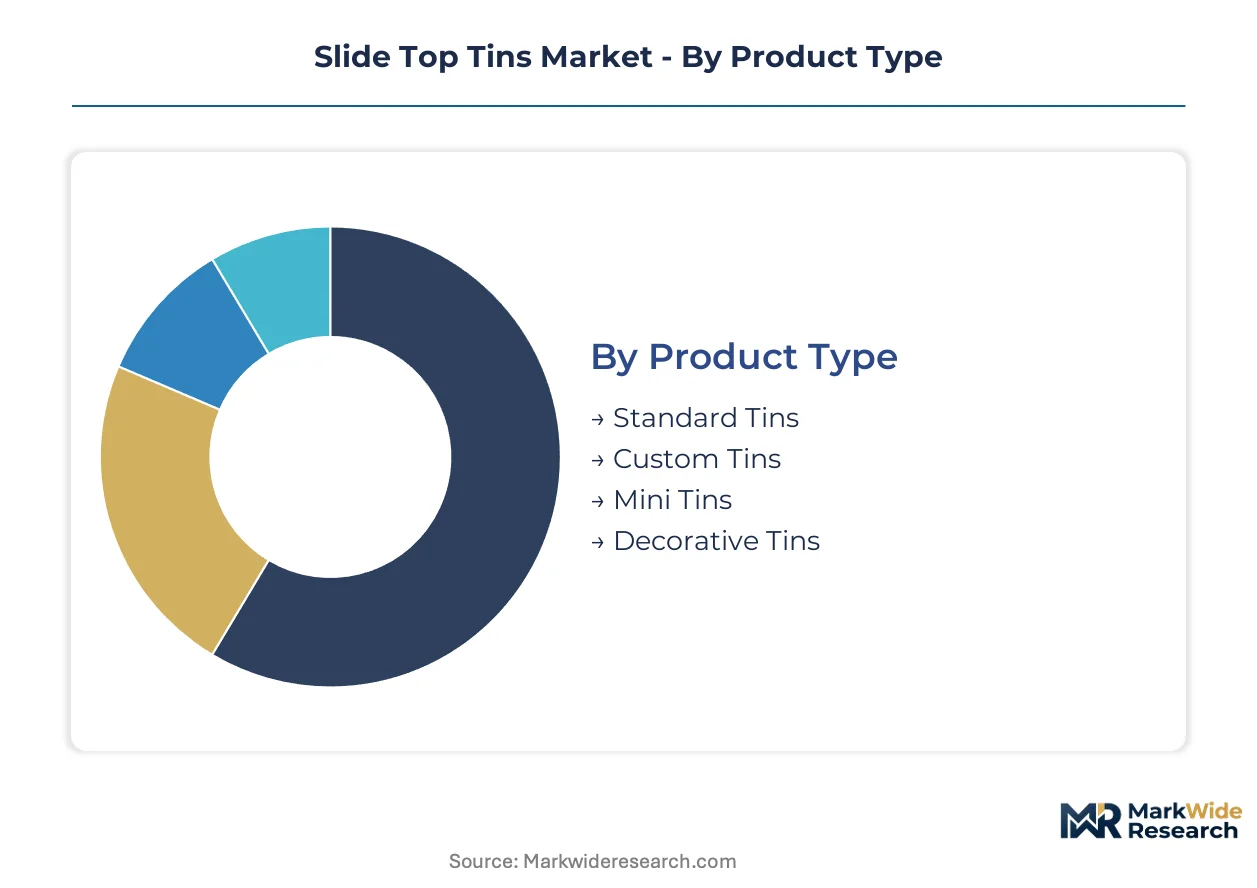
Segmentation in slide top tins reveals divergent margin profiles between commodity food service volumes and premium gift-channel positioning. Material chemistry and format dimensions directly determine recyclability scoring under EU Packaging and Packaging Waste Regulation compliance tiers.
Product Type:
Standard tins dominate tonnage throughput while custom and decorative variants extract premium pricing through lithographic differentiation.
- Standard Tins:These feature basic rectangular or cylindrical geometries with single-color offset printing and minimal embossing. German and French confectionery distributors specify standard tins for seasonal chocolate assortments where cost efficiency outweighs shelf differentiation.
- Custom Tins:Bespoke die-cut profiles and proprietary slide track geometries require deep tooling investments that few converters maintain. UK subscription coffee merchants rotate custom artwork quarterly to sustain direct-to-consumer engagement and justify recurring shipment economics.
- Mini Tins:Pocket-sized formats serve fragrance sampling and travel retail duty-free channels.
- Decorative Tins:Multi-pass lithography with metallic inks and tactile varnishes command gift-channel price premiums.
Today's leader: Standard Tins. Tomorrow's challenger: Custom Tins.
Material:
Weight-sensitive logistics corridors are accelerating aluminum displacement of traditional tinplate specifications.
- Aluminum:Alloy grades with enhanced formability reduce dimensional weight charges by 15-20 percent in e-commerce fulfillment networks. Netherlands-based premium chocolate shippers have adopted aluminum slide top tins to optimize last-mile economics without sacrificing premium unboxing experience.
- Tinplate:Mono-material tinplate constructions qualify for top-tier EU recyclability performance grades that influence retailer procurement decisions. Belgian and French specialty tea brands specify tinplate to eliminate plastic window films that downgrade recyclability scores.
- Plastic:Polymer alternatives persist in cost-constrained food service applications.
- Steel:Heavier substrate grades retain niche presence in industrial protective packaging.
Established incumbent: Tinplate. Expanding most quickly: Aluminum.
End User:
Food packaging absorbs the majority of volume while cosmetics and tobacco deliver superior unit economics.
- Food Packaging:Protective, reclosable storage for premium confectionery, specialty tea, and boutique coffee dominates order books. German chocolate brands and Scandinavian subscription roasters specify slide top tins for repeated access functionality that supports premium price positioning.
- Cosmetic Industry:Fragrance houses and skincare brands pilot pocket-sized formats for trial-size distribution. Travel retail duty-free channels in France and Belgium favor decorative mini tins for gift-set assembly.
- Tobacco Products:Traditional presence in loose-leaf and rolling paper storage.
- Pharmaceuticals:Limited adoption constrained by EFSA migration testing requirements for novel coating systems.
Volume anchor: Food Packaging. Margin leader: Cosmetic Industry.
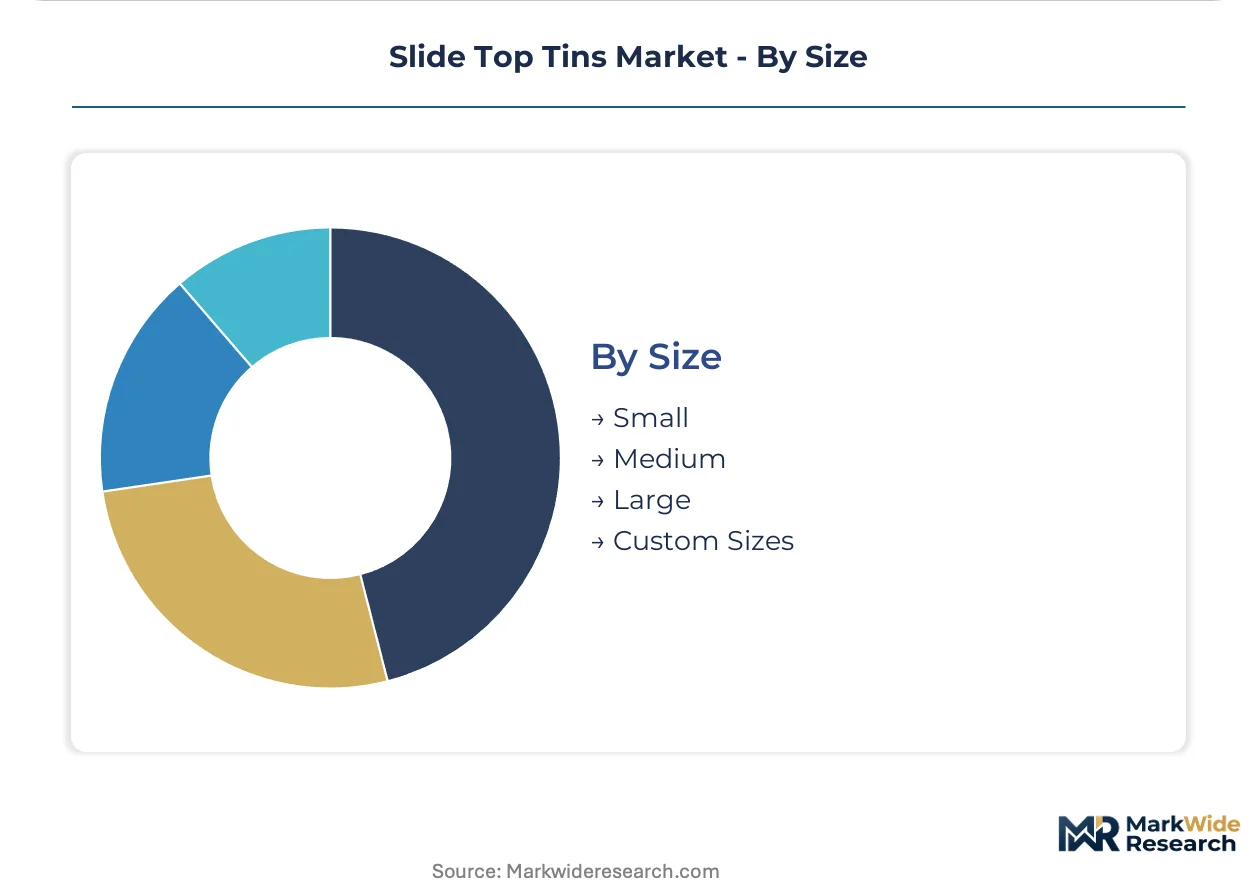
Size:
Format dimensions correlate directly with channel economics and shipping cost optimization.
- Small:Pocket-sized dimensions serve cosmetic sampling, travel retail, and subscription trial formats. UK fragrance merchants specify small slide top tins for direct-mail customer acquisition campaigns.
- Medium:Standard retail shelf formats balance display presence with logistics efficiency. French specialty tea brands favor medium tins for boutique roaster shelf differentiation.
- Large:Bulk storage and gift-set assembly formats.
- Custom Sizes:Non-standard dimensions for proprietary product geometries.
Current standard: Medium. Gaining share fastest: Small.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Slide top tin manufacturing traces its commercial lineage to 19th-century British metalworking centers, where lithographed tinplate containers first served confectionery and tobacco merchants. Contemporary production networks retain this European heritage while dispersing fabrication capacity across three continents.
Germany
Premium chocolate brands in Cologne and Hamburg have expanded slide top tin orders for seasonal gift collections, driving demand for decorative embossing and metallic lithography. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility that favors mono-material tinplate constructions over multi-layer alternatives. The Ruhr industrial corridor hosts specialized press configurations capable of custom slide track geometries.
France
Specialty tea merchants in Paris and Lyon specify slide top tins for boutique shelf differentiation and reusable consumer storage. EFSA migration limits govern direct food contact materials, constraining coating chemistries and surface treatments. The Île-de-France region concentrates decorative finishing capabilities that command gift-channel price premiums.
United Kingdom
Subscription coffee roasters in London and Manchester rotate custom tin artwork quarterly to sustain direct-to-consumer engagement. REACH compliance requirements force reformulation investments for epoxy-based internal lacquers. The Midlands manufacturing belt anchors deep tooling capabilities for proprietary slide track formats.
Netherlands
E-commerce fulfillment operators have adopted aluminum slide top tins for premium chocolate shipments, cutting dimensional weight charges by fifteen to twenty percent. The EU Green Deal broadens compliance obligations for reusable and recyclable packaging across consumer goods supply chains. Rotterdam logistics corridors favor lightweight aluminum specifications for last-mile optimization.
China
Dongguan and Qingyuan manufacturing clusters supply global demand for standard and custom slide top tin formats across food and cosmetic applications. The country's national packaging regulator enforces food contact material standards aligned with international migration limits. Pearl River Delta fabricators leverage scale economies for high-volume confectionery and tea packaging contracts.
Slide Top Tins Market Competitive Landscape
Premium-margin players sit above commodity-margin players across lithographic differentiation and custom tooling depth. The vendor base organizes into three tiers: multinational metal packaging conglomerates with continental manufacturing footprints, mid-scale regional specialists with decorative finishing capabilities, and volume-focused contract fabricators serving standardized specifications. Strategic archetypes include vertical integrators controlling substrate supply, design-forward converters capturing gift-channel premiums, and logistics-optimized producers favoring aluminum alloys. Dominant competitive moves encompass backward integration into tinplate sourcing and geographic expansion through distributor partnerships.
Among North American fabricators, Allstate Can anchors production with press configurations for custom formats, while Crown Holdings, Inc. leverages its continental manufacturing footprint to serve beverage-to-tin crossover demand. TinWerks Packaging represents the design-forward archetype, occupying a position where decorative finishes command premium positioning in gift-oriented channels. These three exemplify how geographic origin and stated specialization map to distinct margin tiers within the competitive structure.
| Leading Market Players |
|---|
| Allstate Can |
| TinWerks Packaging |
| Qingyuan Max Tin Cans Manufacturing |
| Yum Tin |
| Dongguan Tinpak |
| Independent Can |
| Dongguan City Xin Yu Tin Can Manufactory |
| Tin-Pac Promotional Packaging |
| Crown Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
The EU Packaging and Packaging Waste Regulation gates qualified supply and premium-tier pricing access by mandating extended producer responsibility and recyclability performance grades that disqualify non-compliant converters. Mono-material tinplate constructions command pricing premiums as Belgian and French specialty tea brands reformulate specifications to eliminate plastic window films and secure top-tier labeling that influences retailer procurement decisions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by lithographic complexity and tooling depth. Premium tiers extract margins through custom embossing and metallic finishes for German chocolate gift collections, while standard tiers compete on tinplate substrate efficiency for seasonal volume orders. Cost compression in economy tiers intensifies as aluminum substitution pressures tinplate specifications in Netherlands e-commerce fulfillment networks. Food service distributors exhibit highest price sensitivity, whereas direct-to-consumer subscription brands absorb premiums for quarterly artwork rotation.
Supply Chain Analysis
Regional distribution centers in the Ruhr industrial corridor and Pearl River Delta maintain hub-and-spoke patterns for press configurations and decorative finishing capabilities. Manufacturing concentrates in Germany, China, and the Netherlands, with Dongguan clusters supplying high-volume confectionery contracts and Hamburg facilities serving custom track geometries. Raw material flows draw from steel substrate smelters, aluminum alloy formulators, and epoxy lacquer chemistries constrained by REACH notification backlogs. Single-source vulnerability persists for deep tooling press configurations capable of proprietary slide track precision. Distribution runs through Rotterdam logistics corridors for last-mile aluminum optimization and Midlands belt fabrication networks for bespoke UK formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The slide top tins market functions as a regulatory compounder where EU Green Deal mandates on minimum recycled content thresholds and extended producer responsibility create structural demand for compliant mono-material constructions.
For Market Incumbents: Acquire certified scrap supply chains to secure first-mover positioning ahead of forthcoming EU delegated acts on post-consumer metal content. Crown Holdings and Allstate Can should anchor backward integration into tinplate sourcing to defend margin position against aluminum substitution in weight-sensitive logistics corridors. Deepen decorative finishing capabilities in Île-de-France and Midlands clusters to capture gift-channel premiums from fragmenting direct-to-consumer order patterns.
For New Entrants and Emerging Players: Enter via cosmetic sampling mini formats for fragrance houses and skincare brands piloting pocket-sized slide top tins for trial-size distribution and duty-free channel assembly. Target UK and Scandinavian subscription coffee merchants rotating quarterly artwork, where 5,000-unit batch economics bypass traditional food service distributor concentration. Position through platform-native brand partnerships that prioritize unboxing experience over legacy wholesale relationships.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional specialists with decorative lithography capabilities because buyer concentration among direct-to-consumer brands fragments order patterns toward smaller runs with faster turnaround. Long-term viability hinges on converters with EFSA pre-approved coating systems that avoid migration testing backlogs. Watch ECHA reformulation timelines for epoxy-based internal lacquers as the inflection signal for specification freeze risk and launch delay exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tinplate Sourcing | Captive steel substrate supply insulates Crown Holdings from energy-intensive smelting price spikes. |
| Aluminum Alloy Formulation Investment | Enhanced formability grades cut Netherlands e-commerce dimensional weight charges for premium chocolate shippers. |
| EFSA Pre-Approved Coating Certification | Novel lacquer systems with completed migration testing avoid extended approval timelines freezing specifications. |
| Direct-to-Consumer Subscription Channel Launch | Quarterly artwork rotation builds retention through packaging permanence for UK coffee merchants. |
| Decorative Finishing Capability Expansion | Multi-pass lithography with metallic inks commands gift-channel price premiums in Paris and Lyon boutiques. |
Research Methodology
Direct dialogue with tinplate converter operations managers, specialty tea brand procurement leads, confectionery packaging designers, REACH compliance consultants, and e-commerce fulfillment operators grounded qualitative findings. Secondary validation drew from EFSA migration limit databases, ECHA restriction proposals, EU Packaging and Packaging Waste Regulation delegated act drafts, and customs records for steel substrate trade flows. Bottom-up unit economics for press configuration utilization and top-down market sizing across material grades and end-use segments were triangulated to constrain estimate variance.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, material chemistry, end-use application, and format dimensions. The analytical framework incorporated recyclability performance grade thresholds, coating chemistry compliance tiers, and channel-specific batch size economics. CAGRs were derived from elasticity-adjusted demand curves for premium confectionery gift packaging and aluminum substitution rates in logistics corridors. Industry-specific forecast inputs included EMA and EFSA regulatory timelines and direct-to-consumer subscription penetration assumptions.
Inputs from EFSA notification databases and converter capacity utilization surveys were available through the study window; gaps in forthcoming EU delegated act implementation schedules introduce uncertainty bands around minimum recycled content threshold assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Modular Container Market
Containers
North America Plastic Bottles and Containers Market
Containers
Wire Containers Market
Containers
Metal Cans and Glass Jars Market
Containers
Wooden Barrels Market
Containers
Hinged Deli Containers Market
Containers
Container Fixed Fittings Market
Containers
Global Multi Pack Carriers Market
Containers
PET Hinged Containers Market
Containers
Dispensing Jug Market
Containers
Foldable Container Market
Containers
Container Market
Containers
Foam Containers Market
Containers
Stainless Steel Cask Market
Containers
Car Lube Container Market
Containers
Compartment Trays Market