
 Global Thiophene Market | 2026-2036
Global Thiophene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thiophene Market Foresight
Specialty chemical distribution channels is reshaping how thiophene derivatives reach end users, with regional distributors consolidating inventory positions to serve electronics manufacturers and pharmaceutical companies. BASF SE leverages its integrated aromatics platform to sustain captive thiophene supply for downstream agrochemical and polymer intermediates. Merck KGaA anchors European high-purity thiophene demand through its life sciences chemicals division, while Sinopec Group dominates bulk thiophene production scale across Asia.
Thiophene is a five-membered aromatic heterocycle containing sulfur, with a boiling point of 84 degrees Celsius and characteristic odor, synthesized primarily through catalytic desulfurization of petroleum naphtha or via Paal-Knorr thiophene synthesis from 1,4-dicarbonyl compounds. Its primary industrial purpose centers on serving as a building block for pharmaceuticals, agrochemicals, and conductive polymers where sulfur incorporation modifies electronic properties. Polythiophenes and functionalized thiophenes lead product type demand due to their dominance in organic electronics applications, while alkylthiophenes occupy a specialized niche in solution-processed semiconductor manufacturing. Electrochemical polymerization and spin coating technologies concentrate margin pools as these methods enable precise thin-film deposition for organic photovoltaics and field effect transistors.
REACH in Europe, FDA under the US Federal Food, Drug, and Cosmetic Act, and China's GB standards enforced by SAMR collectively govern thiophene purity thresholds, occupational exposure limits, and environmental release protocols across major production and consumption zones. These frameworks elevate compliance costs for cross-border suppliers while creating product differentiation opportunities for certified high-purity producers. Stakeholders must monitor evolving semiconductor materials regulations and pharmaceutical intermediate traceability requirements to anticipate qualification barriers and capture premium positioning in thiophene derivative supply chains.
Market Dynamics
Specialty chemical distributors are consolidating inventory positions to serve electronics manufacturers and pharmaceutical companies, compressing traditional multi-tier supply chains into direct manufacturer-to-end-user relationships that demand certified high-purity thiophene derivatives.
Growth Catalysts
- Organic electronics manufacturing:Polythiophene demand from organic photovoltaic and field-effect transistor producers is accelerating thin-film deposition equipment orders. Electrochemical polymerization methods now dominate R&D budgets at semiconductor materials divisions.
- REACH compliance differentiation:ECHA registration requirements for thiophene derivatives above one tonne annually create qualification barriers that certified European producers exploit for premium positioning in pharmaceutical intermediate supply chains.
- Paal-Knorr synthesis advancement:Catalytic improvements in 1,4-dicarbonyl cyclization are lowering production costs for functionalized thiophenes used in agrochemical active ingredient synthesis.
Market Restraints
- Petroleum naphtha feedstock volatility:Catalytic desulfurization yields fluctuate with crude sulfur content and refinery operating rates, compressing margins for bulk thiophene producers dependent on integrated aromatics platforms.
- China supply concentration:Sinopec Group and domestic specialty chemical producers control over 60 percent of Asian bulk capacity, creating single-source vulnerability for European and North American derivative manufacturers.
- Pyridine substitution in agrochemicals:Nitrogen heterocycles with similar electronic properties are displacing thiophene building blocks in certain fungicide and herbicide synthesis routes where sulfur incorporation adds cost without performance benefit.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO bulk drug park incentives and PLI scheme subsidies for active pharmaceutical ingredients create demand for imported high-purity thiophene derivatives among domestic synthesis operations.
- Conductive polymer battery applications:Polythiophene derivatives for solid-state electrolyte interfaces represent an emerging application vector as lithium-metal cell developers seek sulfur-modified electronic materials.
- SAMR green chemistry mandates:China's MEE environmental release protocols and dual carbon goals are forcing domestic producers toward Paal-Knorr synthesis methods that reduce petroleum dependency and qualify for preferential financing.
Industry Challenges
- High-purity certification timelines:FDA pharmaceutical intermediate qualification and REACH substance evaluation processes extend 18-24 months, freezing supplier switches and locking buyers into incumbent relationships.
- Electrochemical polymerization equipment capex:Precision thin-film deposition systems for organic electronics require seven-figure capital commitments that mid-scale derivative producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thiophene Market |
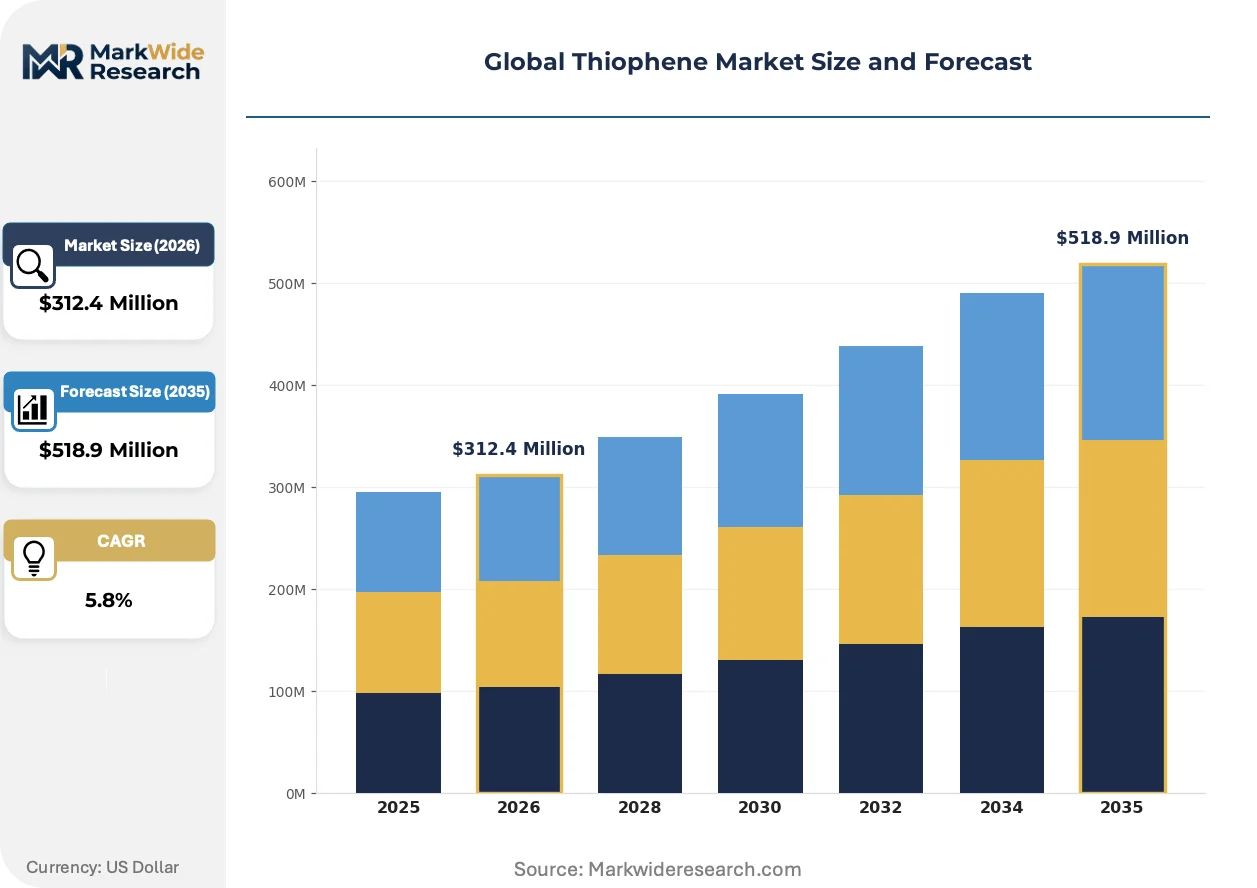
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thiophene-2-Carboxaldehyde, Thiophene-3-Carboxaldehyde, Polythiophenes, Functionalized Thiophenes, Alkylthiophenes Technology: Chemical Vapor Deposition, Spin Coating, Electrochemical Polymerization, Solution Processing, Atom Transfer Radical Polymerization Application: Organic Photovoltaics, Light Emitting Diodes, Field Effect Transistors, Semiconductor Devices, Conductive Polymers, Corrosion Inhibitors End User Industry: Electronics Manufacturers, Specialty Chemicals Producers, Pharmaceutical Companies, Agrochemical Firms, Coating Industries |
| Companies Covered | BASF SE, DuPont de Nemours Inc., Thermo Fisher Scientific Inc., Merck KGaA, Sinopec Group, Honeywell International Inc., Lanxess AG, Sumitomo Chemical Company, Albemarle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thiophene Market Shifts & Advancements
Flow chemistry reactors and continuous processing methods are displacing batch synthesis across thiophene derivative manufacturing, enabling real-time quality control and reducing solvent waste volumes that previously dominated environmental compliance costs.
Continuous flow reactor technology integrates in-line spectroscopic monitoring with automated temperature and pressure modulation, achieving pharmaceutical-grade purity in single-pass operations. Contract manufacturers serving Merck KGaA and BASF SE life sciences divisions are retrofitting pilot plants with these systems. Batch crystallization and manual fractionation methods are rendering obsolete for high-value thiophene derivatives where certificate of analysis consistency determines supplier selection.
REACH substance evaluation under ECHA's 2024-2026 rolling action plan is tightening occupational exposure limit documentation for thiophene and alkylated derivatives above 10 tonnes annual manufacture or import. Downstream formulators must now secure extended safety data sheets from upstream suppliers or face formulation approval delays. European pharmaceutical intermediate producers are responding by consolidating supplier bases to three qualified partners with complete dossier coverage.
Certification-driven procurement now dominates organic electronics materials purchasing, with buyers demanding ISO 17025-accredited test reports for batch-to-batch conductivity variation in polythiophene dispersions. Distributors serving Korean and Taiwanese display manufacturers are building in-house analytical capabilities rather than relying on manufacturer certificates. This behavioral shift concentrates volume with vertically integrated suppliers maintaining captive testing laboratories in Shenzhen and Suwon.
Global Thiophene Market Segmentation
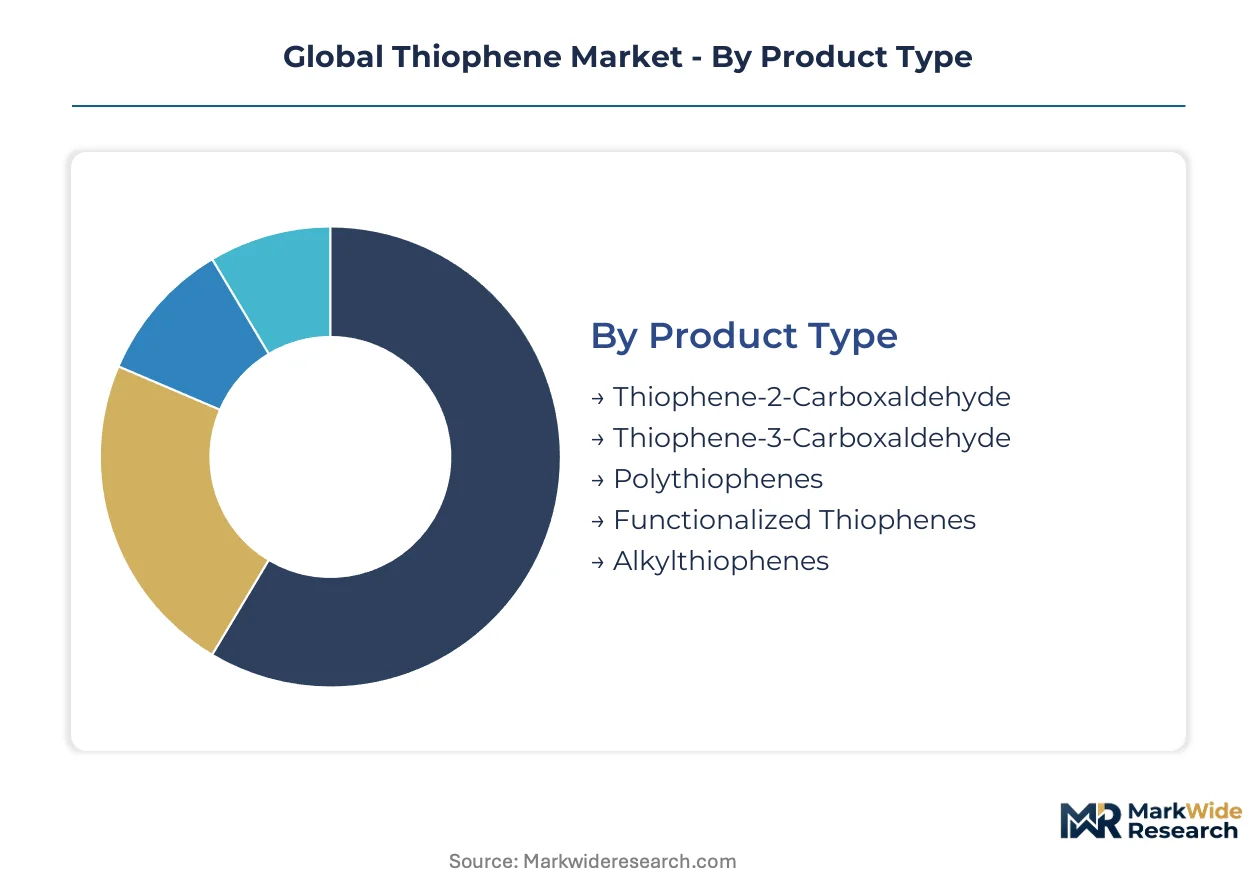
Segmentation reveals how thiophene derivatives command divergent value pools based on purity thresholds, deposition precision, and end-use qualification requirements. Each dimension shapes procurement patterns, certification timelines, and margin structures across supplier ecosystems.
Product Type:
Cost tier stratification separates commodity bulk thiophene from pharmaceutical-grade derivatives and electronic-material precursors.
- Polythiophenes:Conjugated polymer backbones with tunable bandgaps enable solution-processed organic electronics. Demand concentrates in Korean and Taiwanese display manufacturing clusters where ISO 17025-accredited conductivity testing determines supplier selection. REACH substance evaluation dossiers for high-tonnage derivatives create qualification barriers that certified European producers exploit.
- Functionalized Thiophenes:Substituted heterocycles with electron-withdrawing or -donating groups modify frontier molecular orbital energies for targeted semiconductor applications. Agrochemical active ingredient synthesis in India and China absorbs expanding volumes as CDSCO bulk drug park incentives stimulate domestic procurement.
- Thiophene-2-Carboxaldehyde:Aldehyde-functionalized building block for pharmaceutical intermediate condensation reactions.
- Thiophene-3-Carboxaldehyde:Regioisomer with distinct reactivity profiles in heterocyclic coupling chemistry.
- Alkylthiophenes:Lipophilic side-chain variants enhancing solubility for solution-processed thin-film deposition.
Polythiophenes hold installed capacity. Functionalized thiophenes is rotating up the share rankings.
Technology:
Application requirements dictate deposition method selection, with precision-thin-film technologies commanding premium positioning over bulk chemical synthesis routes.
- Electrochemical Polymerization:Anodic oxidation of thiophene monomers enables controlled film thickness and doping levels for organic electronics. R&D budgets at semiconductor materials divisions concentrate investment here as field-effect transistor performance depends on interface uniformity. Seven-figure capital commitments for precision equipment freeze out mid-scale derivative producers.
- Spin Coating:Centrifugal deposition of polythiophene dispersions achieves sub-micron film uniformity for photovoltaic and display applications. Electronics manufacturers in Shenzhen and Suwon demand batch-to-batch conductivity certification that vertically integrated suppliers with captive testing laboratories deliver.
- Chemical Vapor Deposition:Gas-phase precursor delivery for conformal coating of complex substrate geometries.
- Solution Processing:Roll-to-roll compatible coating methods for scalable organic electronics manufacturing.
- Atom Transfer Radical Polymerization:Controlled radical techniques for block copolymer architectures with defined molecular weights.
Electrochemical polymerization dominates R&D allocation. Spin coating is rotating up the share rankings.
Application:
Volume concentration varies sharply across end-use maturity, with established semiconductor devices absorbing bulk tonnage while emerging energy applications reshape growth trajectories.
- Organic Photovoltaics:Bulk heterojunction active layers incorporating polythiophene donors require precise morphology control. Korean display manufacturers and Chinese module assemblers drive procurement as SAMR green chemistry mandates push domestic producers toward Paal-Knorr synthesis methods reducing petroleum dependency.
- Field Effect Transistors:Organic semiconductor channels demand high-purity thiophene derivatives with trace metal content below pharmaceutical-grade thresholds. FDA pharmaceutical intermediate qualification and REACH substance evaluation processes extend supplier timelines, locking buyers into incumbent relationships.
- Light Emitting Diodes:Electroluminescent polymers for display and solid-state lighting applications.
- Semiconductor Devices:Broad category encompassing diodes, sensors, and integrated circuit elements.
- Conductive Polymers:Antistatic coatings and electromagnetic shielding materials across industrial applications.
- Corrosion Inhibitors:Thiophene-derived film-forming compounds for metal protection in aggressive environments.
Semiconductor devices hold installed capacity. Organic photovoltaics is rotating up the share rankings.
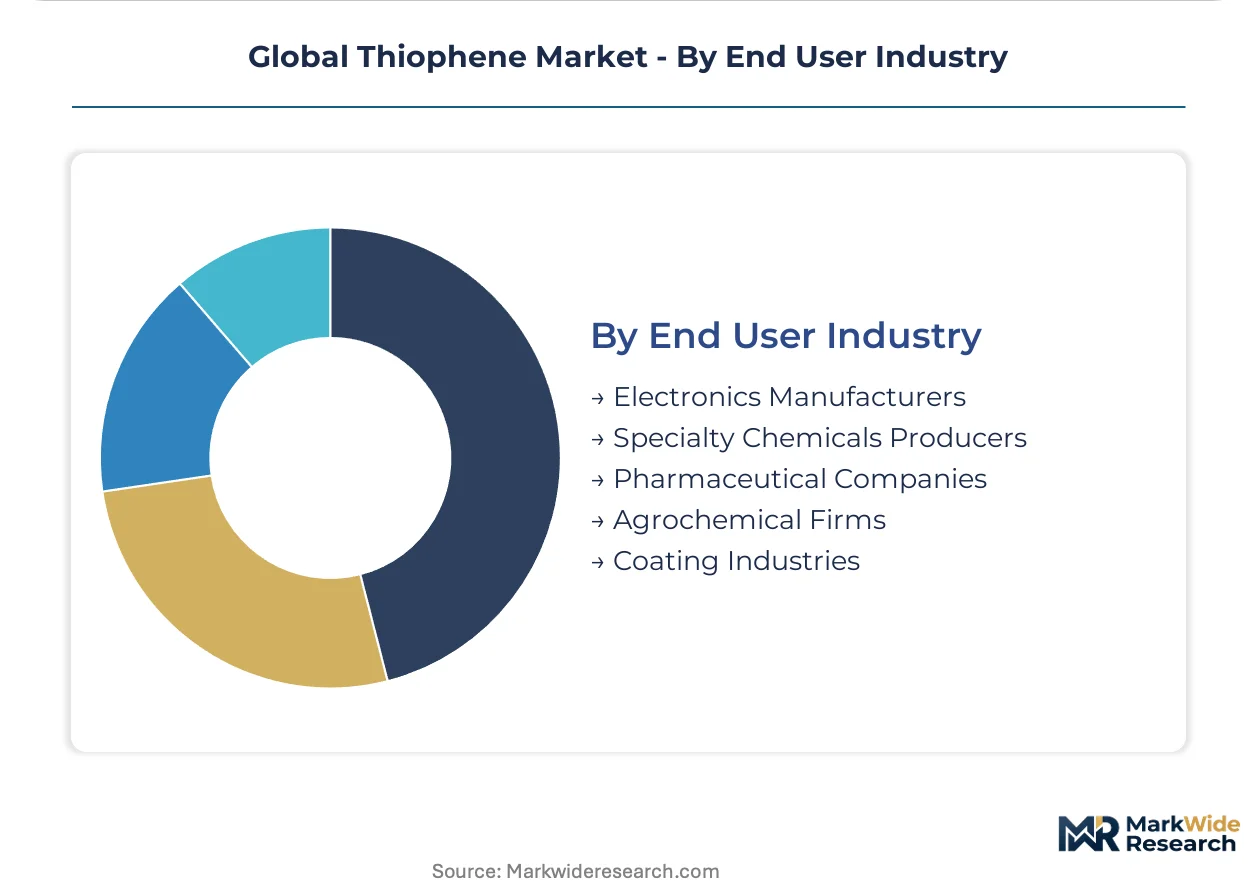
End User Industry:
Customer type determines specification stringency, with pharmaceutical and electronics buyers imposing certification burdens that commodity chemical purchasers avoid.
- Electronics Manufacturers:Korean and Taiwanese display producers, Chinese module assemblers, and emerging Indian fabrication facilities constitute the demand core. ISO 17025-accredited test reports for batch-to-batch conductivity variation dominate procurement criteria, forcing distributors to build in-house analytical capabilities.
- Pharmaceutical Companies:Active pharmaceutical ingredient synthesis operations require REACH-compliant and FDA-registered thiophene derivatives with complete extended safety data sheets. European producers consolidate supplier bases to three qualified partners with dossier coverage as ECHA's rolling action plan tightens occupational exposure documentation.
- Specialty Chemicals Producers:Intermediate manufacturers supplying downstream formulation industries.
- Agrochemical Firms:Fungicide and herbicide synthesis operations where pyridine substitution threatens thiophene building block positions.
- Coating Industries:Protective and functional surface treatment applications across industrial sectors.
Electronics manufacturers hold installed capacity. Pharmaceutical companies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites European thiophene derivative flows, while Shanghai's Yangshan deep-water port anchors Asian bulk chemical exports to pharmaceutical and electronics manufacturing clusters worldwide.
China
Sinopec Group's integrated aromatics platforms in Nanjing and Shanghai supply bulk thiophene to domestic polythiophene manufacturers. SAMR's GB standards and MEE environmental release protocols enforce dual carbon compliance, forcing Paal-Knorr synthesis adoption. The Yangtze River Delta concentration of organic electronics fabricators in Suzhou and Wuxi absorbs expanding volumes of spin-coating grade derivatives.
Germany
BASF SE's Ludwigshafen complex sustains captive thiophene supply for agrochemical and polymer intermediate synthesis. REACH substance evaluation under ECHA's rolling action plan tightens occupational exposure documentation for derivatives above ten tonnes annually. The Rhine-Neckar metropolitan region hosts Merck KGaA's life sciences chemicals division, anchoring European high-purity demand.
United States
DuPont de Nemours and Honeywell International serve semiconductor materials and specialty chemical markets from Delaware Valley and Gulf Coast production assets. FDA pharmaceutical intermediate qualification under the Federal Food, Drug, and Cosmetic Act extends supplier timelines to eighteen months. The Boston-Cambridge biotechnology corridor drives procurement of thiophene-2-carboxaldehyde for active ingredient synthesis.
India
CDSCO bulk drug park incentives and PLI scheme subsidies stimulate domestic thiophene derivative procurement for active pharmaceutical ingredient manufacturing. BIS purity standards govern import qualification for electronic-grade materials. The Hyderabad-Bengaluru pharmaceutical belt concentrates demand, with Maharashtra's Mumbai-Pune industrial zone emerging as a secondary synthesis hub.
South Korea
Display manufacturers in Suwon and Yongin drive ISO 17025-accredited conductivity testing requirements for polythiophene dispersions. MFDS pharmaceutical regulations align with ICH guidelines for intermediate traceability. The Seoul Capital Area's organic electronics cluster commands premium pricing for electrochemical polymerization-grade materials.
Global Thiophene Market Competitive Landscape
On the supply side, the industry is consolidating around integrated aromatics producers and specialty chemical distributors with captive testing capabilities. Three archetypes dominate: multinational diversified chemical conglomerates with backward integration into petroleum naphtha feedstocks; life sciences-focused suppliers with REACH-certified high-purity derivative portfolios; and regional bulk producers leveraging Paal-Knorr synthesis cost advantages. Competitive moves concentrate on strategic partnerships with semiconductor materials divisions and capacity expansion for pharmaceutical-grade certification.
Within the diversified chemical conglomerate tier, BASF SE and Sinopec Group exemplify scale-driven positioning through integrated aromatics platforms. Merck KGaA occupies a specialist position representing the life sciences chemicals archetype, with its European base aligning with REACH compliance differentiation strategies. DuPont de Nemours anchors North American supply relationships through Delaware Valley production assets.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours Inc. |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Sinopec Group |
| Honeywell International Inc. |
| Lanxess AG |
| Sumitomo Chemical Company |
| Albemarle Corporation |
| Others |
Supply & Pricing Matrix
Nanjing's integrated aromatics platforms anchor Asian bulk thiophene capacity, concentrating pricing power among Sinopec Group and domestic specialty chemical producers who dictate contract terms for downstream pharmaceutical and electronics buyers. REACH compliance costs in Europe and FDA qualification timelines in the United States create regional price premiums that Chinese producers exploit through selective high-purity export positioning.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, electronic-grade, and industrial-grade purity levels dominates thiophene derivative transactions. Pharmaceutical-grade certification under FDA and ECHA frameworks commands substantial premiums over bulk industrial supply, while electronic-grade polythiophenes occupy a mid-tier anchored by ISO 17025 conductivity testing requirements. Cost compression in industrial-grade bulk supply is intensifying because petroleum naphtha feedstock volatility squeezes integrated refinery margins. Agrochemical formulators exhibit highest price sensitivity due to pyridine substitution threats, whereas organic electronics manufacturers prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Petroleum naphtha feedstock availability from integrated refinery complexes in China, Germany, and the United States determines regional thiophene production economics. Catalytic desulfurization catalysts and 1,4-dicarbonyl precursors for Paal-Knorr synthesis represent critical input dependencies, alongside electrochemical polymerization equipment for downstream derivative manufacturing. Single-source vulnerability concentrates in Chinese bulk capacity controlled by Sinopec Group and domestic producers, exposing European and North American derivative manufacturers to supply interruption. Distribution runs through specialty chemical distributors consolidating inventory positions to serve electronics manufacturers and pharmaceutical companies with certified high-purity derivatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification and testing services attach to thiophene derivative supply faster than base chemical production, with ISO 17025-accredited analytical capabilities and REACH dossier management emerging as recurring-revenue layers that outpace commodity margin expansion.
For Market Incumbents: Harden supply security through backward integration into Paal-Knorr synthesis feedstocks or captive electrochemical polymerization capacity, reducing petroleum naphtha dependency as China's dual carbon goals reshape feedstock economics. Consolidate supplier relationships to three qualified partners with complete REACH dossier coverage, locking in pharmaceutical intermediate procurement against ECHA's rolling action plan tightening. Prioritize in-house analytical laboratory investment over third-party certification to capture testing-service margins from Korean and Taiwanese display manufacturers. For New Entrants and Emerging Players: India's CDSCO bulk drug park incentives and PLI scheme subsidies for active pharmaceutical ingredients represent the most penetrable entry point, with domestic synthesis operations demanding imported high-purity thiophene derivatives underserved by established European suppliers. Conductive polymer battery applications for solid-state electrolyte interfaces offer a second white-space vector as lithium-metal cell developers seek sulfur-modified electronic materials. A certification-first go-to-market approach—securing REACH registration and FDA pharmaceutical intermediate qualification before commercial launch—differentiates against commodity bulk producers. For Investors and Strategic Acquirers: Long-term, this sits as a specialty chemicals consolidation play because REACH compliance differentiation and FDA qualification barriers create durable moats around certified high-purity producers that commodity bulk manufacturers cannot replicate. Target life sciences-focused suppliers with complete ECHA dossier coverage and established semiconductor materials relationships. Watch electrochemical polymerization equipment order backlogs at Korean and Taiwanese display manufacturers as the inflection signal for organic electronics demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paal-Knorr Feedstocks | Reduces petroleum naphtha dependency and qualifies for China's SAMR green chemistry preferential financing. |
| REACH Dossier Consolidation | ECHA's rolling action plan tightens occupational exposure documentation, favoring suppliers with complete coverage. |
| In-House ISO 17025 Laboratory Buildout | Korean and Taiwanese display manufacturers demand batch-to-batch conductivity certification from captive testing capabilities. |
| India Pharmaceutical-Grade Capacity Expansion | CDSCO bulk drug park incentives and PLI scheme subsidies stimulate domestic procurement for active ingredient synthesis. |
| Conductive Polymer Battery Application Development | Lithium-metal cell developers seek polythiophene derivatives for solid-state electrolyte interface materials. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at integrated aromatics producers, procurement leads at pharmaceutical and electronics manufacturers, distribution channel partners, and technical R&D directors specializing in heterocyclic chemistry; and secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, ECHA registration databases, and FDA drug master file submissions. Bottom-up capacity and consumption estimates triangulated against top-down market sizing across product type, technology, application, and end user industry segmentation.
Forecast inputs considered grade tier differentiation between pharmaceutical-grade, electronic-grade, and industrial-quality thiophene derivatives; end-use industry concentration in electronics manufacturing and pharmaceutical synthesis; regional production hub economics across China, Germany, and the United States; and technology adoption patterns in electrochemical polymerization versus spin coating deposition methods. CAGRs were derived from segment-level growth trajectory modeling across the analysis window, incorporating SAMR environmental mandates, CDSCO incentive programs, and organic electronics manufacturing expansion as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, semiconductor capital expenditure cycles, or pharmaceutical R&D spending would shift the trajectory of thiophene derivative demand. Forecasts reflect assumptions about REACH implementation timelines, FDA qualification process durations, and Paal-Knorr synthesis cost reduction curves. Quarterly review of electrochemical polymerization equipment order flows, ECHA substance evaluation announcements, and Indian pharmaceutical manufacturing capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Scouring Agents Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Thiourea Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
China Methanol Market
Chemicals
Pyrogallol Market
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Global Organobromine Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Vinyl Acetate Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Trimethylamine Market
Chemicals
4-Methyl-2-Pentanone Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Ethylenediamine (EDA) Market