
 Sulfuric Acid Market | 2026-2036
Sulfuric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfuric Acid Market Analysis
Chinese copper smelter expansions is repositioning merchant acid availability across the Pacific Rim. The Mosaic Company leverages captive phosphate rock integration to sustain margin capture in fertilizer-grade output. Jiangxi Copper Corporation anchors regional supply through smelter-linked acid production in southern China. BASF SE differentiates via specialized industrial-grade formulations for European chemical manufacturing.
Sulfuric acid is a highly corrosive mineral acid with the formula H₂SO₄, typically produced through the contact process using sulfur dioxide oxidation over vanadium pentoxide catalysts; its primary industrial purpose centers on phosphate fertilizer manufacturing, metal ore leaching, and petroleum alkylation. Industrial-grade formulations dominate volume flows into fertilizer and petrochemical applications, where margin pools remain tied to sulfur feedstock cost volatility. Battery-grade sulfuric acid represents the fastest-expanding quality tier, driven by lead-acid battery demand and emerging traction in lithium extraction processing.
EPA enforcement of Risk Management Plan requirements shapes US acid storage and transport infrastructure investment, while China's MEE sulfur recovery mandates tighten smelter emissions thresholds and linked acid output. REACH registration obligations in Europe constrain import pathways for non-EU producers seeking chemical sector placement. Stakeholders must monitor evolving battery-grade purity specifications and regional sulfur feedstock availability to align capacity decisions with shifting demand composition.
Market Dynamics
China's dual carbon goals are forcing smelter-linked acid producers to reconfigure sulfur recovery systems, tightening Pacific Rim merchant supply and concentrating bargaining power with phosphate processors in Brazil and Southeast Asia.
Growth Catalysts
- Phosphate Fertilizer Expansion:Brazilian and Indonesian fertilizer producers are scaling wet-process phosphoric acid capacity, pulling sulfuric acid offtake volumes upward as agricultural input demand intensifies across tropical cultivation zones.
- Battery-Grade Purity Mandates:South Korean and Japanese cathode active material plants are imposing stricter metal-ion specifications on acid suppliers, creating specification premiums that reward purification technology investments.
- REACH Registration Pathways:European chemical manufacturers seeking non-EU acid sources must navigate ECHA compliance obligations, advantaging registered producers with established dossier portfolios in Rotterdam and Antwerp trading hubs.
Market Restraints
- Sulfur Feedstock Volatility:Refinery-derived elemental sulfur pricing swings directly compress acid producer margins, particularly for non-integrated merchant operators lacking captive smelter gas sources.
- Chinese Supply Concentration:Jiangxi and Anhui province smelters control disproportionate regional acid output, creating single-source dependency risks for Southeast Asian phosphate buyers during maintenance turnarounds.
- Alkylation Substitution Pressure:Solid acid catalyst technologies for petroleum refining are displacing liquid acid alkylation units at select North American refineries, eroding a traditional volume anchor.
Strategic Opportunities
- Lithium Extraction Processing:Direct lithium extraction facilities in Chile's Atacama and Argentina's Cauchari-Olaroz are specifying high-purity acid for brine processing, opening premium-grade demand outside traditional battery applications.
- EPA Risk Management Plan Incentives:US storage infrastructure upgrades triggered by enforcement actions are creating contract opportunities for engineering firms capable of delivering compliant tankage and vapor recovery systems.
- Dual-Use Purification Systems:Membrane and crystallization technologies originally developed for semiconductor-grade chemicals are integrating into acid plants, enabling multi-product output flexibility across industrial and battery specifications.
Industry Challenges
- Corrosion Engineering Talent Scarcity:Acid plant operators face acute shortages of materials specialists capable of specifying alloys for concentrated acid service at elevated temperatures, extending project timelines.
- Legacy Control System Integration:Smelter-linked acid producers attempting to retrofit digital monitoring for sulfur recovery compliance encounter protocol incompatibilities between 1990s-era distributed control systems and modern emissions analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfuric Acid Market |
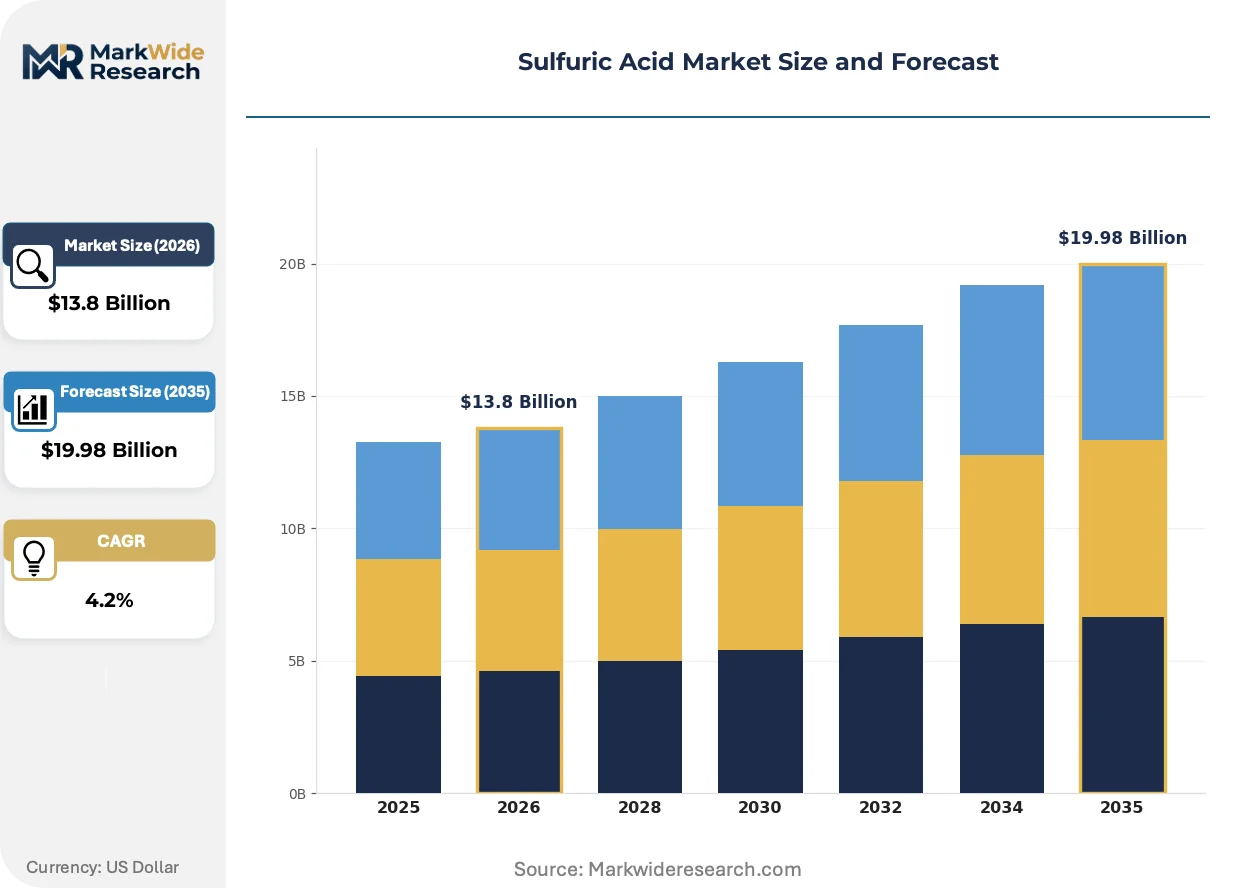
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $19.98 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Grade, Industrial Grade, Battery Grade, Reagent Grade Application: Fertilizers, Petrochemicals, Metal Processing, Water Treatment End User: Agriculture, Oil & Gas, Mining, Manufacturing Distribution Channel: Direct Sales, Wholesale, Online Sales, Retail |
| Companies Covered | The Mosaic Company, Aurubis AG, PhosAgro Group, OCP Group, BASF SE, Jiangxi Copper Corporation, Chemtrade Logistics Inc., Boliden Group, PVS Chemicals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfuric Acid Market Emerging Trajectories
Process intensification and purity specification escalation are compressing traditional acid production economics while rewarding technology differentiation across fertilizer, chemical, and battery supply chains.
Membrane electrolysis for acid regeneration is integrating into spent acid recovery circuits at metal finishing and pickling operations. European steel processors are piloting closed-loop systems that convert waste acid back to virgin concentration. This technology is integrating merchant acid suppliers into circular service contracts that displace conventional product sales with tolling arrangements.
China's MEE sulfur recovery mandates are tightening smelter emissions thresholds and linked acid output quotas. Southern Chinese copper producers must invest in double-contact absorption upgrades or face production caps. Acid traders in Guangdong and Fujian provinces are responding by diversifying sourcing toward Indonesian and Philippine smelter streams.
Battery-grade specification premiums are concentrating procurement authority with cathode material producers in South Korea and Japan. Long-term offtake contracts now embed purity escalation clauses rather than fixed technical standards. This pattern is most visible in the Ulsan and Yokkaichi industrial corridors, where acid suppliers compete on batch certification reliability rather than unit pricing alone.
Sulfuric Acid Market Segmentation
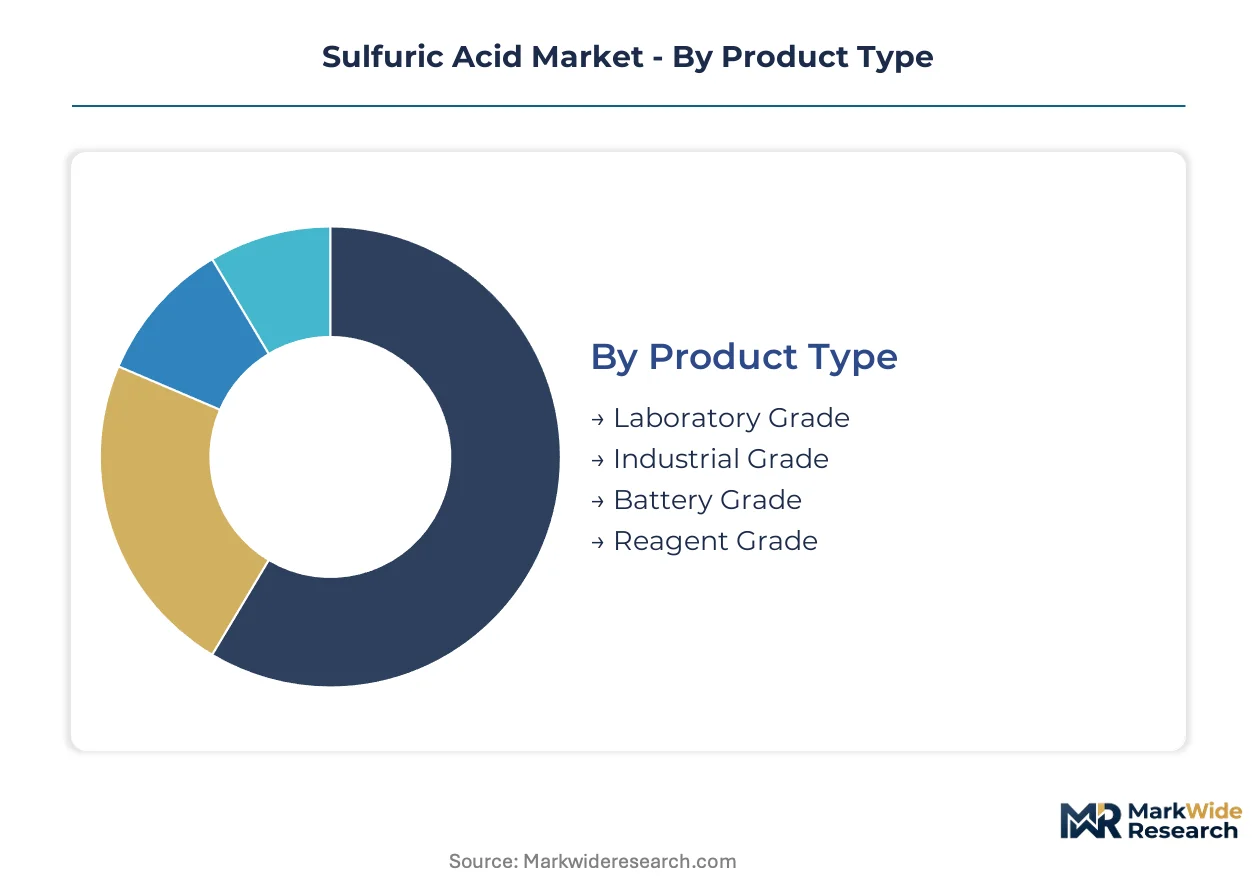
Sulfuric acid specifications diverge sharply across end-use applications, with purity thresholds and impurity tolerances dicting procurement decisions. Buyers in phosphate processing prioritize volume and sulfur cost linkage, while battery material producers impose metal-ion ceilings that eliminate most merchant supply.
Product Type:
Purchase contracts hinge on specification compliance costs rather than base chemical equivalence, with purification intensity determining margin capture.
- Industrial Grade:Concentrations of 93-98% H₂SO₄ with controlled iron and organic content serve phosphate fertilizer and petrochemical alkylation operations. Brazilian phosphate processors and Indonesian wet-process acid plants anchor volume offtake, with sulfur feedstock cost pass-through clauses dominating contract structures.
- Battery Grade:Ultra-low heavy metal specifications below 10 ppb for lead-acid and lithium extraction applications command purification premiums. South Korean cathode material plants in the Ulsan corridor and Japanese battery manufacturers impose batch certification requirements that disqualify non-specialized producers.
- Laboratory Grade:ACS-certified formulations for analytical and research applications carry modest volumes.
- Reagent Grade:High-purity specifications for pharmaceutical and electronic chemical synthesis occupy niche demand.
Volume sits with Industrial Grade; growth tilts toward Battery Grade.
Application:
End-use chemistry determines acid concentration requirements and consumption intensity per unit of output.
- Fertilizers:Wet-process phosphoric acid production consumes concentrated acid to digest phosphate rock into soluble phosphorus forms. Brazilian agricultural input demand and Southeast Asian plantation expansion drive capacity additions, with Mosaic Company and similar integrated producers securing captive acid supply.
- Metal Processing:Copper and uranium ore leaching, plus steel pickling, requires acid resistant to metal contamination accumulation. Chilean copper mines and Australian uranium operations specify acid with controlled chloride and fluoride content to protect solvent extraction circuits.
- Petrochemicals:Alkylation units in petroleum refining use acid as catalyst for high-octane gasoline component production.
- Water Treatment:pH adjustment and wastewater neutralization applications accept lower purity thresholds.
Fertilizers command the largest volume share; metal processing applications are expanding most quickly.
End User:
Industry verticals impose distinct logistics and storage requirements that segment supplier capabilities.
- Agriculture:Fertilizer manufacturers and distributors purchase acid for phosphate processing or direct soil acidification in specialty crop systems. Brazilian soybean producers and Indonesian palm oil plantations generate seasonal demand spikes that stress regional logistics infrastructure.
- Mining:Copper, uranium, and rare earth extraction operations specify acid for heap leaching and solvent extraction. Chile's Atacama operations and Australian rare earth processors represent concentrated demand nodes with dedicated supply contracts.
- Oil & Gas:Refinery alkylation units and well stimulation operations consume acid in fixed ratios to throughput.
- Manufacturing:Diverse industrial applications from pigment production to textile processing generate fragmented demand.
Agriculture generates the highest absolute consumption; mining shows the steepest expansion trajectory.
Distribution Channel:
Supply security requirements and volume scale determine channel selection across user categories.
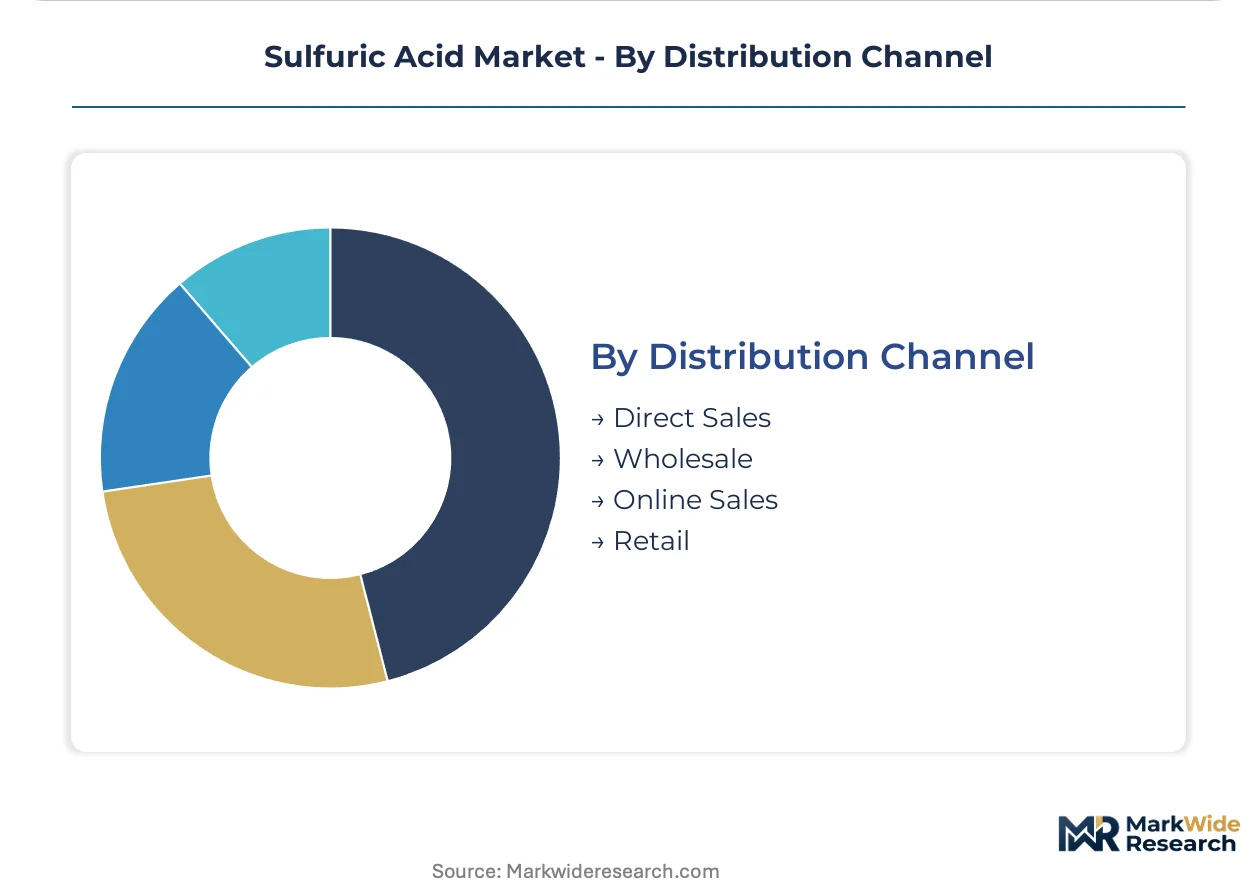
- Direct Sales:Integrated supply agreements link smelter-linked producers to phosphate and petrochemical processors. Jiangxi Copper Corporation and similar metallurgical acid suppliers bypass intermediaries for large-volume contracts with fixed offtake commitments.
- Wholesale:Regional distributors aggregate merchant acid from multiple sources to serve fragmented manufacturing and water treatment demand. Guangdong and Fujian province traders diversify sourcing across Chinese and Southeast Asian smelter streams to manage supply interruption risks.
- Online Sales:Digital procurement platforms facilitate spot transactions for laboratory and reagent grade quantities.
- Retail:Small-package sales for agricultural and industrial maintenance applications serve dispersed end users.
Direct Sales capture volume concentration; Wholesale channels are gaining share fastest in merchant supply regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elemental sulfur recovery from Canadian oil sands and Mexican petroleum refining anchors North American acid supply chains, while Chilean copper smelters and Brazilian phosphate processors reshape Pacific and Atlantic basin trade flows.
China
Copper smelter expansions in Jiangxi and Anhui provinces are tightening merchant acid availability across East Asia. MEE sulfur recovery mandates are forcing double-contact absorption upgrades at metallurgical facilities. The Pearl River Delta trading hubs in Guangdong and Fujian provinces are diversifying sourcing toward Indonesian and Philippine smelter streams to mitigate supply interruption risks.
Brazil
Phosphate fertilizer processors are scaling wet-process phosphoric acid capacity to serve soybean plantation demand across Mato Grosso and Paraná states. ANVISA chemical registration pathways constrain import sourcing for non-integrated acid suppliers. The Cubatão industrial complex in São Paulo state anchors southeastern acid consumption as Mosaic Company and similar integrated producers secure captive supply arrangements.
United States
Petroleum alkylation units and spent acid regeneration facilities concentrate demand along the Gulf Coast refining corridor. EPA Risk Management Plan enforcement is triggering storage infrastructure upgrades at Texas and Louisiana terminals. The Houston Ship Channel and Port Arthur complex represent the dominant logistics nodes where Chemtrade Logistics and PVS Chemicals maintain terminal and distribution assets.
Chile
Copper heap leaching and solvent extraction operations in the Atacama Desert generate concentrated acid demand for mining applications. The national mining regulator imposes strict chloride and fluoride content specifications to protect electrowinning circuits. Antofagasta and Calama serve as the primary consumption clusters where BHP and Codelco operations specify acid with controlled impurity profiles.
Germany
Industrial-grade formulations for European chemical manufacturing sustain demand despite alkylation substitution pressure at select refineries. REACH registration obligations administered by ECHA constrain import pathways for non-EU producers seeking chemical sector placement. The Ludwigshafen chemical complex and Antwerp-Rotterdam-Amsterdam trading corridor anchor northwestern supply security for BASF SE and comparable integrated chemical producers.
Sulfuric Acid Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue battery-grade purification and circular acid regeneration services. The market structure concentrates around metallurgical acid suppliers with captive sulfur dioxide streams and integrated phosphate-fertilizer processors with backward rock integration. Three archetypes dominate: smelter-linked merchants with regional supply control, fertilizer-integrated captives with cost-advantaged rock positions, and specialty purifiers serving battery material specifications. Capacity expansion and purification technology licensing represent the dominant competitive moves as players respond to specification escalation in cathode active material supply chains.
Within the smelter-linked tier, Jiangxi Copper Corporation exemplifies Chinese metallurgical acid production anchored in southern China copper processing. BASF SE occupies a position representing European industrial-grade formulation capability for chemical manufacturing applications. The Mosaic Company sits within the fertilizer-integrated archetype, demonstrating captive phosphate rock integration sustaining margin capture in volume-grade output. These three entities collectively illustrate the geographic and vertical specialization patterns structuring competitive positioning across Pacific Rim and Atlantic basin markets.
| Leading Market Players |
|---|
| The Mosaic Company |
| Aurubis AG |
| PhosAgro Group |
| OCP Group |
| BASF SE |
| Jiangxi Copper Corporation |
| Chemtrade Logistics Inc. |
| Boliden Group |
| PVS Chemicals Inc. |
| Others |
Supply Flow & Price Mechanics
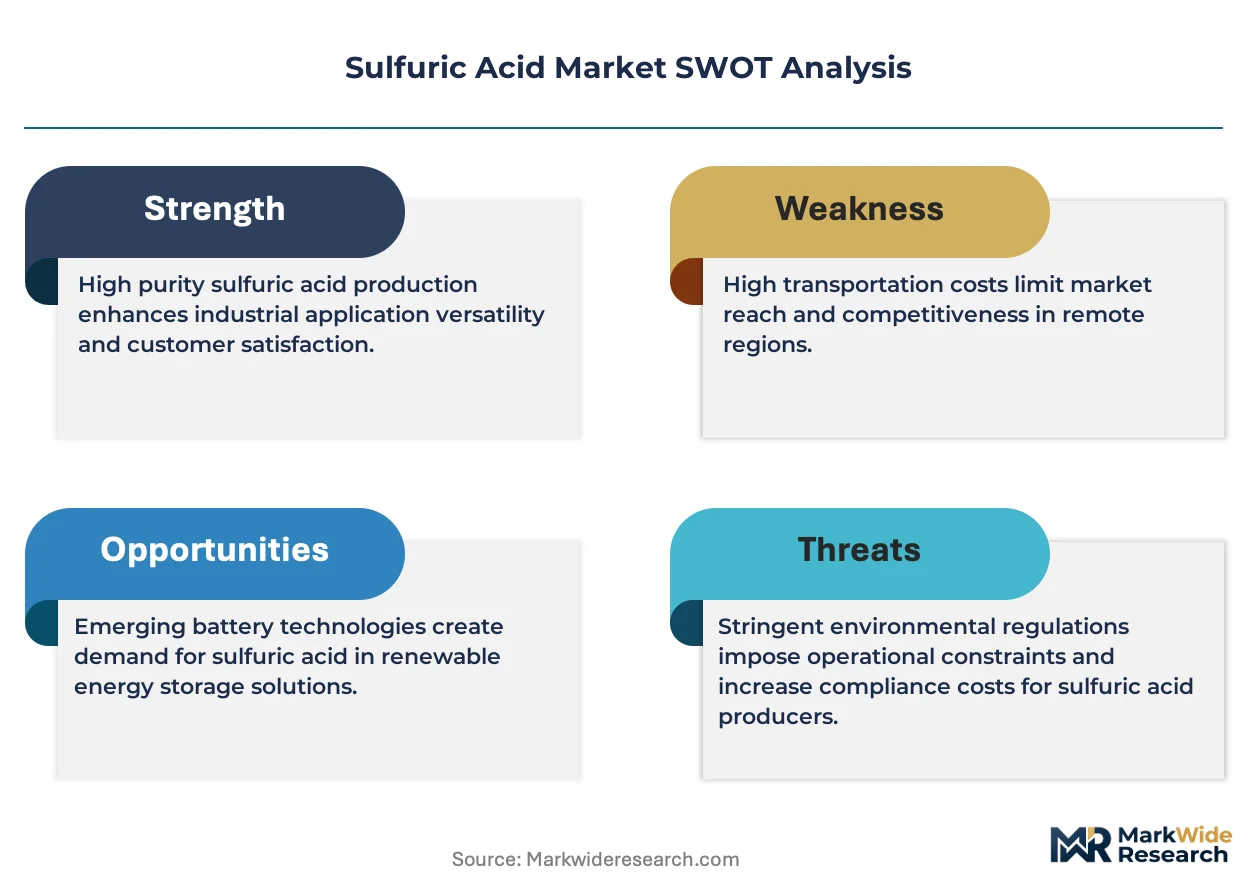
China's MEE sulfur recovery mandates gate both qualified supply and premium-tier pricing access, as smelter-linked producers must absorb double-contact absorption upgrade costs to maintain merchant acid eligibility while battery-grade purification investments create specification premiums that only registered suppliers can capture.
Pricing Analysis
Warranty and batch certification bundling separates battery-grade contracts from industrial-grade spot transactions. Three-tier pricing structure across battery, industrial, and laboratory grades reflects purification intensity and metal-ion compliance costs. Price differentiation rests on sulfur feedstock linkage and REACH registration status for European chemical sector access. Phosphate fertilizer processors in Brazil exhibit highest price sensitivity due to sulfur cost pass-through exposure, while South Korean cathode material plants accept specification premiums for certified low-impurity supply.
Supply Chain Analysis
Single-source vulnerability sits with Jiangxi and Anhui province smelters controlling East Asian merchant acid output. Geographic supply concentration centers on China, Indonesia, and Chile for metallurgical acid, with Brazilian phosphate processors and US Gulf Coast refiners anchoring downstream demand. Raw material dependencies span elemental sulfur from petroleum refining, copper concentrate processing streams, and phosphate rock quality. Tariff exposure on sulfur feedstock imports threatens margin stability at non-integrated merchant operators. Distribution runs through direct sales contracts for volume offtake and wholesale aggregation for fragmented manufacturing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive sulfur dioxide streams and backward phosphate rock control determine margin sustainability against feedstock volatility.
For Market Incumbents: Extend purification capacity to capture battery-grade specification premiums before cathode material procurement consolidates around certified suppliers. Defend regional supply positions by locking long-term offtake with Indonesian and Philippine smelter expansions. Counter alkylation substitution pressure at North American refineries by diversifying into spent acid regeneration services. For New Entrants and Emerging Players: Membrane electrolysis for acid regeneration offers a technology-first wedge into circular service contracts with European steel processors. Target lithium extraction facilities in Chile's Atacama and Argentina's Cauchari-Olaroz with high-purity acid supply positioned against incumbent merchant distributors. Pursue tolling arrangements that displace conventional product sales with closed-loop processing partnerships. For Investors and Strategic Acquirers: REACH registration completion by non-EU producers is the leading indicator that premium chemical sector placement is achievable. Five-to-ten-year viability favors specialized purifiers with multi-grade output flexibility over single-tier commodity operators. Acquisition screening should prioritize smelter-linked assets with sulfur recovery compliance already deployed.| Strategic Initiative | Industry Significance |
|---|---|
| Double-Contact Absorption Upgrade | MEE compliance at Chinese smelters preserves merchant acid eligibility against production caps. |
| Battery-Grade Purification Investment | South Korean cathode plants impose metal-ion ceilings that eliminate non-specialized producers. |
| Backward Phosphate Rock Integration | Mosaic Company and similar captives sustain margin capture against sulfur feedstock volatility. |
| Spent Acid Regeneration Service | European steel processors pilot closed-loop systems converting waste acid to virgin concentration. |
| Indonesian Smelter Stream Diversification | Guangdong traders mitigate Jiangxi supply interruption risks through Philippine sourcing expansion. |
Methodological Framework
Trade flow databases, customs records, and SEC 10-K filings formed the secondary backbone, supplemented by primary interviews with acid plant managers, phosphate processor procurement leads, copper smelter technical directors, and European chemical distributor channel partners. Bottom-up and top-down triangulation validated volume estimates against capacity utilization disclosures and regional consumption intensity benchmarks.
Bottom-up modeling anchored projections across the analysis window, with top-down macroeconomic cross-checks for sulfur feedstock price elasticity and fertilizer demand correlation. Segmentation dimensions included grade tier, end-use application, and regional production hub concentration. CAGRs derived from capacity expansion pipelines and specification escalation trajectories in cathode material supply chains, incorporating MEE compliance timelines and REACH registration pathways as structural constraints.
Several conditions sit outside the modeled scope, including unannounced smelter maintenance schedules, sudden sulfur recovery mandate enforcement variations, and alkylation unit closure decisions at individual refineries. Deviation in Chinese dual carbon policy implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Allyl Chloride Market
Chemicals
Etidronic Acid Market
Chemicals
Global N-Butanol Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Bakers Ammonia Market
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
India Ethoxylates Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Diphosphate Market