
 Tetrapotassium Pyrophosphate Market | 2026-2036
Tetrapotassium Pyrophosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Tetrapotassium Pyrophosphate Market Analytics
Food manufacturing procurement is collapsing toward premium-grade suppliers as clean-label formulation standards tighten across developed markets. Hubei Xingfa Chemicals leverages captive phosphate rock access to sustain cost leadership in bulk industrial supply. Innophos differentiates through technical service bundling for North American food processors. Aarti Phosphates anchors South Asian demand with localized blending operations.
Tetrapotassium pyrophosphate (K4P2O7) is an inorganic potassium salt of pyrophosphoric acid, typically manufactured via thermal dehydration of monopotassium phosphate at temperatures exceeding 300°C, yielding a tetrahydrate or anhydrous white crystalline powder with strong chelating and dispersing properties. Industrial grade dominates volume flows into fertilizer and detergent intermediates, while food grade commands margin concentration from emulsifier applications in processed meat and seafood. Pharmaceutical grade occupies a narrow but high-barrier niche where USP-NF certification filters out commodity producers.
EPA oversight of phosphate discharge limits shapes industrial-grade demand in US surface water management applications, while REACH registration requirements in Europe constrain importer access for non-EU producers. China's SAMR enforces GB 25562 food additive purity standards that diverge from Codex Alimentarius thresholds. Stakeholders must monitor regulatory divergence between major consuming jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing food-grade supply chains toward certified producers with documented phosphate provenance, while industrial-grade flows concentrate around captive rock processors in China and Morocco.
Growth Catalysts
- EFSA purity thresholds:Tightened food additive specifications in Europe are disqualifying commodity suppliers and redirecting procurement toward qualified producers with full traceability documentation.
- Processed meat emulsification:Rising demand for texture-stabilized poultry and seafood products in North American retail channels sustains food-grade volume expansion.
- China's phosphate rock concentration:Vertical control over upstream ore reserves by state-affiliated processors anchors cost-competitive industrial-grade supply for fertilizer and detergent intermediates.
Market Restraints
- Rock phosphate volatility:Concentrated Moroccan and Chinese ore deposits expose pricing to export quota fluctuations and geopolitical supply disruptions.
- REACH registration barriers:ECHA compliance costs and data requirements block non-EU commodity producers from European industrial-grade distribution.
- Organic phosphate substitutes:Citrate and polyphosphate blends in premium food formulations displace tetrapotassium pyrophosphate in clean-label positioning.
Strategic Opportunities
- Southeast Asia food processing:Vietnam and Indonesia's expanding seafood export sectors lack qualified local emulsifier supply, creating qualification windows for certified importers.
- Water treatment chelation:EPA discharge limits on heavy metals in US surface water management are expanding industrial-grade demand for phosphate-based sequestration.
- Pharmaceutical USP-NF certification:Narrow producer base for injectable-grade material creates margin expansion potential for qualified specialty chemical manufacturers.
Industry Challenges
- Dual-grade production switching:Food and industrial lines require segregated equipment campaigns, compressing asset utilization and extending changeover downtime.
- SAMR-REACH divergence:China's GB 25562 purity thresholds differ from Codex and EFSA specifications, forcing parallel qualification tracks for multi-jurisdiction suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetrapotassium Pyrophosphate Market |
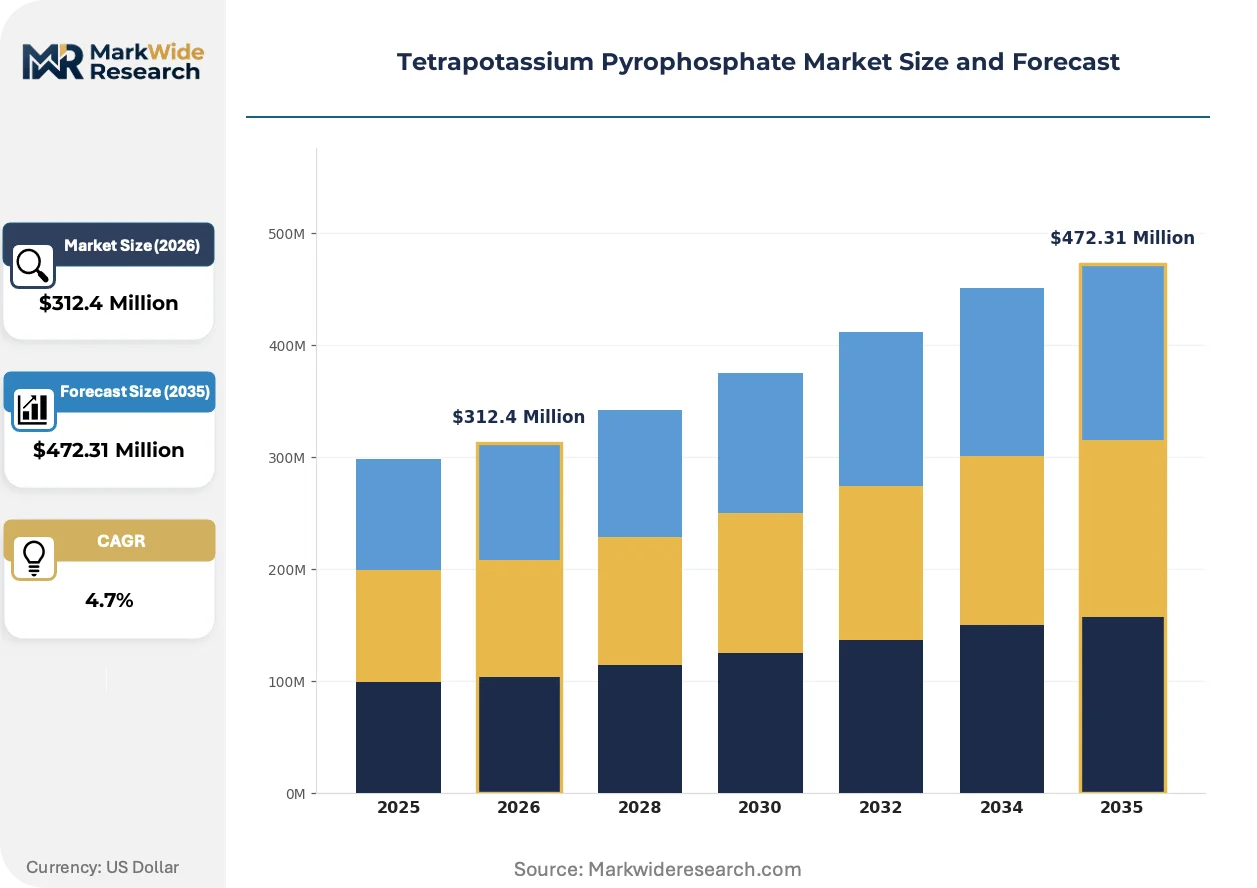
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Cosmetic Grade Application: Food Additive, Fertilizer, Cosmetic Products, Pharmaceuticals End User: Food Manufacturing, Agriculture, Personal Care, Healthcare Delivery Mode: Bulk Supply, Retail Packaging, Online Distribution, Direct Sales |
| Companies Covered | Aarti Phosphates, ICL Performance, Hubei Xingfa Chemicals, Airedale Chemicals, Innophos, Zhenjiang Huangxu Chemicals, TongVo, Nutrien, Tri-Chem Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetrapotassium Pyrophosphate Market Evolving Landscape
Thermal process optimization and regulatory compliance automation are restructuring competitive advantage around energy efficiency and documentation systems rather than scale alone.
Continuous rotary kiln dehydration is bifurcating the producer base between integrated operations with captive energy supply and merchant producers exposed to volatile natural gas pricing. European chemical parks with combined heat and power infrastructure are capturing food-grade margins, while standalone facilities in high-cost jurisdictions face capacity rationalization. The technology is compressing viable production geography to phosphate-rock-adjacent or energy-subsidized zones.
REACH registration renewal deadlines under ECHA's 2024-2026 evaluation window are forcing non-EU industrial-grade exporters to establish EU-based legal entities or forfeit market access. The regulation is accelerating importer consolidation around distributors with in-house regulatory affairs capabilities. Specialty chemical traders in Rotterdam and Hamburg are capturing intermediary value previously retained by direct mill relationships.
Food manufacturers are unbundling technical service from material supply, contracting directly with application laboratories for formulation support while sourcing commodity chemical through competitive tender. This disintermediation compresses supplier margins and privileges producers with standalone technical service organizations. North American meat processors are most advanced in this separation, with similar patterns emerging in European dairy alternatives.
Tetrapotassium Pyrophosphate Market Segmentation
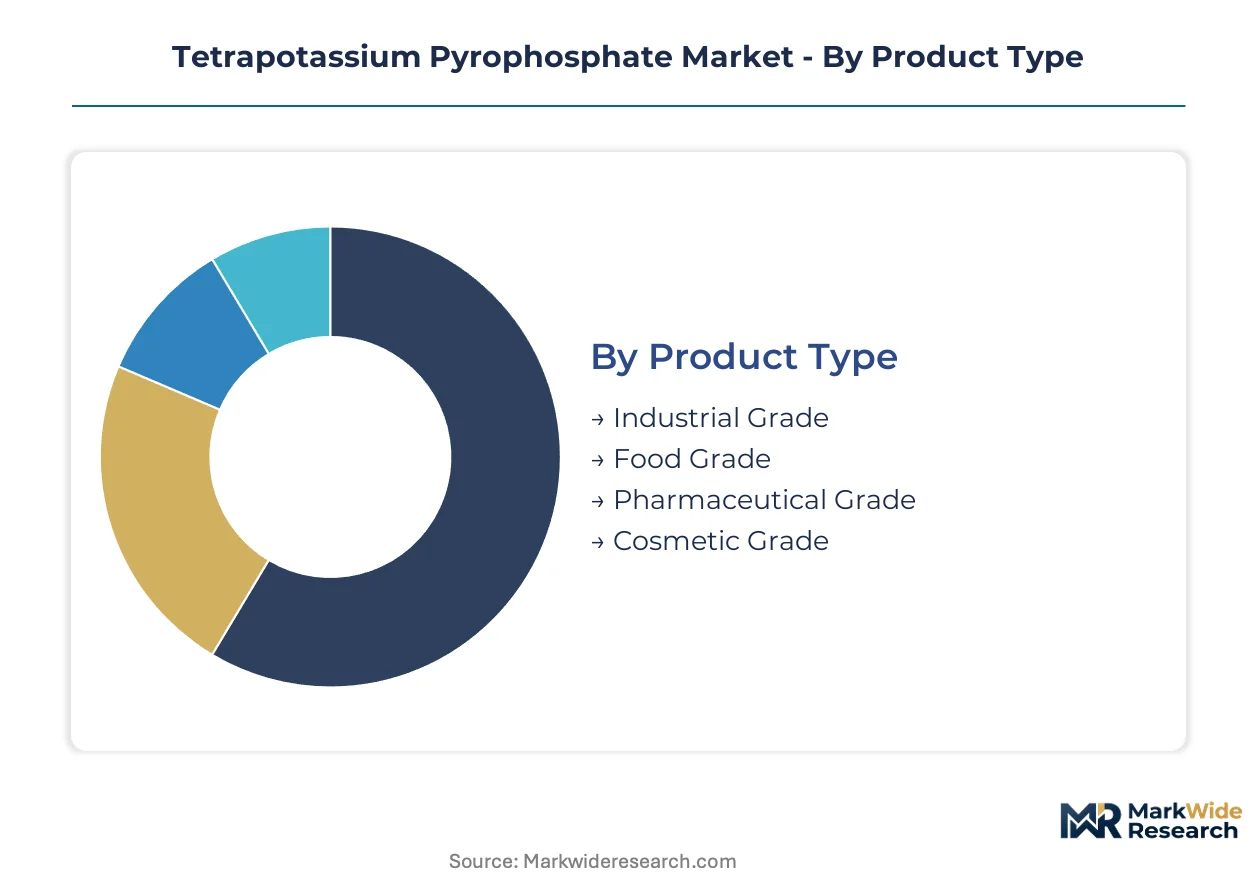
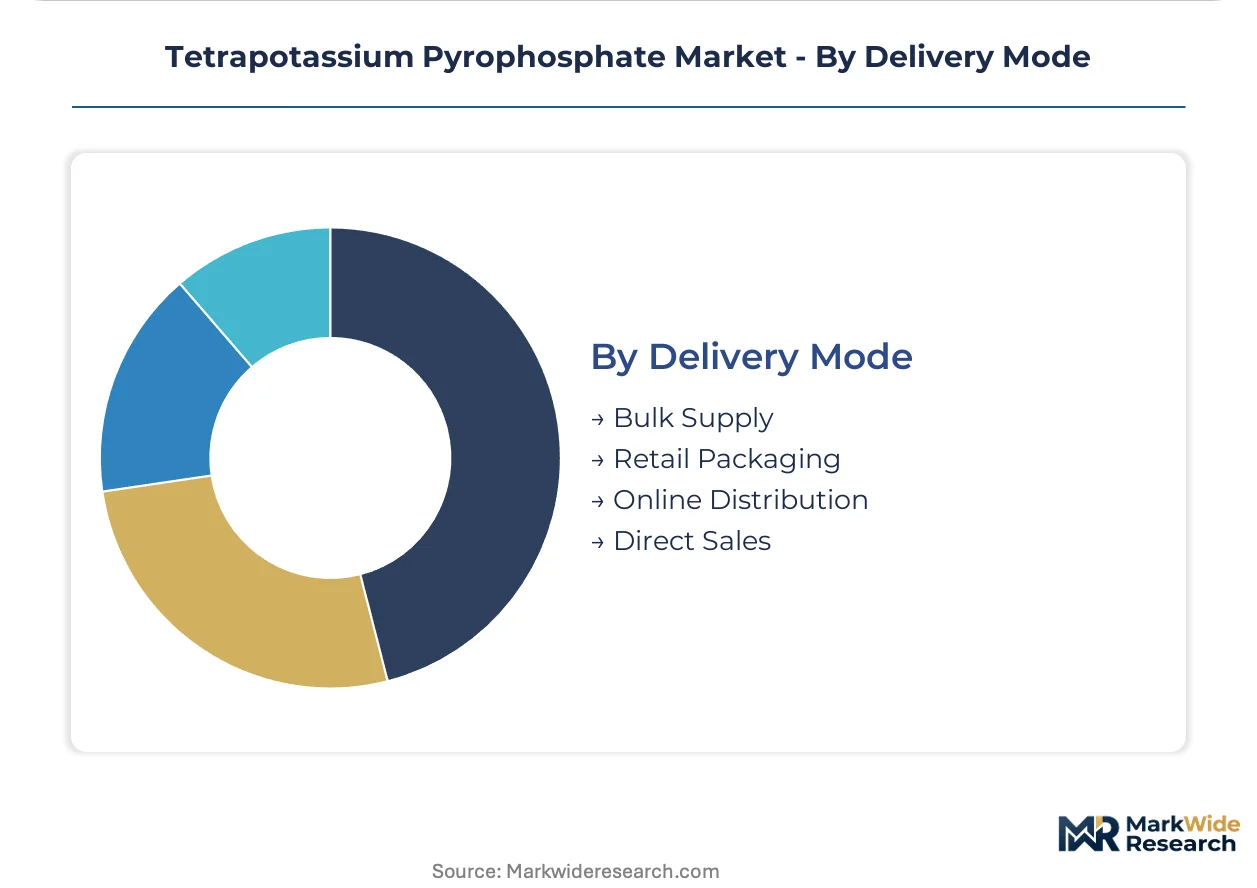
Segmentation in tetrapotassium pyrophosphate reveals how purity grades and delivery modes fragment procurement channels. Food-grade specifications diverge sharply from industrial flows, creating parallel supply chains with distinct qualification barriers and margin structures.
Product Type:
Industrial-grade material moves through bulk commodity distributors, while food and pharmaceutical grades channel through certified specialty chemical networks with full documentation requirements.
- Industrial Grade:Manufactured via thermal dehydration of monopotassium phosphate at temperatures exceeding 300°C, yielding anhydrous powder with strong chelating properties. Demand concentrates in Chinese fertilizer and detergent intermediate production, anchored by state-affiliated processors with captive phosphate rock access.
- Food Grade:Tetrahydrate crystalline form meeting GB 25562, Codex Alimentarius, and EFSA purity thresholds for emulsifier applications. North American processed meat and seafood manufacturers drive procurement expansion as clean-label formulation standards tighten.
- Pharmaceutical Grade:USP-NF certified material for injectable applications with narrow qualified producer base.
- Cosmetic Grade:Purified specification for personal care formulations with regional quality variance.
Industrial Grade dominates installed base. Food Grade is where expansion concentrates.
Application:
Cost tier separation distinguishes commodity-scale applications from premium formulation uses with stringent certification overhead.
- Food Additive:Emulsification and texture stabilization in processed poultry, seafood, and dairy alternatives. EFSA and FDA clean-label mandates are compressing supply chains toward producers with documented phosphate provenance.
- Fertilizer:Intermediate for compound fertilizer manufacturing, primarily in China and Morocco where vertical ore control anchors cost position.
- Cosmetic Products:Chelating agent in personal care formulations with regional regulatory divergence.
- Pharmaceuticals:Buffer and sequestrant in parenteral formulations requiring USP-NF certification.
Fertilizer commands volume leadership. Food Additive is climbing the fastest.
End User:
Customer type determines procurement sophistication, with food manufacturers unbundling technical service from material supply.
- Food Manufacturing:Processed meat, seafood, and dairy alternative producers sourcing through competitive tender with standalone laboratory support contracts.
- Agriculture:Compound fertilizer blenders purchasing industrial-grade material through bulk commodity channels.
- Personal Care:Cosmetic formulators with regional quality specifications and localized blending operations.
- Healthcare:Pharmaceutical manufacturers with USP-NF qualification requirements and narrow supplier bases.
Agriculture anchors volume demand. Food Manufacturing is gaining share fastest.
Delivery Mode:
Supply concentration in phosphate-rock-adjacent regions dictates viable distribution economics for each channel.
- Bulk Supply:Rail and vessel shipments of industrial-grade material from Chinese and Moroccan production clusters to fertilizer and detergent intermediate processors.
- Retail Packaging:Smaller-format food and cosmetic grade distribution through specialty chemical distributors with regional warehousing.
- Online Distribution:Emerging channel for laboratory and small-batch industrial procurement with documentation automation.
- Direct Sales:Account-managed relationships for pharmaceutical and large food manufacturing contracts with technical service bundling.
Bulk Supply dominates tonnage flows. Direct Sales is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese phosphate processors dominate export flows to European food manufacturers seeking REACH-compliant material, while Moroccan ore reserves anchor Atlantic basin fertilizer intermediate supply.
China
State-affiliated processors with captive phosphate rock access in Hubei and Guizhou provinces supply industrial-grade material to domestic fertilizer blenders and Southeast Asian detergent manufacturers. SAMR enforces GB 25562 food additive purity standards that diverge from Codex thresholds, forcing parallel qualification tracks for exporters. The Yangtze River Delta cluster around Nanjing and Shanghai concentrates food-grade finishing capacity for premium export markets.
United States
EPA discharge limits on heavy metals in surface water management expand industrial-grade demand for phosphate-based sequestration in municipal treatment systems. FDA clean-label mandates compress food-grade procurement toward suppliers with documented phosphate provenance. Gulf Coast petrochemical corridors in Texas and Louisiana host blending operations serving processed meat manufacturers across the Southeast and Midwest.
Germany
ECHA REACH registration renewal deadlines force non-EU industrial-grade exporters to establish EU-based legal entities or forfeit market access. EFSA purity thresholds redirect food additive procurement toward qualified producers with full traceability documentation. The Rhine-Ruhr chemical park infrastructure captures food-grade margins through combined heat and power integration.
Morocco
Vertical control over the world's largest phosphate ore reserves anchors cost-competitive industrial-grade supply for Atlantic basin fertilizer manufacturers. Export quota fluctuations expose pricing to geopolitical supply disruptions. The Khouribga-Jorf Lasfar industrial corridor concentrates mining, beneficiation, and intermediate chemical production in a vertically integrated configuration.
India
FSSAI food additive regulations tighten purity specifications for imported emulsifiers used in processed poultry and seafood exports. Aarti Phosphates anchors South Asian demand with localized blending operations in Gujarat and Maharashtra. The Mumbai-Pune industrial belt concentrates pharmaceutical-grade qualification capacity for parenteral formulation applications.
Tetrapotassium Pyrophosphate Market Competitive Landscape
Player mix skews toward state-affiliated resource processors and specialty chemical distributors with regulatory affairs capabilities. Concentration is moderate at the industrial-grade tier where captive rock access determines cost position, while food and pharmaceutical grades exhibit tighter supplier bases filtered by certification barriers. Two strategic archetypes dominate: vertically integrated miners with downstream chemical conversion assets, and specialty distributors bundling technical service with documentation compliance. Capacity expansion in phosphate-rock-adjacent zones and regulatory partnership formations with EU-based legal entities represent the dominant competitive moves.
Among Chinese state-affiliated processors, Hubei Xingfa Chemicals exemplifies the captive-resource archetype with upstream ore control, while Innophos occupies a position within the North American specialty tier emphasizing technical service bundling. Aarti Phosphates represents the localized-blending archetype serving South Asian markets with regional formulation support. These three anchors illustrate how geographic resource access, certification depth, and service integration separate viable competitors from commodity merchants.
| Leading Market Players |
|---|
| Aarti Phosphates |
| ICL Performance |
| Hubei Xingfa Chemicals |
| Airedale Chemicals |
| Innophos |
| Zhenjiang Huangxu Chemicals |
| TongVo |
| Nutrien |
| Tri-Chem Industries |
| Others |
Value Network & Pricing Analysis
Captive phosphate rock access in Hubei and Guizhou provinces anchors cost floors for industrial-grade material, compressing merchant producers without upstream ore control into narrow margin bands. Food-grade thermal finishing at Yangtze River Delta facilities commands premium spreads over commodity bulk, with energy integration at Rhine-Ruhr chemical parks capturing parallel margin concentration in Europe.
Pricing Analysis
Continuous rotary kiln dehydration technology separates pricing between integrated operations with captive energy supply and standalone facilities exposed to volatile natural gas pricing. Three-tier pricing structure across pharmaceutical-grade USP-NF certification, food-grade EFSA-compliant material, and industrial-grade bulk commodity reflects quality grade and certification level differentiation. Cost compression in industrial-grade flows is intensifying because Moroccan and Chinese export quota fluctuations inject raw material volatility. Agriculture sector buyers exhibit highest price sensitivity through bulk commodity tender processes, while pharmaceutical manufacturers accept steep premiums for narrow qualified supplier bases.
Supply Chain Analysis
Strategic stockpile preferences dominate fertilizer intermediate procurement, with compound blender inventories absorbing Moroccan ore export disruptions. Supply concentrates in China, Morocco, and India for phosphate rock beneficiation and thermal conversion. Downstream flows draw from monopotassium phosphate feedstock, natural gas for kiln energy, and sulfuric acid for acidulation stages. Single-source vulnerability runs through concentrated Moroccan ore deposits controlled by state-affiliated entities. Distribution runs through bulk rail and vessel shipments from Khouribga-Jorf Lasfar and Yangtze River Delta clusters to Atlantic basin and Southeast Asian processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between SAMR, EFSA, and FDA purity thresholds fragments qualification requirements, creating specialist niches for documentation-capable suppliers. Clean-label formulation mandates unbundle technical service from material supply, opening margin capture opportunities for standalone application laboratories.
For Market Incumbents: Secure backward integration into captive phosphate rock reserves or exclusive offtake agreements with Moroccan and Chinese state-affiliated miners to defend cost position against ore export quota volatility. Invest in parallel EFSA and SAMR certification tracks to capture multi-jurisdiction food-grade procurement consolidation. Channel control through Rotterdam and Hamburg regulatory affairs capabilities captures intermediary value from REACH renewal deadlines. For New Entrants and Emerging Players: USP-NF certification fast-track for injectable-grade material opens margin-rich pharmaceutical supply with narrow incumbent competition. Target Vietnam and Indonesia seafood export processing sectors lacking qualified local emulsifier supply, establishing qualification windows before regional capacity develops. Go-to-market through direct technical service contracts with North American meat processors unbundling formulation support from commodity procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty chemical distributors with in-house regulatory affairs capabilities serving European food manufacturers through REACH compliance. Long-term viability across the analysis window favors acquisition of EU-based legal entities holding active substance registrations, with capacity rationalization exposure for standalone high-cost jurisdiction facilities. Watch ECHA evaluation window completion rates as inflection indicator for importer consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive ore access in Hubei or Khouribga insulates margin from export quota disruption. |
| Dual-Jurisdiction Certification Investment | Parallel SAMR and EFSA qualification captures fragmented clean-label procurement consolidation. |
| EU Legal Entity Establishment | REACH registration holding companies in Rotterdam or Hamburg capture distributor intermediary value. |
| Technical Service Unbundling | Standalone application laboratories contract directly with meat processors for formulation support. |
| Continuous Rotary Kiln Deployment | Combined heat and power integration at chemical park sites captures food-grade margin concentration. |
Research Methodology
Desk research of customs and trade flow databases, SEC and ECHA regulatory filings, and ACC industry reports preceded structured interviews with phosphate plant managers, food manufacturing procurement leads, specialty chemical distribution channel partners, and technical R&D directors at emulsifier suppliers. Primary fieldwork across Chinese state-affiliated processors, European specialty distributors, and North American meat processing facilities was validated against secondary trade statistics and production capacity disclosures. Bottom-up volume estimates from facility-level output data were triangulated with top-down demand aggregation across fertilizer, food additive, and pharmaceutical end-uses.
Variance decomposition across grade tier, end-use industry, packaging format, and regional production hub dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate assumptions calibrated to regulatory milestone timelines and capacity expansion announcements. Forecast inputs incorporated EPA discharge limit enforcement trajectories, EFSA clean-label mandate adoption curves, and SAMR food additive standard revision schedules.
Decision-makers should treat outputs as directional under sustained phosphate rock export quota regimes and stable thermal energy pricing; material deviation would warrant model refresh. Forecasts reflect assumptions regarding REACH registration renewal completion rates and clean-label formulation mandate enforcement intensity. Revision becomes warranted when Moroccan ore export policy or Chinese environmental compliance inspections cross thresholds that restructure Atlantic basin supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Quaternium-15 Market
Chemicals
Global Construction Chemical Market
Chemicals
Pinoxaden Market
Chemicals
Europe Biguanide Market
Chemicals
Global Acetic Anhydride Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Global Glycol Ether Market
Chemicals
Global N-Butanol Market
Chemicals
Triethylaluminum Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Lead Tetracetate Market
Chemicals
Southeast Asia Construction Chemicals Market
Chemicals
Phenylethyl Market
Chemicals
Hydrophobing Agents Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market